
 Tuna and Algae Omega-3 Ingredient Market | 2026-2036
Tuna and Algae Omega-3 Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Tuna and Algae Omega-3 Ingredient Market Insights
Pharmaceutical-grade concentration tiers above 90% EPA/DHA is bifurcating the competitive landscape into premium validators and commodity suppliers. BASF SE leverages its integrated biotechnology platform to control fermentation-to-refinement pathways for algal oil. Aker BioMarine anchors Antarctic krill supply chains but extends its reach into tuna-derived concentrates through Nordic processing partnerships. DSM-Firmenich differentiates via its life sciences division, specializing in customized omega-3 formulations for medical nutrition.
Tuna and algae omega-3 ingredients comprise long-chain polyunsaturated fatty acids—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—extracted through molecular distillation or heterotrophic fermentation, standardized to triglyceride or ethyl ester forms for bioavailability enhancement. These ingredients serve cardiovascular, cognitive, and anti-inflammatory therapeutic applications across human and animal health sectors. Algal oil captures the fastest expansion trajectory within product type classifications, driven by vegetarian formulation demands and marine ecosystem sustainability concerns. Dietary supplements dominate end-user value pools, though pet nutrition exhibits accelerated growth as premiumization permeates companion animal nutrition. Softgel formulations maintain volume leadership, yet liquid delivery formats gain share in pediatric and geriatric compliance segments.
The FDA's New Dietary Ingredient notification requirements and EFSA's health claim substantiation frameworks govern market access for novel omega-3 concentrates, while China's NMPA regulates pharmaceutical-grade imports through drug master file submissions. These overlapping compliance architectures elevate capital barriers for new entrants and reward pre-qualified suppliers with multi-jurisdiction dossiers. Stakeholders must monitor evolving contaminant testing protocols and carbon footprint disclosure mandates to preserve competitive positioning.
Market Dynamics
Pharmaceutical-grade concentration tiers above 90% EPA/DHA are bifurcating the competitive landscape into premium validators and commodity suppliers, forcing mid-tier processors to choose between capital-intensive refinement upgrades or volume-driven commodity positioning.
Growth Catalysts
- EFSA Contaminant Threshold Tightening:The European Food Safety Authority's stricter limits on marine-sourced omega-3 pollutants accelerate algae-derived alternatives among infant formula manufacturers seeking compliant supply chains.
- Heterotrophic Fermentation Scale-Up:Industrial biotechnology platforms now achieve pharmaceutical-grade algal oil yields that match fish-derived concentrates in bioavailability metrics.
- Pet Nutrition Premiumization:Companion animal owners in Germany and Japan now purchase omega-3 fortified formulations at human-grade purity standards, opening adjacent revenue pools.
Market Restraints
- Antarctic Krill Supply Concentration:A single geography and limited vessel fleets create bottleneck risk for marine-sourced phospholipid-bound omega-3 derivatives.
- EPA/DHA Raw Material Cost Volatility:Tuna byproduct availability fluctuates with global seafood processing volumes and seasonal catch restrictions.
- FDA New Dietary Ingredient Notification Friction:Pre-market safety documentation requirements delay novel concentrate launches by 18-24 months.
Strategic Opportunities
- Pediatric Liquid Formulation White Space:Geriatric and infant compliance segments in Australia show unmet demand for non-softgel delivery systems.
- Carbon Footprint Disclosure Mandates:EU Green Deal reporting requirements favor fermentation-based algal producers with measurable Scope 3 advantages.
- Medical Nutrition Customization:Hospital and clinical channels seek patient-specific EPA/DHA ratios for post-surgical anti-inflammatory protocols.
Industry Challenges
- Multi-Jurisdiction Dossier Complexity:Suppliers must maintain simultaneous FDA, EFSA, and NMPA compliance architectures, stretching regulatory affairs teams.
- Fermentation-to-Refinement Integration:Biotechnology firms struggle to optimize downstream processing yields without sacrificing triglyceride structural integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuna and Algae Omega-3 Ingredient Market |
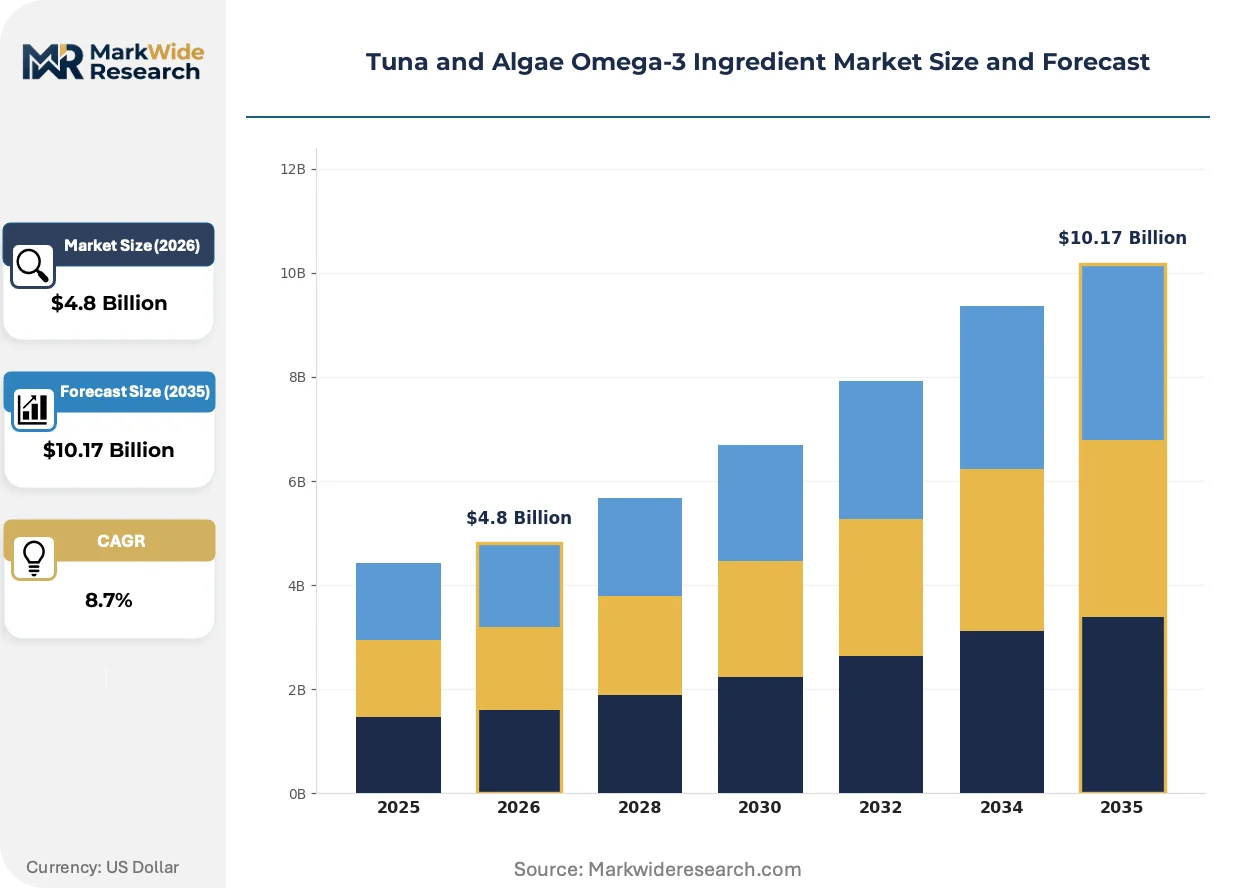
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Ethyl Ester, Triglyceride End User: Dietary Supplements, Functional Foods, Pet Nutrition, Pharmaceuticals Form: Softgel, Liquid, Powder, Capsule Application: Cardiovascular Health, Joint Health, Immune Support, Brain Function |
| Companies Covered | BASF SE, Polaris S.A., Archer Daniels Midland Company, AlgaeCytes, Source-Omega LLC, Corbion N.V., Aker BioMarine, Golden Omega, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuna and Algae Omega-3 Ingredient Market Trends and Innovations
Extraction and formulation technologies are fragmenting traditional supply hierarchies while regulatory disclosure mandates and shifting procurement behaviors redistribute competitive advantage across the value chain.
Single-cell oil production via heterotrophic fermentation is fragmenting the long-standing dominance of marine capture fisheries in long-chain omega-3 supply. Infant formula manufacturers in China and the United States now source algal-derived DHA at parity pricing to fish oil equivalents. This technology is fragmenting geographic supply concentration by enabling inland production facilities independent of coastal processing infrastructure.
EFSA's tightened contaminant thresholds for dioxins and heavy metals in marine lipids are compressing acceptable supplier pools for European food and pharma applications. Processors must now demonstrate batch-level testing protocols that exceed prior industry norms. Algae-derived concentrate producers capture displaced volume as established tuna oil refiners absorb capital costs for enhanced purification systems.
Certification-driven procurement now prioritizes carbon footprint documentation and marine ecosystem impact scoring over historical price-volume negotiations. Dietary supplement brands in Germany and Australia now require supplier sustainability attestations as standard contract terms. This behavioral shift favors integrated biotechnology platforms with captive fermentation capacity over commodity traders dependent on volatile wild-catch supply chains.
Tuna and Algae Omega-3 Ingredient Market Segmentation
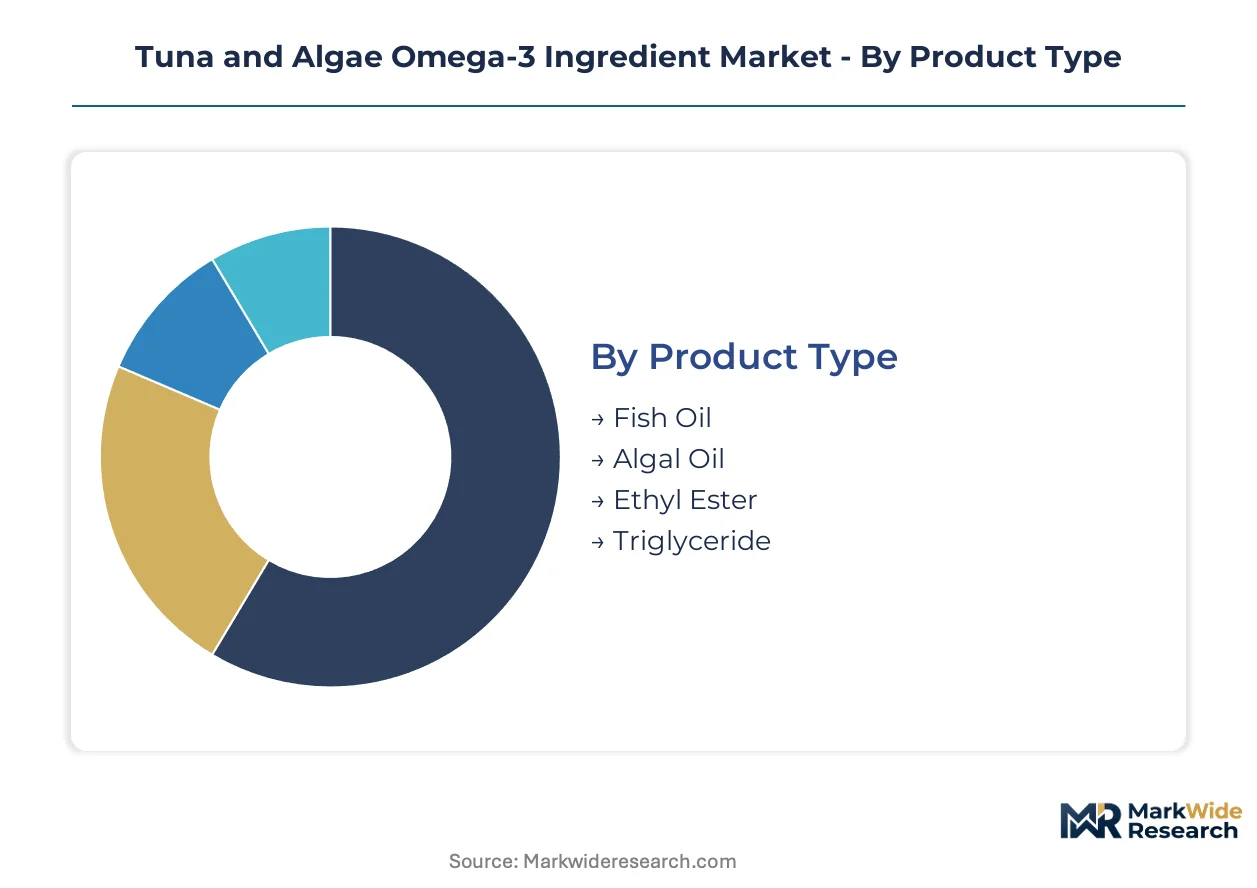
Segmentation in the Tuna and Algae Omega-3 Ingredient Market reveals divergent supply chain configurations and regulatory compliance burdens across product categories. Each dimension exposes distinct margin structures and geographic concentration patterns that determine competitive positioning.
Product Type:
Fish Oil dominates domestic processing in coastal economies with established tuna harvesting infrastructure, while Algal Oil exports concentrate from controlled-environment fermentation facilities in Germany and China.
- Fish Oil:Extracted from tuna byproducts through molecular distillation, yielding EPA/DHA concentrates standardized to 30-90% purity tiers. Demand concentrates in dietary supplement manufacturers across Japan and Australia seeking cost-competitive long-chain omega-3 for cardiovascular formulations.
- Algal Oil:Produced via heterotrophic fermentation of Schizochytrium or Crypthecodinium strains, achieving triglyceride-bound DHA at pharmaceutical-grade specifications. Infant formula producers in China and the United States now source algal-derived concentrates at parity pricing to fish oil equivalents, driven by EFSA contaminant threshold tightening.
- Ethyl Ester:Chemically modified form enabling ultra-high EPA/DHA concentration above 90% for medical nutrition applications.
- Triglyceride:Natural molecular structure preferred for bioavailability in pediatric and geriatric delivery formats.
Fish Oil holds the largest share; momentum sits with Algal Oil.
End User:
Cost tier stratification separates premium pharmaceutical-grade purchasers from commodity-volume dietary supplement brands, with pet nutrition emerging as a mid-tier growth corridor.
- Dietary Supplements:Volume leader commanding the broadest SKU proliferation across softgel and liquid formats. German and Australian brands now mandate supplier sustainability attestations as standard contract terms, compressing acceptable supplier pools.
- Pet Nutrition:Companion animal owners in Germany and Japan purchase omega-3 fortified formulations at human-grade purity standards. Premiumization in this segment opens adjacent revenue pools with margin structures approaching pharmaceutical applications.
- Functional Foods:Bakery and dairy fortification applications requiring oxidative stability and neutral flavor profiles.
- Pharmaceuticals:Prescription-grade EPA/DHA concentrates for hypertriglyceridemia and anti-inflammatory protocols, governed by FDA and NMPA drug master file requirements.
Dietary Supplements anchors volume; Pet Nutrition climbs the fastest.
Form:
Manufacturing scale and compliance intensity vary dramatically by delivery system, with liquid formats demanding specialized filling infrastructure and pediatric-focused stability testing.
- Softgel:Encapsulated oil-in-gelatin matrix maintaining oxidation protection and dose precision. Dominates adult supplement shelves in retail pharmacy channels across Japan and Germany.
- Liquid:Non-encapsulated oil requiring flavor masking and stability engineering. Geriatric and infant compliance segments in Australia show unmet demand for non-softgel delivery systems, creating formulation white space.
- Powder:Microencapsulated or spray-dried formats for functional food integration and pet kibble coating.
- Capsule:Hard-shell alternatives to softgels for vegetarian positioning and reduced gelatin content.
Softgel holds the largest share; Liquid gains share fastest in compliance-driven segments.
Application:
Clinical substantiation depth determines pricing power, with cardiovascular health claims supported by decades of trial data while immune support remains underdeveloped.
- Cardiovascular Health:EPA-dominant concentrates for triglyceride reduction and endothelial function support. FDA-approved prescription omega-3 products anchor this segment's premium tier.
- Brain Function:DHA-dominant formulations for cognitive development and neuroprotection. Infant formula manufacturers in China prioritize algal-derived DHA for prenatal and early-life nutrition.
- Joint Health:Anti-inflammatory applications in sports nutrition and osteoarthritis management, competing with glucosamine and collagen alternatives.
- Immune Support:Emerging positioning leveraging specialized pro-resolving mediators derived from EPA and DHA metabolism.
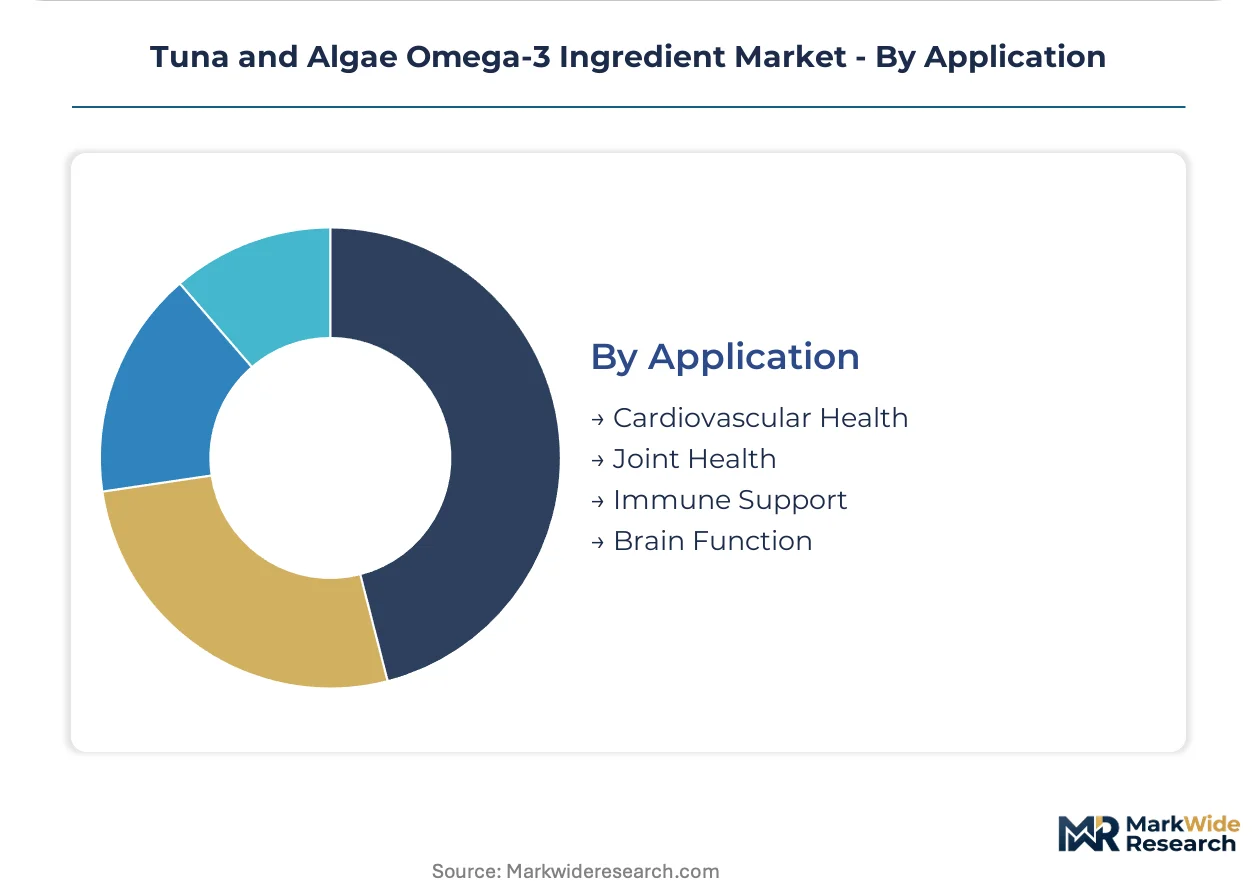
Cardiovascular Health holds the largest share; Brain Function shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Australia demonstrate the lowest price elasticity, mandating sustainability attestations as standard contract terms, while Chinese infant formula manufacturers exhibit higher sensitivity to EPA/DHA concentrate costs despite volume commitments.
United States
FDA New Dietary Ingredient notification requirements delay novel concentrate launches by 18-24 months, compressing acceptable supplier pools for domestic dietary supplement brands. Pharmaceutical-grade EPA/DHA concentrates gain traction among infant formula manufacturers seeking compliant supply chains. Boston and New Jersey clusters host medical nutrition formulation specialists customizing patient-specific ratios.
Germany
EFSA contaminant threshold tightening accelerates algae-derived alternatives as established tuna oil refiners absorb capital costs for enhanced purification systems. EU Green Deal carbon footprint disclosure mandates favor fermentation-based producers with measurable Scope 3 advantages. Frankfurt and Hamburg anchor integrated biotechnology platforms controlling captive fermentation capacity.
China
NMPA drug master file submissions govern pharmaceutical-grade omega-3 imports, elevating capital barriers for new entrants and rewarding pre-qualified suppliers. Infant formula manufacturers prioritize algal-derived DHA for prenatal and early-life nutrition at parity pricing to fish oil equivalents. Yangtze River Delta fermentation facilities achieve pharmaceutical-grade yields matching marine-derived concentrates.
Japan
PMDA regulations and METI industrial standards shape market access for novel omega-3 concentrates in dietary supplement channels. Companion animal owners purchase omega-3 fortified formulations at human-grade purity standards, opening adjacent revenue pools. Osaka and Nagoya clusters concentrate softgel manufacturing infrastructure for adult supplement retail pharmacy distribution.
Australia
TGA therapeutic goods regulations intersect with EFSA-aligned contaminant protocols for imported marine lipids. Geriatric and infant compliance segments show unmet demand for non-softgel liquid delivery systems, creating formulation white space. Sydney and Melbourne dietary supplement brands now require supplier sustainability attestations as mandatory procurement criteria.
Tuna and Algae Omega-3 Ingredient Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with biotechnology platforms commanding premium positioning while commodity traders compete on volume scale. The market structures around three strategic tiers: integrated fermentation specialists, marine capture processors, and formulation service providers. Dominant competitive moves include heterotrophic fermentation scale-up investments and downstream purification system upgrades.
Among biotechnology-anchored producers, BASF SE and DSM-Firmenich exemplify integrated platform operators, while Aker BioMarine occupies a position within marine-sourced phospholipid-bound derivatives. These three entities represent divergent supply chain configurations—controlled-environment fermentation, Antarctic krill harvesting partnerships, and Nordic tuna processing alliances—each anchoring distinct competitive vectors without overlapping core technologies.
| Leading Market Players |
|---|
| BASF SE |
| Polaris S.A. |
| Archer Daniels Midland Company |
| AlgaeCytes |
| Source-Omega LLC |
| Corbion N.V. |
| Aker BioMarine |
| Golden Omega |
| DSM-Firmenich |
| Others |
Pricing and Supply Chain Analysis
Ninety-day fermentation cycles for pharmaceutical-grade algal oil concentrate inventory holdings in German and Chinese facilities, compressing working capital efficiency for biotechnology platforms while extending pricing power over marine-dependent competitors facing seasonal tuna byproduct scarcity.
Pricing Analysis
After-sales technical service contracts for customized EPA/DHA ratio formulations drive lifetime value capture in medical nutrition channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade purity levels separates premium validators from commodity suppliers. Cost compression in standard-grade fish oil concentrates intensifies as Chinese infant formula manufacturers negotiate volume offtakes at parity to algal alternatives. Dietary supplement brands in Germany exhibit lowest price sensitivity, while functional food fortification buyers in emerging markets anchor the economy tier.
Supply Chain Analysis
Inventory concentration in controlled-environment fermentation facilities across Germany, China, and the Netherlands insulates biotechnology platforms from marine ecosystem volatility. Pharmaceutical-grade output draws from Schizochytrium and Crypthecodinium strain banks, molecular distillation equipment, and downstream purification resin systems. Single-source vulnerability concentrates in Antarctic krill harvesting fleets for phospholipid-bound omega-3 derivatives. Distribution runs through integrated life sciences distributors for pharmaceutical channels and direct procurement contracts for infant formula manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as plant-derived omega-3 from genetically engineered oilseed crops threatens to displace fermentation-based algal oil in cost-sensitive applications.
For Market Incumbents: Fortify captive fermentation capacity in the Yangtze River Delta and Rhine-Ruhr corridor to secure pharmaceutical-grade output ahead of oilseed crop substitutes. Deepen backward integration into proprietary strain development to protect margin structures against commodity algal oil entrants. Prioritize EFSA and FDA dual-dossier maintenance to preserve multi-jurisdiction access as regulatory complexity escalates. For New Entrants and Emerging Players: FDA New Dietary Ingredient notification fast-tracks offer regulatory arbitrage for novel delivery formats targeting pediatric liquid white space in Australian and Japanese compliance segments. Penetrable ground sits with geriatric non-softgel formulations where established players lack specialized stability engineering capabilities. Go-to-market positioning should emphasize carbon footprint documentation advantages under EU Green Deal procurement mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized fermentation assets and dormant pharmaceutical-grade certification pathways. Long-term viability favors biotechnology platforms with integrated strain-to-refinement control over commodity traders exposed to wild-catch volatility. Signal to monitor: NMPA drug master file approval velocity for imported concentrates as a proxy for Chinese market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Heterotrophic Fermentation Scale-Up | Captive production in German and Chinese facilities matches marine-derived bioavailability metrics at controlled carbon intensity. |
| Pharmaceutical-Grade Purification Upgrade | Downstream molecular distillation investments preserve EFSA compliance as contaminant thresholds tighten for European infant formula supply. |
| Pediatric Liquid Formulation Development | Non-softgel delivery systems address unmet demand in Australian geriatric and infant compliance segments with specialized stability protocols. |
| Dual-Jurisdiction Dossier Expansion | Simultaneous FDA and NMPA pre-qualification elevates capital barriers for competitors while securing Chinese pharmaceutical channel access. |
| Carbon Footprint Disclosure Integration | EU Green Deal Scope 3 reporting capabilities favor fermentation-based producers in German and Australian procurement decisions. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation technology directors, infant formula procurement managers, regulatory affairs specialists at omega-3 concentrate suppliers, and dietary supplement brand formulation scientists, then refined through secondary validation against EFSA contaminant threshold documentation, FDA New Dietary Ingredient notification databases, NMPA drug master file registries, and customs trade records for tuna byproduct flows. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand segmentation across end-use applications.
Variance decomposition across product type, end-user tier, geographic regulatory cluster, and delivery format dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic demand drivers and technology substitution curves. Forecast inputs incorporated heterotrophic fermentation yield improvements and EFSA compliance cost absorption trajectories for marine-derived refiners.
Decision-makers should treat outputs as directional under sustained pharmaceutical-grade purity premium assumptions and stable Antarctic krill harvest volumes; material deviation in oilseed crop omega-3 bioavailability breakthroughs or EFSA threshold further tightening would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Grapeseed Oil Market
Ingredients
Desiccated Coconut Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Global Dietary Fibers Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Tryptose Market
Ingredients
Green Gram Powder Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Specialty Yeast Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
Modified Maize Starch Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Asia-Pacific Fats and Oil Market