
 Global Dried Processed Food Market | 2026-2036
Global Dried Processed Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dried Processed Food Market Intelligence
Food engineering talent shortages in thermal processing and dehydration automation is redrawing competitive boundaries across the dried processed food sector. Nestlé leverages its captive R&D network to sustain proprietary freeze-dried coffee platforms across multiple continents. Unilever anchors its position through backward integration into sustainable sourcing corridors for soup and sauce applications. Kraft Heinz competes aggressively in North American retail with shelf-stable pasta and cheese portfolios.
Dried processed food encompasses products rendered shelf-stable through controlled moisture removal, typically achieving water activity levels below 0.60 using convective, conductive, or sublimation-based thermal energy transfer. The primary commercial purpose is preservation of nutritional density and flavor compounds while eliminating cold-chain dependency across extended distribution loops. Freeze-dried formats command premium positioning in nutritional supplements and ready-to-eat meals where structural integrity and rehydration speed determine procurement decisions. Spray-dried ingredients dominate bakery and beverage mix supply chains due to superior flowability and instant solubility profiles. Oven-dried and sun-dried categories occupy mature, cost-sensitive snack food segments with thinner margin pools and commodity pricing dynamics.
FDA food safety modernization rules and USDA organic certification requirements shape product standards and facility audit protocols for manufacturers accessing US retail channels. EFSA nutritional labeling directives and EU Green Deal sustainability benchmarks constrain packaging choices and carbon disclosure obligations across European distribution. China's SAMR national food safety standards and GB quality benchmarks govern import access and domestic production licensing. Stakeholders must monitor evolving dual carbon goals in Asia alongside tightening MEE emissions enforcement for thermal drying operations.
Market Dynamics
The EU F-Gas Regulation and REACH compliance requirements are compressing capital deployment timelines for thermal processing equipment across European manufacturing bases. Low-energy drying technologies now determine facility upgrade sequencing and cross-border investment flows.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework accelerates domestic spray-dried ingredient capacity expansion for export-oriented food ingredient supply chains.
- Military procurement programs:Defense and emergency relief agencies across NATO member states expand multi-year dried ration contracts, creating predictable offtake volumes for shelf-stable meal manufacturers.
- Freeze-drying automation:Advances in continuous lyophilization systems reduce unit energy consumption and labor intensity for nutritional supplement processors.
Market Restraints
- Natural gas price volatility:Convective and conductive drying operations face margin compression from input energy cost swings in European and Asian manufacturing clusters.
- Chinese equipment concentration:Spray dryer fabrication capacity concentrates in eastern China, creating supply chain vulnerability for buyers seeking tariff-diversified sourcing.
- Refrigeration substitution:Cold-chain infrastructure expansion in Southeast Asia and sub-Saharan Africa reduces relative cost advantage of shelf-stable formats for certain dairy and protein categories.
Strategic Opportunities
- Sub-Saharan Africa distribution:Underdeveloped retail cold-chain networks in Nigeria, Kenya, and Ethiopia favor ambient-stable formats for infant nutrition and emergency food programs.
- Solar thermal drying:Convergence of photovoltaic generation and conductive drying systems enables off-grid processing nodes for fruit and vegetable cooperatives.
- EU Green Deal packaging mandates:Compostable and mono-material packaging requirements create first-mover advantage for manufacturers with integrated sustainable packaging R&D.
Industry Challenges
- Thermal process engineering talent scarcity:Food engineering programs produce insufficient graduates with dehydration automation and heat transfer optimization expertise.
- Dual certification timelines:Simultaneous USDA organic and EU organic compliance audits extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dried Processed Food Market |
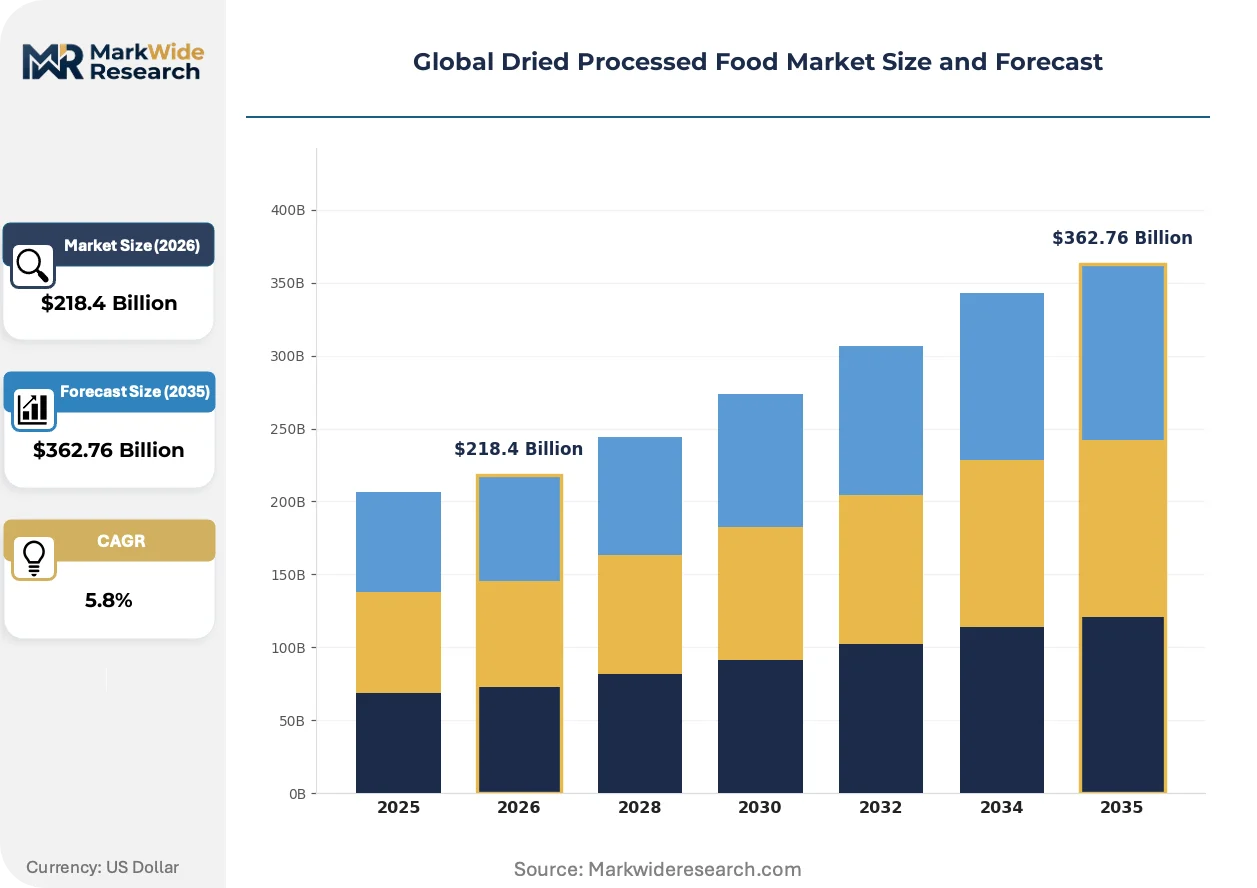
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $362.76 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Spray-Dried, Oven-Dried, Sun-Dried, Drum-Dried, Others Application: Snack Foods, Ready-to-Eat Meals, Bakery Ingredients, Beverage Mixes, Culinary Additives, Nutritional Supplements Packaging Type: Vacuum Packs, Stand-Up Pouches, Glass Jars, Plastic Containers, Retort Pouches, Paper Bags Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Stores, Convenience Stores, Wholesale Distribution, Food Service Providers |
| Companies Covered | Nestlé, Unilever, Kraft Heinz, Campbell Soup Company, General Mills, Ajinomoto, B&G Foods, Nissin Foods, Hormel Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dried Processed Food Market Strategic Shifts & Innovations
Controlled moisture removal technologies are fragmenting into specialized process architectures optimized for specific end-use rehydration performance requirements. Equipment vendors and ingredient processors now compete on energy efficiency metrics and carbon disclosure transparency rather than throughput alone.
Microwave-assisted vacuum drying is decomposing the traditional freeze-dry versus spray-dry dichotomy in nutritional ingredient processing. Sports nutrition and clinical meal manufacturers adopt hybrid systems that achieve intermediate structural integrity at substantially reduced energy intensity. This convergence is compressing premium positioning for conventional freeze-dried formats while elevating quality thresholds for mass-market spray-dried alternatives.
REACH authorization procedures for industrial chemicals used in food-contact drying equipment are extending equipment qualification timelines for European installations. Manufacturers face reformulation requirements for lubricants, sealants, and heat transfer fluids. The bakery and beverage mix segments, with their high equipment turnover rates, absorb disproportionate compliance costs relative to longer-cycle ready-to-eat meal operations.
Direct-to-manufacturer ingredient sourcing is displacing layered distributor networks for spray-dried dairy and plant protein powders. Large bakery and confectionery groups in Germany, the Netherlands, and the United States establish technical partnerships with drying facilities for custom particle size and solubility specifications. This disintermediation compresses margin pools for traditional ingredient traders while rewarding processors with in-house application laboratories.
Global Dried Processed Food Market Segmentation
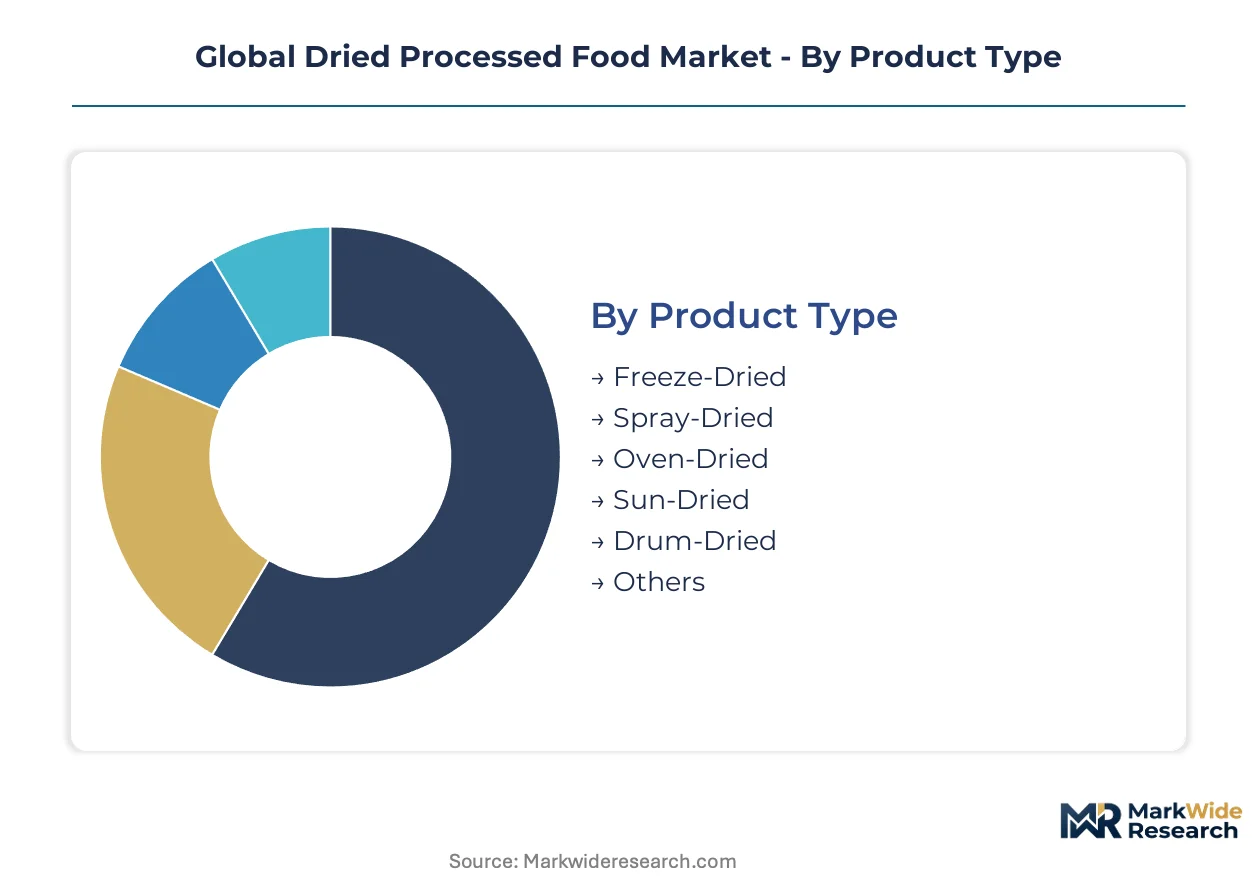
Dried processed food markets fragment along technical process lines that determine rehydration performance, energy intensity, and shelf-life economics. Procurement decisions across military, retail, and industrial channels map directly to these segment boundaries, with freeze-dried formats commanding premium positioning while spray-dried alternatives dominate volume throughput.
Product Type:
Margin pools concentrate in lyophilization systems where equipment utilization rates and pharmaceutical-grade certifications create defensible pricing power.
- Freeze-Dried:Sublimation-based moisture removal preserves cellular structure and rapid rehydration kinetics. Military ration programs in the United States and emergency relief procurement across NATO member states concentrate demand for entrees and nutritional supplements requiring minimal preparation infrastructure.
- Spray-Dried:Atomization and hot-air convection produce free-flowing powders with instant solubility profiles. India's PLI scheme incentives are accelerating domestic capacity for dairy and plant protein ingredients serving export-oriented bakery and beverage supply chains.
- Oven-Dried:Batch conductive heating suits fruit and vegetable snacks where texture variation tolerance exists.
- Sun-Dried:Passive solar exposure dominates artisanal and cooperative-scale operations in Mediterranean and sub-Saharan African production clusters.
- Drum-Dried:Thin-film conductive processing serves commodity starch and cereal flake applications with thinner margin structures.
- Others:Emerging microwave-assisted and radio-frequency systems occupy pilot-scale niches seeking energy efficiency breakthroughs.
The dominant share belongs to spray-dried formats, while freeze-dried applications are closing the gap fastest through military and clinical nutrition procurement expansion.
Application:
Volume concentration tracks cold-chain infrastructure gaps, with ambient-stable formats gaining relative advantage where refrigeration penetration remains shallow.
- Snack Foods:Fruit chips, vegetable crisps, and meat jerky occupy mature retail segments with established consumer acceptance. Nigerian and Kenyan distribution networks favor these formats for urban convenience retail where cold storage is unreliable.
- Ready-to-Eat Meals:Complete shelf-stable entrees require multi-component moisture management and oxygen barrier packaging. Defense procurement agencies across Germany, France, and the United Kingdom are extending multi-year supply contracts for field ration systems.
- Bakery Ingredients:Spray-dried egg powders, dairy solids, and leavening agents supply industrial-scale bread and confectionery manufacturing.
- Beverage Mixes:Instant coffee, tea extracts, and protein fortification powders demand precise particle size distribution for dispersibility.
- Culinary Additives:Dried stocks, seasoning blends, and sauce bases serve food service and industrial kitchen channels.
- Nutritional Supplements:Clinical meal replacements and sports nutrition products require preserved bioactive compound stability.
Snack foods retain the largest volume position, though ready-to-eat meals are expanding most quickly through institutional procurement channel development.
Packaging Type:
Regulatory pressure on single-use plastics is reshaping capital allocation toward mono-material and compostable barrier systems.
- Vacuum Packs:Multi-layer metallized films achieve oxygen transmission rates below 0.1 cc/m²/day for oxygen-sensitive lipids and proteins.
- Stand-Up Pouches:Flexible format with resealability dominates retail snack and beverage mix segments in German and Dutch supermarket channels.
- Glass Jars:Premium positioning for gourmet and gift-oriented dried fruit and culinary additive assortments.
- Plastic Containers:Rigid polyethylene terephthalate and polypropylene formats serve institutional food service bulk procurement.
- Retort Pouches:High-temperature sterilization compatibility for complete meal applications requiring commercial sterility.
- Paper Bags:Kraft-based formats with grease-resistant coatings occupy cost-sensitive commodity segments and direct-to-consumer artisanal channels.
Vacuum packs hold the dominant technology position, while stand-up pouches are gaining share fastest through retail channel format conversion.
Distribution Channel:
Customer access patterns diverge between developed markets where e-commerce penetration is deepening and emerging economies where traditional trade still governs reach.
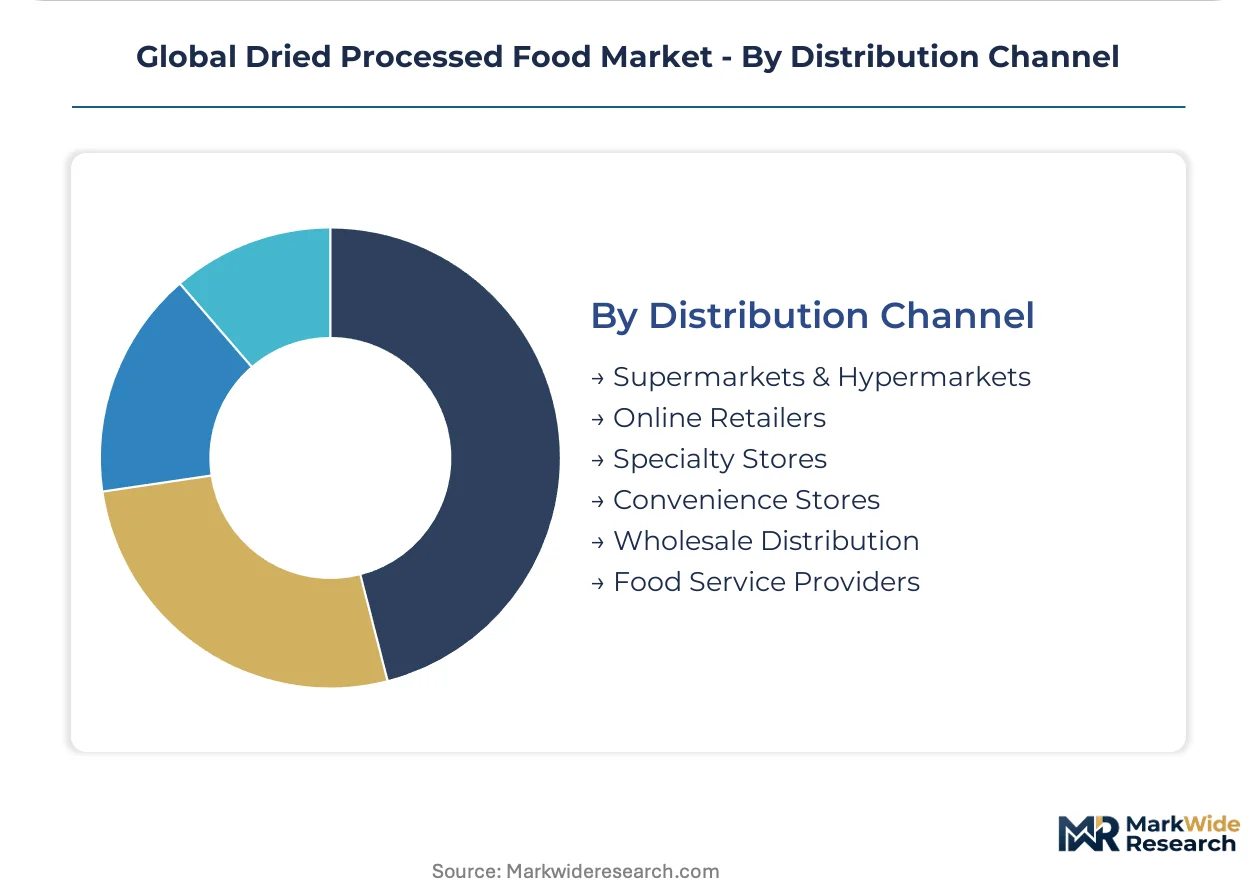
- Supermarkets & Hypermarkets:Category management and private label development concentrate volume in Kroger, Carrefour, and Ahold Delhaize systems across the United States and European Union.
- Online Retailers:Direct-to-consumer subscription models for nutritional supplements and specialty dried ingredients are scaling through Amazon and regional platforms in India and Southeast Asia.
- Specialty Stores:Gourmet and health-focused independents curate premium freeze-dried and artisanal sun-dried assortments.
- Convenience Stores:Single-serve snack formats target immediate consumption occasions in urban Japan and South Korea.
- Wholesale Distribution:Industrial ingredient supply to bakery, confectionery, and food service manufacturers runs through Unilever Food Solutions and similar B2B networks.
- Food Service Providers:Contract catering and institutional feeding operations procure shelf-stable components for menu cost management.
Supermarkets and hypermarkets maintain the dominant channel position, while online retailers are climbing the fastest through subscription nutrition model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food safety modernization rules anchor the United States as the regulatory benchmark for dried processed food standards worldwide. Military procurement programs and emergency relief agencies across NATO member states are expanding multi-year dried ration contracts. India's PLI scheme incentives and BIS certification standards are accelerating domestic spray-dried ingredient capacity for export markets.
United States
Defense procurement agencies and emergency relief programs drive demand for freeze-dried entrees and nutritional supplements. FDA food safety modernization rules and USDA organic certification requirements shape facility audit protocols and product standards. Chicago and Minneapolis-St. Paul industrial corridors host major shelf-stable pasta and soup manufacturing clusters serving North American retail channels.
Germany
Industrial bakery and confectionery groups procure custom spray-dried dairy and plant protein powders for large-scale bread manufacturing. EU F-Gas Regulation and REACH compliance requirements compress capital deployment timelines for thermal processing equipment upgrades. The Rhine-Ruhr and Bavarian manufacturing belts concentrate low-energy drying technology adoption for sustainable production mandates.
India
Export-oriented food ingredient supply chains and domestic convenience food retail expansion accelerate spray-dried capacity buildout. BIS certification standards and PLI scheme incentives reward domestic manufacturing investment with tariff advantages and capital subsidies. Gujarat and Maharashtra industrial zones host emerging spray-dried dairy and plant protein processing hubs targeting Middle East and Southeast Asian markets.
China
Domestic instant beverage and nutritional supplement markets absorb substantial spray-dried and freeze-dried ingredient volumes. SAMR national food safety standards and GB quality benchmarks govern import access and domestic production licensing requirements. Yangtze River Delta manufacturing clusters concentrate spray dryer fabrication capacity serving regional bakery and beverage mix processors.
Brazil
Urban convenience retail and food service channels favor ambient-stable formats where cold-chain infrastructure remains underdeveloped. ANVISA sanitary surveillance standards regulate dried fruit and meat product manufacturing for domestic consumption and export. São Paulo state industrial zones anchor fruit chip and jerky processing capacity serving Mercosur distribution networks.
Global Dried Processed Food Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the dried processed food sector. The market structure fragments between multinational conglomerates with captive R&D networks and regional specialists with flexible contract manufacturing capabilities. Three archetypes dominate: diversified food conglomerates with backward integration into sustainable sourcing corridors, mid-scale processors with application laboratory partnerships for custom specifications, and equipment-integrated ingredient suppliers with energy efficiency differentiation. Competitive moves concentrate on strategic partnerships for direct-to-manufacturer ingredient sourcing and portfolio diversification into low-energy drying technologies.
Within the diversified conglomerate tier, Nestlé and Unilever exemplify archetypes with proprietary freeze-dried platforms and sustainable sourcing integration. Nestlé represents technology leadership through captive R&D networks sustaining multi-continental freeze-dried coffee operations. Unilever anchors cost-competitive positioning through backward integration into soup and sauce ingredient supply chains. Kraft Heinz occupies a position exemplifying retail-focused scale advantages in North American shelf-stable pasta and cheese portfolios.
| Leading Market Players |
|---|
| Nestlé |
| Unilever |
| Kraft Heinz |
| Campbell Soup Company |
| General Mills |
| Ajinomoto |
| B&G Foods |
| Nissin Foods |
| Hormel Foods |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between military procurement agencies and freeze-dried meal manufacturers lock in supply access and price visibility across multi-year horizons, insulating premium tiers from natural gas volatility while exposing spot-market participants to margin compression.
Pricing Analysis
European freeze-dried formats command substantial premiums over Asian spray-dried alternatives due to REACH compliance costs and energy-intensive sublimation processing. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade lyophilization from commodity spray-dried powders and artisanal sun-dried categories. Cost compression in standard-tier spray-dried dairy intensifies because Indian PLI-subsidized capacity floods export markets. Military buyers exhibit lowest price sensitivity due to mission-critical specifications, while African retail distributors face acute budget constraints.
Supply Chain Analysis
China, India, and Germany anchor global spray dryer fabrication and thermal processing equipment production. Raw material flows draw from Australian milk solids, Ukrainian sunflower proteins, and Southeast Asian tropical fruit pulps. Single-source vulnerability concentrates in eastern Chinese equipment manufacturing clusters subject to tariff exposure. Distribution runs through Unilever Food Solutions and comparable B2B ingredient networks serving industrial bakery and confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain infrastructure expansion across Southeast Asia and sub-Saharan Africa threatens shelf-stable format relevance, forcing incumbents to defend ambient-stable positioning against refrigerated alternatives.
For Market Incumbents: Fortify proprietary freeze-dried platforms through captive R&D networks sustaining multi-continental operations. Deepen backward integration into sustainable sourcing corridors for soup and sauce ingredients to offset margin pressure from energy cost volatility. Secure BIS certification and PLI scheme qualifications in India to maintain tariff-advantaged export access. For New Entrants and Emerging Players: Lead with solar thermal drying cooperatives targeting off-grid fruit and vegetable processing nodes in Ethiopia and Kenya. Exploit underdeveloped retail cold-chain networks in Nigerian urban convenience retail where ambient-stable formats retain structural advantage. Establish technical partnerships with European bakery groups for custom particle size specifications. For Investors and Strategic Acquirers: Application-integrated mid-scale processors with in-house laboratories and energy efficiency differentiation represent priority acquisition targets. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for low-energy drying technology adoption rates. Long-term viability hinges on carbon disclosure transparency and sustainable packaging R&D integration.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Energy Drying Technology Adoption | EU F-Gas Regulation compliance compresses capital deployment timelines for European thermal processing upgrades. |
| Direct-to-Manufacturer Ingredient Sourcing | Disintermediation of distributor networks rewards processors with in-house application laboratories and custom specification capabilities. |
| Sustainable Packaging R&D Integration | EU Green Deal compostable mandates create first-mover advantage for manufacturers with integrated barrier system development. |
| PLI Scheme Capacity Expansion | Indian production-linked incentives accelerate domestic spray-dried dairy and plant protein processing for Middle East exports. |
| Military Procurement Contract Extension | NATO defense agencies extend multi-year dried ration offtake agreements creating predictable volume for freeze-dried entree manufacturers. |
Research Approach
The analysis maps freeze-dried, spray-dried, oven-dried, and sun-dried sub-sectors, each validated through thermal process engineers, procurement managers at bakery and confectionery groups, military supply officers, and equipment vendor technical directors. Primary interview insights triangulate against BIS certification databases, EU F-Gas Regulation implementation records, PLI scheme disbursement filings, and customs trade data for dairy and plant protein powders. Bottom-up facility capacity assessments reconcile with top-down demand modeling across military, retail, and industrial channels.
Consistency checks validate volume and value outputs against EFSA nutritional labeling directive adoption curves, SAMR food safety standard enforcement patterns, and ANVISA sanitary surveillance audit frequencies. Segmentation dimensions span drying technology type, application category, packaging format, and distribution channel complexity. CAGRs derive from facility utilization rate trajectories, energy cost scenario modeling, and procurement contract renewal patterns across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained military procurement expansion or accelerated cold-chain infrastructure buildout would require recalibration. Forecasts reflect assumptions regarding natural gas price stabilization, REACH authorization timeline adherence, and dual carbon goal enforcement intensity in Asian manufacturing clusters. Recalibration cycles align with material shifts in EU Green Deal packaging mandates and PLI scheme incentive modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
South America Soup Market
Processed Foods
Processed Vegetable Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Superfruits Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Cashew Market
Processed Foods
Fat Free Food Market
Processed Foods
Global Potato Flake Market
Processed Foods
Fresh Pasta Market
Processed Foods
Europe Soup Market
Processed Foods
United States Food Spread Market
Processed Foods
Spreadable Fats Market
Processed Foods
Processed Potatoes Market
Processed Foods
Processed Peanut Market