
 South America Food Flavor and Enhancer Market | 2026-2036
South America Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Flavor and Enhancer Market Analytics
ANVISA's updated food additive standards is rebalancing compliance costs for new entrants across Brazil, Argentina, and Colombia. Givaudan leverages its botanical extraction network to secure regional supply chains for natural flavor compounds. Kerry Group anchors its position through integrated taste and nutrition platforms serving multinational food manufacturers. Firmenich differentiates via captive biotechnology capabilities that reduce reliance on imported precursor materials.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active molecules, and synergistic additives formulated to modify or intensify sensory perception in finished food products; these systems typically operate at parts-per-million inclusion rates and undergo spray-drying, encapsulation, or solvent extraction during manufacture to ensure thermal stability and controlled release in processing environments. Natural extracts command premium positioning among health-conscious consumers, while synthetic flavorings retain volume leadership in cost-sensitive beverage and snack applications. Seasoning blends concentrate margin pools in quick-service restaurant supply contracts, whereas flavor enhancers such as yeast extracts and nucleotides gain traction in sodium-reduction formulations across dairy and bakery channels.
ANVISA in Brazil, the National Administration of Drugs, Foods and Medical Devices in Argentina, and Peru's national health authority collectively enforce maximum permissible levels for artificial flavor carriers and mandate disclosure thresholds for natural-origin claims on consumer packaging. These frameworks elevate reformulation costs but simultaneously redirect procurement budgets toward certified clean-label suppliers with documented supply chain traceability. Stakeholders must monitor pending harmonization discussions across Mercosur member states, as regulatory alignment would reshape cross-border manufacturing strategies and ingredient sourcing protocols.
Market Dynamics
ANVISA's tightening clean-label mandates are forcing reformulation cycles across Brazil's processed food sector, compressing product development timelines and redirecting procurement budgets toward certified natural extract suppliers with documented traceability systems.
Growth Catalysts
- Brazil's southeastern manufacturing corridor:São Paulo's food processing cluster drives concentrated demand for bulk seasoning blends and natural flavor systems, creating procurement scale advantages for regional suppliers.
- Yeast extract adoption:Sodium-reduction formulations in dairy and bakery channels are pulling nucleotide-based enhancers into standard ingredient specifications.
- Mercosur harmonization discussions:Pending regulatory alignment across member states is accelerating cross-border manufacturing investments and unified sourcing protocols.
Market Restraints
- Natural extract cost volatility:Weather-dependent botanical harvests in Argentina and Colombia create input price instability for clean-label flavor compounds.
- Import dependency for synthetic precursors:Limited regional production of aromatic chemical intermediates concentrates supply risk with Asian manufacturers.
- ANVISA disclosure thresholds:Stricter natural-origin claim verification extends certification timelines and elevates compliance documentation burdens.
Strategic Opportunities
- Peru's underdeveloped flavor sector:Lima's emerging food manufacturing base offers first-mover positioning for natural extract suppliers establishing local blending facilities.
- Quick-service restaurant supply contracts:Seasoning blend procurement for regional QSR chains concentrates margin pools and locks in multi-year volume commitments.
- Biotechnology convergence:Precision fermentation platforms for natural flavor molecules are reducing reliance on agricultural feedstocks and import exposure.
Industry Challenges
- Flavor chemist talent scarcity:Limited regional training programs for sensory science and encapsulation engineering constrain R&D throughput for mid-tier manufacturers.
- Thermal stability certification:Validating spray-dried flavor performance across diverse processing environments extends product qualification cycles.
- Legacy ERP integration:Batch traceability requirements for ANVISA compliance clash with outdated inventory management systems at family-owned processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Flavor and Enhancer Market |
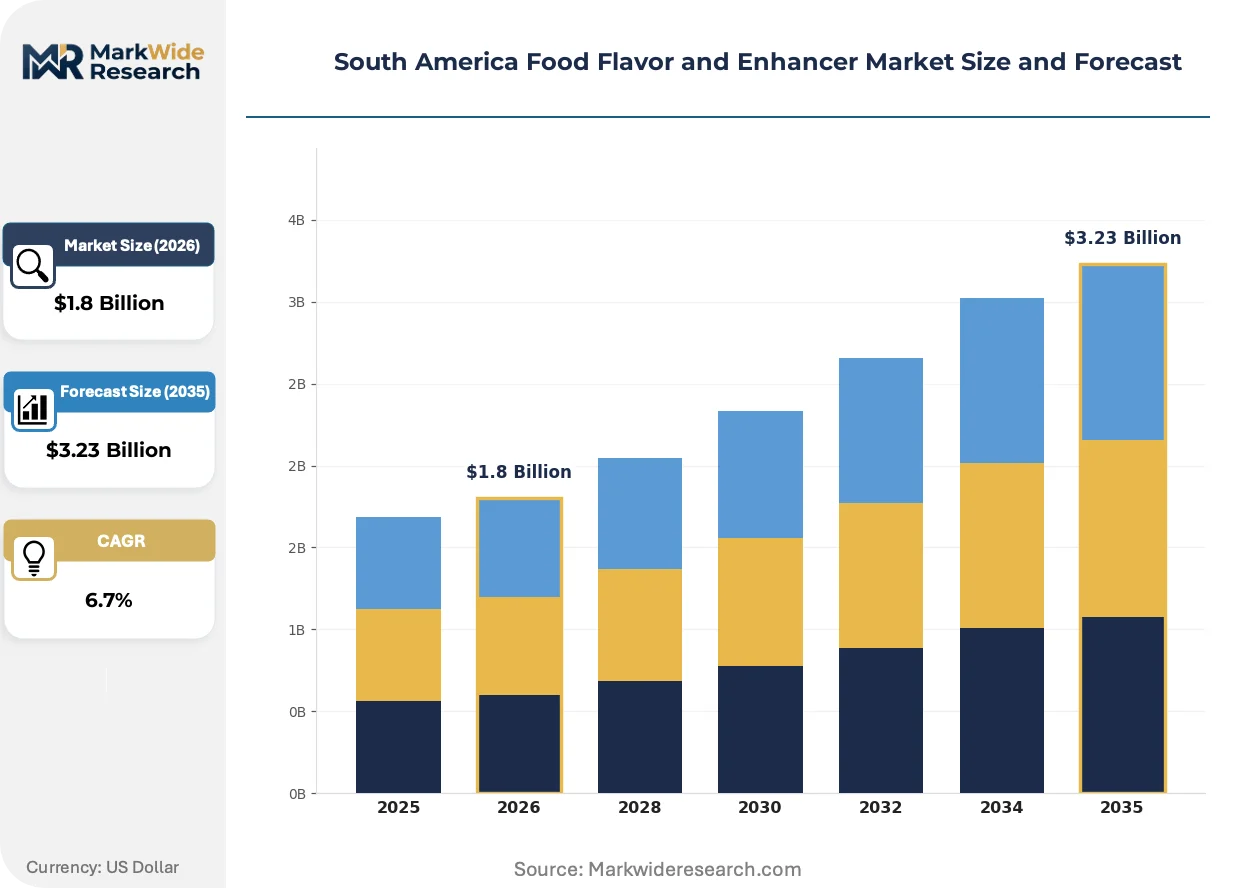
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Synthetic Flavorings, Seasoning Blends, Flavor Enhancers Application: Beverages, Dairy Products, Bakery Items, Snacks End User: Food Manufacturers, Restaurants, Retailers, Culinary Professionals Form: Liquid, Powdered, Granulated, Concentrated |
| Companies Covered | Givaudan, Firmenich, Kerry Group, International Flavors and Fragrances Inc., Symrise, Archer Daniels Midland Company, Ajinomoto, Cargill, Koninklijke DSM NV, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Flavor and Enhancer Market Evolving Landscape
Encapsulation technologies and biotechnology platforms are compressing the cost premium between natural and synthetic flavor systems, while regulatory disclosure mandates are reshaping supplier qualification criteria across South American procurement departments.
Microencapsulation via complex coacervation is integrating controlled-release flavor systems into high-heat snack processing, protecting volatile aromatic compounds during extrusion and baking. Brazilian savory snack manufacturers are adopting these systems at pilot scale, with thermal stability benchmarks now written into supplier technical specifications. This integration is compressing reformulation costs for clean-label product lines and narrowing the performance gap against synthetic alternatives.
ANVISA's updated food additive standards are mandating granular disclosure of carrier solvents and processing aids in artificial flavor declarations, elevating documentation requirements for imported synthetic compounds. Industrial consequence includes procurement preference shifts toward regional natural extract suppliers with shorter, auditable supply chains. Argentine beverage manufacturers are most affected, accelerating internal reformulation timelines to preempt enforcement phase-ins.
Buyer concentration among multinational food manufacturers is consolidating flavor procurement into centralized technical buying centers, displacing fragmented regional distributor relationships. São Paulo-based procurement hubs now specify unified global flavor standards across Brazilian, Argentine, and Colombian production facilities. This concentration is most visible in dairy applications, where parent-company R&D mandates override local formulation autonomy and compress supplier rosters.
South America Food Flavor and Enhancer Market Segmentation
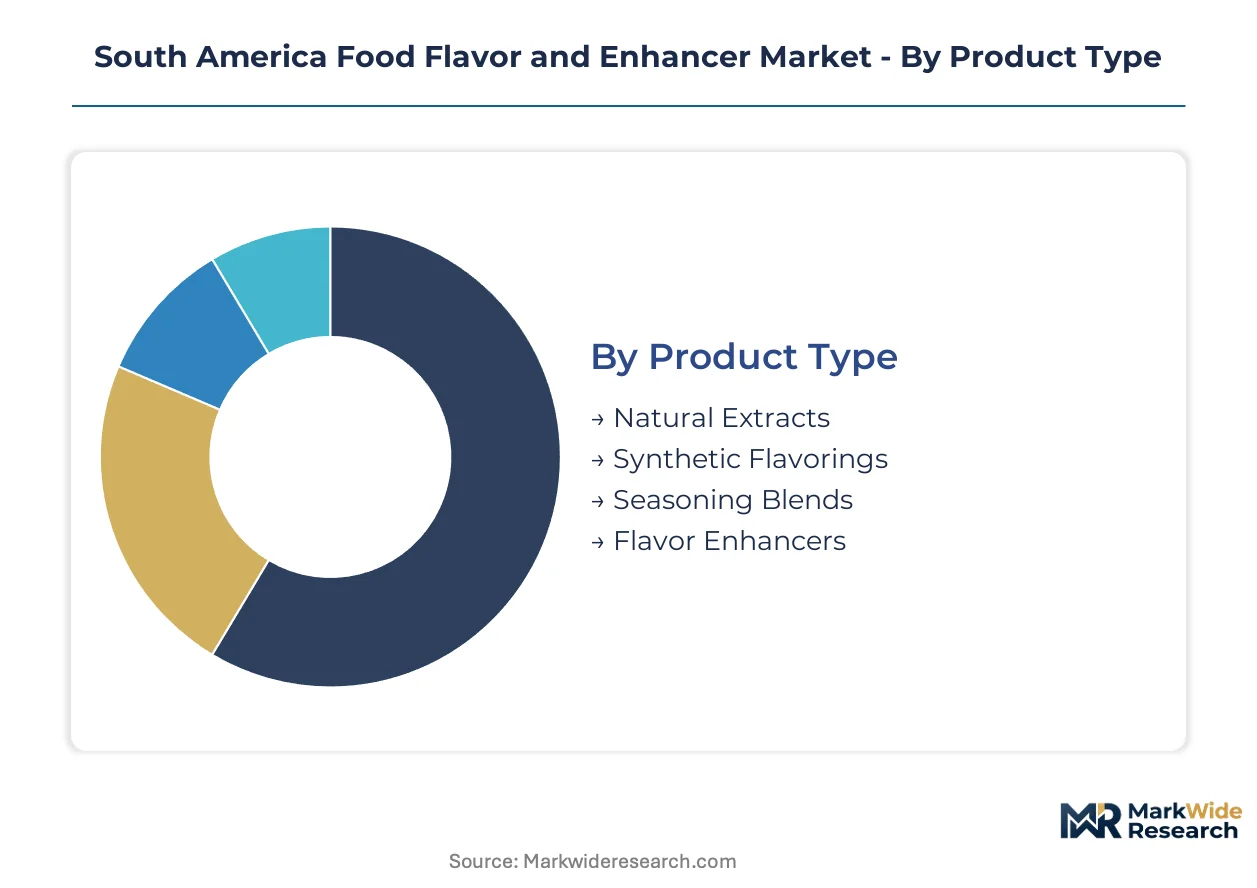
Segmentation in South America's food flavor market reveals how procurement budgets split across technical specifications and regulatory compliance tiers. Manufacturers configure their ingredient portfolios around ANVISA disclosure thresholds, thermal stability requirements, and end-use processing constraints.
Product Type:
Upgrade cycles in Brazil's processed food sector are accelerating as manufacturers replace synthetic systems with certified natural alternatives ahead of enforcement phase-ins.
- Natural Extracts:Botanical-derived aromatic compounds from citrus, vanilla, and tropical fruits undergo solvent extraction or steam distillation to achieve parts-per-million precision. São Paulo's beverage manufacturers are pulling these extracts into reformulated portfolios as ANVISA tightens clean-label verification timelines.
- Synthetic Flavorings:Chemically synthesized aromatic molecules engineered for thermal stability and cost efficiency at volume scale. Argentina's snack processors continue standardizing these compounds for extruded products where heat exposure degrades natural alternatives.
- Seasoning Blends:Pre-mixed savory formulations combining salt, spices, and flavor carriers for quick-service restaurant supply contracts.
- Flavor Enhancers:Yeast extracts and nucleotide-based compounds intensifying umami perception in sodium-reduced dairy and bakery applications.
Volume placements concentrate in Synthetic Flavorings; the faster expansion belongs to Natural Extracts.
Application:
Cost tiering across South American food manufacturing separates premium clean-label positioning from commodity volume plays.
- Beverages:Liquid flavor systems requiring acid stability and cold-chain compatibility throughout distribution. Brazilian soft drink bottlers in the southeastern corridor are consolidating procurement around natural citrus extracts to meet retailer clean-label mandates.
- Dairy Products:Fat-compatible flavor carriers and fermentation-derived enhancers formulated for pasteurization exposure. Argentine yogurt manufacturers are adopting nucleotide-based enhancers to maintain taste intensity in reduced-sodium lines.
- Bakery Items:Heat-stable encapsulated flavors protecting volatile compounds during oven processing.
- Snacks:High-intensity savory coatings and topical seasoning systems for extruded and fried products.
Procurement scale favors Snacks; margin expansion is steepest in Dairy Products.
End User:
Customer type determines specification depth, with multinational manufacturers imposing global technical standards on regional production facilities.
- Food Manufacturers:Industrial-scale buyers integrating flavor systems into packaged goods with batch traceability documentation. São Paulo-based procurement hubs now specify unified standards across Brazilian, Argentine, and Colombian plants, compressing regional supplier rosters.
- Restaurants:Quick-service chains sourcing concentrated seasoning blends through multi-year supply contracts with volume commitments.
- Retailers:Private-label product developers specifying clean-label claims for shelf differentiation.
- Culinary Professionals:Small-volume purchasers of premium extracts for artisanal and foodservice applications.
Contract concentration sits with Food Manufacturers; emerging demand flows from Restaurants.
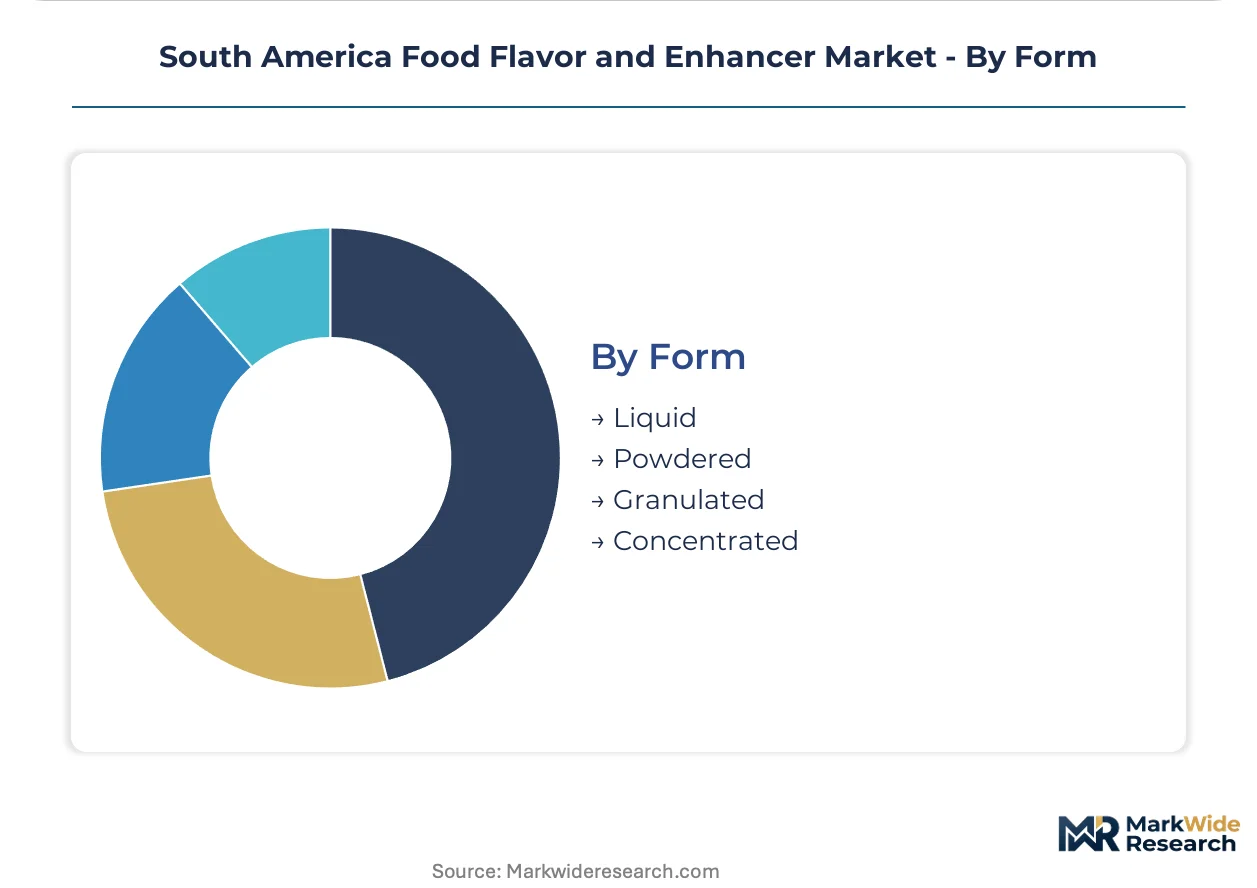
Form:
Supply concentration in Brazil's processing corridor shapes form factor preferences, with powder dominating bulk logistics and liquid serving beverage integration.
- Liquid:Solvent-based or emulsion flavor systems metered through automated dosing equipment. Brazilian beverage bottlers favor liquid formats for seamless integration into high-speed filling lines.
- Powdered:Spray-dried or plated flavors offering extended shelf stability and dry blending compatibility. Argentine bakery manufacturers standardize powdered formats for flour-based mixing processes.
- Granulated:Agglomerated particles reducing dust exposure and improving flow characteristics in seasoning applications.
- Concentrated:High-potency extracts requiring dilution prior to use, minimizing transport and storage costs.
Operational scale anchors Powdered; technical differentiation is climbing fastest in Concentrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement gravity concentrates in Brazil's southeastern manufacturing corridor, where São Paulo's food processing cluster generates concentrated demand for bulk flavor systems and natural extracts.
Brazil
Beverage manufacturers in São Paulo and Minas Gerais are consolidating procurement around natural citrus extracts to meet retailer clean-label mandates. ANVISA's updated food additive standards mandate granular disclosure of carrier solvents in artificial flavor declarations. São Paulo's food processing cluster drives bulk procurement of seasoning blends and natural flavor systems for multinational snack and dairy operations.
Argentina
Snack processors continue standardizing synthetic flavor compounds for extruded products where heat exposure degrades natural alternatives. The National Administration of Drugs, Foods and Medical Devices enforces maximum permissible levels for artificial flavor carriers. Buenos Aires province hosts concentrated dairy manufacturing where nucleotide-based enhancers are penetrating sodium-reduced yogurt lines.
Colombia
Bakery manufacturers are adopting encapsulated flavor systems to protect volatile compounds during high-temperature processing. The country's national health authority mandates disclosure thresholds for natural-origin claims on consumer packaging. Bogotá's food manufacturing base is expanding procurement of spray-dried flavors for flour-based mixing processes.
Peru
Lima's emerging food manufacturing base offers first-mover positioning for natural extract suppliers establishing local blending facilities. Peru's national health authority coordinates with Mercosur alignment discussions on cross-border regulatory harmonization. The capital's processing sector is attracting regional investment in flavor compounding infrastructure to serve Andean markets.
Chile
Wine and beverage producers in the Central Valley are integrating natural flavor systems for non-alcoholic product extensions. Chile's food safety authority maintains strict additive verification protocols aligned with international export standards. Santiago's metropolitan manufacturing zone concentrates technical procurement for multinational food operations serving Pacific trade routes.
South America Food Flavor and Enhancer Market Competitive Landscape
Swiss and Irish producers anchor the premium natural extract tier; Asian specialists hold positions in synthetic precursor supply. The vendor base stratifies across three functional layers: integrated taste-nutrition platforms, captive biotechnology operators, and regional distribution intermediaries. Strategic moves concentrate on backward integration into botanical sourcing and precision fermentation capacity builds.
Within the integrated platform tier, Kerry Group exemplifies the convergence of taste and nutrition capabilities serving multinational food manufacturers. Givaudan and Firmenich occupy positions among biotechnology-forward operators reducing agricultural feedstock dependency. These three anchors represent divergent competitive vectors: procurement consolidation, captive supply chains, and fermentation-based molecular production.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Kerry Group |
| International Flavors and Fragrances Inc. |
| Symrise |
| Archer Daniels Midland Company |
| Ajinomoto |
| Cargill |
| Koninklijke DSM NV |
| Others |
Value Network & Pricing Analysis
Captive botanical extraction networks in Brazil and Argentina anchor both supply security and premium pricing power for natural flavor compounds, compressing margins for distributors lacking upstream control while elevating procurement costs for reformulation-heavy manufacturers.
Pricing Analysis
Volume placements concentrate in synthetic flavorings; margin expansion belongs to certified natural extracts. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-verified clean-label suppliers from uncertified regional blenders and commodity synthetic importers. Pricing pressure stems from weather-driven botanical harvest volatility in Argentina and Colombia. Quick-service restaurant chains exhibit lowest price sensitivity due to multi-year contract lock-ins; family-owned bakery processors face highest cost compression.
Supply Chain Analysis
Reverse-logistics flows for spent botanical biomass and solvent recovery systems are emerging in São Paulo's processing corridor, reducing waste disposal costs and closing loop on extraction inputs. Raw material sourcing draws from citrus groves in Brazil's Minas Gerais, vanilla cultivation in Madagascar and Indonesia, and synthetic precursor imports from Asian chemical manufacturers. Single-source vulnerability concentrates in nucleotide-based enhancers and specialty fermentation feedstocks. Distribution runs through São Paulo-based technical buying centers serving multinational food manufacturers across Mercosur markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
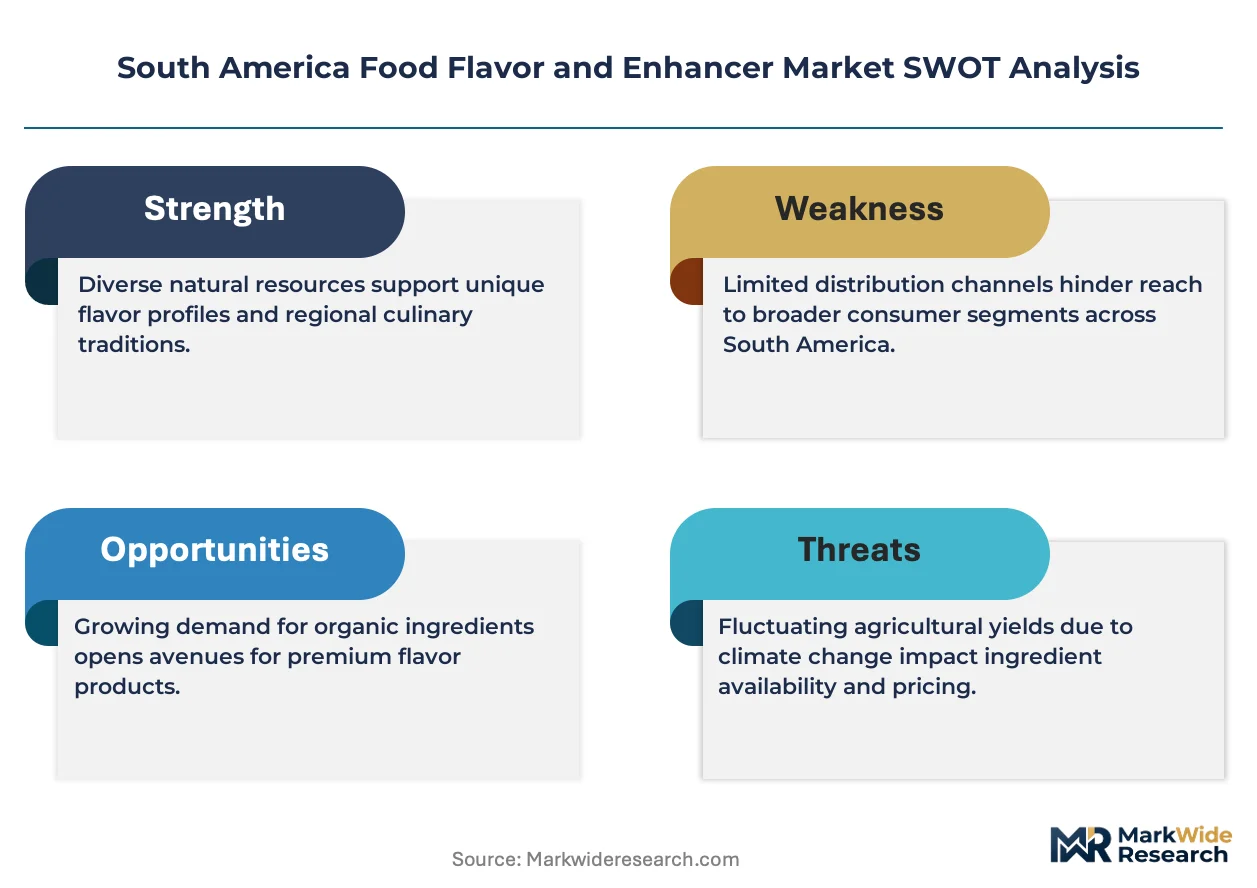
ANVISA's tightening disclosure thresholds for natural-origin claims construct a compliance moat that favors incumbent suppliers with documented traceability systems, elevating capital requirements for market entry.
For Market Incumbents: Extend backward integration into certified botanical sourcing networks in Argentina and Colombia to preempt input price volatility. Lock multi-year supply contracts with São Paulo-based QSR procurement hubs before harmonized Mercosur standards consolidate buyer power. Prioritize precision fermentation capacity builds to reduce agricultural feedstock exposure. For New Entrants and Emerging Players: The premium-to-economy price gap in yeast extract and nucleotide enhancers opens white-space positioning for mid-tier sodium-reduction specialists. Peru's underdeveloped Lima manufacturing base offers first-mover advantage for local blending facilities serving Andean dairy processors. Lead with ANVISA pre-certification to bypass incumbent documentation advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated taste-nutrition platforms seeking South American manufacturing footholds. Five-to-ten-year viability hinges on biotechnology convergence reducing botanical dependency. Monitor ANVISA-Mercosur harmonization implementation timelines as inflection signal for cross-border consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Build | Reduces reliance on Argentine and Colombian weather-dependent botanical harvests for natural flavor molecules. |
| ANVISA Pre-Certification Investment | Accelerates supplier qualification timelines for São Paulo-based multinational procurement hubs. |
| Peru Local Blending Facility Establishment | Captures first-mover positioning in Lima's emerging food manufacturing corridor for Andean market access. |
| Multi-Year QSR Supply Contract Lock | Secures volume commitments with quick-service restaurant chains before buyer consolidation intensifies. |
| Backward Integration into Botanical Sourcing | Controls input cost volatility for citrus and tropical fruit extracts in Brazil's southeastern processing cluster. |
Research Methodology
Document review covered ANVISA regulatory filings, Mercosur harmonization protocols, and customs trade data, complemented by interviews with flavor chemists at Brazilian and Argentine manufacturers, procurement directors at São Paulo-based food processing clusters, and regulatory affairs specialists tracking disclosure threshold evolution. Secondary validation drew from food additive registration databases, botanical harvest reports, and multinational flavor supplier technical specifications. Bottom-up volume modeling and top-down value triangulation anchored projections.
Historical consumption patterns were cross-referenced against expert panel input from sensory science directors and encapsulation engineering leads. Segmentation dimensions modeled include product type, application channel, end-user archetype, and form factor across the projection horizon. CAGRs were derived from weighted average of demand elasticity coefficients and regulatory enforcement phase-in assumptions. Industry-specific inputs incorporated ANVISA compliance cost curves and Mercosur alignment probability assessments.
Inputs from ANVISA enforcement calendars and Mercosur technical working group minutes were available through the study window; gaps in real-time botanical harvest yield data introduce uncertainty bands around natural extract supply assumptions. Forecasts reflect documented regulatory trajectories and procurement consolidation trends. Practitioners should monitor ANVISA audit enforcement intensity and Mercosur harmonization ratification votes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market