
 Anthocyanin Food Colors Market | 2026-2036
Anthocyanin Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Anthocyanin Food Colors Market Outlook
Buyer fragmentation across craft beverage startups and specialty confectioners is repositioning procurement power toward smaller, quality-sensitive accounts. Chr. Hansen leverages its fermentation expertise to supply stable anthocyanin formulations for low-pH drinks. Sensient Technologies Corporation anchors North American distribution through its integrated color extraction network. Döhler competes by bundling anthocyanin colors with flavor systems for turnkey beverage solutions.
Anthocyanin food colors are water-soluble pigments extracted from berry skins, grape pomace, and purple carrot, typically containing glucoside variants of cyanidin, delphinidin, and pelargonidin that shift hue with pH from red to blue. These compounds serve primarily as natural colorants replacing azo dyes in products targeting label-conscious consumers. Powder formats dominate manufacturing logistics for their shelf stability and dosing precision, while liquid concentrates capture growth in ready-to-drink beverage lines where inline blending speeds production. Clean-label positioning across bakery and confectionery applications commands margin premiums over standard natural claims, as dual-certification requirements multiply supplier qualification costs.
EFSA novel food evaluations and FDA color additive petitions shape formulation timelines and regional market access for new anthocyanin sources. REACH compliance for imported botanical raw materials adds traceability burdens across European supply chains. Stakeholders must monitor regulatory divergence between jurisdictions where synthetic dye bans outpace natural colorant approval pathways.
Market Dynamics
Beverage manufacturers are consolidating procurement around anthocyanin suppliers capable of delivering pH-stable formulations for functional drink lines, compressing supplier qualification timelines and elevating technical performance requirements.
Growth Catalysts
- EFSA clean-label frameworks:Synthetic dye bans under EU regulations accelerate reformulation mandates across confectionery and beverage sectors.
- Functional beverage expansion:Health-positioned drink lines in Germany and France prioritize natural colorants with antioxidant marketing claims.
- Fermentation-derived stability:Bioprocess innovations yield anthocyanin variants with extended shelf life in acidic formulations.
Market Restraints
- Botanical raw material volatility:Grape pomace and berry skin supply fluctuates with harvest yields in Eastern European sourcing regions.
- REACH traceability burdens:Import compliance for purple carrot and elderberry extracts adds documentation costs across European supply chains.
- Synthetic dye substitution economics:Tartrazine and Allura Red AC maintain cost advantages in price-sensitive mass-market applications.
Strategic Opportunities
- India natural colorant uptake:FSSAI enforcement of stricter additive standards creates first-mover positioning for certified anthocyanin suppliers.
- Plant-based meat analogues:Visual differentiation requirements in alternative protein categories open new colorant application vectors.
- Dual-certification bundling:Organic plus non-GMO verification commands margin premiums in premium confectionery channels.
Industry Challenges
- Color stability expertise gaps:Formulation chemists capable of managing pH-dependent hue shifts in low-acid applications remain scarce.
- Extraction capex intensity:Supercritical CO2 and membrane filtration systems require substantial capital deployment for food-grade compliance.
- Novel source approval timelines:FDA color additive petitions for emerging botanical extracts extend market entry cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthocyanin Food Colors Market |
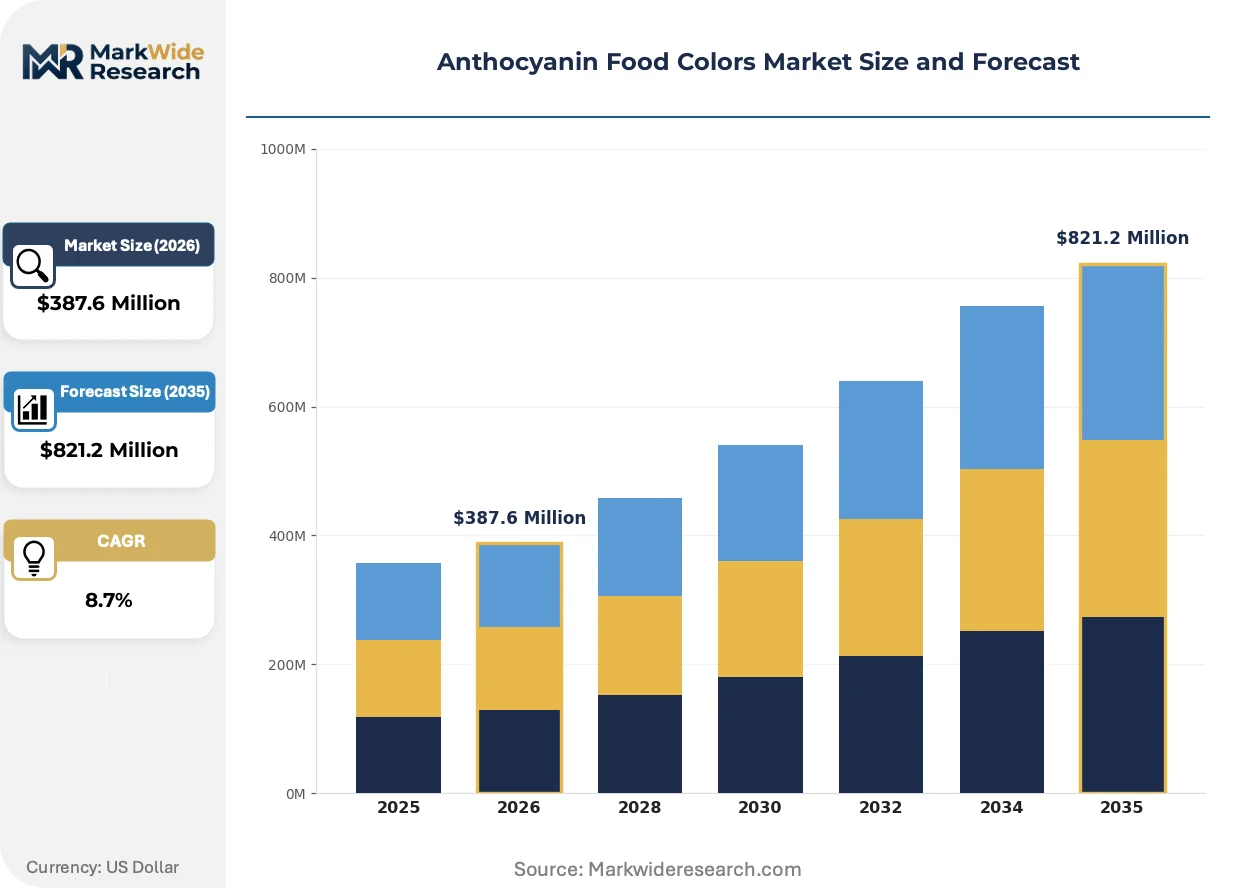
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Spray Application: Beverages, Dairy Products, Bakery, Confectionery Form: Natural, Synthetic, Organic, Clean Label End User: Food Industry, Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Sector |
| Companies Covered | Naturex, BASF, Sensient Technologies Corporation, Döhler, FMC Corporation, Chr. Hansen, Givaudan, Kalsec Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthocyanin Food Colors Market Strategic Shifts
Microencapsulation and fermentation-derived stabilization are compressing technical barriers that historically limited anthocyanin deployment across pH-variable applications.
Encapsulation technology using modified starch and maltodextrin carriers is absorbing instability risks that previously confined anthocyanins to narrow pH windows. Premium confectioners in Belgium and Switzerland are adopting these systems for shelf-stable ruby hues in filled chocolates. The technology is absorbing market share from carmine and beetroot alternatives in applications demanding heat stability.
REACH authorization requirements for imported anthocyanin feedstocks are tightening substance registration obligations across EU member states. Manufacturers must now document full supply chain provenance for elderberry and chokeberry extracts. German and Dutch importers are responding by backward-integrating into controlled cultivation partnerships in Poland and Ukraine.
Ingredient bundling is displacing standalone colorant purchasing as beverage formulators seek streamlined supplier relationships. Turnkey solutions combining anthocyanin colors with matching flavor profiles capture procurement budgets previously allocated to separate vendors. This pattern concentrates most visibly in North American ready-to-drink kombucha and functional water segments where speed-to-market pressures dominate formulation decisions.
Anthocyanin Food Colors Market Segmentation
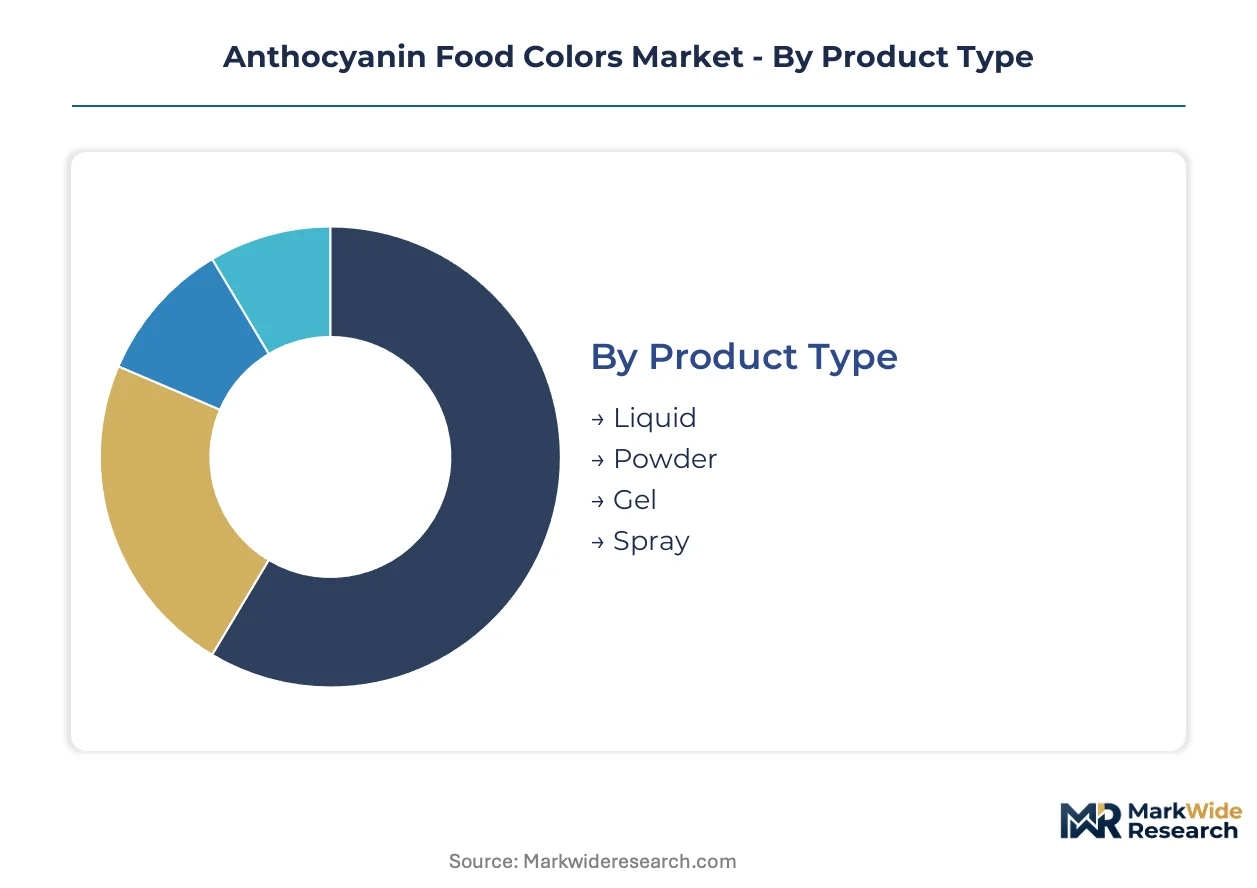
Anthocyanin food colors exhibit divergent technical requirements and margin profiles across product formats and end-use applications. Procurement patterns vary sharply between commodity-scale beverage manufacturers and premium confectionery specialists with distinct stability demands.
Product Type:
Capital deployment intensity separates powder processing infrastructure from liquid formulation systems, with extraction and drying equipment representing the dominant fixed cost burden.
- Liquid:Concentrated aqueous solutions enable inline blending in high-speed bottling operations. Demand concentrates in German functional water and kombucha facilities where pH-stable formulations justify premium sourcing costs.
- Powder:Spray-dried or freeze-dried matrices containing maltodextrin carriers deliver extended shelf stability. Belgian and Swiss premium confectioners deploy these for heat-stable ruby hues in filled chocolate applications.
- Gel:Viscous suspensions suit artisan bakery decorating where precise dosing control matters.
- Spray:Atomized formats target surface coating applications in snack and confectionery sectors.
Most installed capacity flows through Powder. Expansion is steepest in Liquid.
Application:
Volume concentration and margin capture diverge between mass-market beverage scale and premium confectionery value extraction.
- Beverages:Functional drink lines in Germany and France drive procurement of pH-stable anthocyanin systems. EFSA clean-label frameworks accelerate reformulation away from synthetic azo dyes in this segment.
- Confectionery:Premium positioning in Belgium and Switzerland demands dual-certification organic and non-GMO verification. Microencapsulation investments absorb instability risks for shelf-stable ruby coloration.
- Dairy Products:Yogurt and fermented milk applications require acid-stable formulations.
- Bakery:Heat-exposure during baking limits deployment to glazes and fillings.
Volume leadership sits with Beverages. Value capture concentrates in Confectionery.
Form:
Certification tiering and regulatory compliance costs stratify supplier qualification burdens and procurement pricing.
- Clean Label:Dual-verification combining organic certification with non-GMO documentation commands margin premiums in premium channels. REACH traceability requirements for elderberry and chokeberry extracts add documentation intensity.
- Natural:Standard botanical extraction without additional certification serves mid-tier reformulation demand.
- Organic:Cultivation-controlled sourcing from Poland and Ukraine supports German importer backward integration strategies.
- Synthetic:Not applicable to anthocyanin category; included for comparative market mapping only.
Procurement budgets are shifting fastest toward Clean Label. Natural maintains volume dominance.
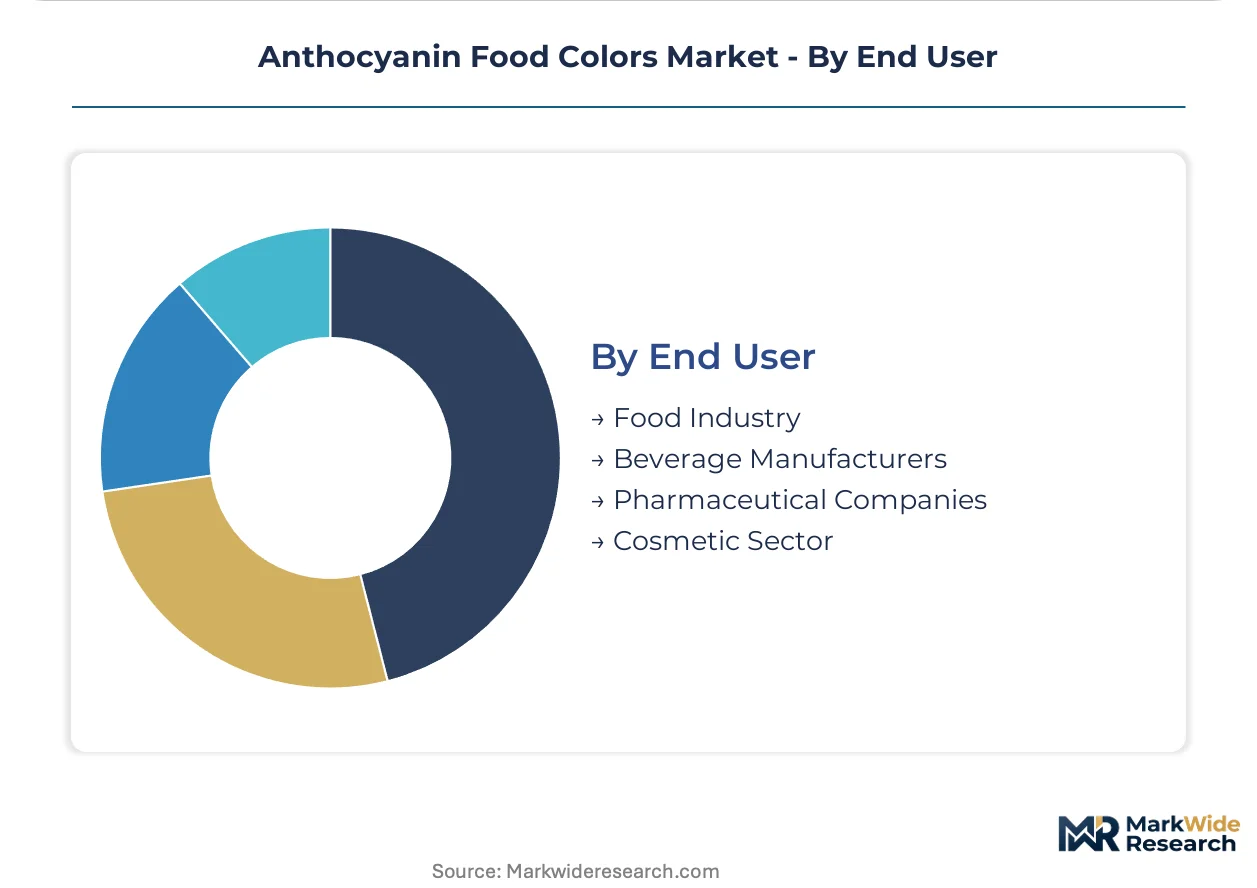
End User:
Technical capability requirements and formulation support needs fragment supplier relationships across customer scale.
- Beverage Manufacturers:Consolidating procurement around suppliers delivering pH-stable formulations compresses qualification timelines. Turnkey solutions bundling color with flavor profiles capture budgets in North American ready-to-drink segments.
- Food Industry:Bakery and general food processing applications prioritize cost-efficient powder logistics.
- Pharmaceutical Companies:GMP compliance and batch documentation requirements limit qualified supplier pools.
- Cosmetic Sector:Skin-contact applications drive dermatological safety testing investments.
Supplier development investment concentrates on Beverage Manufacturers. Pharmaceutical qualification cycles extend longest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's premium confectionery sector commands higher anthocyanin adoption rates than the United States, where beverage reformulation drives larger absolute volumes. France and Switzerland concentrate value capture through dual-certification requirements. India presents emerging regulatory catalysts under stricter FSSAI enforcement.
Germany
Functional beverage manufacturers in Bavaria and Baden-Württemberg procure pH-stable anthocyanin systems for kombucha and health-positioned drink lines. EFSA clean-label frameworks accelerate synthetic dye bans across confectionery applications. Cologne and Hamburg host importer backward-integration partnerships with Polish and Ukrainian cultivation operations.
United States
Ready-to-drink beverage formulators in California and the Pacific Northwest consolidate procurement around turnkey color-flavor bundles. FDA color additive petition timelines constrain novel botanical extract approvals. Chicago and New Jersey processing clusters absorb membrane filtration investments for food-grade extraction compliance.
France
Paris and Lyon-based premium confectioners demand organic-plus-non-GMO verification for shelf-stable ruby chocolate applications. ANSM oversight of food contact materials adds dermatological safety documentation for cosmetic-crossover uses. Auvergne-Rhône-Alpes clusters specialize in microencapsulation technology for heat-stable formulations.
Switzerland
Swissmedic alignment with EU novel food evaluations streamlines cross-border ingredient approvals for Basel and Zurich headquarters operations. Belgian-Swiss premium chocolate corridors absorb the highest clean-label certification premiums. Geneva trading houses coordinate elderberry and chokeberry sourcing from Eastern European supply chains.
India
FSSAI enforcement of stricter additive standards in Maharashtra and Gujarat creates first-mover positioning for certified anthocyanin suppliers. Mumbai and Ahmedabad beverage startups pilot natural colorant reformulation away from synthetic azo dyes. Karnataka and Tamil Nadu extraction facilities face capital deployment hurdles for supercritical CO2 compliance.
Anthocyanin Food Colors Market Competitive Environment
European producers anchor the premium stability tier; North American specialists hold scale advantages in beverage turnkey solutions. The vendor base arranges around fermentation-derived formulation capabilities versus integrated extraction networks. Three archetypes dominate: bioprocess innovators, botanical extraction consolidators, and flavor-color bundlers. Capacity expansion in Eastern European raw material zones and strategic partnerships for REACH traceability documentation represent the dominant competitive moves.
Within the fermentation-derived stability tier, Chr. Hansen exemplifies bioprocess expertise applied to low-pH beverage applications. Sensient Technologies Corporation anchors North American distribution through integrated color extraction infrastructure. Döhler occupies a bundling position combining anthocyanin colorants with matching flavor systems for streamlined procurement.
| Leading Market Players |
|---|
| Naturex |
| BASF |
| Sensient Technologies Corporation |
| Döhler |
| FMC Corporation |
| Chr. Hansen |
| Givaudan |
| Kalsec Inc. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Grape pomace futures and elderberry harvest indices cascade through Eastern European supply chains into three distinct pricing tiers for anthocyanin colorants. Powder formats command premiums in Belgian chocolate applications where heat-stable formulations justify certification costs, while liquid concentrates face margin compression in high-volume beverage contracts.
Pricing Analysis
Capacity additions in Poland and Ukraine are reshaping price floors for standard-grade anthocyanin powders. Three-tier pricing structure across premium, standard, and economy levels stratifies by dual-certification status and REACH documentation completeness. Cost compression in economy-tier liquid concentrates is intensifying because synthetic dye substitution economics still favor azo alternatives in mass-market applications. Beverage manufacturers in North America exhibit highest price sensitivity, while Swiss and Belgian confectioners absorb premium tiers with minimal volume elasticity.
Supply Chain Analysis
REACH substance registration obligations are reshaping sourcing decisions for German and Dutch importers seeking controlled cultivation partnerships. Supply concentrates in Poland, Ukraine, and Bulgaria for elderberry and chokeberry feedstocks. Extraction infrastructure draws from grape pomace, purple carrot, and berry skin inputs. Single-source vulnerability in Eastern European harvest yields threatens supply continuity during poor growing seasons. Distribution runs through integrated color houses and flavor-color bundlers serving North American ready-to-drink segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anthocyanin food colors market functions as a regulatory compounder where EFSA synthetic dye bans and FDA color additive petition timelines continuously reshape demand curves and supplier qualification burdens.
For Market Incumbents: To counter fermentation-derived stability advances from bioprocess specialists, Chr. Hansen and comparable incumbents must deepen captive supply of pH-stable formulations through backward integration into Polish cultivation partnerships. Certification investment in dual organic-plus-non-GMO verification secures margin premiums in Belgian and Swiss chocolate corridors. For New Entrants and Emerging Players: Enter via India's FSSAI enforcement window where stricter additive standards create first-mover positioning for certified suppliers in Maharashtra and Gujarat beverage startups. Plant-based meat analogues present the most penetrable application vector, with turnkey color-flavor bundling as the preferred go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier extraction specialists possessing membrane filtration capabilities and pending FDA color additive petitions. Long-term viability hinges on regulatory approval velocity rather than scale economics alone. The signal to watch is FDA petition timeline compression for novel botanical sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | German importers secure REACH-compliant elderberry supply through Polish partnerships. |
| Microencapsulation Technology Investment | Belgian confectioners achieve heat-stable ruby hues replacing carmine alternatives. |
| Dual-Certification Program | Organic-plus-non-GMO verification captures premium pricing in Swiss chocolate channels. |
| Fermentation-Derived Stabilization | Bioprocess innovations extend shelf life in acidic functional beverage formulations. |
| Turnkey Color-Flavor Bundling | Streamlined procurement accelerates speed-to-market for North American kombucha brands. |
Study Parameters
Bottom-up beverage and confectionery modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement managers at functional drink manufacturers, regulatory affairs specialists, and premium confectionery R&D directors combined with secondary validation from EFSA novel food evaluations, FDA color additive petitions, REACH registration databases, and customs trade flows. Triangulation across these sources yields volume and value estimates.
Historical trendline analysis of anthocyanin adoption patterns across powder, liquid, and gel formats informs projection mechanics. Segmentation dimensions span product type, application category, certification tier, and end-user scale. CAGRs derive from fitted growth curves calibrated against EFSA regulatory milestone timelines and beverage reformulation announcement frequencies. Industry-specific forecast inputs include pH stability performance benchmarks and supercritical CO2 extraction capacity deployment.
The model holds under sustained EFSA clean-label enforcement and FDA petition processing rates; deviation in harvest yield volatility or synthetic dye ban acceleration would shift trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Oil Soluble Flavors Market