
 Global Chicory Market | 2026-2036
Global Chicory Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chicory Market Analysis
Chicory root fiber is shifting from niche ingredient status toward mainstream sugar reduction formulations across European and North American food systems. BENEO GmbH leverages its Belgian processing heritage and inulin extraction expertise to anchor supply relationships with multinational beverage brands. Leroux SAS sustains century-old roasting traditions while competing in instant chicory blends across French retail channels. Cosucra Groupe Warcoing specializes in pea-chicory ingredient synergies, differentiating its portfolio toward plant-protein hybrid applications.
Chicory comprises a perennial herbaceous plant of the Asteraceae family whose taproot contains inulin polysaccharides reaching 15-20% fresh weight, extracted through hot-water diffusion and refined via spray-drying or enzymatic hydrolysis for food-grade fiber and sweetener applications. Chicory root dominates raw material procurement volumes due to established agronomic programs across northern France and Belgium, while chicory extract occupies concentrated margin pools through pharmaceutical-grade inulin certifications. The dietary supplements channel leads application growth as health and wellness brands formulate synbiotic products combining chicory-derived prebiotics with probiotic strains.
EFSA novel food evaluations and EU Green Deal farm-to-fork traceability mandates shape ingredient sourcing protocols for chicory processors serving European food manufacturers. FDA GRAS notifications and USDA organic certification requirements govern market access for chicory fiber entrants targeting US beverage and nutraceutical accounts. Stakeholders must monitor evolving prebiotic health claim substantiation standards across multiple jurisdictions to anticipate reformulation cycles and label positioning requirements.
Market Dynamics
Clean-label prebiotic demand is compressing formulation cycles across beverage and nutraceutical supply chains, forcing ingredient processors to accelerate inulin extraction throughput while maintaining EU Green Deal traceability compliance from farm to finished product.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:EFSA traceability requirements are locking in long-term supply contracts between Belgian processors and certified chicory growers across Flanders and Picardy.
- Synbiotic formulation expansion:Health and wellness brands are combining chicory-derived prebiotics with probiotic strains in dietary supplements, opening new margin pools beyond conventional fiber applications.
- Hot-water diffusion optimization:Enzymatic hydrolysis refinements are lifting inulin extraction yields from chicory taproots, reducing unit costs for food-grade fiber production.
Market Restraints
- Raw material geographic concentration:Chicory cultivation clusters in northern France and Belgium expose processors to regional weather volatility and single-source agronomic risk.
- FDA GRAS notification timelines:US market entrants face extended premarket safety review periods for novel inulin applications, delaying revenue recognition from American beverage accounts.
- Substitute fiber proliferation:Acacia gum and resistant starch suppliers are capturing reformulation briefs in cost-sensitive bakery and confectionery segments.
Strategic Opportunities
- USDA organic certification pathway:Premium-positioned chicory fiber holds untapped penetration potential in American organic food channels where clean-label credentials command price premiums.
- Plant-protein hybrid convergence:Pea-chicory ingredient synergies are enabling novel texture and nutrition solutions in meat-alternative formulations.
- Pharmaceutical-grade inulin certification:EU pharmacopeia compliance opens high-margin supply relationships with clinical nutrition and drug delivery formulators.
Industry Challenges
- Prebiotic health claim substantiation:EFSA novel food evaluations require extensive clinical dossiers, stretching R&D budgets and extending time-to-market for branded ingredient positioning.
- Legacy roasting equipment retrofitting:Instant chicory blend manufacturers face capital-intensive upgrades to meet energy efficiency standards under EU industrial emissions directives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chicory Market |
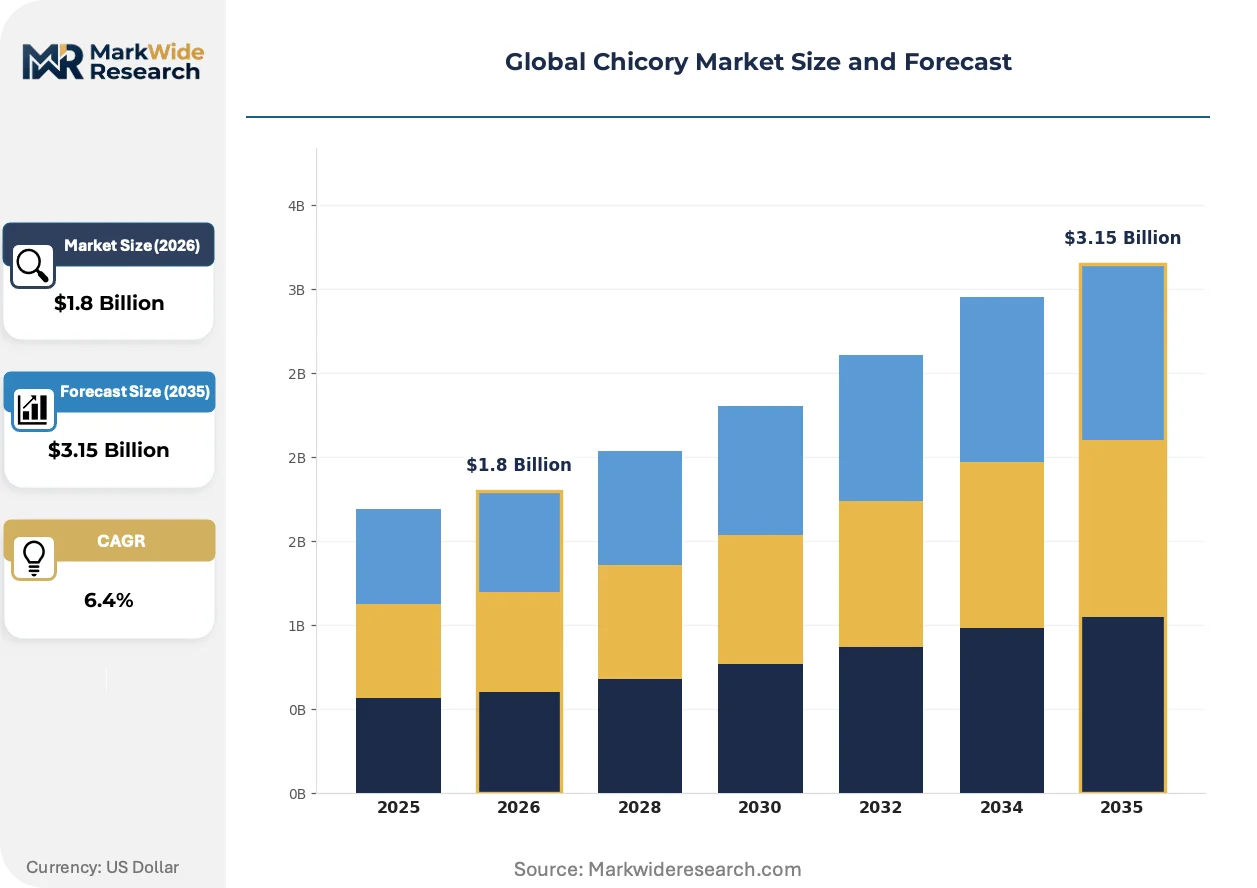
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicory Root, Chicory Powder, Chicory Extract, Roasted Chicory Application: Food & Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed End User: Food Manufacturers, Beverage Producers, Health & Wellness Brands, Nutraceutical Companies Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Leroux SAS, Farmvilla Food Industries Pvt Ltd, BENEO GmbH, Pioneer Chicory, Delecto Foods Pvt Ltd, Cargill, Incorporated, Sensus BV, STOKROS Company Ltd, Cosucra Groupe Warcoing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chicory Market Emerging Trajectories
Extraction technology maturation and regulatory data requirements are compressing the gap between agricultural raw material and finished prebiotic ingredient, reshaping how processors capture value across the chicory supply chain.
Enzymatic inulin hydrolysis systems are modularizing production footprints for mid-scale processors, enabling regional supply hub deployment without centralized Belgian infrastructure. North American contract manufacturers are adopting these systems to bypass trans-Atlantic shipping costs and customs complexity. The technology is modularizing competitive entry barriers, fragmenting what was previously a concentrated European supplier base.
EFSA novel food evaluation protocols under the EU Green Deal are tightening botanical ingredient documentation requirements, mandating full genealogical traceability from seed stock to extraction batch. Chicory processors serving multinational food manufacturers must now integrate blockchain-enabled provenance systems. French and Belgian suppliers are absorbing compliance costs to defend existing supply relationships against emerging competitors.
Direct procurement relationships between functional beverage brands and certified chicory growers are displacing traditional ingredient distributor intermediaries in North American and European markets. Large-format beverage manufacturers are establishing captive supply agreements with specific Flemish and Picardy farming cooperatives. This pattern is most visible in Germany and the Netherlands, where clean-label positioning drives preference for named-origin prebiotic sourcing.
Global Chicory Market Segmentation
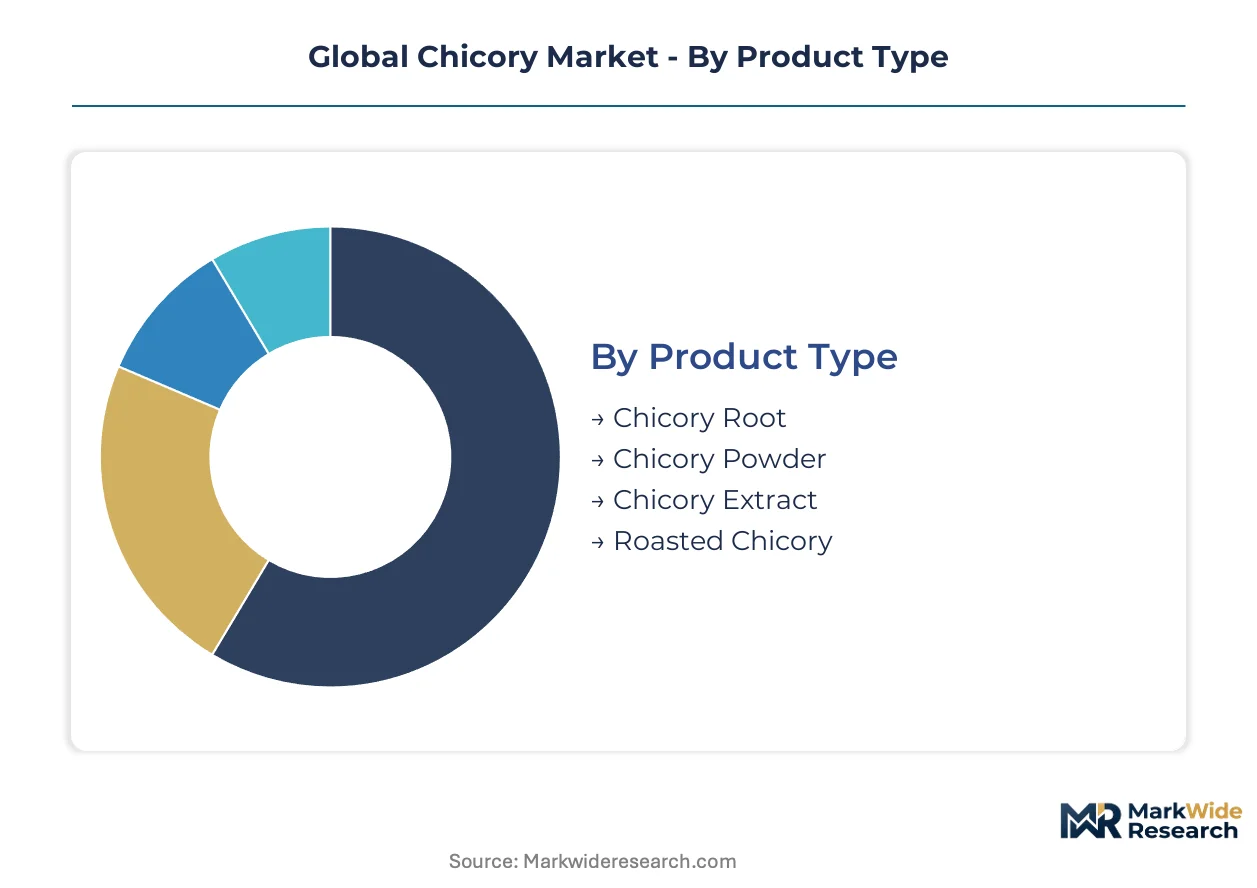
Chicory market segmentation reveals how extraction technology and formulation requirements fragment value capture across the supply chain. Product type distinctions separate commodity agricultural throughput from certified pharmaceutical-grade margins, while application channels determine regulatory compliance intensity and customer procurement protocols.
Product Type:
Extraction method and refinement level define commercial positioning across the four product categories, with hot-water diffusion yields and enzymatic hydrolysis sophistication determining unit economics.
- Chicory Root:Fresh taproots contain 15-20% inulin by fresh weight and serve as the foundational agricultural commodity for downstream processing. Belgian and French farming cooperatives in Flanders and Picardy dominate cultivation infrastructure, though single-source geographic concentration exposes supply chains to regional weather volatility.
- Chicory Extract:Concentrated inulin solutions undergo spray-drying or enzymatic refinement for pharmaceutical-grade certifications. Demand concentrates in clinical nutrition and drug delivery applications where EU pharmacopeia compliance commands substantial price premiums over food-grade alternatives.
- Chicory Powder:Intermediate processing stage bridges raw agricultural throughput and finished ingredient specifications.
- Roasted Chicory:Thermal processing creates soluble beverage bases through century-old Belgian and French roasting traditions.
Mature deployment sits with Chicory Root. Newer deployment is concentrated in Chicory Extract.
Application:
End-use regulatory burden and formulation complexity stratify margin structures across the four application channels.
- Dietary Supplements:Synbiotic formulations combining chicory-derived prebiotics with probiotic strains are expanding most quickly as health and wellness brands pursue clean-label positioning. EFSA novel food evaluations require extensive clinical dossiers, stretching R&D budgets for branded ingredient positioning.
- Food & Beverage:Sugar reduction and fiber fortification drive reformulation cycles across European and North American manufacturing. Functional beverage producers in Germany and the Netherlands are establishing direct procurement relationships with named-origin Flemish and Picardy farming cooperatives.
- Pharmaceuticals:Clinical nutrition and drug delivery applications demand pharmacopeia-grade certifications.
- Animal Feed:Prebiotic inclusion in livestock nutrition represents emerging volume demand.
Steepest expansion trajectory belongs to Dietary Supplements. Established volume concentration remains in Food & Beverage.
End User:
Procurement scale and technical specification requirements differentiate customer relationships across the four end-user categories.
- Food Manufacturers:Large-scale bakery and confectionery producers drive bulk fiber procurement with cost-sensitive reformulation briefs. Acacia gum and resistant starch suppliers are capturing share in price-driven segments.
- Nutraceutical Companies:Specialized formulators require documented prebiotic health claim substantiation for branded positioning. EFSA evaluation protocols mandate full genealogical traceability from seed stock to extraction batch.
- Beverage Producers:Functional drink brands prioritize clean-label credentials and named-origin sourcing.
- Health & Wellness Brands:Direct-to-consumer positioning demands organic certification and transparent supply chains.
Volume concentration sits with Food Manufacturers. Margin expansion concentrates in Nutraceutical Companies.
Distribution Channel:
Customer access method and order fulfillment infrastructure shape working capital requirements and geographic reach.
- Direct Sales:Long-term supply contracts between Belgian processors and multinational beverage brands are displacing traditional distributor intermediaries. Blockchain-enabled provenance systems defend existing relationships against emerging competitors.
- Online Retail:E-commerce penetration in specialty prebiotic ingredients is climbing fastest as mid-scale health and wellness brands bypass conventional procurement channels.
- Supermarkets:Mass retail placement for instant chicory blends and consumer packaged goods.
- Health Stores:Specialty retail channels serve premium-positioned organic and clean-label products.
Relationship depth concentrates in Direct Sales. Channel expansion is accelerating through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's Flanders region anchors chicory processing infrastructure through concentrated inulin extraction facilities and EU Green Deal compliance investments. French Picardy farming cooperatives supply raw taproot volumes to processors across the border. Dutch beverage manufacturers drive clean-label prebiotic procurement through direct sourcing relationships.
Belgium
Functional beverage brands in Flanders purchase inulin fiber under long-term supply contracts tied to EU Green Deal traceability mandates. EFSA novel food evaluation protocols require blockchain-enabled provenance documentation from seed stock through extraction batch. Processing clusters around Tienen and Leuven host enzymatic hydrolysis refinements that lift yields for multinational accounts.
France
Instant chicory blend demand concentrates in French retail channels where century-old roasting traditions sustain consumer loyalty. ANSM pharmaceutical-grade certifications enable clinical nutrition applications from northern extraction facilities. Picardy farming cooperatives in the Hauts-de-France region supply named-origin taproots directly to German and Dutch beverage manufacturers.
Netherlands
Clean-label positioning drives Dutch functional drink producers to establish captive supply agreements with Belgian processors. EU farm-to-fork traceability requirements mandate full genealogical documentation for prebiotic ingredient imports. Rotterdam logistics hubs facilitate trans-Atlantic distribution to North American nutraceutical accounts seeking EU-certified fiber.
Germany
Synbiotic formulation expansion propels German health and wellness brands to combine chicory-derived prebiotics with probiotic strains. KBA industrial emissions directives pressure legacy roasting equipment retrofits at instant blend manufacturers. Bavarian beverage producers prioritize named-origin sourcing from Flemish farming cooperatives for transparent supply chain marketing.
United States
FDA GRAS notification timelines delay market entry for novel inulin applications targeting American beverage accounts. USDA organic certification requirements govern premium-positioned fiber penetration in clean-label food channels. Midwest contract manufacturers adopt modular enzymatic hydrolysis systems to bypass trans-Atlantic shipping costs and customs complexity.
Global Chicory Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with extraction technology sophistication determining tier placement. Belgian and French heritage processors defend established supply relationships through EU Green Deal compliance investments. Three archetypes dominate: vertically integrated agricultural processors, modular technology licensors, and regional roasting specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves as mid-scale entrants deploy enzymatic systems.
Among heritage-anchored processors, BENEO GmbH and Leroux SAS exemplify divergent strategic positions within the European supplier base. BENEO leverages Belgian processing infrastructure to anchor multinational beverage supply relationships. Leroux sustains century-old French roasting traditions while competing across retail instant blend channels. Cosucra Groupe Warcoing occupies a hybrid position specializing in pea-chicory ingredient synergies for plant-protein applications.
| Leading Market Players |
|---|
| Leroux SAS |
| Farmvilla Food Industries Pvt Ltd |
| BENEO GmbH |
| Pioneer Chicory |
| Delecto Foods Pvt Ltd |
| Cargill, Incorporated |
| Sensus BV |
| STOKROS Company Ltd |
| Cosucra Groupe Warcoing |
| Others |
Supply Flow & Price Mechanics
EU Green Deal farm-to-fork traceability mandates gate qualified supply access and premium-tier pricing for chicory fiber processors serving multinational food manufacturers. Belgian and French extraction facilities absorb blockchain-enabled provenance system costs to defend long-term supply contracts against emerging competitors, compressing margins at standard-grade tiers while reinforcing pharmaceutical-grade premium positioning.
Pricing Analysis
Short lead-time premiums distinguish urgent reformulation briefs from contracted annual offtake agreements across European and North American procurement channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications reflects extraction refinement intensity and documentation burden. Pricing pressure stems from acacia gum and resistant starch substitution in cost-sensitive bakery applications. Food manufacturers exhibit highest price sensitivity due to bulk volume procurement protocols, while nutraceutical companies accept premium positioning for health claim substantiation.
Supply Chain Analysis
Chicory taproot supply rests on farming cooperatives concentrated across Belgium's Flanders region and France's Picardy belt, with Dutch processors completing the Benelux processing cluster. Hot-water diffusion equipment, enzymatic hydrolysis catalysts, and spray-drying infrastructure constitute critical input dependencies. Single-source geographic concentration exposes supply chains to regional weather volatility and agronomic disruption. Distribution runs through direct procurement relationships displacing traditional ingredient distributor intermediaries in German and Dutch beverage markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chicory fiber supply constraints tighten as EU pharmacopeia certification capacity fails to match synbiotic formulation demand expansion, propping pricing power for qualified processors.
For Market Incumbents: Acquire certified organic farmland in Picardy and Flanders to secure captive raw material supply against weather volatility and competitor encroachment. Invest in modular enzymatic hydrolysis licensing to fragment regional supply hub economics before North American contract manufacturers achieve scale. Defend multinational beverage relationships through blockchain traceability system deployment that emerging competitors cannot replicate without heritage infrastructure. For New Entrants and Emerging Players: Capture USDA organic certification pathways in American clean-label food channels where established European suppliers lack localized processing footprint. Target synbiotic dietary supplement formulations in German health and wellness markets where EFSA health claim dossier requirements deter rapid incumbent response. Deploy regional enzymatic extraction hubs to bypass trans-Atlantic shipping cost disadvantages against Belgian heritage processors. For Investors and Strategic Acquirers: FDA GRAS notification clearance for novel inulin applications is the leading indicator that North American market access barriers are falling for acquisition targets. Five-to-ten year viability favors processors with dual EU pharmacopeia and USDA organic certification capabilities spanning pharmaceutical and food-grade margin pools. Watch for direct procurement relationship announcements between functional beverage brands and named-origin farming cooperatives as consolidation pressure signals.| Strategic Initiative | Industry Significance |
|---|---|
| EU Pharmacopeia Certification Investment | Unlocks clinical nutrition supply relationships with German hospital formulators and French ANSM-regulated drug delivery applications. |
| Backward Integration into Organic Farmland | Secures named-origin taproot supply for Dutch beverage direct procurement contracts against weather volatility exposure. |
| Modular Enzymatic Hydrolysis Licensing | Enables North American regional hub deployment without centralized Belgian infrastructure investment. |
| Blockchain Provenance System Deployment | Defends existing multinational relationships against emerging competitors through EU Green Deal compliance differentiation. |
| USDA Organic Certification Pathway | Opens premium-positioned penetration in American clean-label channels where European heritage lacks localized processing. |
Methodological Framework
Document review covered EFSA novel food evaluation protocols, FDA GRAS notification filings, EU trade customs data, and agricultural cooperative annual reports, complemented by interviews with Belgian extraction facility technical directors, French farming cooperative procurement leads, German nutraceutical brand formulators, and Dutch functional beverage supply chain managers. Secondary validation drew from EU Green Deal implementation guidance, USDA organic certification databases, and pharmacopeia compliance registries. Bottom-up cultivation volume estimates triangulated against top-down end-use demand segmentation.
Segment-level value and volume trajectories across the projection horizon reflect product type distinctions between root commodity, extract refinement, and roasted processing tiers, crossed with application intensity across dietary supplements, food and beverage, pharmaceutical, and animal feed channels. CAGRs emerged from historical price trend analysis and procurement pattern elasticity assessment. Forecast inputs incorporated synbiotic formulation adoption curves, enzymatic yield improvement trajectories, and regulatory clearance timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA health claim substantiation standard evolution, FDA GRAS review period volatility, and agronomic disruption in the Benelux cultivation belt. A small set of named triggers warrants ongoing watch: FDA clearance acceleration, modular extraction technology cost curves, and direct procurement contract announcements between beverage brands and farming cooperatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Quillaia Extracts Market