
 Poria Cocos Extract Market | 2026-2036
Poria Cocos Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Poria Cocos Extract Market Insights
A capital-intensity divergence between extraction-scale specialists and formulation-focused distributors is rotating competitive advantage toward upstream operators. Xi'an Natural Field Bio-Technique leverages captive raw material sourcing from Qinling mountain cultivation zones. Shaanxi Undersun Biomedtech sustains GMP-certified spray-drying capacity that anchors pharmaceutical-grade powder output. NOW Foods competes through retail channel control across North American health store networks.
Poria cocos extract comprises triterpenoid and polysaccharide fractions derived from the sclerotium of Wolfiporia extensa, a wood-decay fungus traditionally harvested from pine substrates and now cultivated on artificial logs or submerged fermentation systems. The extract functions primarily as an adaptogenic and diuretic agent in nutraceutical and dermatological applications. Powder formulations dominate volume throughput due to blending flexibility in capsule and tablet manufacturing, while liquid extract SKUs command margin premiums in functional beverage applications. Pharmaceutical-grade specifications concentrate demand among healthcare providers seeking USP-verified polysaccharide content.
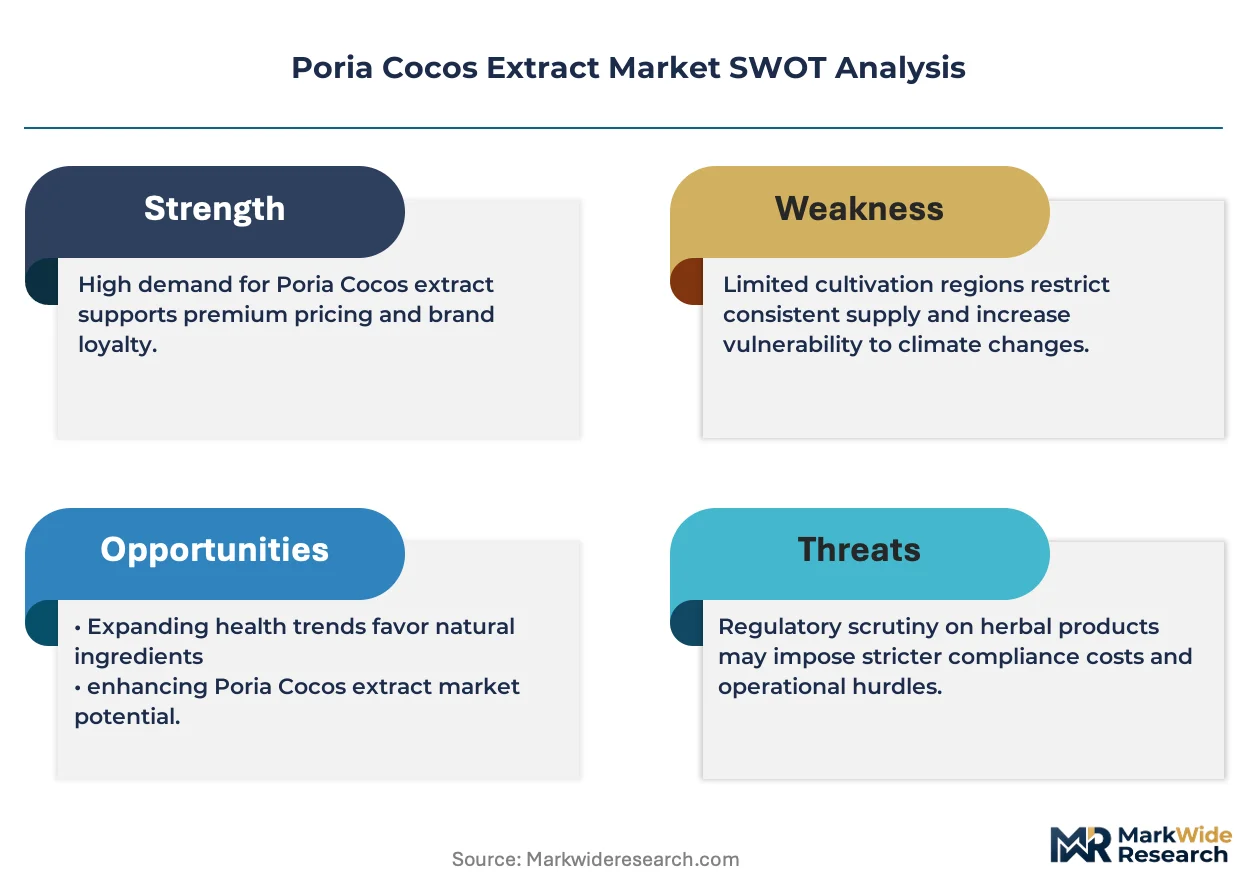
China's NMPA enforces dual carbon goals compliance for fermentation-based extraction facilities, while the US FDA's botanical drug development guidance shapes IND-enabling documentation requirements for novel therapeutic claims. The EU EFSA novel food catalog creates market access friction for non-traditional extract formats entering European nutraceutical channels. Stakeholders must monitor evolving pharmacopeial monograph harmonization between Chinese, USP, and EP standards to anticipate qualification barriers for cross-border ingredient trade.
Market Dynamics
Dual carbon goals compliance in China is forcing fermentation-based extractors to retrofit energy-intensive facilities, while NMPA documentation requirements are compressing the supplier base toward operators with captive analytical capabilities.
Growth Catalysts
- Immune-modulating nutraceutical demand:North American and East Asian formulators are expanding polysaccharide-rich extract procurement for adaptogenic supplement lines targeting stress-response and metabolic health applications.
- Pharmacopeial harmonization momentum:Convergence between Chinese Pharmacopoeia, USP, and EP monograph standards is reducing cross-border qualification friction for standardized triterpenoid and polysaccharide specifications.
- Submerged fermentation scale-up:Artificial log and liquid fermentation systems are displacing wild-harvested pine substrate dependence, stabilizing raw material throughput for cosmetic and pharmaceutical grade outputs.
Market Restraints
- Wild substrate supply volatility:Qinling mountain cultivation zones face climate-induced yield fluctuation, concentrating procurement risk among extractors without captive artificial log capacity.
- EFSA novel food catalog friction:Non-traditional liquid extract formats encounter extended safety assessment timelines for European nutraceutical channel entry, delaying margin-premium SKU launches.
- Synthetic diuretic substitution:Pharmaceutical formulators in regulated markets increasingly favor small-molecule alternatives for edema management, compressing therapeutic-grade Poria cocos demand in clinical settings.
Strategic Opportunities
- Functional beverage channel expansion:Liquid extract formats with verified polysaccharide content are penetrating ready-to-drink adaptogenic portfolios in US and Japanese convenience retail networks.
- Dermatological actives positioning:Triterpenoid fractions are gaining traction in Korean and Chinese cosmeceutical formulations targeting barrier repair and anti-inflammatory topical applications.
- IND-enabling documentation services:Botanical drug development guidance from the US FDA is creating service revenue streams for extractors with validated analytical methods and GMP-certified powder output capabilities.
Industry Challenges
- Standardized testing protocol implementation:Tightened NMPA and FDA botanical ingredient documentation requirements demand capital investment in HPLC and mass spectrometry infrastructure that mid-scale operators struggle to finance.
- Cross-functional technical talent scarcity:Fermentation engineering expertise combined with pharmacognosy knowledge remains concentrated among Shaanxi and Zhejiang province clusters, limiting facility expansion into secondary production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poria Cocos Extract Market |
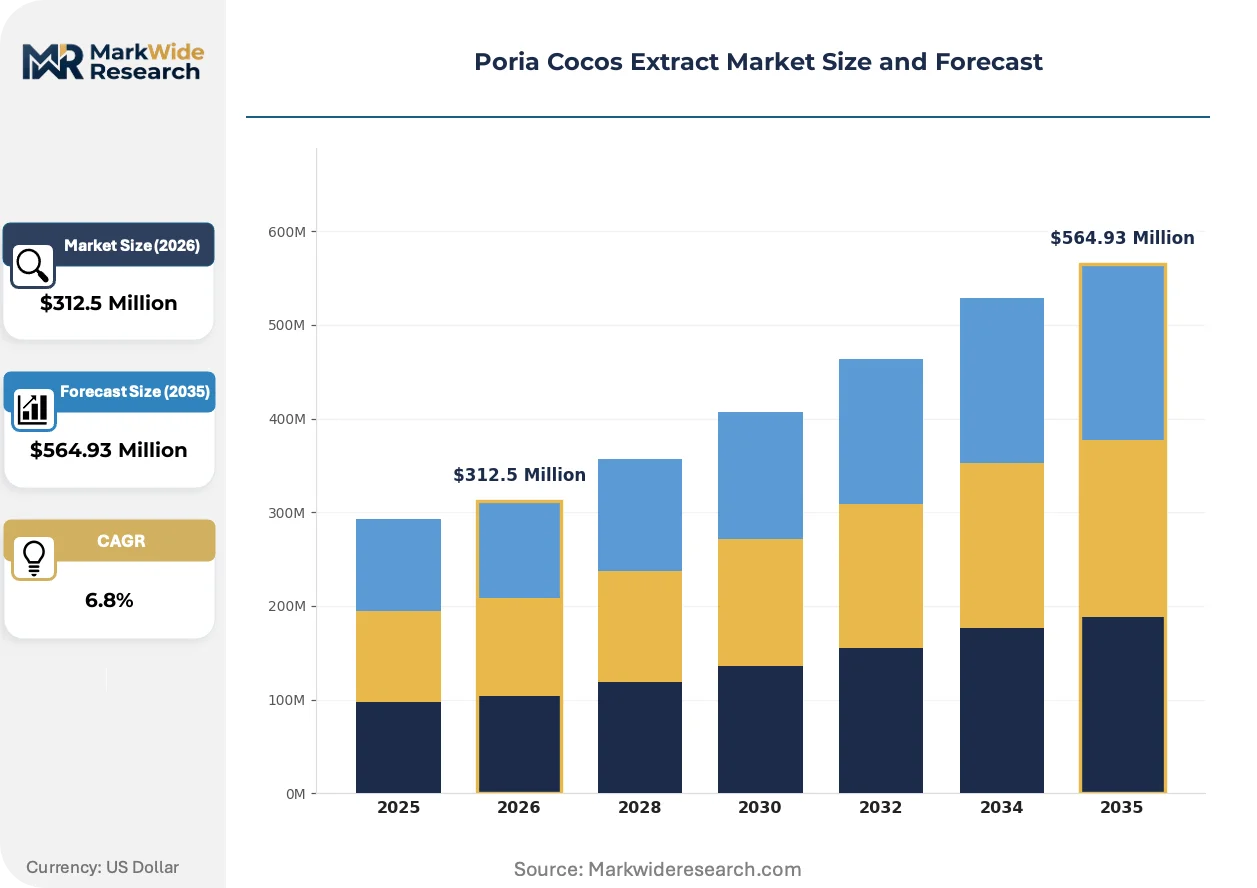
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Liquid Extract, Tincture Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Food & Beverages End User: Retail Consumers, Healthcare Providers, Nutraceutical Companies, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Health Stores, Wholesalers |
| Companies Covered | Xi'an Natural Field Bio-Technique Co., Ltd., Shaanxi Undersun Biomedtech Co., Ltd., Phytoney Natural Products Co., Ltd., Inner Mongolia Runxi Biotechnology Development Co., Ltd., Guangdong Nenghua Biotech Co., Ltd., Hunan Ouming Pharmaceutical Co. Ltd., Jiangyin Yacheng Biotech Co. Ltd., Zibo Orient Poria Co., Ltd., NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poria Cocos Extract Market Trends and Innovations
Extraction technology convergence with quality verification automation is compressing batch-to-batch variability, while regulatory documentation requirements are reshaping competitive advantage toward integrated analytical capabilities.
Submerged liquid fermentation systems optimized for Wolfiporia extensa mycelial biomass production are displacing traditional sclerotium drying and solvent extraction workflows. Pharmaceutical-grade extractors in China's Shaanxi province are adopting these bioreactor configurations to reduce extraction cycle times from weeks to days. The structural consequence is a compression of capital recovery timelines for GMP-certified facilities, forcing wild-harvest dependent operators toward equipment upgrades or contract manufacturing relationships.
REACH registration requirements for novel botanical substances entering European cosmetic and nutraceutical channels are tightening substance characterization thresholds. ECHA documentation demands for full constituent profiling are extending market access timelines by twelve to eighteen months for non-traditional extract formats. Small-scale liquid extract specialists are responding by partnering with EU-based regulatory consultancies to pre-validate dossier submissions before commercial launch attempts.
Direct procurement relationships between North American nutraceutical brands and Chinese extraction facilities are shortening traditional distributor-mediated supply chains. Health store network operators and e-commerce pure-plays are establishing quality agreements with GMP-certified spray-drying specialists in Zhejiang province, bypassing regional import brokers. This channel disintermediation is most visible in premium capsule and tablet segments where USP-verified polysaccharide content commands price premiums over standard-grade powder alternatives.
Poria Cocos Extract Market Segmentation
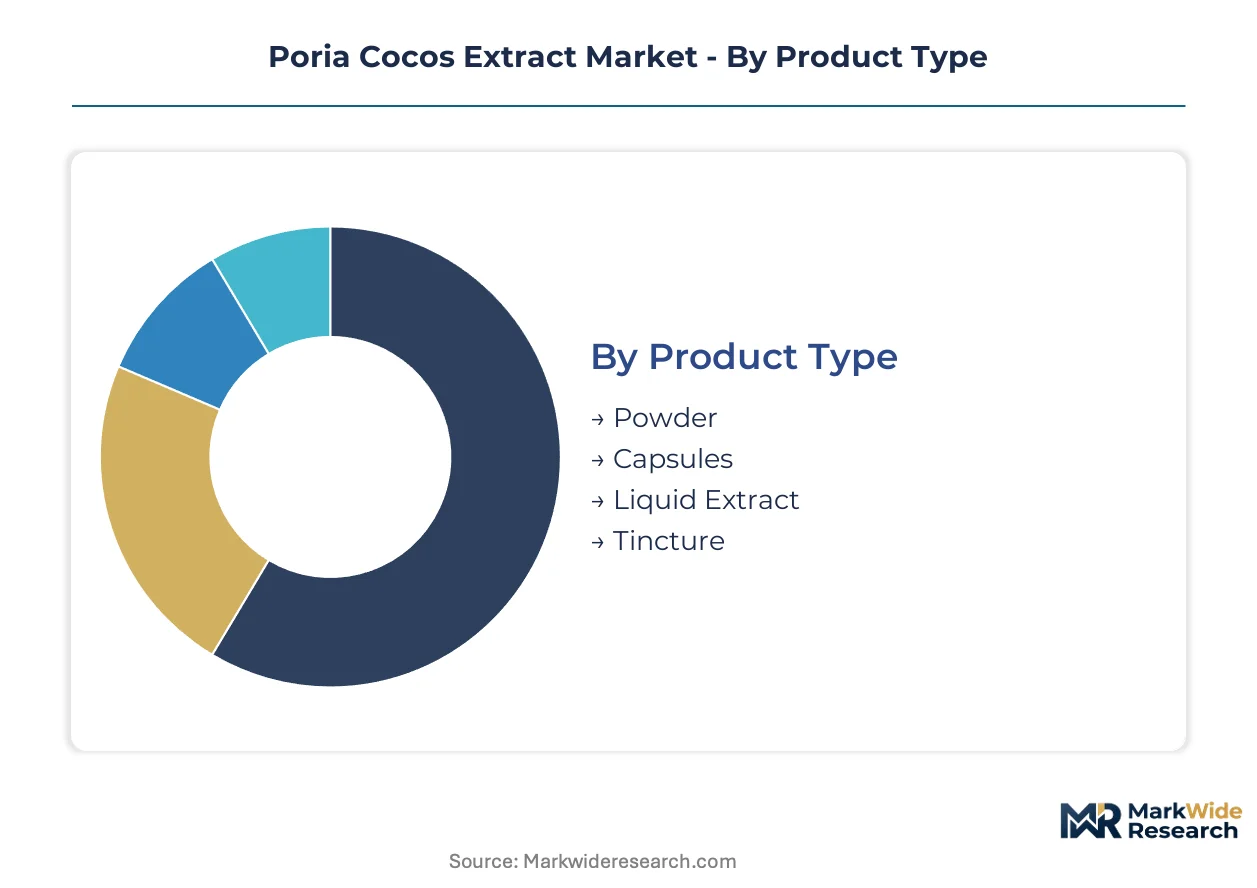
Poria cocos extract flows through distinct channel pathways shaped by formulation requirements, regulatory complexity, and end-user sophistication. Segment boundaries reflect where extraction-grade powder converts into finished goods versus where standardized actives reach formulators directly.
Product Type:
Powder formulations move through bulk ingredient channels to capsule manufacturers, while liquid SKUs concentrate in functional beverage and tincture bottling networks.
- Powder:Spray-dried polysaccharide and triterpenoid concentrates serve as the foundational input for tablet compression and capsule filling operations. Shaanxi province GMP-certified facilities supply North American nutraceutical companies seeking USP-verified specifications for immune-modulating supplement lines.
- Liquid Extract:Hydroalcoholic or glycerite solutions command margin premiums in ready-to-drink adaptogenic beverages and functional shot formats. Japanese and US convenience retail networks are expanding procurement of verified polysaccharide content liquids for stress-response positioning.
- Capsules:Pre-filled gelatin or vegetable cellulose units target health store consumers seeking standardized dosing convenience without formulation complexity.
- Tincture:Alcohol-based extracts concentrate in specialty herbalist channels and direct-to-consumer wellness brands emphasizing traditional preparation methods.
Powder dominates installed base. Liquid extract is where expansion concentrates.
Application:
Cost tiers separate pharmaceutical-grade documentation requirements from cosmetic and food-grade flexibility, with dietary supplements occupying the middle ground on both specification and margin.
- Dietary Supplements:Capsule, tablet, and softgel formats incorporating polysaccharide-rich extracts for adaptogenic and metabolic health claims. North American formulators are expanding procurement from Zhejiang province spray-drying specialists with validated analytical methods.
- Pharmaceuticals:IND-enabling documentation and USP-verified monograph compliance for botanical drug development targeting diuretic and immunomodulatory indications. FDA guidance on botanical drug submissions shapes extractor investment in GMP-certified infrastructure.
- Cosmetics:Triterpenoid fractions for Korean and Chinese cosmeceutical formulations targeting barrier repair and anti-inflammatory topical positioning.
- Food & Beverages:Functional ingredient incorporation into adaptogenic beverages, fortified foods, and traditional medicine-inspired product lines with less stringent active constituent verification.
Pharmaceuticals anchor premium pricing. Dietary supplements are climbing the fastest.
End User:
Volume scale differentiates procurement patterns, with institutional buyers commanding batch consistency guarantees unavailable through retail channels.
- Nutraceutical Companies:Direct quality agreements with Chinese extraction facilities are shortening supply chains for premium capsule and tablet segments. These formulators specify USP-verified polysaccharide content and require GMP documentation for retail channel entry.
- Healthcare Providers:Hospital systems and integrative medicine clinics sourcing pharmaceutical-grade extracts for therapeutic protocols demand comprehensive constituent profiling and stability data.
- Food Manufacturers:Ingredient procurement for functional beverage and fortified food applications prioritizes cost efficiency over maximum standardization.
- Retail Consumers:End purchasers of finished supplements, tinctures, and traditional medicine products through health stores and online channels with limited technical specification visibility.
Nutraceutical companies dominate procurement volume. Healthcare providers are where qualification requirements tighten most.
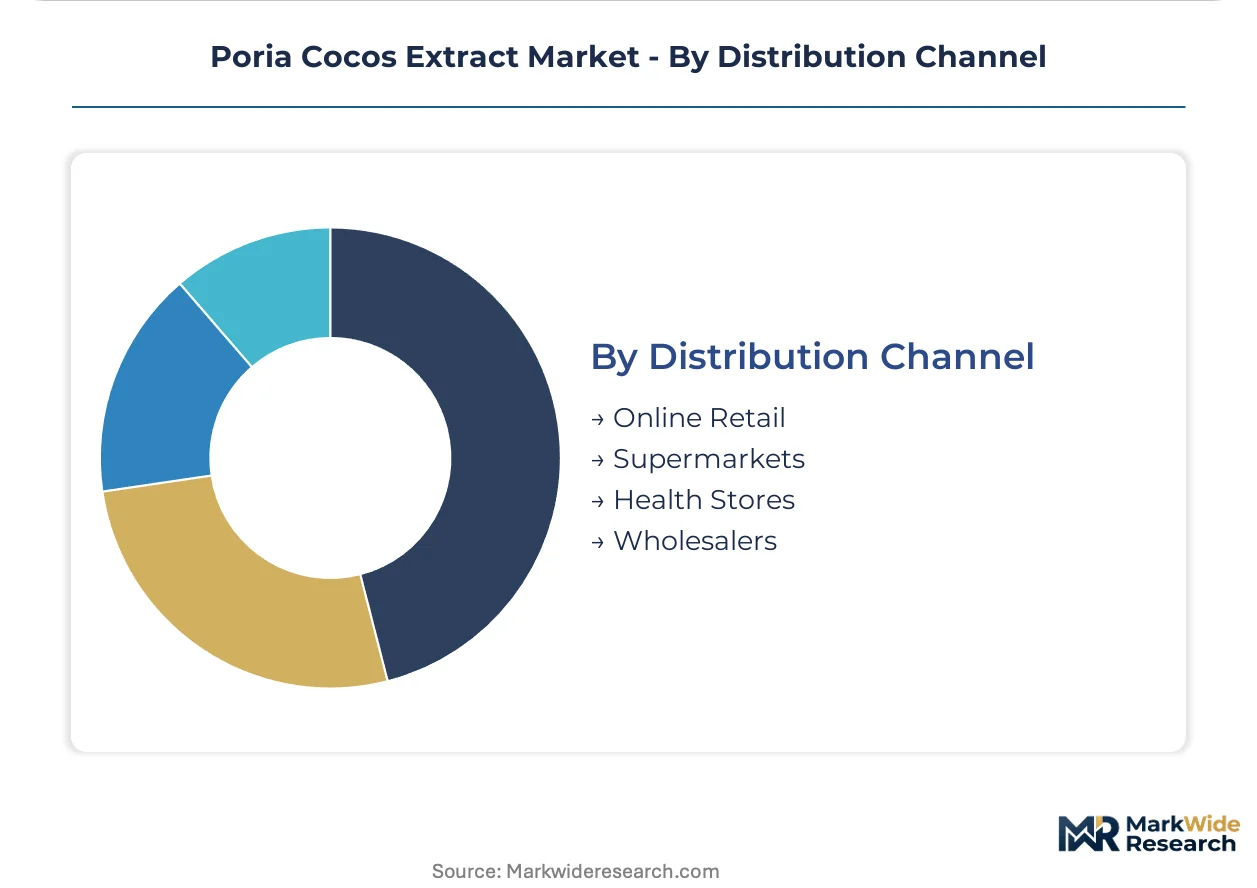
Distribution Channel:
Channel disintermediation is compressing traditional broker-mediated flows, with direct relationships between extractors and brand owners reshaping margin capture.
- Online Retail:E-commerce pure-plays and direct-to-consumer wellness brands are establishing quality agreements with Zhejiang province GMP-certified facilities, bypassing regional import distributors for premium powder segments.
- Health Stores:Specialized retail networks across North America stock capsule and tablet formats with visible USP verification marks, creating price premiums over standard-grade alternatives.
- Wholesalers:Traditional bulk ingredient distributors serving mid-scale formulators without direct China sourcing capabilities or regulatory documentation expertise.
- Supermarkets:Mass retail placement for finished supplements and functional beverages with lower active constituent thresholds and competitive pricing requirements.
Online retail is gaining share fastest. Health stores maintain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's Shaanxi and Zhejiang provinces where GMP-certified spray-drying capacity anchors pharmaceutical-grade premiums, while North American formulators absorb cost markups through shortened supply chains that bypass traditional import brokers.
China
Qinling mountain cultivation zones supply wild-harvested substrates to extraction facilities in Shaanxi province, while artificial log fermentation systems in Zhejiang stabilize throughput for cosmetic-grade outputs. NMPA dual carbon goals compliance mandates energy-intensive facility retrofits that compress the supplier base toward operators with captive analytical capabilities. Xi'an and Hangzhou industrial clusters host submerged fermentation bioreactors that displace traditional sclerotium drying workflows.
United States
Health store networks and e-commerce pure-plays drive procurement of USP-verified polysaccharide powders for immune-modulating supplement lines targeting stress-response applications. FDA botanical drug development guidance shapes IND-enabling documentation requirements that favor extractors with validated analytical methods and GMP-certified infrastructure. Direct quality agreements between domestic brands and Chinese spray-drying specialists are shortening traditional distributor-mediated supply chains.
Japan
Convenience retail networks expand procurement of liquid extract formats with verified polysaccharide content for ready-to-drink adaptogenic beverages. METI standards for functional food ingredient safety create qualification friction for non-traditional extract formats entering nutraceutical channels. Osaka and Tokyo metropolitan areas concentrate demand from formulators seeking triterpenoid fractions for barrier repair cosmeceuticals.
South Korea
Cosmeceutical manufacturers in Seoul and Gyeonggi province drive demand for triterpenoid fractions targeting anti-inflammatory topical applications and barrier repair positioning. MFDS cosmetic ingredient documentation requirements align with K-beauty export standards that emphasize constituent profiling for European and North American market access. Domestic fermentation engineering expertise supports captive mycelial biomass production for pharmaceutical-grade extract outputs.
Germany
REACH registration requirements for novel botanical substances entering cosmetic and nutraceutical channels tighten substance characterization thresholds for extract importers. ECHA documentation demands for full constituent profiling extend market access timelines for non-traditional liquid extract formats. Frankfurt and Munich-based regulatory consultancies partner with Chinese liquid extract specialists to pre-validate dossier submissions before commercial launch attempts.
Poria Cocos Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with upstream extraction-scale specialists capturing margin from standardized testing protocols while formulation-focused distributors compete through retail channel control. The supplier base compresses toward operators with captive raw material sourcing and GMP-certified spray-drying capacity as NMPA and FDA documentation requirements intensify. Two strategic archetypes dominate: fermentation-scale specialists with bioreactor configurations and quality-verification-integrated extractors with validated analytical methods. Competitive moves concentrate on direct procurement relationships that disintermediate traditional brokers and IND-enabling documentation services that capture pharmaceutical-grade premiums.
Among Shaanxi province-based extraction specialists, Xi'an Natural Field Bio-Technique Co., Ltd. and Shaanxi Undersun Biomedtech Co., Ltd. occupy positions within the upstream operator tier that benefits from capital-intensity divergence. NOW Foods represents the North American retail channel control archetype, anchoring health store network distribution across domestic markets. These three entities exemplify how competitive advantage rotates toward integrated capabilities spanning cultivation zones through validated powder output.
| Leading Market Players |
|---|
| Xi'an Natural Field Bio-Technique Co., Ltd. |
| Shaanxi Undersun Biomedtech Co., Ltd. |
| Phytoney Natural Products Co., Ltd. |
| Inner Mongolia Runxi Biotechnology Development Co., Ltd. |
| Guangdong Nenghua Biotech Co., Ltd. |
| Hunan Ouming Pharmaceutical Co. Ltd. |
| Jiangyin Yacheng Biotech Co. Ltd. |
| Zibo Orient Poria Co., Ltd. |
| NOW Foods |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between North American nutraceutical brands and Shaanxi province spray-drying specialists lock in both raw material access and price visibility for pharmaceutical-grade polysaccharide powders. These contracts insulate buyers from Qinling mountain cultivation volatility while securing GMP-certified capacity for immune-modulating supplement lines.
Pricing Analysis
The customization-premium spread separates configured-to-order USP-verified specifications from standard-grade powder alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale commitments. Pricing pressure stems from synthetic diuretic substitution in clinical settings, compressing therapeutic-grade demand. Food manufacturers exhibit highest price sensitivity due to cost-efficiency priorities, while healthcare providers absorb premiums for comprehensive constituent profiling.
Supply Chain Analysis
Qinling mountain substrate access acts as a chokepoint concentrating procurement risk among extractors without captive artificial log fermentation capacity. Supply concentrates in China's Shaanxi and Zhejiang provinces, with secondary inputs drawn from submerged fermentation bioreactor systems and pine cultivation zones. Single-source vulnerability runs through wild-harvest dependence in mountain cultivation areas. Distribution runs through direct quality agreements disintermediating traditional import brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic small-molecule diuretics and pharmaceutical-grade mushroom substitutes threaten to displace Poria cocos in therapeutic applications, forcing incumbents to defend positioning through differentiation and documentation depth.
For Market Incumbents: Consolidate GMP-certified spray-drying capacity in Shaanxi and Zhejiang provinces to anchor pharmaceutical-grade premiums against synthetic substitution threats. Deepen backward integration into artificial log fermentation systems, reducing wild-harvest exposure. Invest in IND-enabling documentation services to capture botanical drug development revenue streams from FDA-guided therapeutic positioning.
For New Entrants and Emerging Players: Lead with functional beverage liquid extract formats targeting Japanese and US convenience retail networks, where verified polysaccharide content commands margin premiums. Dermatological actives for Korean cosmeceutical formulators represent the most penetrable white-space segment. Establish direct quality agreements with Zhejiang province GMP-certified facilities to bypass distributor markups.
For Investors and Strategic Acquirers: Fermentation-scale specialists with validated analytical methods and captive Qinling mountain cultivation zones offer the strongest long-term viability through the substitution defense window. Monitor pharmacopeial harmonization momentum between Chinese Pharmacopoeia, USP, and EP standards as the critical inflection signal for cross-border qualification friction reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | Shaanxi province facilities secure FDA and NMPA documentation compliance for pharmaceutical-grade output. |
| Submerged Fermentation Scale-Up | Bioreactor configurations displace wild-harvest dependence, stabilizing raw material throughput for cosmetic applications. |
| Direct Procurement Relationships | North American brands bypass traditional import brokers, capturing margin from shortened supply chains. |
| IND-Enabling Documentation Services | Extractors with validated HPLC methods capture pharmaceutical-grade premiums from botanical drug developers. |
| Functional Beverage Channel Expansion | Liquid extract SKUs penetrate Japanese convenience retail networks with adaptogenic positioning. |
Research Methodology
A standing panel of extraction facility operations directors, nutraceutical formulator procurement leads, regulatory affairs specialists at NMPA and FDA, and health store network category buyers provided ongoing calibration across primary fieldwork. Secondary validation drew from NMPA botanical ingredient guidance documents, FDA botanical drug development guidance, USP and EP pharmacopeial monographs, and customs trade data for polysaccharide-rich extract flows. Bottom-up facility capacity assessments triangulated against top-down nutraceutical formulation demand estimates.
Consistency checks validated volume and value outputs against external benchmarks including fermentation capacity disclosures and functional beverage launch announcements. Segmentation modeling spanned product type, application tier, end-user archetype, and distribution channel across the projection horizon. CAGRs were derived from installed base growth rates and substitution elasticity parameters, incorporating submerged fermentation yield improvements and pharmacopeial harmonization adoption curves as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NMPA dual carbon goals enforcement and FDA botanical drug guidance frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as synthetic diuretic substitution rates and EFSA novel food catalog timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Taste Modulators Market