
 Europe Aluminium Cans Market | 2026-2036
Europe Aluminium Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminium Cans Market Intelligence
Craft beer and premium sparkling water is rebalancing the European beverage packaging mix toward aluminium. Ball Corporation leverages its continental manufacturing footprint to serve Nordic and Central European brewers. Ardagh Group S.A. anchors supply through its diversified metal packaging network across Ireland, Germany, and the UK. Crown Holdings Inc. differentiates via advanced lightweighting technologies that reduce material inputs per unit.
Europe aluminium cans are cylindrical single-serve containers formed from aluminium alloy 3104-H19 or 3004-H19, typically wall-drawn and ironed to achieve sidewall thickness below 0.1mm, designed primarily for carbonated and non-carbonated beverage containment with hermetic sealing. Specialty cans command margin premiums as beverage makers pursue shelf differentiation through embossed textures and custom shaping. Sleek cans represent the fastest-growing capacity-adjusted format as energy drink and ready-to-drink coffee brands target on-the-go consumption occasions. The 330ml standard retains volume dominance in beer applications across Germany and the Czech Republic.
EU Green Deal packaging regulations and the F-Gas Regulation shape material circularity mandates, while ECHA REACH compliance governs coating chemistries and interior lacquer formulations. National implementations of extended producer responsibility frameworks in France, Germany, and Italy tighten collection and recycling targets. Stakeholders must monitor evolving deposit-return scheme harmonization across EU member states and assess recycling infrastructure investments against regulatory compliance timelines.
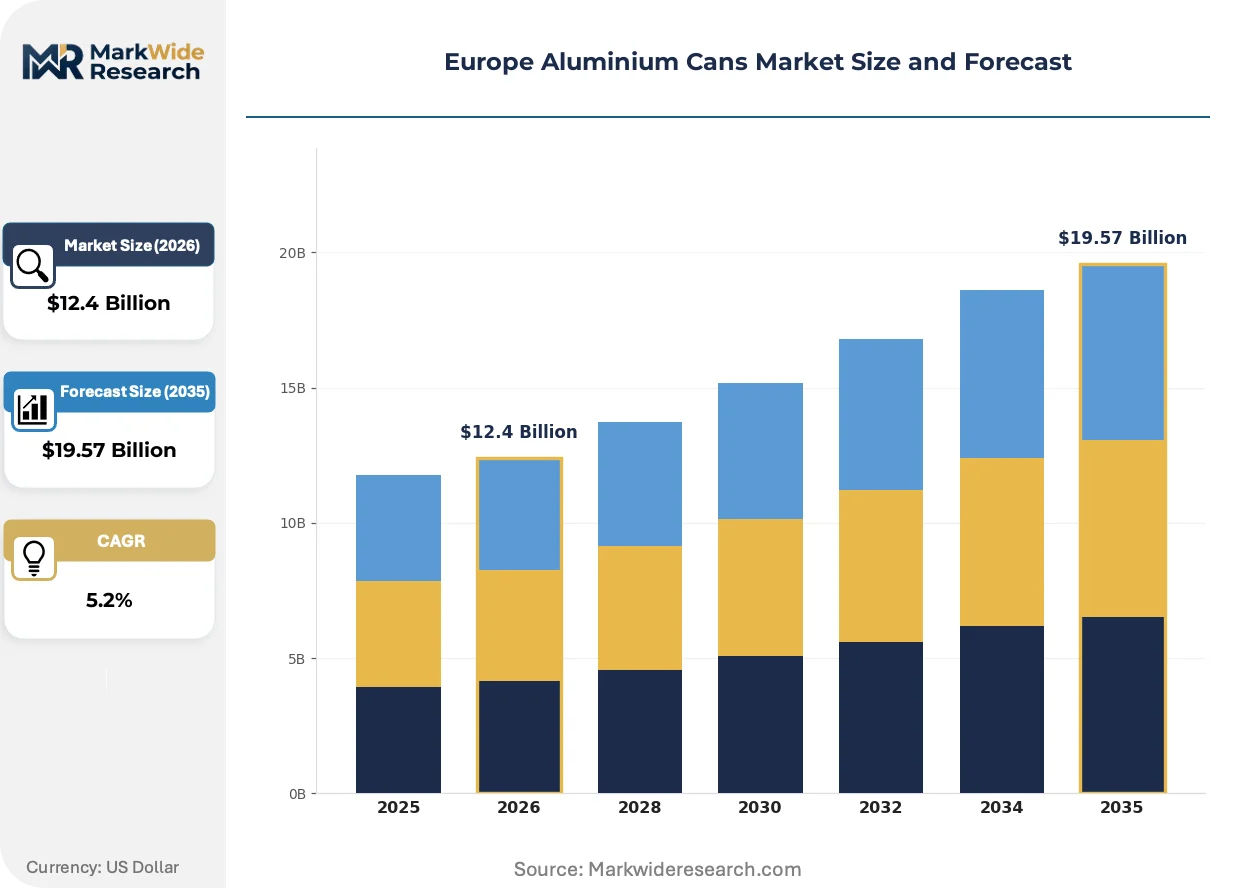
Market Dynamics
The EU Green Deal's packaging waste directives are compressing material circularity timelines, forcing beverage brands and can makers to accelerate lightweighting investments and closed-loop recycling infrastructure ahead of regulatory deadlines.
Growth Catalysts
- Deposit-return scheme harmonization:EU member states are converging collection targets under extended producer responsibility frameworks, expanding aluminium recovery rates across France, Germany, and Italy.
- Craft beer format migration:Small-batch brewers in the Czech Republic and Belgium are abandoning glass bottles for 330ml and 500ml aluminium formats to reduce breakage and logistics weight.
- Sparkling water premiumization:Nordic and German mineral water brands are adopting embossed and matte-finish cans to command shelf price premiums in convenience retail.
Market Restraints
- Primary aluminium input volatility:LME price swings for aluminium ingot directly compress converter margins, particularly for independent can makers without smelter backward integration.
- Lacquer chemistry compliance costs:ECHA REACH restrictions on bisphenol-A and epoxy-based interior coatings force reformulation investments that add cents per unit.
- Steel can substitution persistence:Three-piece tinplate formats retain cost advantages in ambient shelf-stable beverages, limiting aluminium penetration in Eastern European value segments.
Strategic Opportunities
- Central European capacity gap:Poland and Hungary show underpenetrated demand for sleek and slim can formats as energy drink consumption rises among urban demographics.
- Digital printing convergence:High-speed inkjet decoration on can bodies enables batch-of-one customization, allowing craft brewers to run limited editions without plate changeover downtime.
- F-Gas Regulation thermal management:Beverage cooling equipment mandates are accelerating demand for ambient-stable packaging that tolerates supply chain temperature excursions.
Industry Challenges
- Lightweighting engineering talent scarcity:Deep-drawing simulation expertise for sub-0.09mm wall thicknesses concentrates at a handful of German and Austrian tooling houses.
- Collection infrastructure capex intensity:Reverse vending machine deployment and sorting line upgrades require municipal co-investment that lags behind producer compliance timelines.
- Cross-border scrap traceability:Harmonized mass-balance accounting for recycled content claims remains unresolved across EU member state implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminium Cans Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $19.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Specialty Cans, Sleek Cans, Pull-Tab Cans End User: Beverage, Food, Personal Care, Household Products Capacity: 330ml, 500ml, 1L, 250ml Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers |
| Companies Covered | Silgan Holdings Inc., CCL Container Inc., Ball Corporation, Massilly Holding SAS, Tecnocap Group, Ardagh Group S.A., CAN-PACK SA, Sonoco Products Company, Crown Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminium Cans Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compression are redefining can performance specifications. Three developments are reshaping competitive positioning: alloy optimization, policy-driven circularity mandates, and on-the-go consumption format preferences.
High-strength aluminium-magnesium alloy variants are electrifying lightweighting trajectories. These formulations permit sidewall thickness reductions below 0.085mm without sacrificing pressure resistance. Premium sparkling water and ready-to-drink coffee brands in Germany and the UK are specifying these alloys for 250ml slim formats. The technology is compressing gram-weight per unit and enabling logistics cost savings that offset alloy premiums.
EU Green Deal packaging regulations are mandating minimum recycled content thresholds and extended producer responsibility fee structures. These rules are forcing converters to secure scrap supply contracts and invest in alloy separation technologies. The craft beer segment faces the steepest compliance curve due to smaller batch volumes and limited negotiating leverage with recyclers.
Convenience retail channel expansion is fragmenting traditional beverage distribution. Forecourt stores and urban micro-fulfillment centers are prioritizing single-serve formats with smaller case cubes. Energy drink brands are responding with 200ml and 250ml slim cans optimized for chilled impulse fixtures in Nordic and Benelux markets.
Europe Aluminium Cans Market Segmentation
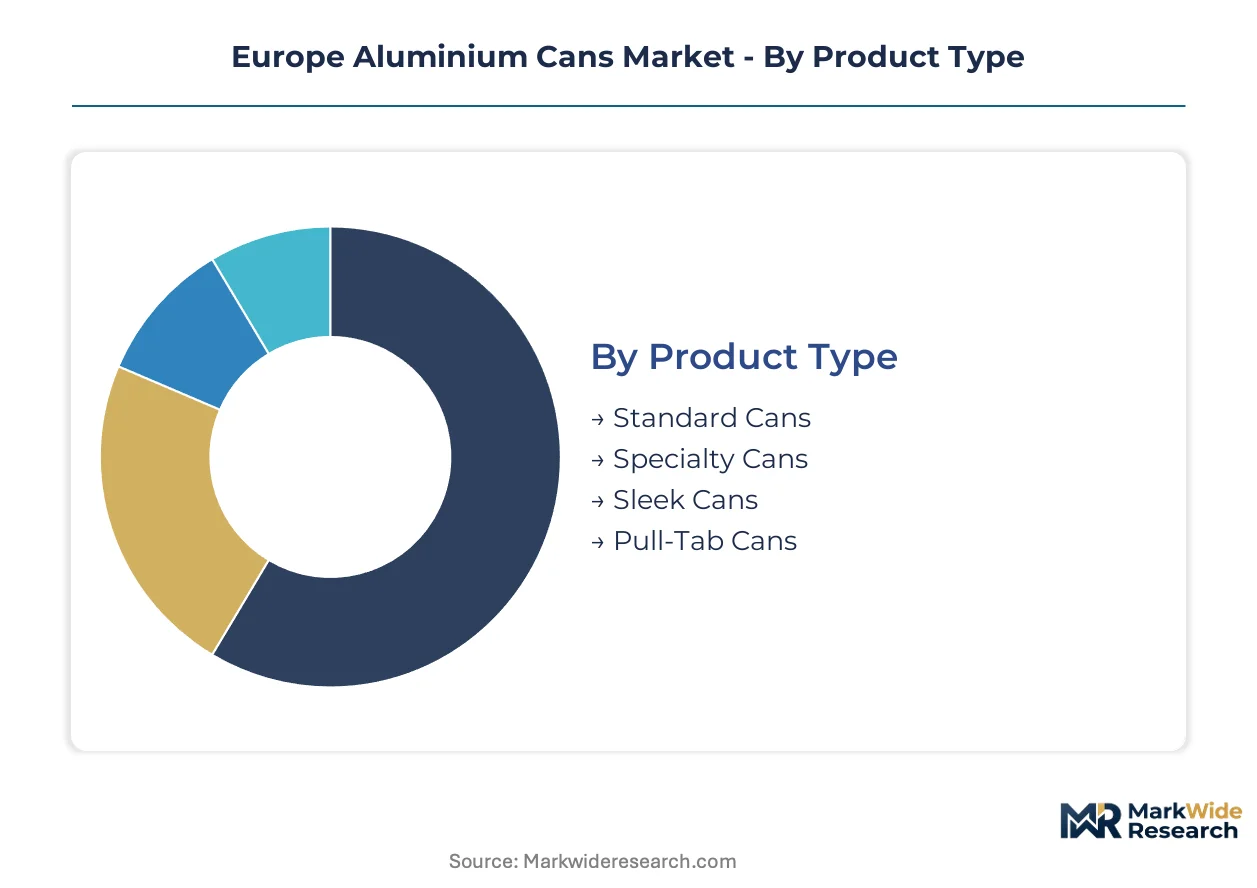
Aluminium can specifications diverge sharply across beverage categories, with wall thickness, alloy composition, and surface finish determining suitability for carbonation pressure, thermal processing, and shelf differentiation. European converters must align capacity investments with format-specific demand trajectories in craft beer, energy drinks, and premium water.
Product Type:
Wall thickness and forming complexity separate commodity formats from engineered specialty variants.
- Standard Cans:Drawn-and-ironed 3104-H19 alloy construction with 0.095mm sidewall thickness serves mass-market beer and carbonated soft drinks across Germany and the Czech Republic. Demand concentrates in high-volume brewing contracts where gram-weight optimization drives logistics economics.
- Sleek Cans:Narrow-diameter 250ml and 330ml formats with reduced end diameter accommodate higher filling speeds and smaller case cubes for convenience retail. Energy drink brands in Nordic markets and ready-to-drink coffee lines in the UK specify these for chilled impulse fixtures.
- Specialty Cans:Embossed textures, matte finishes, and custom shaping command margin premiums from premium sparkling water producers seeking shelf differentiation.
- Pull-Tab Cans:Stay-on-tab designs dominate EU regulatory compliance for litter reduction, with full-aperture ends gaining share in craft beer for aroma release.
Standard cans lead on scale; sleek cans lead on momentum.
End User:
Pressure requirements and regulatory exposure vary substantially across consumption categories.
- Beverage:Carbonated beer, soft drinks, and energy drinks generate the dominant volume, with EU Green Deal packaging mandates forcing lightweighting investments across German and French supply chains.
- Food:Aseptically filled ready meals and pet food applications utilize thicker-walled 3004-H19 variants for retort processing compatibility.
- Personal Care:Aerosol propellant cans for deodorants and hair sprays face F-Gas Regulation compliance pressures on propellant chemistry.
- Household Products:Insecticides and cleaning sprays require corrosion-resistant interior lacquer formulations meeting ECHA REACH restrictions.
Beverage commands installed capacity; personal care faces steepest reformulation costs.
Capacity:
Volume selection reflects consumption occasion and channel placement economics.
- 330ml:The continental standard for beer across Germany, Belgium, and the Czech Republic, optimized for on-premise serving sizes and supermarket multi-packs.
- 500ml:Large-format cans serve value beer segments and sharing-size soft drinks in Eastern European markets.
- 250ml:Energy drinks and espresso-based beverages target single-serve convenience consumption in urban Benelux and Nordic forecourt retail.
- 1L:Family-size formats for sparkling water and mixers concentrate in German and Austrian discount grocery channels.
330ml anchors production volume; 250ml expands most quickly.
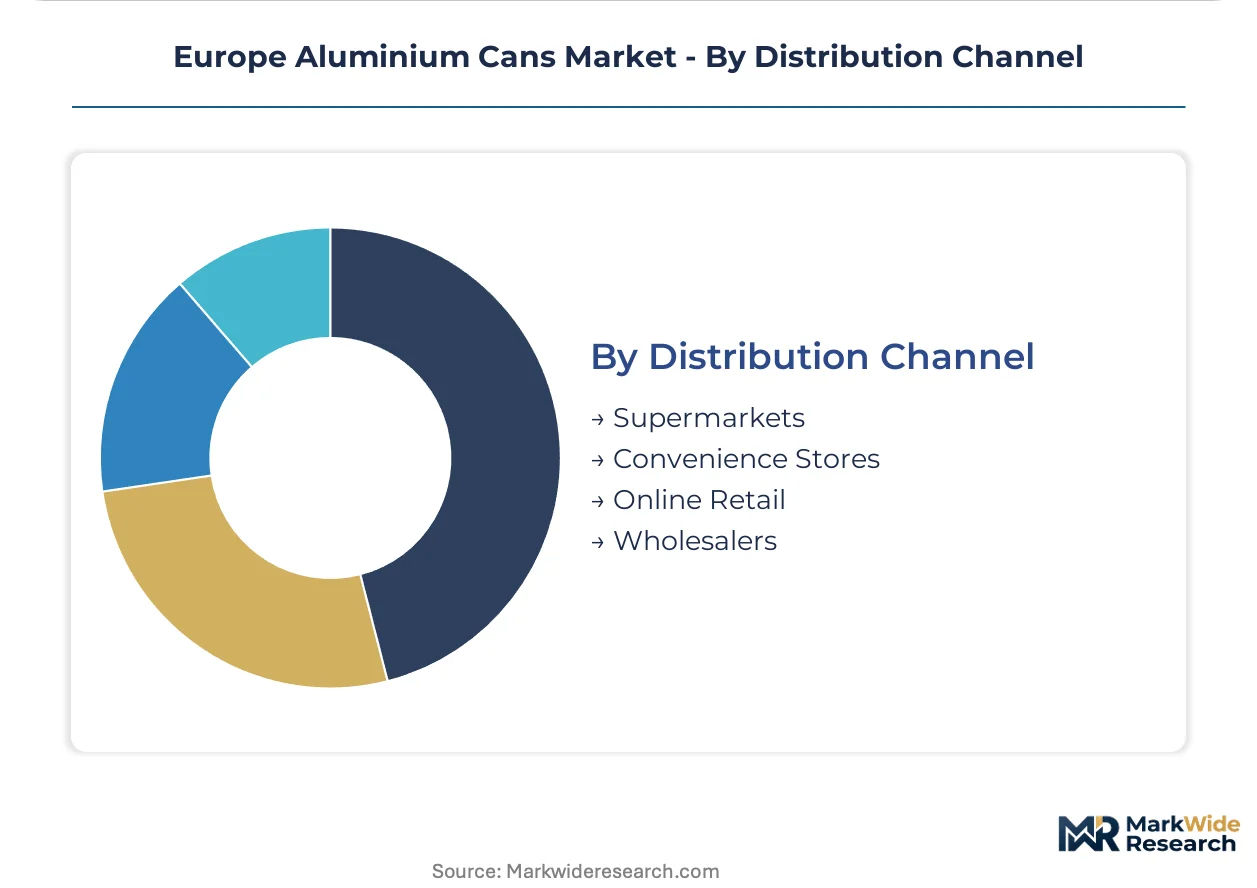
Distribution Channel:
Channel mix determines case configuration, palletization, and promotional customization requirements.
- Supermarkets:High-velocity German and French retail chains demand 24-can trays with shelf-ready packaging and seasonal promotional lithography.
- Convenience Stores:Forecourt and urban micro-retail in Nordic markets prioritize smaller case cubes and chilled single-serve availability.
- Online Retail:Direct-to-consumer beverage subscriptions require enhanced dent resistance and customized outer packaging for last-mile delivery.
- Wholesalers:Cash-and-carry and foodservice distributors in Italy and Spain handle bulk-format 500ml and 1L cans for hospitality sector resale.
Supermarkets dominate volume throughput; online retail forces packaging redesign investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as converters weigh ECHA REACH compliance costs against logistics proximity to beverage clusters. The EU Green Deal's packaging waste directives create uneven cost-of-compliance surfaces across member states, with some jurisdictions accelerating deposit-return scheme harmonization faster than others.
Germany
Deposit-return scheme harmonization under the German Packaging Act is driving aluminium recovery rates above regional averages. ECHA REACH restrictions on interior lacquer chemistries are forcing reformulation investments at converter facilities in Bavaria and North Rhine-Westphalia. The Rhine-Ruhr industrial corridor hosts deep-drawing tooling specialists serving sub-0.09mm wall thickness specifications for premium beverage clients.
United Kingdom
Craft beer format migration is accelerating as small-batch brewers abandon glass for 330ml and 500ml aluminium formats to reduce breakage. The UK Environment Agency's extended producer responsibility framework is tightening collection targets ahead of EU convergence timelines. Manufacturing capacity concentrates in the Midlands and Yorkshire, where converters serve ready-to-drink coffee brands targeting convenience retail.
France
Sparkling water premiumization is driving demand for embossed and matte-finish cans in Parisian convenience retail channels. ANSM and CNIL oversight of packaging materials intersects with EU Green Deal circularity mandates to create dual compliance layers. The Hauts-de-France region anchors production for mineral water brands exporting across Benelux markets.
Italy
Foodservice distribution through cash-and-carry wholesalers in Lombardy and Emilia-Romagna is sustaining bulk-format 500ml demand for hospitality resale. National implementation of extended producer responsibility frameworks lags German and French timelines, creating temporary cost advantages for converters. Northern Italian industrial clusters specialize in corrosion-resistant lacquer formulations for aseptically filled applications.
Poland
Underpenetrated demand for sleek and slim can formats is attracting capacity investments as energy drink consumption rises among Warsaw and Kraków urban demographics. Polish packaging regulations are converging toward EU Green Deal standards, though deposit-return infrastructure remains less developed than Western European benchmarks. The Silesian manufacturing belt is emerging as a cost-competitive location for 250ml format production serving Central European markets.
Europe Aluminium Cans Market Key Industry Players
Capacity expansion dominates the current landscape as converters position ahead of EU Green Deal compliance deadlines. The vendor base stratifies across three tiers: integrated multinationals with captive alloy supply, mid-cap specialists with regional manufacturing footprints, and independent converters serving niche format specifications. Strategic archetypes include lightweighting technology leaders, circularity infrastructure investors, and digital printing capability builders. M&A activity and geographic expansion represent the dominant competitive vectors as players seek scale efficiencies and scrap supply security.
Within the integrated multinational tier, Ball Corporation and Crown Holdings Inc. exemplify scale-driven positioning through continental manufacturing networks. Ardagh Group S.A. occupies a distinctive position as a diversified metal packaging specialist with manufacturing presence across Ireland, Germany, and the UK. Among mid-cap specialists, CAN-PACK SA represents the Central European cost-optimization archetype with production gravity in Poland serving underpenetrated regional demand.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| CCL Container Inc. |
| Ball Corporation |
| Massilly Holding SAS |
| Tecnocap Group |
| Ardagh Group S.A. |
| CAN-PACK SA |
| Sonoco Products Company |
| Crown Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap converters in Bavaria and North Rhine-Westphalia anchor supply discipline through conservative leverage policies that buffer pricing volatility during LME aluminium swings. Their financing structure limits aggressive discounting even when independent can makers face margin compression from primary ingot cost spikes.
Pricing Analysis
Retailer markup layers in German and French supermarket channels absorb the steepest cost compression from EU Green Deal compliance investments. Three-tier pricing structure across premium embossed specialty, standard drawn-and-ironed, and economy lightweight formats separates Ball Corporation's high-end contracts from CAN-PACK SA's volume-driven Central European positioning. Pricing pressure stems from ECHA REACH lacquer reformulation costs that add per-unit burden without commensurate brand premium recovery. Value-tier energy drink brands in Poland show highest price sensitivity, while premium Nordic sparkling water producers absorb cost pass-through with minimal volume elasticity.
Supply Chain Analysis
Hub-and-spoke warehouse patterns radiate from Rhine-Ruhr and Midlands manufacturing clusters toward Nordic forecourt retail and Benelux convenience channels. Supply concentrates in Germany, the United Kingdom, and Poland, with the Silesian belt emerging as cost-competitive capacity for 250ml sleek formats. Raw material dependencies rest on primary aluminium ingot from Norwegian smelters, recycled scrap streams from deposit-return schemes, and high-strength magnesium alloy additives from Austrian specialty mills. Single-source vulnerability runs through deep-drawing tooling expertise concentrated at German and Austrian engineering houses. Distribution runs through cash-and-carry wholesalers in Italy and Spain for hospitality sector bulk formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters face a geographic-arbitrage play between Western European compliance costs under EU Green Deal mandates and Central European lag in extended producer responsibility implementation. Poland and Hungary offer temporary margin shelter as German and French facilities absorb full regulatory burden.
For Market Incumbents: Hedge primary aluminium exposure through long-term offtake contracts with Norwegian smelters before LME volatility intensifies. Deepen backward integration into scrap collection infrastructure to secure mass-balance accounting for recycled content claims. Steel can substitution in Eastern European value segments threatens volume retention; counter with lightweighting technology investments that preserve logistics economics against tinplate cost advantages. For New Entrants and Emerging Players: The 40-cent per-unit gap between premium embossed specialty cans and economy standard formats in Central European energy drink channels offers white-space entry. Target underpenetrated sleek format demand in Warsaw and Kraków urban demographics where convenience retail expansion outpaces domestic converter capacity. Pursue digital printing partnerships with German inkjet equipment specialists to enable batch-of-one craft beer customization without plate inventory burden. For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters lacking smelter backward integration but holding sub-0.09mm wall thickness engineering capabilities. Long-term viability hinges on EU deposit-return scheme harmonization completion and scrap supply contract security. Watch for inflection in cross-border scrap traceability regulation resolution, which would unlock recycled content premium pricing and validate circularity infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Investment | Sub-0.085mm wall thickness capabilities unlock logistics savings for premium beverage clients in Germany. |
| Scrap Supply Contract Securement | Mass-balance accounting compliance under EU Green Deal mandates validates recycled content claims for ECHA REACH. |
| Digital Printing Capability Buildout | High-speed inkjet decoration enables craft brewer limited editions without plate changeover downtime in UK. |
| Central European Capacity Expansion | Polish and Hungarian production footprints capture energy drink format demand ahead of regulatory convergence. |
| Corrosion-Resistant Lacquer Reformulation | Bisphenol-A-free interior coatings satisfy ECHA REACH restrictions for aseptic food and beverage applications. |
Research Approach
Bottom-up beverage end-use modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Polish manufacturing facilities, procurement leads at Nordic beverage brands, distribution channel partners in Benelux forecourt retail, and technical R&D directors at lacquer formulation houses supplied operational data. Secondary validation drew from EU customs trade statistics, ECHA REACH regulatory filings, SEC 10-K disclosures by listed packaging multinationals, and national packaging association production surveys. Triangulation across these sources reconciled volume estimates with capacity utilization patterns.
Historical trendline analysis of alloy input costs, lightweighting adoption curves, and deposit-return scheme expansion informed projection parameters. The forecast framework segments by can format type, beverage category end-use, capacity specification, and distribution channel intensity across the analysis window. CAGRs derive from regression against macro drivers including EU Green Deal implementation pace, craft beer format migration velocity, and energy drink consumption growth in urban Central European demographics. Model inputs include LME aluminium price scenarios, ECHA REACH compliance cost curves, and reverse vending machine deployment rates.
The model assumes a particular technology adoption path; alternative pathways for high-strength aluminium-magnesium alloy lightweighting would alter the outlook if deep-drawing simulation talent scarcity persists. Forecasts reflect documented assumptions regarding regulatory timeline adherence and scrap infrastructure investment pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Metal Casting Market
Metals
Steel Casting Market
Metals
HSLA Steel Plate Market
Metals
Industrial Metal Strips Market
Metals
Zirconium Market
Metals
Global Vanadium Market
Metals
Steel Long Products Market
Metals
Global Flat Carbon Steel Market
Metals
Tin Chloride Market
Metals
GCC Aluminium Cans Market
Metals
Global Copper Sputtering Target Market
Metals
Aluminum Extrusion Market
Metals
Copper Chromium Black Market
Metals
Japan Aluminium Powder Market
Metals
Global Bronze Market
Metals
Prebaked Anodes for Aluminum Market