
 Rare Earth Elements Recycling Market | 2026-2036
Rare Earth Elements Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Earth Elements Recycling Market Analytics
Market Context
The capital-intensity divergence between integrated refiners and specialized recyclers is unwinding as pyrometallurgical furnace investments decline relative to hydrometallurgical circuit builds. MP Materials Corp. leverages its Mountain Pass extraction infrastructure to anchor magnet rare earth supply chains domestically. Solvay S.A. sustains European chemical refining leadership through its La Rochelle rare earth separation complex. Mitsubishi Materials Corporation dominates Japanese urban mining operations with proprietary scrap-sorting technologies.
Technical Definition and Segment Structure
Rare earth elements recycling encompasses the recovery of lanthanides and scandium from post-consumer and post-industrial waste streams through hydrometallurgical leaching, solvent extraction, or electrowinning to achieve 99.5% purity grades suitable for magnet remanufacturing. The process primarily serves to bypass Chinese concentrate dependency and secure defense-critical neodymium-praseodymium supply for permanent magnet production. Magnet recycling occupies the deepest margin pools due to neodymium-iron-boron alloy value concentration, while bioleaching represents the fastest-growing technology segment as bacterial lixiviant methods reduce acid consumption and tailings toxicity. Mechanical separation remains mature with limited upside, though it anchors feedstock preparation for downstream chemical circuits.
Regulatory Frame and Outlook
The US Department of Defense and EPA coordinate stockpile releases and hazardous waste permitting to shape domestic recycling economics, while the EU Critical Raw Materials Act imposes 15% recycled content benchmarks for strategic minerals by decade end. REACH compliance and RoHS substance restrictions further constrain feedstock acceptance criteria across European processors. Stakeholders must monitor how China's export license regime for rare earth technology interacts with Western subsidy programs to determine optimal facility siting and offtake contracting strategies.
Market Dynamics
Magnet rare earth recovery from end-of-life electronics is compressing feedstock economics as hydrometallurgical leaching circuits displace pyrometallurgical furnaces. This technology pivot is redrawing capital allocation between integrated refiners and specialized urban mining operators.
Growth Catalysts
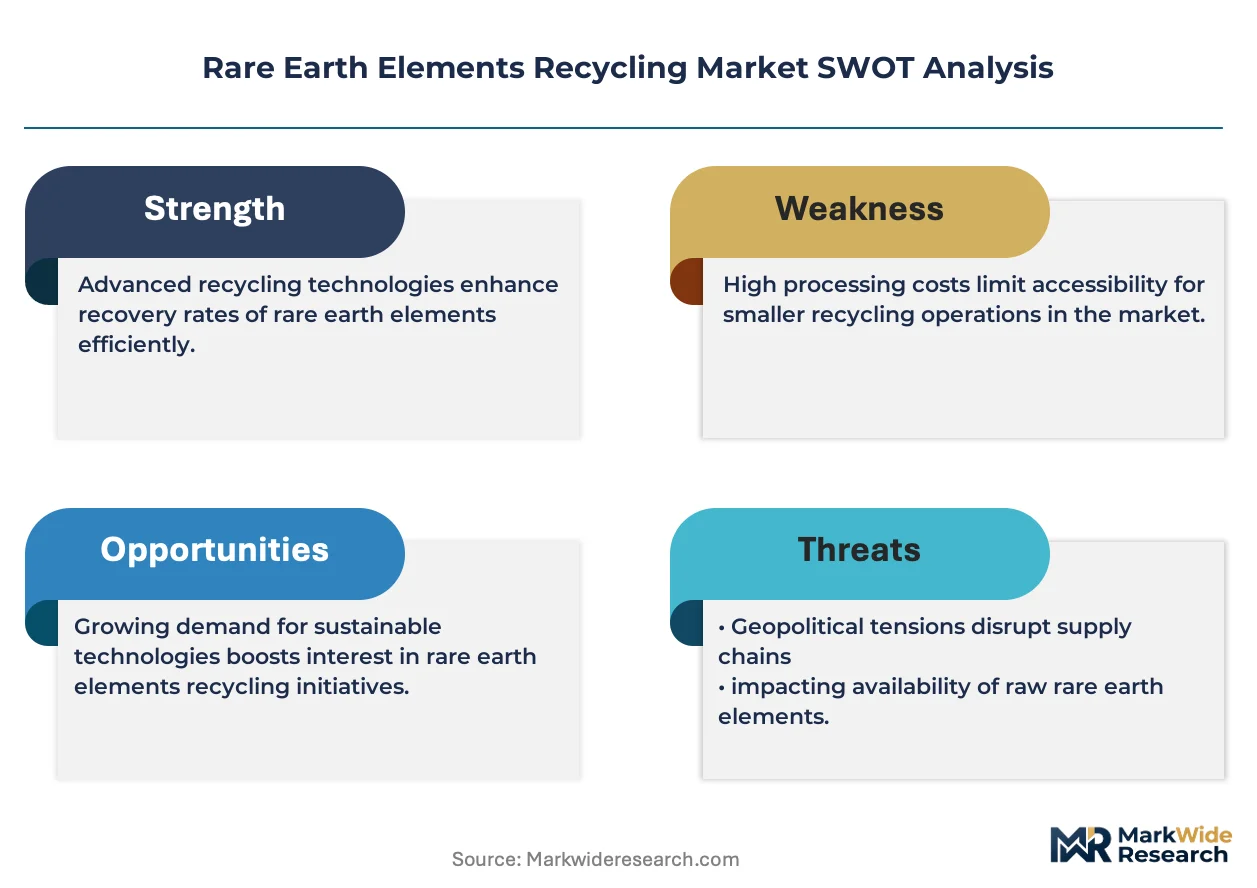
- EU Critical Raw Materials Act:The 15% recycled content mandate for strategic minerals by decade end is forcing automotive and wind turbine OEMs to secure qualified magnet scrap offtake contracts.
- Neodymium-iron-boron magnet demand:Electric vehicle traction motors and direct-drive wind generators are consuming virgin concentrate faster than mining capacity expands, pulling recycled NdPr oxides into specification-grade supply chains.
- Hard disk drive retirement waves:Data center decommissioning protocols in North America and Western Europe are releasing concentrated rare earth magnet feedstock at predictable volumes.
Market Restraints
- Chinese concentrate dependency:Western recyclers remain tethered to Chinese rare earth oxide pricing for feedstock valuation, limiting margin capture during concentrate price spikes.
- REACH substance restrictions:European processors face feedstock rejection when trace heavy metals exceed RoHS thresholds, constraining acceptable scrap sources.
- Acid reagent cost volatility:Sulfuric and hydrochloric acid prices swing with energy markets, eroding hydrometallurgical circuit economics during input cost spikes.
Strategic Opportunities
- Defense stockpile programs:The US Department of Defense is contracting domestic recyclers for neodymium-praseodymium supply security, creating premium-priced offtake channels outside commercial spot markets.
- Bioleaching technology convergence:Bacterial lixiviant methods combined with membrane filtration are opening low-grade magnet slag processing at acid consumption rates below conventional circuits.
- Japan's urban mining infrastructure:METI-subsidized collection networks for consumer electronics are generating high-purity magnet scrap streams with documented provenance for aerospace magnet remanufacturing.
Industry Challenges
- Solvent extraction engineering talent:Rare earth separation chemistry expertise concentrates at legacy mining operations, forcing recyclers to recruit from phosphate or uranium processing industries.
- 99.5% purity certification timelines:Magnet alloy specifications require 18-24 month qualification cycles with automotive Tier-1 suppliers, delaying revenue recognition for new recycling capacity.
- Scrap-sorting IP fragmentation:Proprietary automated disassembly technologies for hard disk drives are locked behind exclusive licensing agreements, limiting technology access for mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Earth Elements Recycling Market |
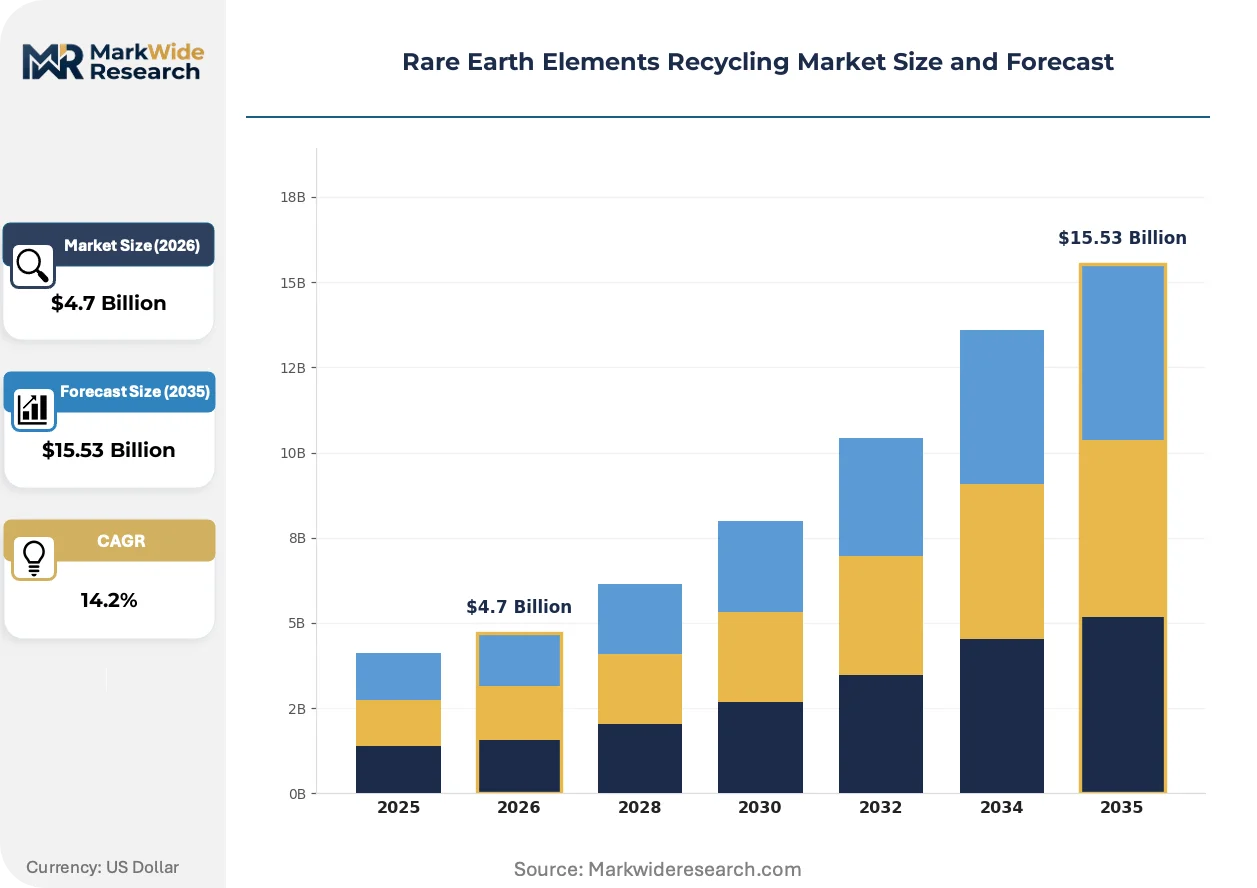
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
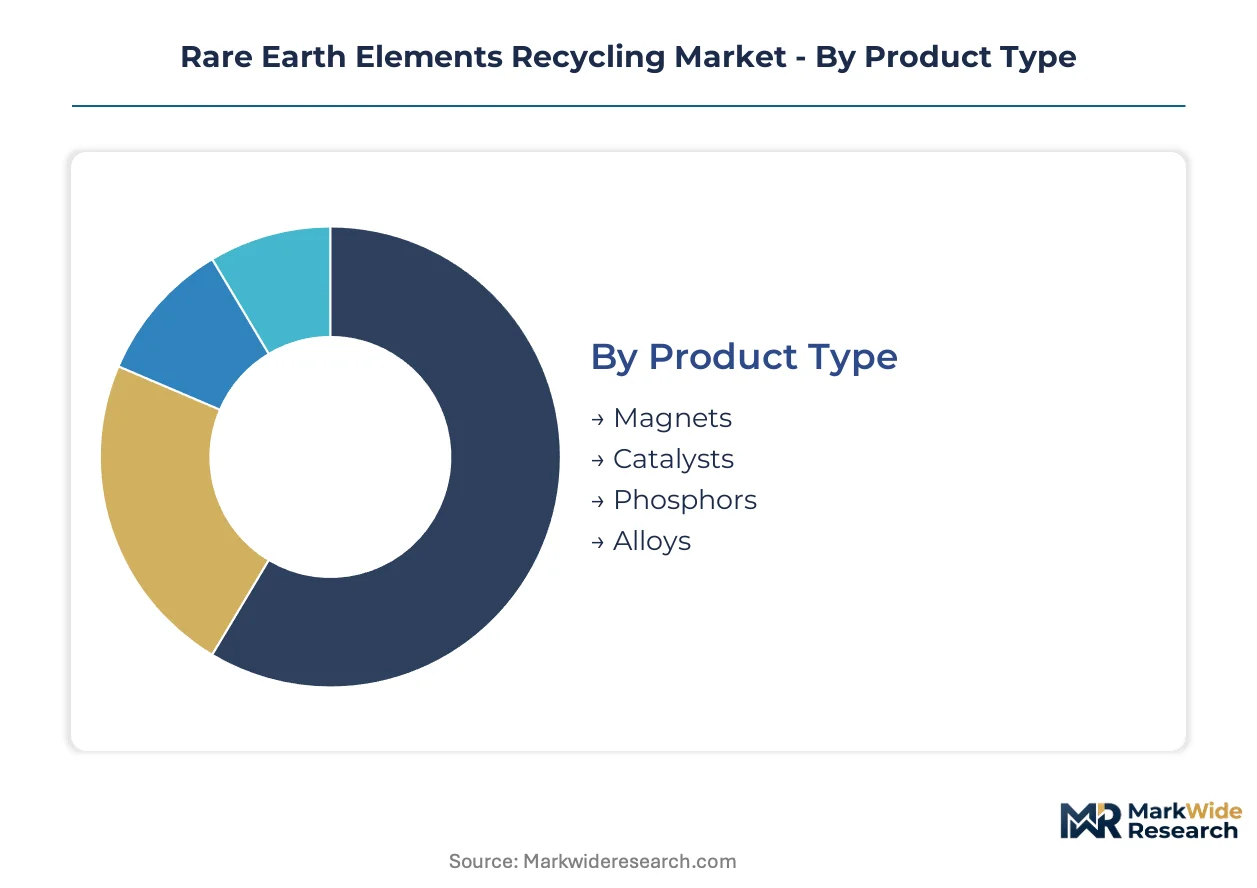
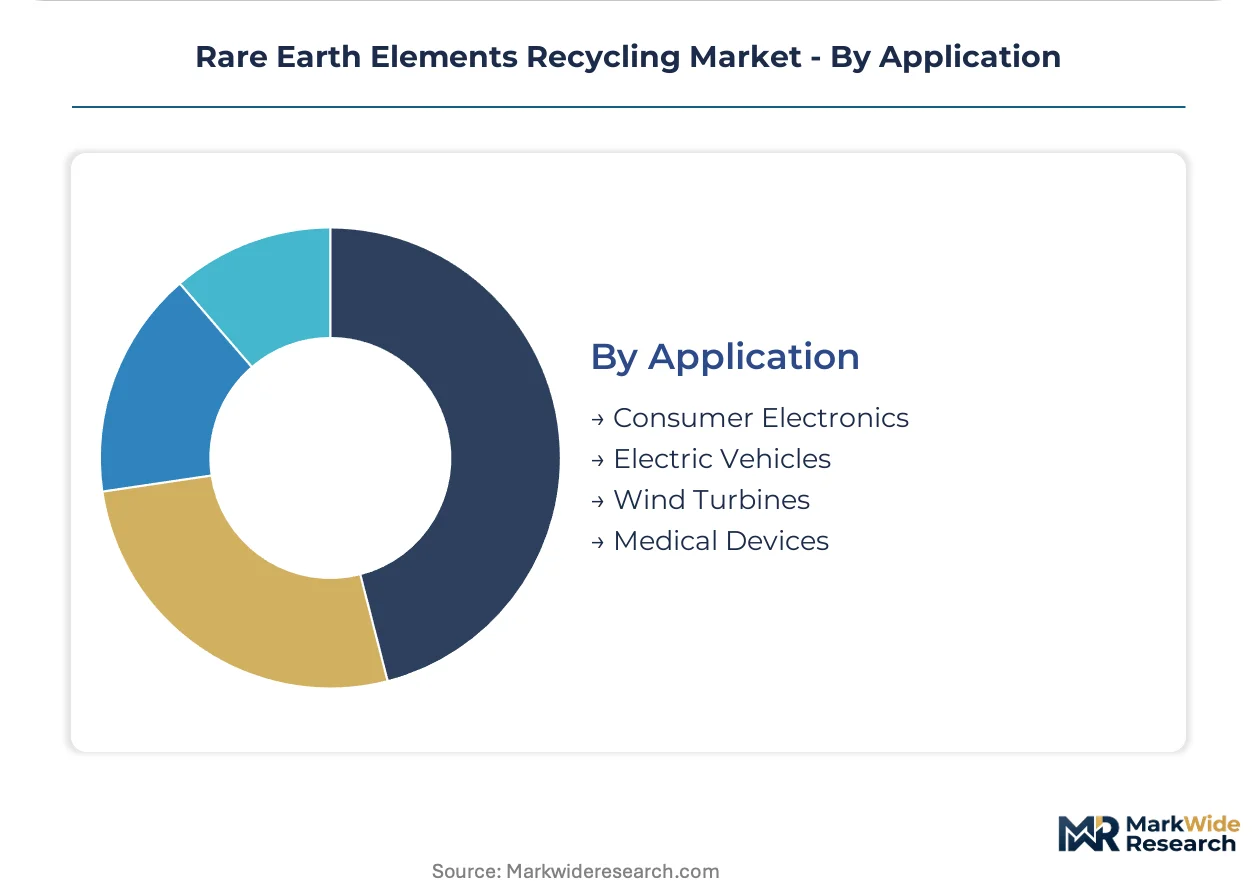
| Segmentation | Product Type: Magnets, Catalysts, Phosphors, Alloys End User: Aerospace, Electronics, Automotive, Renewable Energy Technology: Hydrometallurgical, Bioleaching, Pyrometallurgical, Mechanical Separation Application: Consumer Electronics, Electric Vehicles, Wind Turbines, Medical Devices |
| Companies Covered | MP Materials Corp., Neo Performance Materials, Solvay S.A., Geomega Resources Inc., Mitsubishi Materials Corporation, Hitachi Metals, Energy Fuels Inc., REEcycle Inc., Umicore N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Earth Elements Recycling Market Evolving Landscape
Hydrometallurgical process flows are fragmenting into acid-saving and acid-intensive variants as environmental compliance costs diverge across jurisdictions. Equipment suppliers are now configuring modular leaching skids for either bacterial or conventional chemistry.
Bioleaching is bifurcating the technology landscape for low-grade magnet residue processing. Acidithiobacillus ferrooxidans strains now achieve 85% rare earth recovery from slag at pH levels below conventional acid requirements. Wind turbine decommissioning contractors in Denmark and Germany are piloting these circuits for blade magnet recovery. The technology is compressing tailings liability costs while extending economically viable feedstock to sub-10% rare earth content streams.
REACH authorization requirements for solvent extraction reagents are tightening feedstock acceptance criteria across European processors. ECHA's 2024 update to Annex XIV candidate list classification is forcing recyclers to substitute organophosphorus extractants with less efficient alternatives. German hydrometallurgical facilities are responding by segregating European-origin scrap from imported feedstock to maintain reagent compliance.
Magnet remanufacturers are consolidating procurement through long-term scrap supply agreements rather than spot market purchases. Automotive Tier-1 magnet suppliers in Japan and Germany now contract directly with data center decommissioning firms for hard disk drive retirement schedules. This disintermediation is visible most acutely in the Neodymium-iron-boron alloy segment, where qualified scrap now trades at premiums to virgin oxide pricing.
Rare Earth Elements Recycling Market Segmentation
Segmentation in rare earth recycling determines which feedstock streams justify capital-intensive hydrometallurgical circuits versus simpler mechanical routes. Channel economics diverge sharply between defense-qualified magnet scrap and consumer electronics residue.
Product Type:
Channel flows split between high-value magnet alloys routed through aerospace and defense contractors versus bulk catalyst streams moving through chemical processors.
- Magnets:Neodymium-iron-boron and samarium-cobalt alloys concentrate 90% plus rare earth content by mass. Demand from electric vehicle traction motor manufacturers in Germany and Japan is pulling qualified scrap into long-term offtake contracts at premiums to spot oxide pricing.
- Catalysts:Fluid catalytic cracking residues from petroleum refining contain lanthanum and cerium in recoverable concentrations. US Gulf Coast refiners are contracting directly with Solvay's La Rochelle facility for closed-loop lanthanum recovery.
- Phosphors:Compact fluorescent lamp and LED phosphor waste streams yield europium and terbium at lower concentrations than magnet scrap.
- Alloys:Nickel-metal hydride battery waste and master alloy trimmings from magnet manufacturing generate mixed rare earth streams requiring extended solvent extraction trains.
Magnets dominate installed base. Catalysts is where expansion concentrates.
End User:
Cost tier segmentation separates defense-aerospace buyers paying qualification premiums from automotive OEMs optimizing unit economics at scale.
- Electronics:Hard disk drive decommissioning from data centers in Virginia and Frankfurt generates concentrated neodymium-iron-boron feedstock with documented chain of custody. Tier-1 magnet suppliers in Japan now contract directly with decommissioning firms rather than spot markets.
- Automotive:Electric vehicle motor production in Germany and South Korea is consuming recycled NdPr oxides as virgin concentrate shortages extend lead times. The EU Critical Raw Materials Act is forcing 15% recycled content benchmarks by decade end.
- Aerospace:Samarium-cobalt magnet remanufacturing for jet engine applications requires 99.5% purity certification cycles lasting 18-24 months with US Department of Defense contractors.
- Renewable Energy:Wind turbine decommissioning in Denmark and Germany is releasing blade-mounted magnet assemblies at predictable volumes for the first time.
Electronics channels the highest volume flows. Automotive is climbing the fastest.
Technology:
Volume concentration favors hydrometallurgical circuits, though margin pools are fragmenting as acid costs and tailings liability reshape project economics.
- Hydrometallurgical:Sulfuric acid leaching followed by solvent extraction achieves 99.5% purity grades required for magnet remanufacturing. German facilities are segregating European-origin scrap to maintain REACH compliance for organophosphorus extractants.
- Bioleaching:Acidithiobacillus ferrooxidans strains achieve 85% rare earth recovery from slag at pH levels below conventional acid requirements. Danish wind turbine contractors are piloting these circuits for blade magnet recovery.
- Pyrometallurgical:High-temperature smelting remains capital-intensive with declining investment relative to hydrometallurgical builds.
- Mechanical Separation:Automated disassembly and sorting of hard disk drives anchors feedstock preparation but carries limited technology upside.
Hydrometallurgical dominates installed base. Bioleaching is gaining share fastest.
Application:
Customer type segmentation separates defense-procured medical device magnet supply from consumer electronics spot market volatility.
- Electric Vehicles:Traction motor NdFeB specifications require consistent rare earth ratios that recycled oxide streams now achieve. Automotive Tier-1 suppliers in Germany and Japan are locking scrap supply agreements 3-5 years forward.
- Wind Turbines:Direct-drive generators consume 600kg plus NdFeB per megawatt. Decommissioning protocols in Denmark are generating the first predictable magnet scrap streams from 1990s turbine retirements.
- Consumer Electronics:Smartphone and laptop miniaturization is reducing rare earth content per unit even as retirement volumes climb.
- Medical Devices:MRI magnet recycling requires specialized handling for helium-depleted superconducting coils, limiting processor options to qualified facilities in Japan and Germany.
Electric Vehicles dominates installed base. Wind Turbines is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan consume recycled rare earths primarily for automotive magnet remanufacturing, while the United States channels material through defense stockpile programs. China dominates processing throughput but relies less on recycling for domestic supply security. This consumption-mix differential shapes facility siting and offtake contracting across major economies.
United States
Defense procurement from the Department of Defense and EPA-coordinated stockpile releases anchor domestic demand. The Inflation Reduction Act subsidizes domestic rare earth separation infrastructure. Mountain Pass, California hosts the only integrated rare earth mining and processing facility in North America, with adjacent recycling capacity under development.
Germany
Automotive OEMs in Stuttgart and Munich contract directly for qualified magnet scrap to meet electric vehicle production schedules. The EU Critical Raw Materials Act imposes binding recycled content thresholds. La Rochelle, France adjacent facilities and German hydrometallurgical plants in North Rhine-Westphalia process European-origin scrap to maintain REACH compliance.
Japan
METI-subsidized urban mining networks generate high-purity feedstock from consumer electronics retirement. Aerospace magnet remanufacturing for jet engine applications requires 18-24 month qualification cycles. Osaka and Nagoya industrial clusters concentrate automated disassembly and solvent extraction expertise.
China
Export license controls on rare earth processing technology constrain Western facility development. Domestic recyclers serve battery and magnet manufacturers in the Yangtze River Delta. Jiangxi and Inner Mongolia host pyrometallurgical operations with limited hydrometallurgical expansion.
Denmark
Wind turbine decommissioning from 1990s installations releases the first predictable blade magnet scrap streams in Europe. Bioleaching pilots using Acidithiobacillus ferrooxidans strains process low-grade slag at reduced acid consumption. Copenhagen-area contractors coordinate directly with German hydrometallurgical facilities for downstream refining.
Rare Earth Elements Recycling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital requirements for solvent extraction circuits creating natural segmentation. The upper tier controls Mountain Pass extraction infrastructure and European chemical refining complexes. Mid-scale urban mining operators concentrate in Japan and Germany with proprietary scrap-sorting technologies. Competitive moves center on long-term offtake contracting with automotive Tier-1 suppliers and technology licensing for automated disassembly systems.
Within the integrated extraction-to-magnet tier, MP Materials Corp. and Solvay S.A. anchor Western supply chain positioning through captive infrastructure. Mitsubishi Materials Corporation exemplifies the urban mining specialist archetype with Japanese consumer electronics collection networks. Neo Performance Materials occupies a bridging position between chemical separation and magnet alloy manufacturing. These three entities represent the dominant geographic and functional configurations in the competitive set.
| Leading Market Players |
|---|
| MP Materials Corp. |
| Neo Performance Materials |
| Solvay S.A. |
| Geomega Resources Inc. |
| Mitsubishi Materials Corporation |
| Hitachi Metals |
| Energy Fuels Inc. |
| REEcycle Inc. |
| Umicore N.V. |
| Others |
Value Network & Pricing Analysis
Hydrometallurgical acid substitution for pyrometallurgical furnace processing is redrawing feedstock valuation geography while compressing margin structures across European and North American facilities. This chemistry pivot simultaneously elevates sulfuric acid procurement costs in Germany and reduces energy-intensive smelting premiums that previously anchored Chinese concentrate pricing benchmarks.
Pricing Analysis
Long-term offtake contracts now dominate qualified magnet scrap procurement, with automotive Tier-1 suppliers in Stuttgart and Nagoya locking three-to-five-year supply agreements at premiums to spot oxide markets. Price differentiation hinges on REACH-compliant certification grades and documented chain-of-custody provenance for defense-aerospace buyers. Cost compression in standard-grade electronics scrap is intensifying because acid reagent volatility erodes hydrometallurgical circuit economics. Defense stockpile programs exhibit least price sensitivity, while consumer electronics spot traders face margin pressure from Chinese concentrate pricing tethering.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for German hydrometallurgical facilities sourcing feedstock from Japanese urban mining networks. Supply concentration centers on China for rare earth oxide pricing benchmarks, Germany for automotive magnet remanufacturing, and Japan for high-purity scrap collection infrastructure. Raw material dependencies encompass sulfuric acid reagents, organophosphorus extractants, and specialized membrane filtration systems. Single-source vulnerability from Chinese export license controls on rare earth processing technology constrains Western facility development. Distribution runs through direct contracting between data center decommissioning firms and magnet alloy manufacturers, bypassing traditional mineral traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and technology pathways is creating defendable niches as the EU Critical Raw Materials Act forces automotive OEMs to secure qualified scrap supply outside spot markets.
For Market Incumbents: Shield solvent extraction expertise through exclusive licensing of automated hard disk drive disassembly technologies, denying mid-scale entrants access to concentrated neodymium-iron-boron feedstock. Anchor capacity expansion in North Rhine-Westphalia to capture EU recycled content mandates while Chinese export controls constrain competitor facility development. For New Entrants and Emerging Players: Certification fast-track through aerospace-qualified samarium-cobalt magnet remanufacturing opens premium margin pools with 18-24 month qualification cycles that deter incumbent resource reallocation. Target Danish wind turbine decommissioning contractors for bioleaching pilot partnerships, leveraging Acidithiobacillus ferrooxidans strains to process sub-10% rare earth content slag at reduced acid consumption. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors hydrometallurgical circuit operators with captive acid supply agreements and REACH-compliant reagent substitution capabilities. Long-term viability over the next decade rests on defense procurement diversification and automotive electrification pull-through. Monitor Chinese export license regime adjustments as the primary inflection indicator for Western facility economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Production | Solvay's La Rochelle complex secures captive sulfuric acid supply for rare earth separation circuits. |
| Long-term Magnet Scrap Supply Agreement | German automotive Tier-1 suppliers contract directly with Frankfurt data center decommissioning firms. |
| Bioleaching Technology Licensing | Danish wind contractors pilot bacterial lixiviant methods for blade magnet recovery at reduced tailings cost. |
| Defense Stockpile Procurement Contract | US Department of Defense channels premium-priced offtake outside volatile commercial oxide markets. |
| REACH-Compliant Reagent Substitution | German facilities segregate European-origin scrap to maintain ECHA Annex XIV authorization for extractants. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hydrometallurgical plant managers, automotive Tier-1 procurement leads, defense stockpile contracting officers, and solvent extraction R&D directors; alongside secondary validation through SEC filings from integrated rare earth operators, ECHA REACH authorization databases, METI urban mining subsidy disclosures, and USGS mineral commodity summaries. Bottom-up feedstock volume estimates from data center decommissioning protocols were triangulated against top-down magnet alloy demand projections from electric vehicle traction motor specifications.
Across the projection horizon, the analytical framework modeled segmentation across product type, end-use industry, technology pathway, and geographic regulatory cluster. CAGRs were derived from supply-demand balance assessments incorporating virgin concentrate expansion timelines against end-of-life electronics retirement curves. Forecast inputs encompassed acid reagent cost volatility indices and EU Critical Raw Materials Act compliance trajectory assumptions.
Underlying assumptions cover sustained defense procurement prioritization and automotive electrification penetration rates, with deviation risk concentrated in Chinese export license regime adjustments and REACH reagent authorization timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Selenium Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Diamond Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Beryllium Hydroxide Market