
 Europe Water Treatment Chemicals Market | 2026-2036
Europe Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Treatment Chemicals Market Analysis
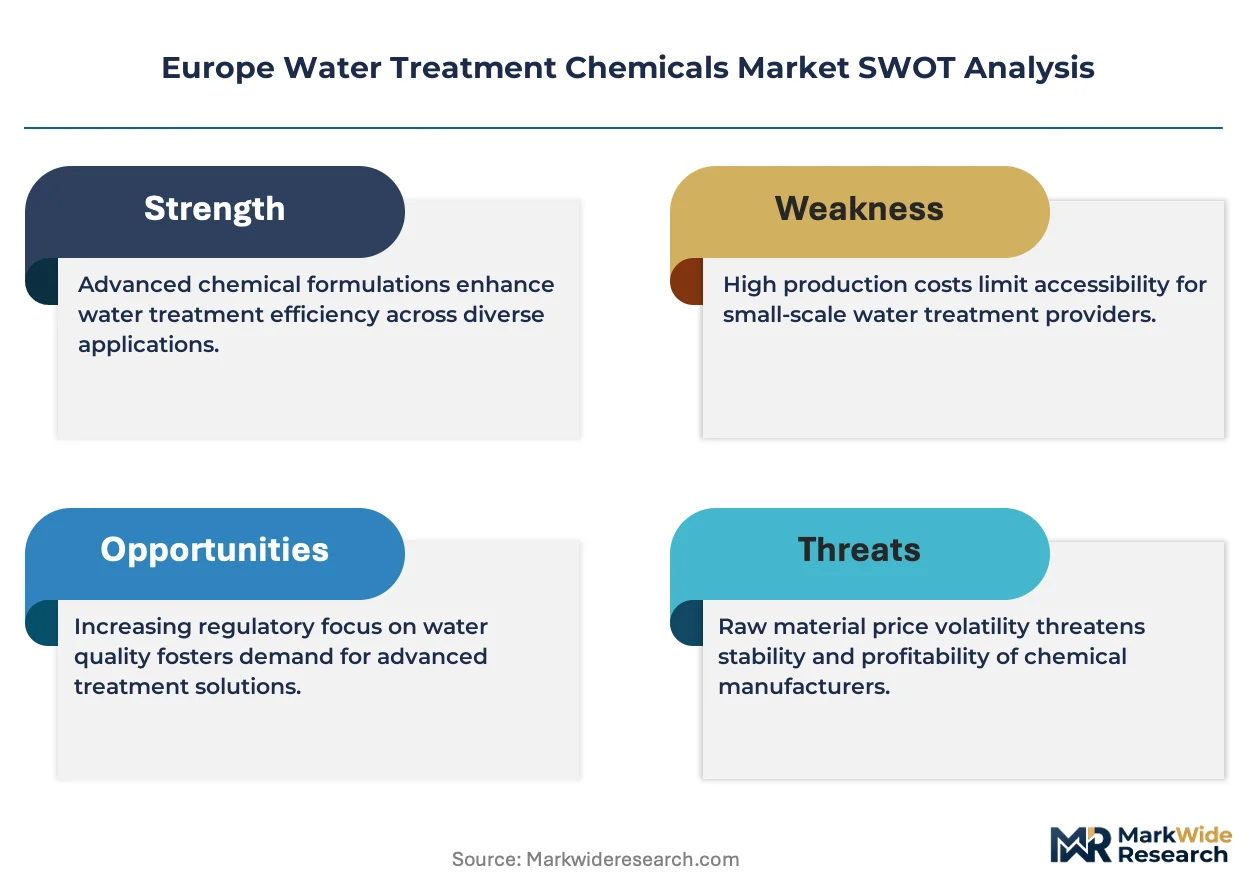
REACH compliance is decoupling commodity chemical suppliers from premium contract positions across European water treatment markets. Solenis leverages backward integration into polymer manufacturing to sustain margin stability under tightening registration requirements. Kemira anchors its position through specialized aluminum-based coagulant formulations tailored to Nordic surface water chemistries.
Water treatment chemicals comprise formulated active ingredients including polyacrylamide flocculants, chlorine-based disinfectants, and sulfuric acid pH adjusters, dosed at parts-per-million to parts-per-billion concentrations depending on turbidity and microbial load targets. Municipal water treatment applications dominate volume consumption, while membrane filtration-compatible antiscalants command premium pricing in desalination and industrial reuse installations. Chemical processing end users represent the fastest-growing demand pool, driven by zero-liquid-discharge mandates and internal recycling targets.
EMA and ECHA jointly shape product authorization pathways, with the F-Gas Regulation additionally constraining refrigerant-based cooling water chemistries in power generation. The EU Drinking Water Directive revision forces reformulation of legacy biocides and coagulant aids. Stakeholders must monitor delegated acts on endocrine disruptor thresholds and per- and polyfluoroalkyl substance restrictions to anticipate portfolio obsolescence risks.
Market Dynamics
REACH registration deadlines are forcing commodity biocide suppliers to surrender premium municipal contracts to specialized polymer formulators with captive manufacturing assets.
Growth Catalysts
- EU Drinking Water Directive revision:Tightened purity thresholds for endocrine disruptors and PFAS compounds are mandating coagulant reformulation across German and French municipal utilities.
- Zero-liquid-discharge mandates:Chemical processing plants in the Rhine-Ruhr corridor are expanding antiscalant procurement for closed-loop cooling systems.
- Membrane filtration expansion:Desalination installations in Spain and Italy require compatible biocides with reduced oxidant demand, creating specification premiums.
Market Restraints
- Feedstock volatility:Acrylic acid and acrylamide monomer prices fluctuate with crude oil indices, compressing margins for polyacrylamide flocculant producers.
- Registration concentration:Only ECHA-registered suppliers can serve Dutch and Belgian municipal markets, excluding smaller formulators lacking dossier resources.
- Technical substitution:UV-C and ozone systems displace chlorine-based disinfection in Scandinavian surface water treatment, eroding volume demand.
Strategic Opportunities
- Polish industrial corridor:Power generation and steel processing clusters around Katowice remain underpenetrated for specialized corrosion inhibitors.
- Digital dosing integration:IoT-enabled chemical feed systems combine with predictive turbidity algorithms to create bundled service offerings.
- F-Gas Regulation phase-down:Refrigerant-based cooling water chemistry faces forced transition, opening markets for ammonia-compatible biocide formulations.
Industry Challenges
- REACH dossier maintenance:ECHA substance evaluation timelines extend 18-24 months, freezing product portfolio decisions and R&D allocation.
- Legacy infrastructure retrofit:Victorian-era water treatment works in northern England require chemical feed system upgrades incompatible with modern polymer viscosities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Treatment Chemicals Market |
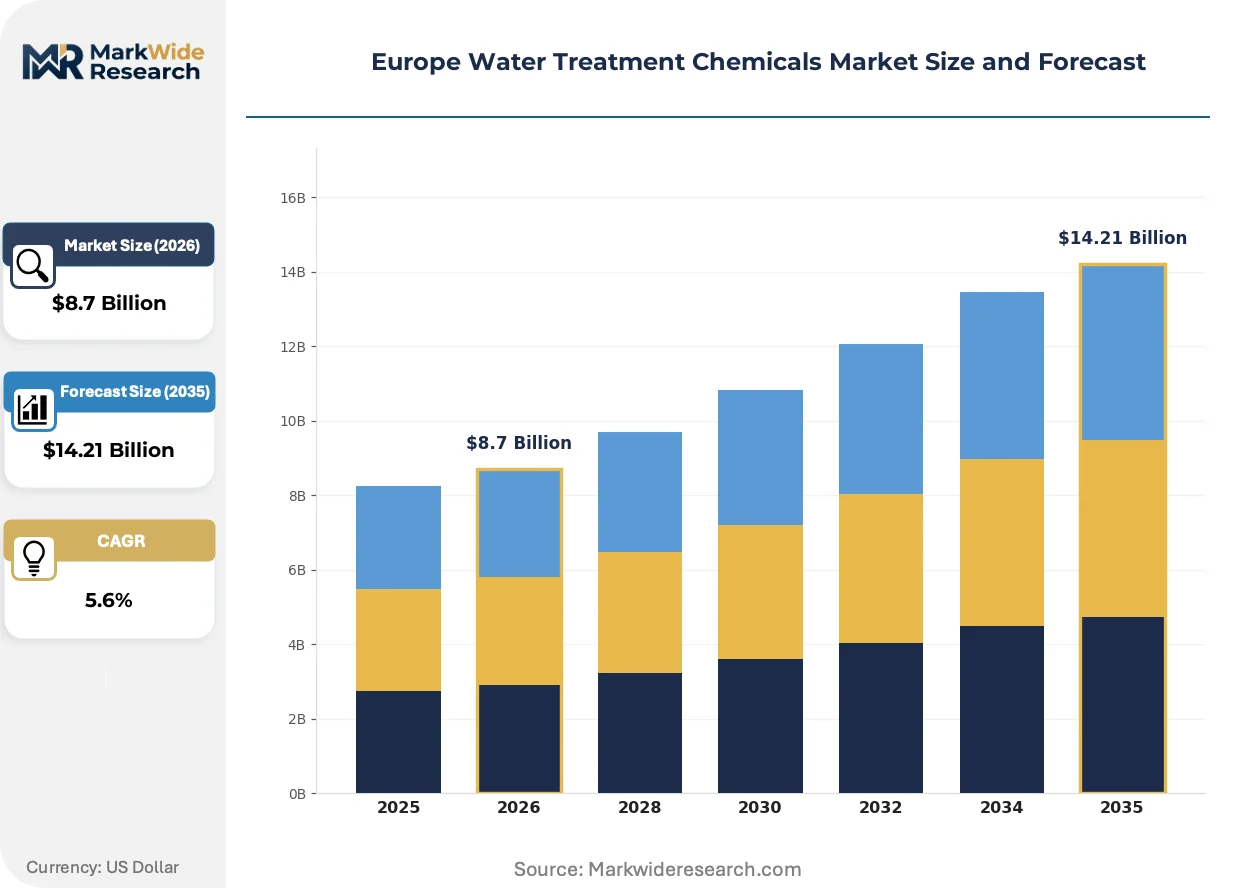
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Control Agents Application: Municipal Water Treatment, Industrial Water Treatment, Wastewater Treatment, Aquaculture End User: Water Utilities, Manufacturing Plants, Chemical Processing, Power Generation Technology: Membrane Filtration, Biological Treatment, Chemical Treatment, Physical Treatment |
| Companies Covered | Solenis, SUEZ SA, BASF SE, Kurita Water Industries Ltd., SNF Floerger, Kemira, Veolia, Nouryon, Ecolab, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Treatment Chemicals Market Emerging Trajectories
Electrochemical generation technologies and bio-based polymer feedstocks are compressing traditional chemical supply chains while regulatory pressure on halogenated biocides accelerates formulation turnover.
On-site electrochlorination systems are decentralizing sodium hypochlorite supply for coastal desalination plants. Spanish and Italian operators adopt modular cells to eliminate hazardous material transport from centralized chlor-alkali facilities. This shift compresses merchant chemical volumes while raising service contract attachment rates for electrode maintenance and brine management.
REACH authorization lists are expanding endocrine disruptor scrutiny to brominated and iodinated biocides. Industrial cooling tower operators face reformulation deadlines without drop-in chemical alternatives. German power generators are piloting quaternary ammonium compounds and stabilized chlorine dioxide as oxidation-compatible substitutes.
Performance-based chemical management contracts now dominate procurement for large municipal utilities in France and the Netherlands. Water quality outcomes replace tonnage-based purchasing, transferring dosing optimization risk to supplier engineers. Dutch regional water authorities have pioneered this model, with German utilities adopting adapted frameworks through 2024-2025 tender cycles.
Europe Water Treatment Chemicals Market Segmentation
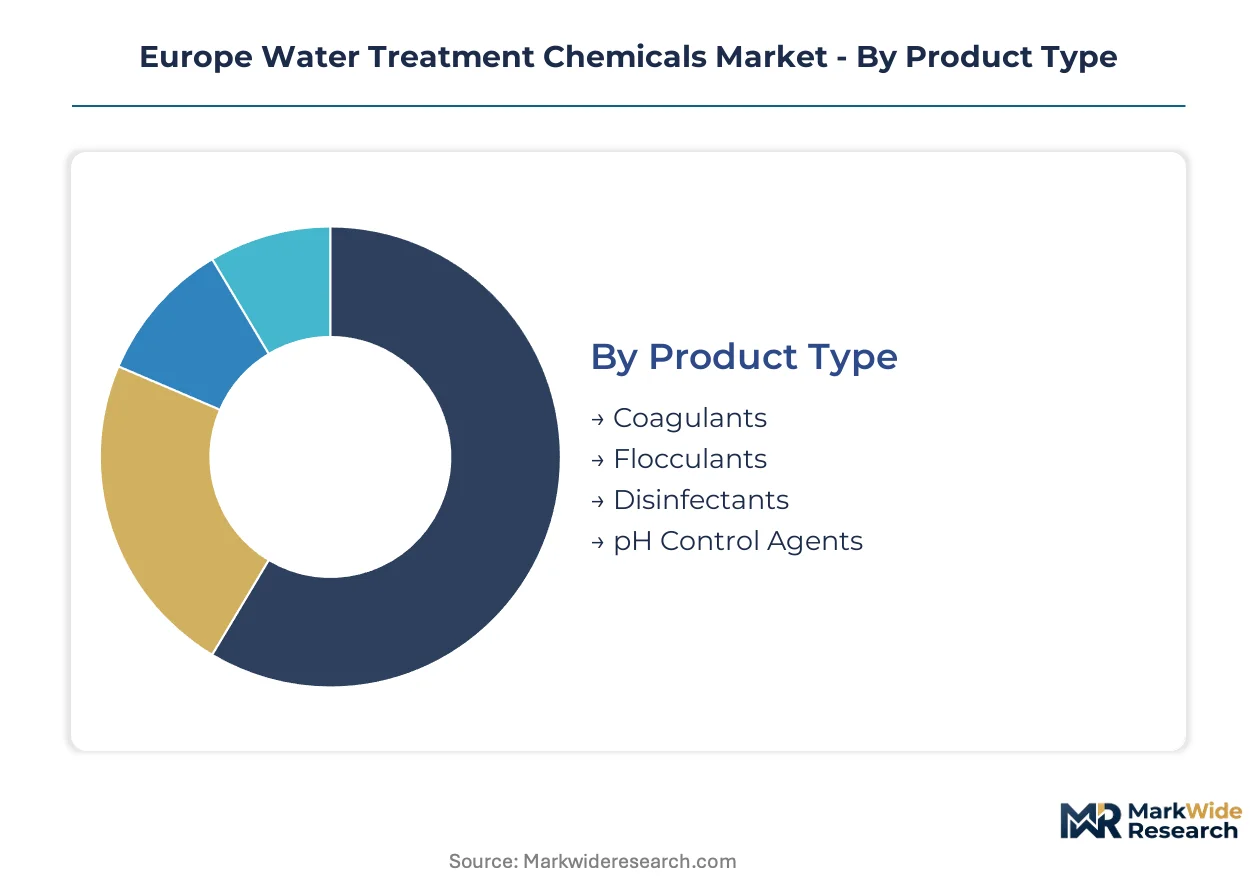
Water treatment chemical procurement patterns diverge sharply across end-use contexts. Municipal utilities prioritize regulatory compliance and bulk volume efficiency, while industrial operators demand application-specific formulations for closed-loop systems.
Product Type:
Replacement cycles for legacy formulations accelerate under REACH substance evaluation timelines.
- Coagulants:Aluminum sulfate and polyaluminum chloride formulations precipitate suspended solids from raw surface water. German municipal utilities in the Rhine-Ruhr corridor dominate procurement volumes as ECHA tightens residual aluminum thresholds in finished water.
- Flocculants:High-molecular-weight polyacrylamide polymers bridge destabilized particles into settleable flocs. Membrane filtration pre-treatment stages in Spanish desalination plants drive specification premiums for low-ionic-strength grades compatible with reverse osmosis modules.
- Disinfectants:Chlorine-based oxidants, chlorine dioxide, and peracetic acid formulations control microbial loading. Dutch surface water treatment works favor chloramine residuals for distribution system stability.
- pH Control Agents:Sulfuric acid, caustic soda, and carbon dioxide adjust alkalinity for coagulation optimization and corrosion control. Power generation cooling circuits in Poland consume bulk volumes for scaling prevention.
Volume placements concentrate in coagulants; the faster expansion belongs to flocculants.
Application:
Cost tier separation distinguishes commodity bulk treatment from premium specialized installations.
- Municipal Water Treatment:Surface water and groundwater purification for potable supply. French regional water authorities are consolidating procurement through performance-based management contracts that transfer dosing risk to chemical suppliers.
- Industrial Water Treatment:Process water conditioning for manufacturing and energy production. Zero-liquid-discharge mandates at chemical processing clusters in the Netherlands are expanding antiscalant demand for evaporative crystallizer trains.
- Wastewater Treatment:Effluent polishing and nutrient removal before environmental discharge. Italian industrial zones face tightened COD discharge limits under EU Urban Wastewater Treatment Directive revisions.
- Aquaculture:Disinfection and oxygenation for intensive fish farming operations. Norwegian salmon producers are displacing formaldehyde-based therapeutants with peracetic acid alternatives under veterinary prescription requirements.
Municipal applications anchor volume demand; industrial water treatment climbs the fastest as manufacturing recycling targets tighten.
End User:
Customer type determines specification stringency and contract structure variation across the value chain.
- Water Utilities:Public and private entities managing municipal supply and sanitation networks. Tender frameworks in Belgium and the Netherlands restrict eligible suppliers to ECHA-registered formulators with complete substance dossiers.
- Manufacturing Plants:Food and beverage, pharmaceutical, and electronics producers requiring process water purity. Semiconductor fabrication facilities in Germany's Saxony cluster demand ultrapure water chemistries with part-per-trillion contaminant specifications.
- Chemical Processing:Petrochemical and specialty chemical producers with complex effluent streams. Internal recycling targets at Rhine-Ruhr corridor plants are expanding demand for corrosion inhibitors compatible with high-salinity recirculating loops.
- Power Generation:Thermal and nuclear facilities managing cooling water chemistry. The F-Gas Regulation phase-down is forcing transition from refrigerant-based cooling tower treatments to ammonia-compatible biocide formulations at German lignite plants.
Water utilities command the largest tonnage placements; chemical processing end users are expanding most quickly under circular economy mandates.
Technology:
Process maturity separates established chemical dosing from emerging physical and biological alternatives.
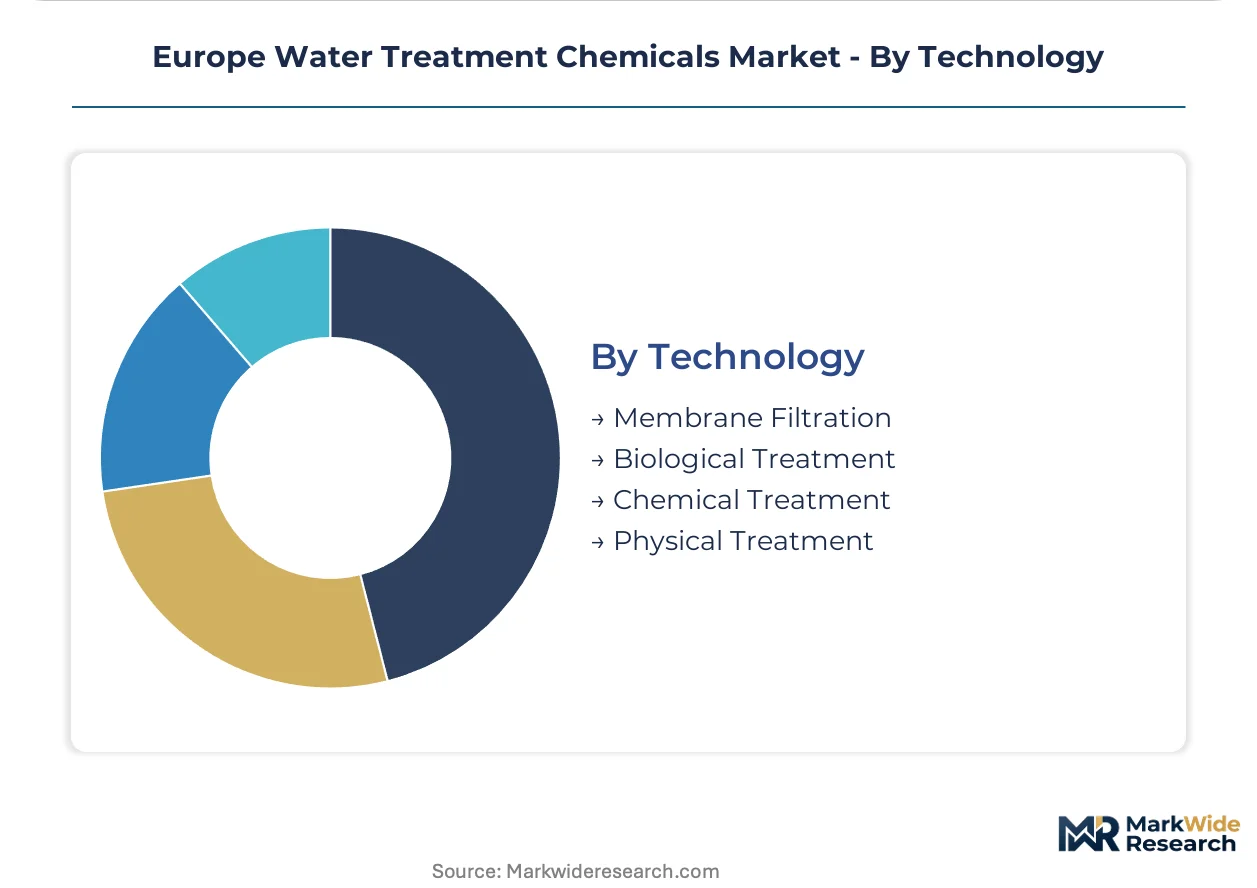
- Membrane Filtration:Reverse osmosis, nanofiltration, and ultrafiltration systems requiring compatible pretreatment chemistries. Spanish Mediterranean desalination operators specify low-fouling antiscalants for seawater reverse osmosis trains.
- Biological Treatment:Activated sludge, biofilm reactors, and constructed wetlands reducing organic loading. Nutrient removal requirements in Danish wastewater treatment works are expanding carbon source dosing for denitrification enhancement.
- Chemical Treatment:Conventional coagulation, flocculation, and disinfection processes. Victorian-era infrastructure in northern England constrains polymer viscosity specifications for legacy feed equipment compatibility.
- Physical Treatment:Sedimentation, filtration, and adsorption without chemical transformation. Activated carbon replacement cycles for micropollutant removal are extending under EU Drinking Water Directive revision cost recovery negotiations.
Chemical treatment retains the dominant volume position; membrane filtration gains share fastest as desalination capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's chemical processing cluster concentrates procurement volumes for scale inhibitors and biocides across northwestern Europe.
Germany
Rhine-Ruhr power generation and chemical processing plants drive antiscalant demand under zero-liquid-discharge mandates. ECHA substance evaluation timelines extend 18-24 months for REACH dossier maintenance. Bavarian semiconductor fabrication facilities in the Saxony cluster demand ultrapure water chemistries with part-per-trillion contaminant specifications.
France
French regional water authorities consolidate procurement through performance-based management contracts transferring dosing risk to suppliers. The EU Drinking Water Directive revision tightens purity thresholds for endocrine disruptors. Île-de-France municipal utilities expand coagulant reformulation for surface water treatment.
Netherlands
Dutch regional water authorities pioneered outcome-based chemical management contracts now adopted by German utilities. Tender frameworks restrict eligible suppliers to ECHA-registered formulators with complete substance dossiers. Rotterdam's chemical processing clusters expand evaporative crystallizer antiscalant procurement under circular economy mandates.
Spain
Spanish Mediterranean desalination operators specify low-fouling antiscalants for seawater reverse osmosis trains. Modular on-site electrochlorination systems compress merchant chemical volumes while raising service contract attachment rates. Catalonian coastal plants adopt electrochemical generation to eliminate hazardous material transport.
Poland
Polish power generation and steel processing clusters around Katowice remain underpenetrated for specialized corrosion inhibitors. Bulk sulfuric acid consumption dominates pH control for cooling circuits. The industrial corridor's internal recycling targets expand demand for high-salinity compatible formulations.
Europe Water Treatment Chemicals Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base organizes around captive manufacturing assets versus toll-formulation dependencies. Three archetypes dominate: backward-integrated polymer producers with REACH registration autonomy, regional toll blenders serving municipal spot markets, and electrochemical technology licensors bundling hardware with chemical supply. Consolidation pressures favor M&A among mid-cap formulators lacking dossier resources, while capacity expansion concentrates in polymer manufacturing to secure feedstock stability.
Within the integrated-formulator tier, Solenis exemplifies backward integration into polymer manufacturing sustaining margin stability under tightening registration requirements. Kemira anchors specialized aluminum-based coagulant positions tailored to Nordic surface water chemistries. SNF Floerger occupies the high-molecular-weight polyacrylamide segment where membrane filtration compatibility commands specification premiums.
| Leading Market Players |
|---|
| Solenis |
| SUEZ SA |
| BASF SE |
| Kurita Water Industries Ltd. |
| SNF Floerger |
| Kemira |
| Veolia |
| Nouryon |
| Ecolab |
| Others |
Supply Flow & Price Mechanics
Acrylic acid and acrylamide monomer costs cascade from petrochemical feedstocks through polyacrylamide flocculant pricing tiers, compressing margins for toll-blenders lacking captive polymer manufacturing while rewarding backward-integrated formulators with supply security.
Pricing Analysis
Lead-time premiums separate municipal utilities demanding 48-hour emergency delivery from industrial buyers accepting 4-week contracted schedules. Three-tier pricing structure across premium, standard, and economy levels reflects REACH registration status, with ECHA-registered suppliers commanding 15-20% spreads over unregistered spot vendors. Pricing pressure stems from feedstock volatility linked to crude oil indices, particularly affecting polyacrylamide producers. Municipal water utilities exhibit highest price sensitivity due to fixed budget cycles, while semiconductor fabrication facilities in Germany's Saxony cluster accept premium positioning for part-per-trillion purity specifications.
Supply Chain Analysis
Dual-sourcing mandates from Dutch and Belgian regional water authorities require qualified suppliers to maintain manufacturing redundancy across Germany, France, and the Netherlands. Raw material dependencies center on acrylic acid monomers, aluminum hydroxide feedstocks, and sulfuric acid precursors. Supply chain risk concentrates in ECHA registration concentration, where single-dossier dependencies freeze supplier qualification for 18-24 month evaluation windows. Distribution runs through regional blending facilities serving municipal spot markets alongside direct-to-plant bulk delivery for industrial offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races where polymer manufacturing control separates premium contract winners from margin-squeezed toll-blenders, with REACH registration autonomy as the decisive upstream lever.
For Market Incumbents: Deepen captive polymer manufacturing capacity in the Rhine-Ruhr corridor to defend municipal contract positions against emerging electrochlorination system providers. Acquire mid-cap formulators lacking ECHA dossier resources before REACH evaluation timelines freeze portfolio decisions. Prioritize backward integration into acrylamide monomer production to buffer margin compression from crude oil-linked feedstock volatility. For New Entrants and Emerging Players: The price-point gap between premium REACH-registered formulators and economy toll-blenders opens white-space in Poland's Katowice industrial corridor, where power generation and steel processing clusters remain underpenetrated for specialized corrosion inhibitors. Target digital dosing integration partnerships with municipal utilities adopting IoT-enabled chemical feed systems. Enter through performance-based management contract structures pioneered by Dutch regional water authorities. For Investors and Strategic Acquirers: ECHA substance evaluation timeline extensions are the leading indicator that registration-constrained supply will tighten, favoring acquirers of dossier-complete mid-cap specialists over greenfield capacity builds. Frame 5-10 year viability around circular economy mandate acceleration in chemical processing clusters. Monitor F-Gas Regulation phase-down implementation at German lignite plants as the signal for ammonia-compatible biocide formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Solenis exemplifies margin stability under REACH tightening through captive acrylamide production. |
| Performance-Based Chemical Management Contracts | Dutch regional water authorities pioneered outcome-based procurement now adopted across German utilities. |
| Electrochemical Generation Technology Licensing | Spanish Mediterranean desalination operators adopt modular on-site electrochlorination to eliminate hazardous transport. |
| Specialized Coagulant Formulation Development | Kemira anchors position through aluminum-based chemistry tailored to Nordic surface water conditions. |
| Digital Dosing System Integration | IoT-enabled chemical feed systems combine with predictive turbidity algorithms for bundled service offerings. |
Methodological Framework
Trade data from Eurostat, customs declarations, and Cefic industry statistics formed the secondary backbone, cross-referenced with SEC 10-K filings and ECHA registration databases. Primary interviews with municipal procurement managers, chemical plant technical directors, polymer R&D leads, and distribution channel partners validated demand assumptions. Bottom-up volume estimates triangulated against top-down market sizing across coagulant, flocculant, and disinfectant product categories.
Historical trendline analysis established baseline growth patterns across municipal, industrial, and wastewater treatment applications. Segmentation modeling incorporated product type, end-use industry, technology compatibility, and regional regulatory cluster dimensions. CAGRs were derived from demand driver elasticity analysis and substitution threat assessment, with membrane filtration expansion rates and zero-liquid-discharge mandate adoption as key forecast inputs across the projection horizon.
Inputs from ECHA registration timelines and EU Drinking Water Directive delegated acts were available through the study window; gaps in real-time feedstock price volatility data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions on REACH compliance cost pass-through and electrochlorination substitution rates. Deviation in F-Gas Regulation phase-down enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market