
 Global Aluminum Alloys Market | 2026-2036
Global Aluminum Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Alloys Market Foresight
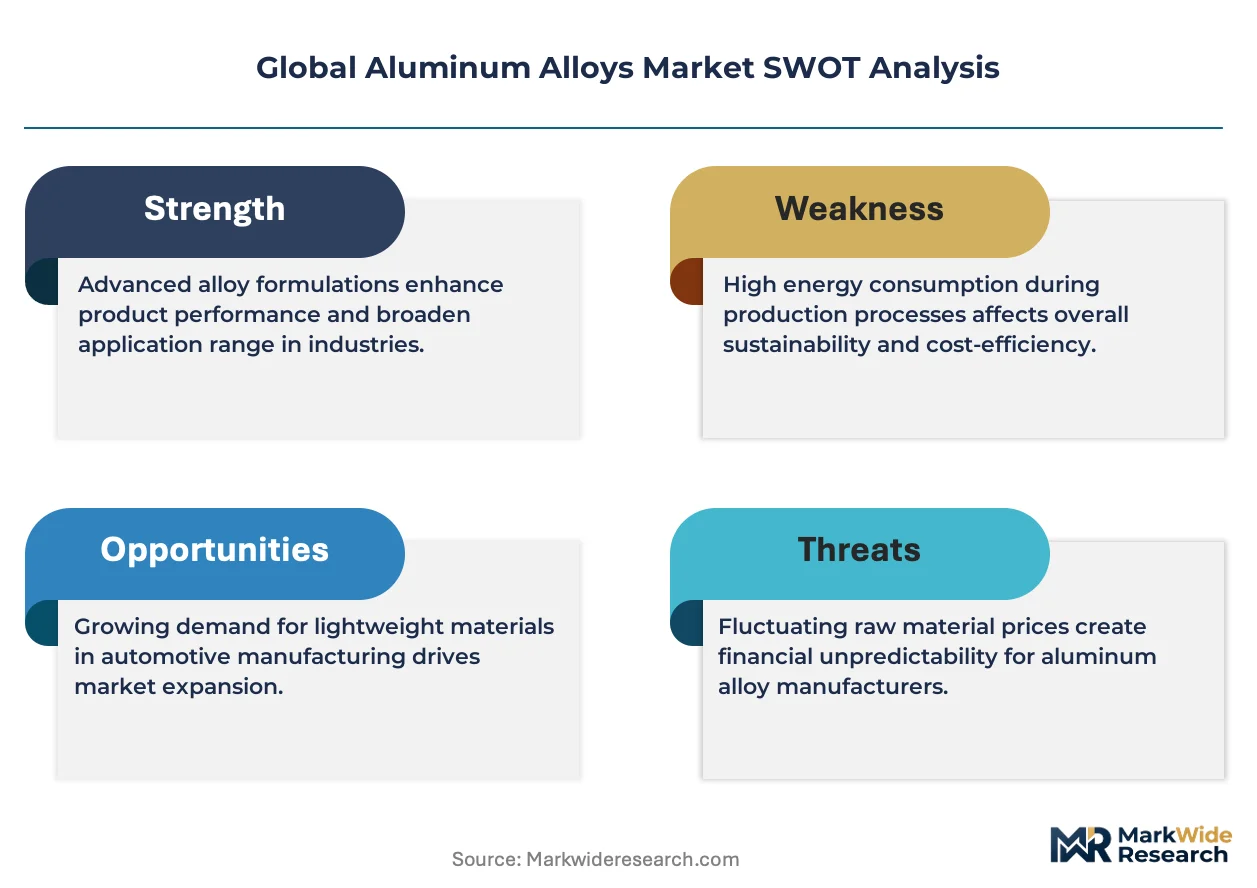
A capital-intensity divergence between integrated smelters and downstream fabricators is redrawing competitive boundaries in aluminum alloys. RusAL leverages captive bauxite and alumina assets across Siberian operations to sustain cost-advantaged primary metal output. Novelis anchors its position through in-house recycling infrastructure and closed-loop supply relationships with automotive and beverage customers. Hindalco Industries competes via backward integration into Indian bauxite mining and captive power generation.
Aluminum alloys are metallic materials composed primarily of aluminum combined with controlled additions of copper, magnesium, silicon, zinc, or manganese, engineered through processes such as heat treatment and cold rolling to achieve specific strength-to-weight ratios, corrosion resistance, and formability for industrial applications. Wrought alloys dominate volume flows into aerospace and transportation applications where fatigue resistance and ductility are specified, while casting alloys command margin pools in complex automotive powertrain components where near-net-shape capability reduces machining costs. Powder alloys occupy a smaller but strategically growing position in additive manufacturing feedstock for aerospace repair and prototyping applications.
The EPA enforces air quality standards that constrain secondary smelter permitting in the United States, while REACH and the EU Green Deal impose carbon-border adjustments and embodied emissions disclosure on aluminum imports into Europe. China's MEE enforces dual carbon goals that cap smelter energy intensity and redirect alloy production toward lower-carbon hydro-powered capacity. Stakeholders must monitor regulatory divergence between carbon-accounting frameworks to anticipate which alloy grades and production origins will face preferential or restricted market access.
Market Dynamics
State-backed smelter consolidation in China is compressing alloy supply availability while EU carbon-border adjustments force producers to requalify production origins for market access.
Growth Catalysts
- Aerospace wrought alloy procurement:Aircraft manufacturers are expanding specifications for fatigue-resistant alloys in airframe structures, pulling volume through heat-treatment capable mills.
- EU Green Deal embodied carbon thresholds:REACH compliance mandates are redirecting import flows toward hydro-powered primary aluminum sources with verifiable low-carbon credentials.
- Closed-loop automotive recycling:In-house recycling infrastructure investments are securing scrap supply chains for sheet alloy production serving electrified vehicle platforms.
Market Restraints
- Alumina input cost volatility:Bauxite refining capacity concentration in Guinea and Australia exposes alloy producers to freight and energy cost swings.
- Siberian supply concentration risk:Captive bauxite-to-metal integrated operations in specific regions create single-source dependency for high-purity primary grades.
- Steel substitution in construction:High-strength steel advances in structural applications constrain aluminum alloy penetration in cost-sensitive building segments.
Strategic Opportunities
- India captive power integration:Backward integration into coal and renewable generation assets offers cost-advantaged smelting capacity for export-grade alloy production.
- Additive manufacturing powder alloys:Aerospace repair and prototyping applications are creating premium-margin demand for gas-atomized alloy feedstock.
- US IRA clean energy incentives:Domestic content requirements for renewable energy infrastructure are stimulating localized alloy rolling and extrusion investments.
Industry Challenges
- Dual carbon compliance timelines:China's MEE energy intensity caps require simultaneous furnace upgrades and renewable power sourcing without disrupting alloy grade consistency.
- Scrap segregation and traceability:Closed-loop supply relationships demand metallurgical tracking systems that legacy ERP platforms cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Alloys Market |
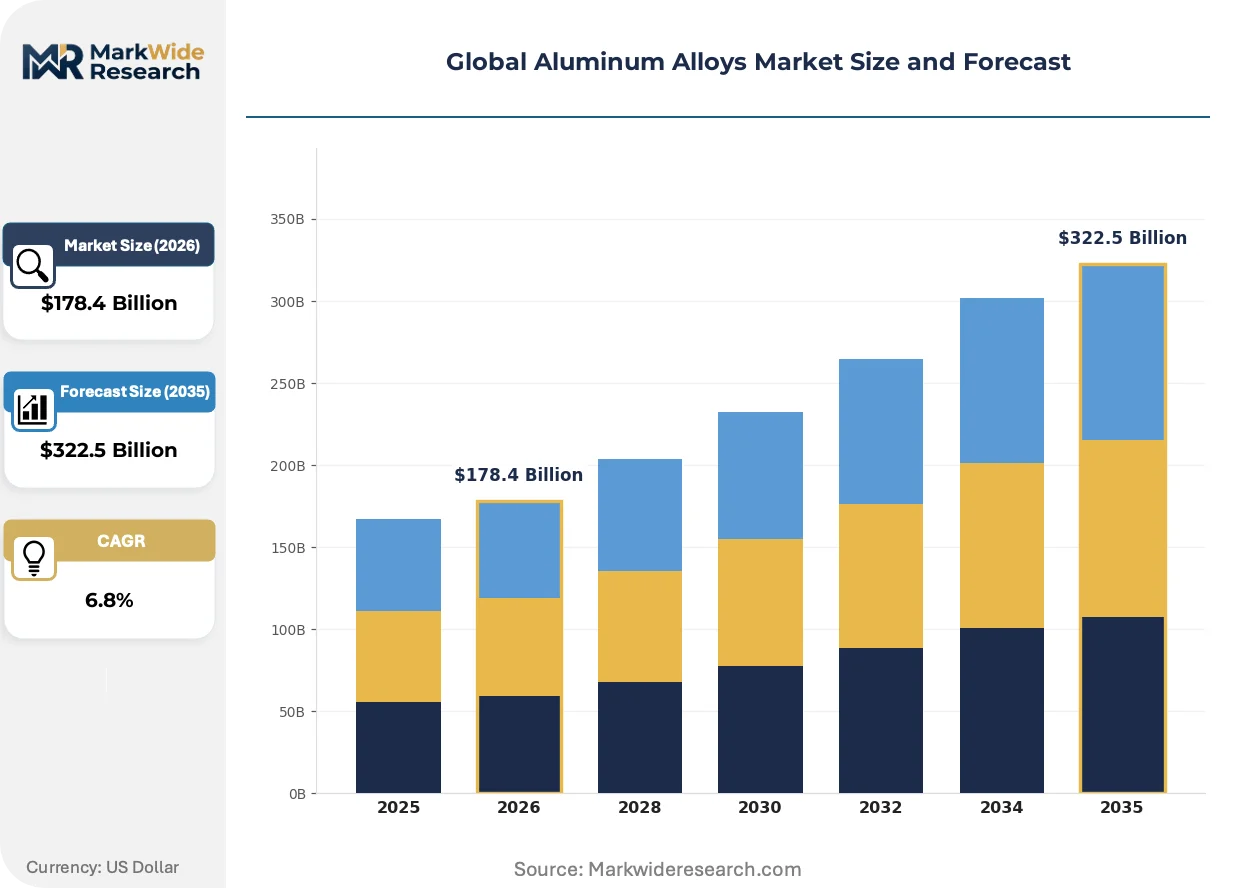
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $322.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrought Alloys, Casting Alloys, Powder Alloys, Fabricated Products Technology: Heat Treatment, Surface Coating, Metal Injection Molding, Cold Rolling Application: Aerospace Components, Construction Materials, Electrical Equipment, Consumer Electronics End User: Aircraft Manufacturers, Building Contractors, Electrical Manufacturers, Electronics Assemblers |
| Companies Covered | Alcoa Corporation, RusAL, Norsk Hydro ASA, Hindalco Industries, UACJ Corporation, Novelis, Aluminum Corporation of China, China Hongqiao Group, Constellium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Alloys Market Shifts & Advancements
Active developments across metallurgical processing, emissions accounting, and procurement models are restructuring how aluminum alloys are specified, sourced, and priced.
Scandium-bearing aluminum alloys are decomposing traditional strength-to-weight tradeoffs in aerospace and sporting goods applications. Tier-one airframers are qualifying these materials for wing rib and fuselage stringer applications at accelerated timelines. The technology is decomposing incumbent 7xxx series dominance in structural airframe segments by offering comparable specific strength with superior weldability and corrosion resistance.
REACH carbon-border adjustments are forcing alloy importers to document embodied emissions across bauxite mining, alumina refining, and smelting stages. European fabricators are now requiring supplier-specific Environmental Product Declarations before contract renewal. Automotive stamping operations in Germany and France are most affected, with several producers redirecting procurement toward Nordic and Canadian hydro-powered primary sources.
Direct mill-buyer contracting is displacing merchant distributor intermediaries in high-volume transportation sheet markets. Automotive OEMs in Michigan and Bavaria are negotiating multi-year tolling arrangements that specify alloy chemistry, gauge tolerances, and recycling content minimums. This pattern is most visible in battery enclosure and body-in-white applications where just-in-sequence delivery requirements favor integrated supply relationships over spot-market purchasing.
Global Aluminum Alloys Market Segmentation
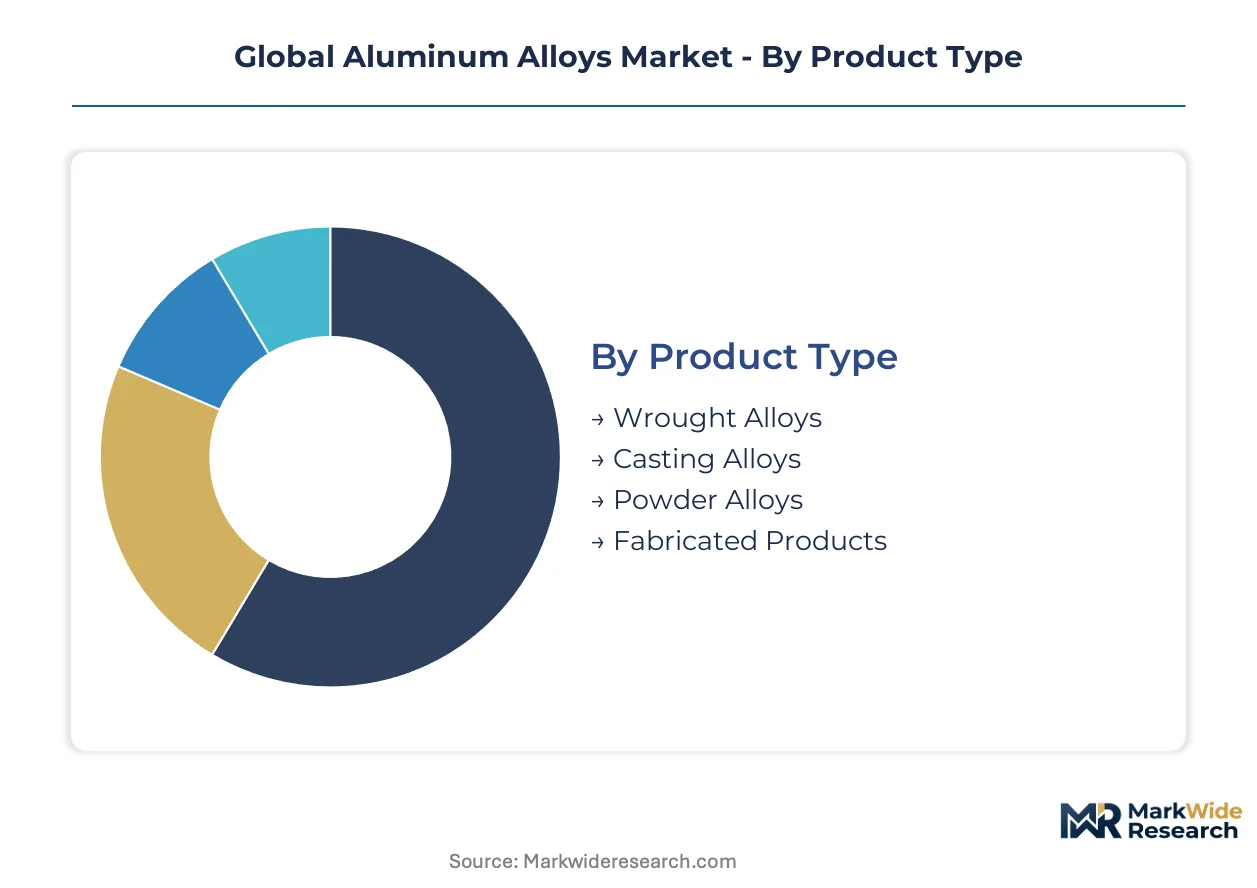
Aluminum alloy specifications diverge sharply across product forms and processing routes, with substitution dynamics from composites and high-strength steels pressuring certain segments harder than others. Understanding where technical differentiation protects margin pools versus where commoditization erodes pricing power shapes procurement strategy and capacity investment decisions.
Product Type:
Wrought alloys face the most acute substitution pressure from carbon fiber composites in aerospace primary structures, while casting alloys defend their position through near-net-shape economics that machining-intensive alternatives cannot match.
- Wrought Alloys:Metallurgically engineered through mechanical working and thermal processing to achieve directional strength properties and fatigue resistance. Aircraft manufacturers in Toulouse and Seattle are expanding procurement of 2xxx and 7xxx series plate and extrusion for wing and fuselage applications, though carbon fiber penetration into primary structures constrains volume growth in the highest-performance grades.
- Casting Alloys:Formed by pouring molten metal into molds to produce complex geometries with minimal post-processing. Automotive powertrain component demand in Stuttgart and Detroit anchors volume flows, where cylinder heads and transmission housings specify Al-Si-Cu formulations that machining from solid billet would render uneconomical.
- Powder Alloys:Gas-atomized feedstock for additive manufacturing and powder metallurgy applications.
- Fabricated Products:Welded, machined, or assembled components from semi-finished alloy forms.
Wrought alloys anchor the volume base while powder alloys gain share at the steepest rate.
Technology:
Processing technology selection tracks end-use performance requirements, with heat treatment commanding premium positioning in structural applications where strength-to-weight ratios are specified.
- Heat Treatment:Controlled thermal cycling to manipulate precipitation hardening and mechanical properties. Aerospace tier-one suppliers in Wichita and Hamburg require solution treatment and artificial aging protocols that meet AMS specifications for airframe fasteners and landing gear components.
- Cold Rolling:Room-temperature reduction to achieve precise gauge tolerances and surface finishes. Beverage can sheet producers in Davenport and Neuss rely on tandem mill configurations that deliver H19 temper material with sub-micron thickness control.
- Surface Coating:Anodizing, conversion coating, and protective layer deposition for corrosion resistance.
- Metal Injection Molding:Powder-based forming for small, complex components with tight dimensional tolerances.
Cold rolling dominates tonnage throughput while heat treatment captures the widest margin expansion.
Application:
Application segmentation reveals diverging carbon intensity pressures, with aerospace components facing the most stringent embodied emissions scrutiny under emerging procurement standards.
- Aerospace Components:Airframe structures, engine casings, and interior fittings subject to FAA and EASA certification requirements. Airbus and Boeing supply chains are requalifying alloy sources to meet EU Green Deal carbon-border documentation demands, redirecting procurement toward hydro-powered primary metal from Quebec and Norway.
- Construction Materials:Curtain wall systems, roofing, and structural extrusions for commercial buildings. High-strength steel advances in mid-rise framing have compressed aluminum penetration in cost-sensitive segments, though corrosion resistance maintains specification in coastal and chemical-exposure environments.
- Electrical Equipment:Busbar, conductor, and transformer winding applications.
- Consumer Electronics:Enclosures, heat sinks, and structural chassis for portable devices.
Construction materials anchor installed capacity utilization while aerospace components command the steepest price escalation.
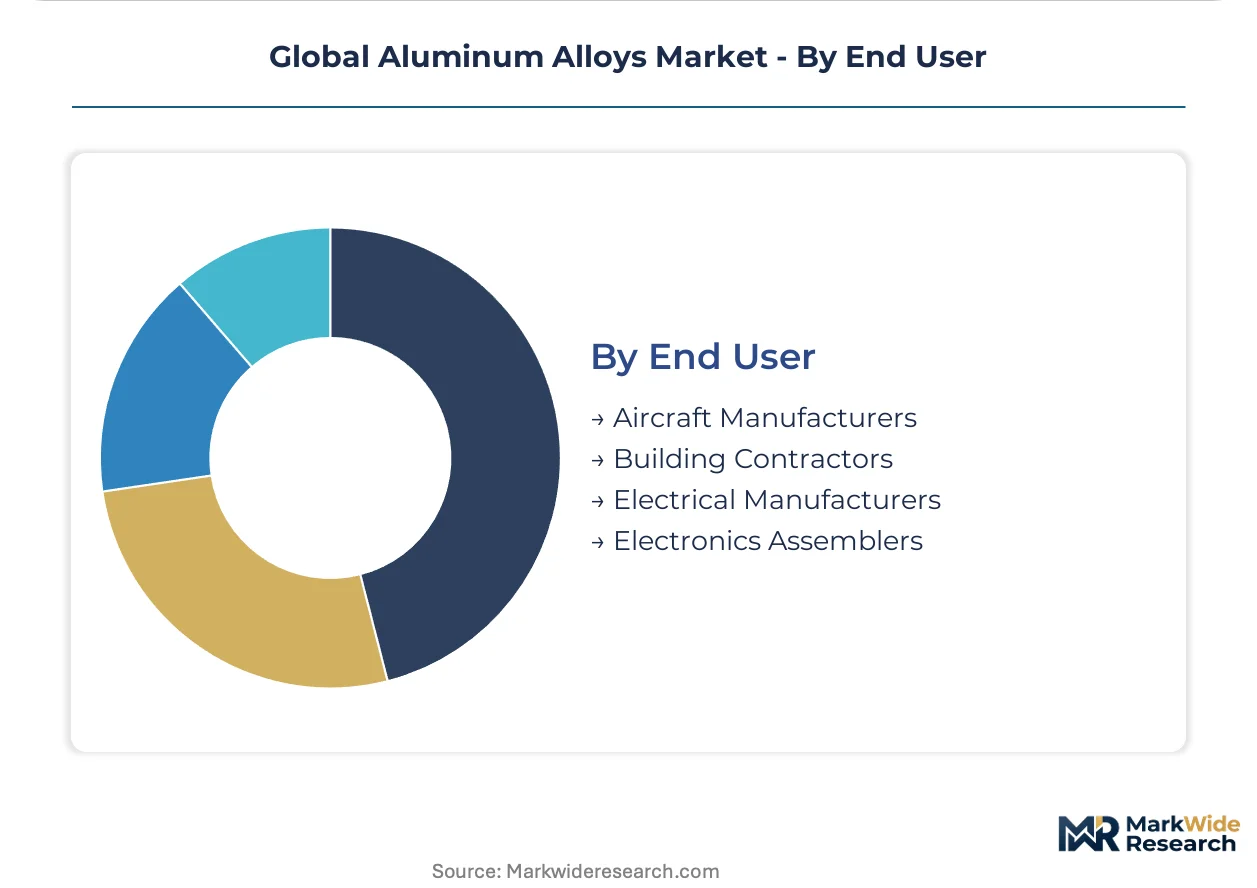
End User:
End user concentration patterns reflect diverging supply chain power, with aircraft manufacturers consolidating procurement through direct mill relationships while building contractors remain fragmented.
- Aircraft Manufacturers:Boeing, Airbus, and their tiered supply base specifying certified alloy grades with full metallurgical traceability. Multi-year tolling agreements with rolling mills in Koblenz and Ravenswood are displacing spot-market purchasing for high-volume wing skin and stringer applications.
- Electrical Manufacturers:Grid infrastructure and power distribution equipment producers. State Grid Corporation of China and ABB are expanding procurement of 1350 and 6201 alloys for transmission conductor and cable applications, with domestic content requirements under India's PLI scheme redirecting some sourcing toward Hindalco and Vedanta capacity.
- Building Contractors:Fragmented regional construction firms specifying standard extrusion and sheet products.
- Electronics Assemblers:Contract manufacturers sourcing precision-machined and surface-finished alloy components.
Electrical manufacturers anchor baseline demand stability while aircraft manufacturers drive the most aggressive qualification timelines for advanced alloy grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity to alumina input swings, while aerospace procurement teams in Germany and the United States prioritize metallurgical certification over unit cost differentials.
China
State-backed smelter consolidation under MEE dual carbon goals is redirecting alloy output toward hydro-powered capacity in Yunnan and Sichuan. The MEE enforces energy intensity caps that require simultaneous furnace upgrades without disrupting grade consistency. Chongqing and Chengdu clusters are absorbing displaced capacity from coal-dependent Shandong operations.
United States
Battery enclosure demand from Michigan automotive OEMs is stimulating localized rolling investments under IRA domestic content rules. The EPA constrains secondary smelter permitting through air quality standards that limit new capacity in the Ohio River Valley. Ravenswood, West Virginia maintains specialized aerospace plate capacity serving Boeing supply chains.
Germany
Automotive stamping operations in Stuttgart and Bavaria face acute pressure from REACH carbon-border adjustments requiring documented embodied emissions. The EU Green Deal forces requalification of primary aluminum sources toward Nordic hydro-powered origins. Koblenz rolling mills are negotiating multi-year tolling agreements that displace spot-market purchasing.
India
Grid infrastructure expansion by State Grid Corporation analogs is pulling 1350 and 6201 conductor alloys through Hindalco and Vedanta capacity. PLI scheme domestic content requirements redirect some sourcing from imports toward Odisha and Jharkhand smelter complexes. Captive coal and renewable generation assets offer cost-advantaged export-grade production.
Japan
Precision component demand from Kansai electronics assemblers specifies surface-finished alloy chassis with tight dimensional tolerances. METI industrial standards govern material certification for aerospace tier-two suppliers in Nagoya clusters. UACJ Corporation anchors domestic wrought alloy supply for automotive and electronics applications.
Global Aluminum Alloys Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated smelters commanding upstream margins and downstream fabricators capturing value through closed-loop recycling relationships. The vendor base organizes around three strategic archetypes: captive resource integrators with bauxite-to-metal control, tolling specialists with heat-treatment and rolling capabilities, and recycling-centric sheet producers serving beverage and automotive packaging. Consolidation pressure concentrates in Chinese state-backed capacity, while European and North American markets favor partnership-based supply relationships over merchant distribution.
Among integrated upstream operators, RusAL exemplifies the captive resource archetype through Siberian bauxite and alumina assets, while Hindalco Industries occupies a parallel position in Indian bauxite mining and captive power. Novelis represents the recycling-centric downstream model through in-house closed-loop infrastructure. Constellium and UACJ Corporation sit within the tolling and precision fabrication tier, serving aerospace and automotive qualification requirements.
| Leading Market Players |
|---|
| Alcoa Corporation |
| RusAL |
| Norsk Hydro ASA |
| Hindalco Industries |
| UACJ Corporation |
| Novelis |
| Aluminum Corporation of China |
| China Hongqiao Group |
| Constellium |
| Others |
Supply & Pricing Matrix
Sixty-day rolling inventory coverage in aerospace-grade wrought alloys signals supply-chain concentration around hydro-powered primary sources and validates premium pricing power for certified low-carbon grades. This lead-time band compresses further when RusAL and Norsk Hydro capacity faces logistics constraints, forcing automotive stampers toward spot-market premiums or qualified alternative origins.
Pricing Analysis
After-sales service contracts for heat-treatment and metallurgical certification anchor lifetime value in aerospace procurement relationships. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon-intensity documentation and AMS specification compliance. Pricing pressure stems from alumina input cost volatility out of Guinea and Australia, which compresses margins for non-integrated rolling mills. Automotive OEMs in Michigan exhibit acute price sensitivity to scrap aluminum spreads, while aircraft manufacturers in Toulouse prioritize certification continuity over unit cost differentials.
Supply Chain Analysis
Container availability constraints on the Guinea-China bauxite trade lane elevate inbound logistics costs for alumina refiners serving Asian alloy production. Supply concentrates in China, Russia, and Canada for primary metal, with secondary processing anchored in Germany, the United States, and Japan. Raw material flows draw from bauxite mining in Guinea and Australia, alumina refining in Shandong and Queensland, and smelting capacity in Yunnan and Siberia. Single-source vulnerability from Siberian high-purity grades creates structural risk for aerospace fastener specifications. Distribution runs through direct mill-buyer tolling agreements that displace merchant distributors in high-volume transportation sheet markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Aluminum Alloys Market tracks a cyclical recovery anchored to aerospace build-rate normalization and battery enclosure demand from electrified vehicle platforms.
For Market Incumbents: Shield margin pools by securing captive bauxite-to-metal integration or closed-loop recycling infrastructure that locks scrap supply chains against novel entrants. Carbon fiber composite substitution in primary airframe structures threatens 7xxx series volume; counter through scandium-bearing alloy qualification investments that decompose weldability tradeoffs. Backward integration into Indian captive power generation offers cost-advantaged export-grade positioning against Chinese state-backed consolidation. For New Entrants and Emerging Players: Lead with additive manufacturing powder alloys for aerospace repair applications, where gas-atomized feedstock commands premium margins and incumbent qualification timelines create white space. Target India conductor alloy production under PLI scheme domestic content requirements, where grid infrastructure expansion pulls 1350 and 6201 specifications through underutilized smelter capacity. Establish tolling relationships with automotive OEMs in Bavaria and Michigan that specify recycling content minimums and just-in-sequence delivery protocols. For Investors and Strategic Acquirers: Long-term, this sits as a resource-integrated tolling play because hydro-powered primary metal access and heat-treatment certification capabilities compound defensive positioning across carbon-border adjustment regimes. Acquisition targets should display in-house recycling infrastructure or qualified aerospace metallurgical tracking systems. Monitor EU Green Deal carbon-border implementation timelines as the inflection signal for preferred origin requalification and associated price-tier separation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Power | Hindalco's Odisha coal and renewable assets anchor cost-advantaged export-grade smelting capacity against alumina volatility. |
| Closed-Loop Recycling Infrastructure | Novelis secures scrap supply chains through in-house beverage can and automotive sheet relationships that meet IRA domestic content rules. |
| Scandium-Bearing Alloy Qualification | Airbus and Boeing tier-one suppliers accelerate wing rib and stringer certification timelines that decompose 7xxx series dominance. |
| Direct Mill-Buyer Tolling Agreements | Stuttgart and Michigan automotive OEMs displace spot-market purchasing with multi-year contracts specifying gauge tolerances and recycling minimums. |
| Hydro-Powered Primary Metal Sourcing | Koblenz and Ravenswood rolling mills requalify toward Quebec and Norwegian origins to satisfy REACH carbon-border documentation demands. |
Research Methodology
Cross-validation between primary interviews with smelter operations managers, aerospace tier-one procurement directors, and automotive platform engineers anchors the qualitative findings against secondary validation from SEC 10-K filings, customs and trade flow databases, and EIA energy intensity disclosures. Bottom-up alloy grade demand modeling triangulates against top-down primary aluminum production capacity assessments across the analysis window.
Sensitivity analysis around alumina input cost bands, carbon-border adjustment implementation timelines, and aerospace build-rate scenarios shapes the analytical framework. Segmentation dimensions include product form, processing technology, application sector, and end-user concentration pattern. CAGRs derive from production capacity utilization trends, substitution elasticity estimates for composites and high-strength steel, and regional regulatory divergence modeling across the projection horizon.
Forecasts assume regulatory continuity in EU Green Deal carbon-border regimes and China's MEE dual carbon enforcement; material policy shifts would require re-modeling. Specific risk factors include Siberian supply disruption, REACH documentation requirement acceleration, and scrap segregation technology adoption lags. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Global Stainless Steel Forgings Market