
 Global Duplex Stainless Steel Market | 2026-2036
Global Duplex Stainless Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duplex Stainless Steel Market Intelligence
The bundling of multiple product forms like pipes and plates into project-specific packages is realigning buyer choice away from single-component procurement. This shift favors large-scale producers with diverse portfolios. Outokumpu Oyj leverages its extensive production capabilities to offer these integrated solutions for major projects. Sandvik AB differentiates through its specialization in advanced grades and tubular products for niche applications. ArcelorMittal S.A. competes on its global manufacturing footprint and logistical network.
Duplex stainless steel is a family of corrosion-resistant alloys characterized by a two-phase microstructure of approximately equal parts austenite and ferrite. This composition provides higher strength and superior resistance to stress corrosion cracking compared to conventional austenitic steels. Within product types, super duplex and hyper duplex grades represent the fastest-growing segments due to performance in harsh environments. The oil and gas application, particularly for pipes and plates, continues to command the largest share of consumption.
Material specification and market access are governed by international standards like ISO 31803 for petroleum and natural gas industries. In Europe, compliance with the Pressure Equipment Directive (PED) and REACH regulations dictates material selection for critical applications. These frameworks ensure performance and safety in high-stress environments. Stakeholders must now navigate the trade-off between adopting cost-effective lean duplex grades and investing in high-performance super duplex for long-term asset integrity.
Market Dynamics
The market's central dynamic revolves around a performance-cost trade-off. End-users in sectors like chemical processing and oil and gas must navigate the choice between lower-cost lean duplex grades for standard applications and high-investment super or hyper duplex grades for long-term asset integrity in aggressive environments.
Growth Catalysts
- Desalination Projects:Investment in new large-scale desalination plants, particularly in water-scarce regions of the Middle East and North Africa, creates sustained demand for corrosion-resistant pipes, pumps, and pressure vessels.
- Green Energy Infrastructure:The build-out of green hydrogen and biofuel production facilities requires materials that can withstand unique corrosive process streams, opening new applications for specialized duplex grades in storage tanks and piping systems.
- Standardization in Energy:Broadening adoption of the ISO 31803 standard for new oil and gas projects, especially in Southeast Asian and Brazilian offshore developments, mandates the use of duplex stainless steels for sour service applications.
Market Restraints
- Input Cost Volatility:Fluctuating prices for key alloying elements, especially nickel and molybdenum, introduce significant cost uncertainty for both producers and end-users, complicating long-term project budgeting and material contracts.
- Welding and Fabrication Complexity:The technical challenges and specialized skills required for welding duplex and super duplex grades, compared to conventional austenitic steels, increase fabrication costs and can limit the pool of qualified contractors.
- Threat of Substitution:In moderately corrosive environments, non-metallic alternatives like fiber-reinforced polymer (FRP) composites and advanced-coating carbon steels present a lower-cost alternative for applications such as water treatment and architectural structures.
Strategic Opportunities
- Electric Vehicle Components:The use of lean duplex grades for electric vehicle battery enclosures offers a novel application, providing a high-strength, corrosion-resistant, and lightweight solution for structural battery pack components.
- Latin American Infrastructure:Underpenetrated markets in Brazil and Mexico present opportunities for expansion, particularly in supporting new offshore oil exploration and upgrading aging chemical processing plants with higher-performance materials.
- Pressure Equipment Modernization:The EU's Pressure Equipment Directive (PED) encourages the use of higher-strength materials, creating an opportunity for super duplex grades to displace thicker, heavier materials in next-generation pressure vessel designs.
Industry Challenges
- Qualified Labor Shortage:A persistent deficit of welders and fabricators certified to work with advanced hyper duplex grades creates project execution bottlenecks and increases labor costs for critical infrastructure projects.
- Lengthy Material Qualification:The extensive and costly testing and certification processes required by major energy and chemical companies for new alloy grades can significantly delay the commercialization and adoption of innovative materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duplex Stainless Steel Market |
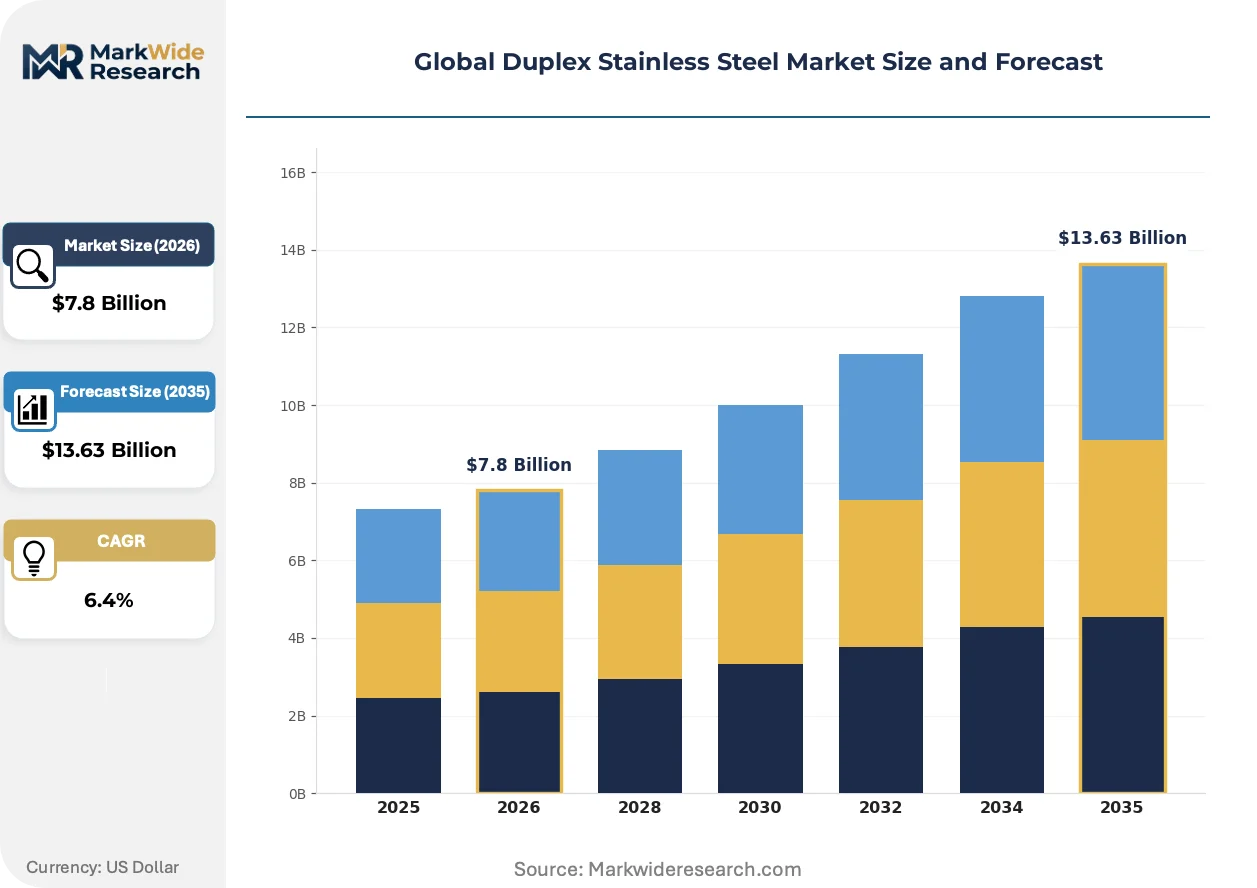
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lean Duplex, Standard Duplex, Super Duplex, Hyper Duplex Application: Oil & Gas, Chemical Processing, Water Treatment, Marine Engineering, Pulp & Paper End User Industry: Petrochemical Plants, Power Generation, Mining Operations, Shipbuilding, Food Processing Form: Sheets, Plates, Pipes, Bars, Wire Rods |
| Companies Covered | Outokumpu Oyj, Thyssenkrupp AG, ArcelorMittal S.A., POSCO, Sandvik AB, Acerinox S.A., Nippon Steel Stainless Steel Corporation, Aperam S.A., Jindal Stainless Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duplex Stainless Steel Market Strategic Shifts & Innovations
Material selection is evolving from a focus on general-purpose grades toward highly specialized, application-specific solutions. This shift is driven by a convergence of advanced manufacturing capabilities, stricter regulatory frameworks, and more sophisticated procurement models for large-scale projects.
Additive manufacturing of duplex stainless steel enables complex part creation. Aerospace and medical device sectors are early adopters for low-volume, high-value components. This technology is electrifying the supply chain for bespoke parts, allowing on-demand production of intricate geometries previously uneconomical to machine.
The European Union's REACH regulation governs chemical substances within the market. This policy compels alloy producers to document and sometimes reformulate compositions to comply with ECHA's substance registration. Producers exporting to the EU are most affected, particularly for grades used in chemical and food contact applications.
A move toward integrated project packages is altering procurement patterns. This model disrupts distributors specializing in single product forms like pipe, favoring large manufacturers with diverse portfolios. The shift is most visible in new LNG terminal and petrochemical plant construction in Southeast Asia and the US Gulf Coast.
Global Duplex Stainless Steel Market Segmentation
The segmentation of the global duplex stainless steel market clarifies the intricate interplay between material properties, specific application requirements, and end-user demands. This detailed breakdown helps stakeholders understand where value is generated and how performance-cost trade-offs influence material selection across diverse industrial landscapes.
Product Type:
The market for duplex stainless steel grades reflects varying levels of material integration, from standalone components to embedded system solutions within complex industrial systems.
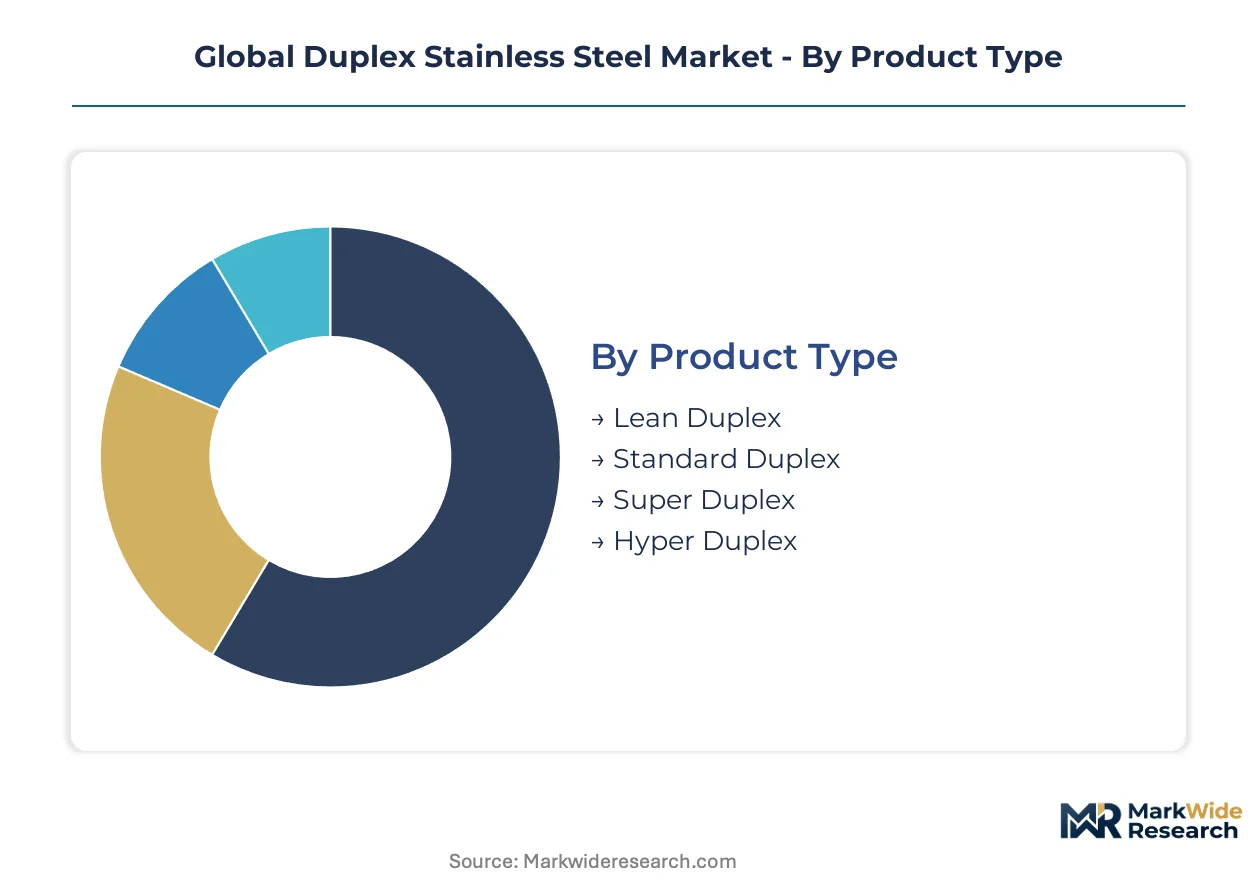
- Lean Duplex:Offers a cost-effective solution with good corrosion resistance for less aggressive environments, finding use in architectural and structural applications.
- Standard Duplex:Represents a balanced performance-cost profile, commonly employed in general industrial applications and some chemical processing.
- Super Duplex:Characterized by enhanced corrosion resistance and strength, these alloys are critical for demanding applications like offshore oil and gas platforms. Demand concentrates in the North Sea and Gulf of Mexico for high-pressure piping and subsea equipment, driven by the need for asset integrity in deepwater exploration.
- Hyper Duplex:Provides the highest level of corrosion resistance and mechanical properties, making it suitable for extremely aggressive conditions such as highly corrosive chemical reactors. Demand is concentrating in new petrochemical plant construction in Southeast Asian countries, driven by the handling of highly acidic process streams.
Volume placements concentrate in Standard Duplex; the faster expansion belongs to Hyper Duplex.
Application:
Application segmentation highlights the diverse operational environments where duplex stainless steels provide critical performance advantages, often dictating specific material grades and forms.
- Oil & Gas:This sector utilizes duplex stainless steels for their strength and resistance to sour service conditions in pipelines, risers, and process equipment. Consumption is particularly high in offshore developments in Brazil, where material integrity is paramount for deep-sea operations.
- Chemical Processing:Duplex grades are essential for handling corrosive chemicals, acids, and high temperatures in reactors, heat exchangers, and storage tanks. Demand is significant in European chemical facilities, driven by stringent safety regulations like REACH and the need for long-term plant reliability.
- Water Treatment:These alloys provide corrosion resistance in desalination plants and wastewater treatment facilities, particularly for pumps and piping.
- Marine Engineering:Duplex stainless steels are used in shipbuilding for components exposed to seawater, including propeller shafts and structural elements.
- Pulp & Paper:The industry employs duplex grades for digesters and bleaching equipment due to resistance against acidic and chloride-rich environments.
The Oil & Gas application continues to command the largest share of consumption, while Chemical Processing exhibits sustained growth due to ongoing industrial expansion.
End User Industry:
End-user industries define the scale and specific requirements driving the adoption of duplex stainless steel across various industrial value chains, influencing material specification and procurement.
- Petrochemical Plants:These facilities require duplex stainless steels for their resistance to aggressive process fluids and high pressures in reactors, columns, and piping systems. New construction in Southeast Asia drives significant demand, aligning with regional energy infrastructure expansion.
- Power Generation:Duplex grades are employed in power plants for components like condensers and heat exchangers, especially in environments with corrosive cooling water or flue gas desulfurization systems. Investment in new thermal and nuclear power projects in India contributes to steady material uptake.
- Mining Operations:Duplex stainless steels find use in mining equipment exposed to abrasive and corrosive slurries, enhancing component lifespan.
- Shipbuilding:This industry uses duplex alloys for structural elements, tanks, and piping systems exposed to harsh marine environments.
- Food Processing:Duplex grades are selected for their hygiene properties and corrosion resistance in food handling and processing equipment.
Petrochemical Plants represent a substantial volume segment, with Shipbuilding also contributing significantly to overall material consumption.
Form:
The various forms of duplex stainless steel reflect the manufacturing capabilities and supply chain configurations necessary to meet diverse project specifications for fabrication and construction.
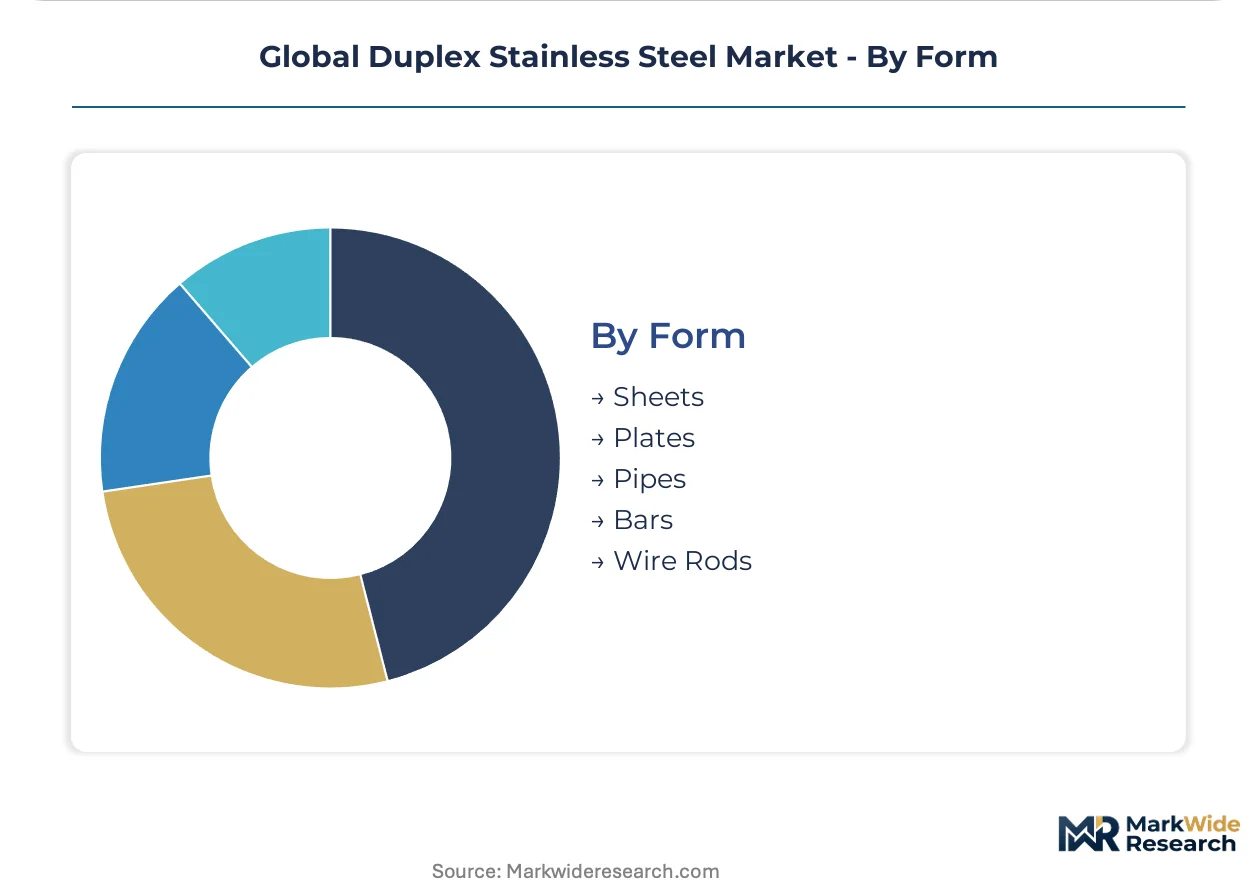
- Sheets:These are used for fabricating tanks, vessels, and general construction where flat material is required.
- Plates:Thicker plates are essential for heavy-duty structural applications, pressure vessels, and large storage tanks in demanding industrial settings. Demand is high in the US Gulf Coast for LNG terminal construction, where robust and corrosion-resistant structural integrity is critical.
- Pipes:Seamless and welded pipes are fundamental for conveying corrosive fluids and gases in oil & gas, chemical, and water treatment applications. Consumption is concentrated in Brazilian offshore developments for subsea pipelines and risers, driven by stringent safety and performance standards.
- Bars:Bars serve as raw material for machined components, fasteners, and structural supports requiring high strength.
- Wire Rods:These are typically processed into welding consumables, wires, and small components for various industrial uses.
Pipes and Plates command the largest share of the market, reflecting their integral role in large-scale infrastructure projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development of industrial zones and special economic corridors across Southeast Asia drives significant duplex stainless steel demand. These regions attract heavy investment in petrochemical and LNG infrastructure, requiring high-performance corrosion-resistant materials. Global demand concentrates in specific industrial hubs.
United States
Significant demand for duplex stainless steel originates from LNG terminal construction and chemical processing expansions in the United States. Compliance with EPA regulations and OSHA standards mandates high-integrity material selection. The US Gulf Coast region sees substantial investment in new LNG export facilities and petrochemical complexes.
Brazil
Brazil's offshore oil and gas developments represent a major consumption area for duplex stainless steels, particularly for deep-sea operations. ANP regulations for local content and safety standards influence material procurement. Coastal regions near Rio de Janeiro and São Paulo support extensive fabrication for these complex projects.
Germany
Germany's advanced chemical processing sector and focus on pressure equipment modernization create steady demand for duplex grades. The Pressure Equipment Directive (PED) and REACH regulations govern material selection for critical applications. Industrial clusters in the Rhine-Ruhr area utilize these materials for reactors and heat exchangers.
Singapore
Singapore's role as a regional petrochemical hub fuels demand for hyper duplex grades in new plant construction. The country's Environmental Protection and Management Act (EPMA) ensures stringent material performance for industrial emissions control. Jurong Island hosts numerous petrochemical facilities driving this specialized material uptake.
Indonesia
Indonesia's expanding oil and gas infrastructure and chemical industry drive material specification for duplex stainless steels. The Ministry of Industry mandates specific material standards for critical infrastructure projects. Major industrial areas in East Kalimantan and West Java are developing new processing facilities and expanding existing operations.
Global Duplex Stainless Steel Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the global duplex stainless steel market. The market structure involves large-scale integrated producers alongside niche manufacturers specializing in specific product forms or advanced grades. Strategic archetypes include global material suppliers with broad offerings, specialized product fabricators, and regional distribution network operators. Capacity expansion and portfolio diversification represent dominant competitive moves among these players seeking to capture project-specific demand.
Within the global material supply segment, Finland-based Outokumpu Oyj exemplifies a large-scale producer leveraging extensive capabilities to offer integrated solutions for major projects. Sweden-based Sandvik AB occupies a position as a specialist in advanced grades and tubular products, serving niche applications requiring high performance. ArcelorMittal S.A., with its Luxembourg company structure, anchors the market through its vast global manufacturing footprint and extensive logistical network. These entities represent different approaches to market penetration and value capture.
| Leading Market Players |
|---|
| Outokumpu Oyj |
| Thyssenkrupp AG |
| ArcelorMittal S.A. |
| POSCO |
| Sandvik AB |
| Acerinox S.A. |
| Nippon Steel Stainless Steel Corporation |
| Aperam S.A. |
| Jindal Stainless Limited |
| Others |
Cost & Logistics Intelligence
Petrochemical plant operators, particularly those undertaking large-scale projects, often encounter project-based contract pricing for duplex stainless steel, reflecting the bespoke nature of these material bundles. This model ensures material availability and technical support for complex infrastructure developments.
Pricing Analysis
Premium pricing often applies to short lead-time orders for specialized duplex stainless steel grades, reflecting accelerated production and delivery costs. The dominant pricing model is project-based contract pricing, especially for large infrastructure developments requiring integrated material packages. Price differentiation stems from the specific performance grade, such as super or hyper duplex, and the level of certification required for critical applications like ISO 31803. Pricing pressure stems from input cost volatility for key alloying elements like nickel and molybdenum, which directly impacts production expenses. Buyers of lean duplex grades exhibit the most price sensitivity, often seeking cost-effective solutions for less aggressive environments.
Supply Chain Analysis
Regional distribution centers facilitate just-in-time delivery for smaller projects and maintenance, while large project orders typically ship directly from manufacturing hubs. Geographic supply concentrates significantly in Europe, specifically Germany and Finland, alongside key East Asian producers in South Korea and Japan. The supply chain draws from critical raw material dependencies including nickel, molybdenum, and chromium. A primary supply chain risk is the inherent input cost volatility of these alloying elements, complicating long-term procurement. The dominant distribution model involves direct sales from large, integrated producers to major project sites, complemented by specialized distributors serving smaller, niche fabrication requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The duplex stainless steel market functions as a supply-constrained ecosystem, with specialized welding and fabrication expertise acting as a key capacity bottleneck driving pricing.
For Market Incumbents: Cement market leadership by expanding integrated project package offerings, particularly for new petrochemical and LNG facilities in Southeast Asia. Invest in advanced welding automation technologies to mitigate fabrication complexity and address qualified labor shortages. This strategy can counter the threat of substitution by non-metallic alternatives in moderately corrosive environments. Focus R&D on next-generation hyper duplex grades for increasingly aggressive process streams.
For New Entrants and Emerging Players: Launch via specialized engineering partnerships to provide value-added fabrication support for complex duplex stainless steel installations. Target underpenetrated markets in Latin American infrastructure upgrades, particularly for offshore oil and gas and chemical processing plant modernizations. Focus on niche applications like lean duplex for electric vehicle battery enclosures, leveraging lightweight and corrosion-resistant properties. Develop expertise in specific product forms, such as advanced tubular products for green hydrogen infrastructure.
For Investors and Strategic Acquirers: The window for entry favors strategic investors targeting niche technology providers with advanced welding and fabrication capabilities. Long-term viability remains strong, driven by global infrastructure development and the energy transition's material demands. Seek out specialized manufacturers of super or hyper duplex tubular products with established certifications for critical applications. The signal to watch is significant investment in new hyper duplex production capacity or specialized fabrication training programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Hyper Duplex | Increases material availability for demanding applications in new petrochemical plants and green energy infrastructure. |
| Backward Integration into Key Alloying Elements | Mitigates input cost volatility for nickel and molybdenum, stabilizing production costs and improving margin predictability. |
| Investment in Advanced Welding Automation | Addresses the qualified labor shortage and reduces fabrication complexity, accelerating project timelines and lowering costs. |
| Long-term Supply Agreements with Major Projects | Secures consistent demand for high-performance grades, providing revenue stability and optimizing production planning for producers. |
| Joint Ventures for Specialized Fabrication Services | Expands market reach into regions with high project activity and provides critical technical support to end-users. |
Research Approach
Independent corroboration across industry expert interviews, regulatory body publications, and company financial disclosures underwrites the qualitative findings within this analysis. Primary research involved discussions with chemical plant engineers, oil and gas project managers, material scientists, and procurement leads across various regions. Secondary data sources included ISO standards documents, ECHA REACH dossiers, company annual reports, and industry association data, providing a robust foundation. This comprehensive approach ensures triangulation of insights from both bottom-up and top-down perspectives.
The forecast framework anchors the projection horizon to historical reference periods, establishing a baseline for future growth trajectories. This analytical approach integrates various segmentation dimensions, including product type, application, end-user industry, form, and regional regulatory compliance. Compound annual growth rates were derived from historical growth patterns and projected infrastructure spending across key industrial sectors. Industry-specific forecast inputs include planned petrochemical plant construction projects and offshore oil and gas development pipelines, informing future material demand.
Input material price shocks, global economic slowdowns, and unforeseen regulatory changes are the dominant revision risks to the presented forecasts. The projections reflect assumptions documented within the study's scope and boundary conditions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Carbotanium Market
Metals
Metal Casting Market
Metals
Industrial Silver Market
Metals
Aluminum Wire Market
Metals
Global Oxygen-Free Copper Market
Metals
Seamless Stainless Steel Products Market
Metals
Copper Azoles Market
Metals
Metal Forging Parts Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Stainless Steel Sheet Market
Metals
Aluminum Flat Products Market
Metals
Heat-Treated Steel Plates Market
Metals
Metal Alloys Market
Metals
North America Metal Casting Market
Metals
Clutch Spring Wires Market
Metals
Beryllium Copper for Telecommunication Market