
 Aluminium Collars Market | 2026-2036
Aluminium Collars Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Collars Market Analytics
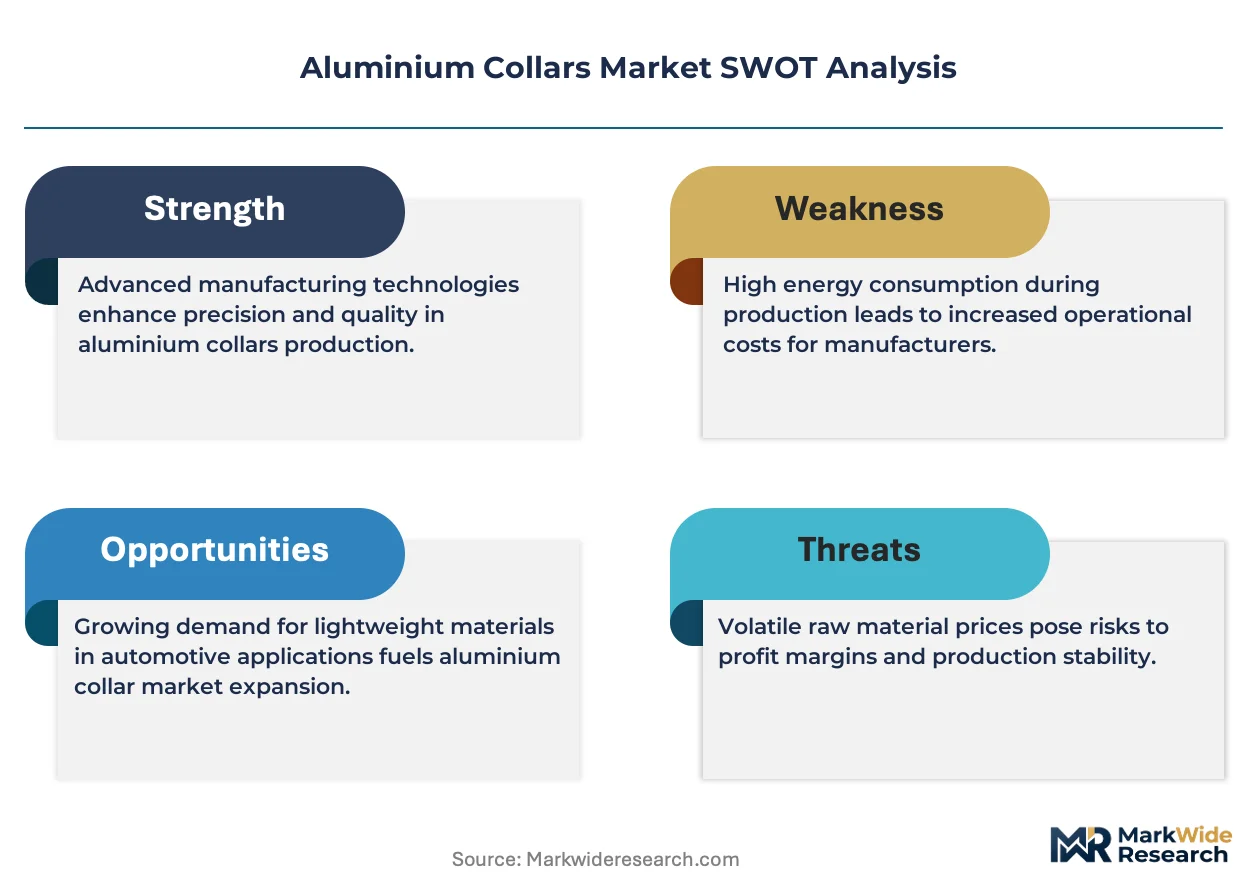
The capability gap between integrated primary producers and component specialists is collapsing as extrusion-to-finish automation becomes table stakes. Norsk Hydro leverages captive bauxite-to-rod supply chains to compress lead times on aerospace-grade collars. Hindalco Industries Ltd. anchors its position through backward integration into Indian smelting capacity, shielding margin from LME volatility. Aluminum Precision Products competes on lot-size flexibility, sustaining foundry relationships that multi-nationals cannot replicate at sub-ten-thousand-unit orders.
Aluminium collars are cylindrical fastening or support components machined from wrought aluminium alloys, typically 6061-T6 or 7075-T73 for stress-corrosion resistance, serving to locate shafts, retain bearings, or seal joints in assemblies subject to thermal cycling and galvanic exposure. Standard collars dominate current volume through OEM maintenance contracts, while sealing collars command premium positioning in cryogenic and pressurized systems where fluorosilicone interfaces replace traditional O-ring grooves. The aerospace industry vertical concentrates the highest specification density, with single-source qualification cycles locking out non-certified suppliers for three to five years per platform.
FAA airworthiness directives and EASA CS-25 certification requirements mandate lot traceability and mechanical testing documentation for flight-critical collar installations, elevating compliance costs for tier-two suppliers. EPA toxicity thresholds for hexavalent chromium conversion coatings are forcing a process shift toward trivalent chromate and plasma electrolytic oxidation finishes across US-based finishing operations. Stakeholders must monitor divergence between EU REACH substance restrictions and US OSHA permissible exposure limits, as misaligned regulatory timelines threaten to fragment qualification regimes and strand inventory on the wrong side of transatlantic shipments.
Market Dynamics
Extrusion-to-finish automation is collapsing the capability gap between integrated primary producers and component specialists, forcing mid-tier suppliers to adopt captive finishing or exit aerospace qualification tracks entirely.
Growth Catalysts
- EU Green Deal carbon-border adjustments:These mechanisms are accelerating demand for low-carbon aluminium traceability, privileging European smelters with renewable energy sourcing over import-dependent competitors.
- Aerospace airframe expansion:Commercial and defense platforms are extending procurement cycles for precision fastening hardware, locking in multi-year collar supply agreements with certified tier-one vendors.
- 7075-T73 alloy substitution:Enhanced stress-corrosion resistance specifications are displacing legacy 6061-T6 collars in cryogenic and pressurized sealing applications.
Market Restraints
- LME aluminium volatility:Unhedged component specialists face margin compression when spot prices spike above contract baselines, particularly Indian and Southeast Asian fabricators without backward integration into smelting.
- Single-source qualification lock-in:Three-to-five-year platform certification cycles by Boeing and Airbus freeze out new entrants regardless of technical parity or pricing advantage.
- Hexavalent chromium phase-out:EPA toxicity thresholds for conversion coatings are forcing capital-intensive process retooling across US-based finishing operations before trivalent alternatives achieve performance parity.
Strategic Opportunities
- Indian PLI scheme for specialty components:Production-linked incentives for aerospace and defense hardware are attracting greenfield collar machining capacity to Bangalore and Hyderabad industrial corridors.
- Fluorosilicone interface integration:Sealing collar designs that embed molded interfaces rather than machined O-ring grooves command premium positioning in cryogenic LNG and hydrogen fuel systems.
- Plasma electrolytic oxidation adoption:PEO surface finishing eliminates chromium entirely while exceeding wear resistance of legacy anodizing, opening qualification pathways with EASA and FAA for next-generation platforms.
Industry Challenges
- NADCAP special process auditor scarcity:The pool of accredited auditors for heat treatment and chemical processing certifications has failed to keep pace with aerospace supplier expansion, extending approval timelines by six to twelve months.
- REACH-OSHA regulatory divergence:Misaligned substance restriction timelines between EU and US authorities threaten to strand inventory on the wrong side of transatlantic shipments, forcing dual qualification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Collars Market |
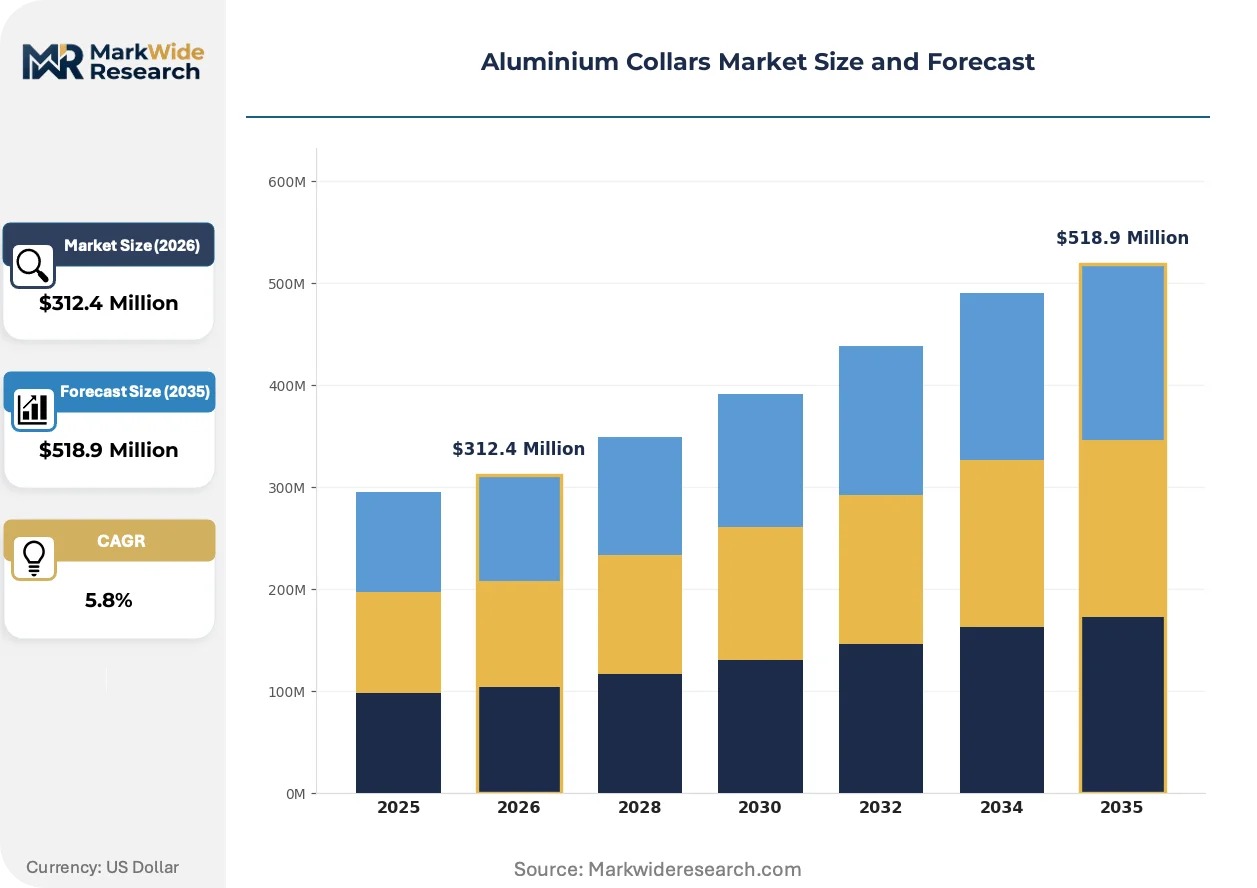
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Collars, Adjustable Collars, Sealing Collars, Decorative Collars Industry Vertical: Aerospace, Construction, Automotive, Industrial Equipment Application: Fastening, Support Structures, Decorative Elements, Thermal Insulation Installation Method: Welded, Bolted, Adhesive, Clamped |
| Companies Covered | Howmet Aerospace, Bharat Forge, Nippon Steel Corporation, Thyssenkrupp AG, Aluminum Precision Products, Hindalco Industries Ltd., UC RUSAL, Norsk Hydro, Vedanta Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Collars Market Evolving Landscape
Process automation and regulatory chemistry shifts are reconfiguring competitive advantage away from scale economies toward qualification velocity and surface engineering expertise.
Plasma electrolytic oxidation is displacing traditional sulfuric acid anodizing as the dominant finishing protocol for flight-critical collars. Aerospace tier-one suppliers in Germany and France are mandating PEO specifications for new platform introductions. The technology is displacing incumbent coating houses that lack electrolyte bath capital and waveform control IP, compressing the vendor base to integrated finishers.
REACH substance restrictions on hexavalent chromium are forcing a process shift toward trivalent chromate and chromium-free alternatives across EU-based supply chains. ECHA authorization requirements have eliminated grandfathering for legacy conversion coatings, triggering qualification sprints by surface engineering houses. German collar specialists around Düsseldorf are responding by vertically integrating PEO capacity rather than outsourcing to Eastern European job shops.
After-sales service unbundling is fragmenting long-term maintenance agreements into component-level procurement events. Airlines and MRO operators are disintermediating OEM channel partners to source FAA 8130-3 tagged collars directly from certified machine shops. This pattern concentrates in North American freight and regional carrier fleets where cost pressure overrides single-source loyalty.
Aluminium Collars Market Segmentation
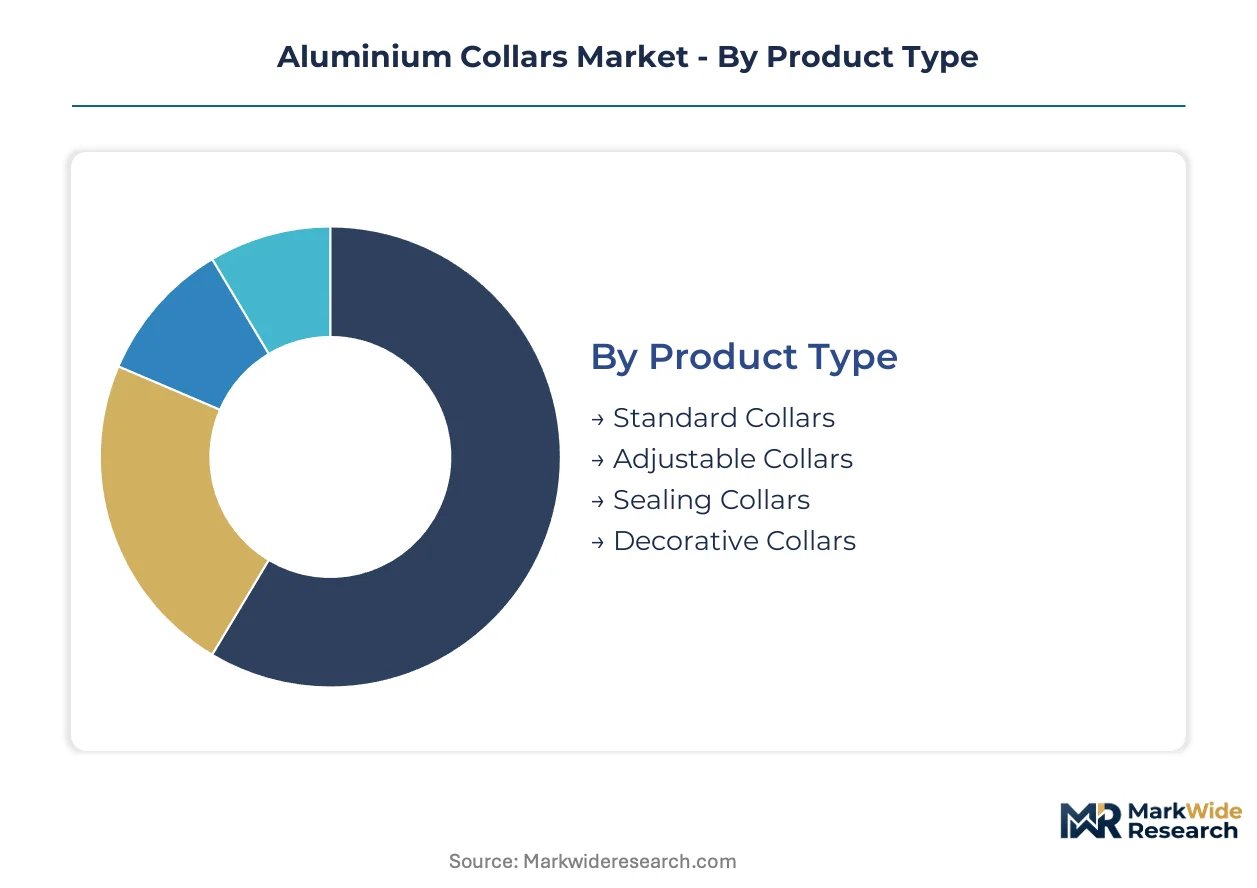
Segmentation in aluminium collars reflects divergent qualification burdens and channel economics. Aerospace-grade hardware flows through certified tier-one distributors, while construction and industrial volumes move through regional metal service centers with minimal traceability requirements.
Product Type:
Channel economics split sharply between maintenance-contract standard collars and specification-driven sealing variants. OEM direct procurement dominates high-performance segments, whereas distributor inventory sustains industrial replacement demand.
- Standard Collars:Machined from 6061-T6 or 7075-T73 alloys with set-screw or clamp-style retention. Demand concentrates in German aerospace MRO facilities and North American freight carrier fleets where FAA 8130-3 traceability documentation drives sourcing decisions.
- Sealing Collars:Integrate fluorosilicone interfaces for cryogenic and pressurized systems. Procurement is accelerating in LNG transport infrastructure and hydrogen fuel system installations across French and German industrial corridors.
- Adjustable Collars:Split-ring or threaded designs for field-fit applications. Metal service centers in India's Bangalore corridor stock these for construction equipment rebuilds.
- Decorative Collars:Anodized or PEO-finished architectural hardware. Specified in premium commercial construction through Düsseldorf-area facade system integrators.
Standard collars dominate installed base. Sealing collars are where expansion concentrates.
Industry Vertical:
Margin structures vary dramatically by vertical, with aerospace capturing certification premiums and construction competing on logistics velocity.
- Aerospace:Single-source qualification cycles lock suppliers to Boeing and Airbus platforms for three-to-five-year terms. EASA CS-25 and FAA airworthiness directives mandate lot traceability and mechanical testing documentation, elevating compliance costs.
- Automotive:EV thermal management systems are adopting aluminium collars for battery pack structural retention. German automotive suppliers specify PEO-finished variants to eliminate hexavalent chromium from supply chains.
- Construction:Curtain wall and structural glazing applications specify decorative collars with architectural anodizing. Regional metal distributors in Dortmund industrial zones stock standard sizes for just-in-time delivery.
- Industrial Equipment:Food processing and pharmaceutical machinery require FDA-compliant surface finishes. Indian PLI scheme incentives are attracting machining capacity to Hyderabad for export to Southeast Asian OEMs.
Aerospace captures value concentration. Automotive is climbing the fastest on electrification-driven thermal management demand.
Application:
Functional requirements determine alloy selection and finishing protocols, with thermal cycling and galvanic exposure driving specification divergence.
- Fastening:Shaft retention and bearing location in rotating assemblies. 7075-T73 alloy substitution is displacing legacy 6061-T6 in stress-corrosion-critical installations across US defense platforms.
- Support Structures:Load-bearing collars in framework and scaffolding systems. Construction activity in Germany's industrial corridor sustains volume demand through regional fabricators.
- Decorative Elements:Architectural trim and exposed hardware. EU Green Deal carbon-border adjustments are privileging European-sourced aluminium with renewable energy traceability.
- Thermal Insulation:Cryogenic pipe support and LNG system interfaces. Sealing collar designs with integrated fluorosilicone are gaining specification in hydrogen fuel infrastructure.
Fastening commands specification density. Thermal insulation is gaining share fastest on energy transition infrastructure buildout.
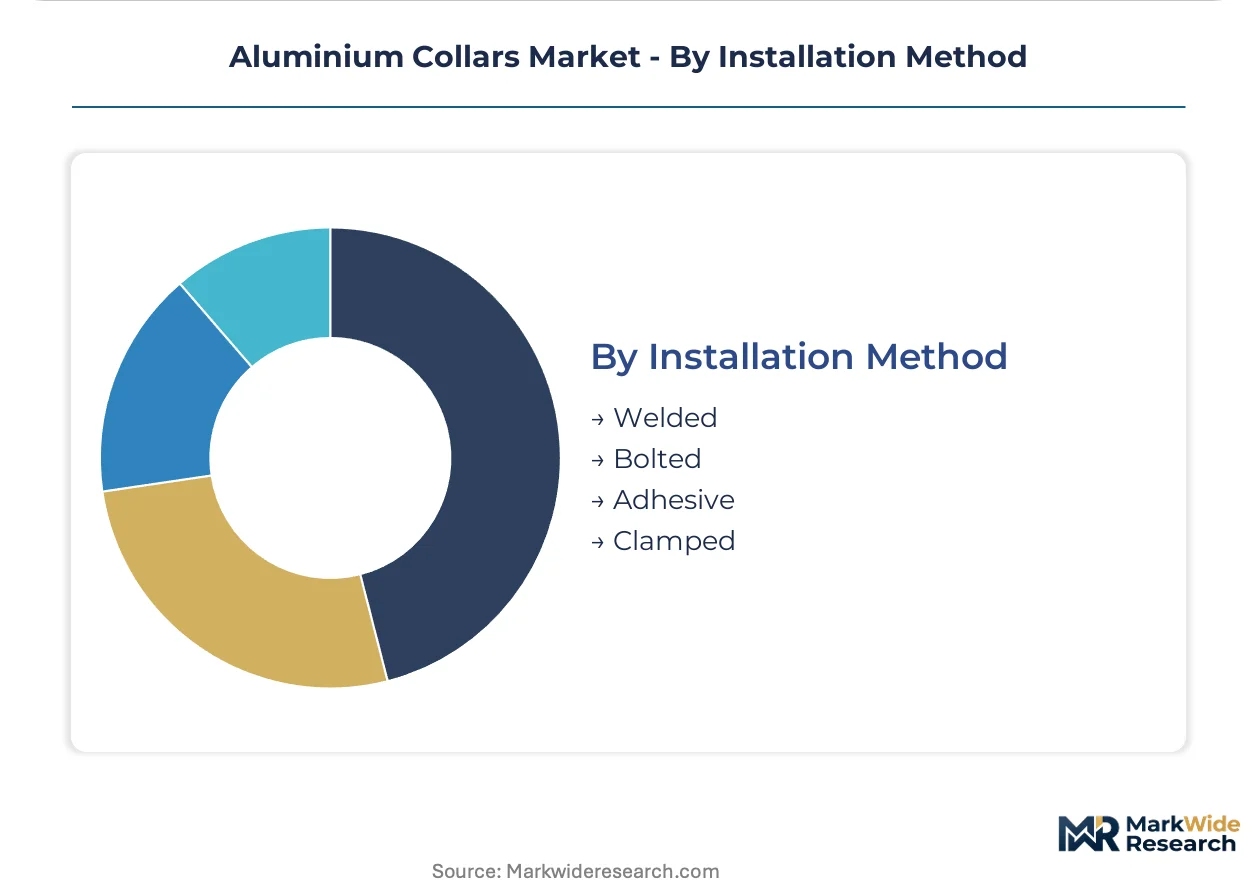
Installation Method:
Assembly labor content and field-service accessibility shape procurement preferences across verticals.
- Bolted:Removable mechanical retention for maintenance-intensive applications. Dominates aerospace and industrial equipment where disassembly cycles are frequent.
- Clamped:Split-ring designs for field adjustment without shaft removal. Preferred in construction equipment and automotive service applications.
- Welded:Permanent structural attachment in architectural and heavy industrial frameworks. Requires 6061-T6 alloy selection for weldability over strength-optimized alternatives.
- Adhesive:Bonded retention for weight-critical and galvanic-isolation applications. Emerging in EV battery pack assemblies where dissimilar metal contact must be eliminated.
Bolted collars retain installed base dominance. Adhesive bonding is expanding most quickly on electrification platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's precision engineering sector exhibit extreme price sensitivity to LME aluminium volatility, while German aerospace OEMs prioritize qualification velocity and carbon traceability over unit cost differentials. This elasticity divergence fragments procurement patterns across geographies.
United States
Defense platform modernization and commercial MRO unbundling sustain demand for FAA 8130-3 traceable collars. EPA toxicity thresholds for hexavalent chromium conversion coatings are forcing capital-intensive process retooling across finishing operations. Precision machining clusters in Connecticut and Arizona concentrate on 7075-T73 alloy substitution for stress-corrosion-critical installations.
Germany
EU Green Deal carbon-border adjustments privilege domestic smelters with renewable energy traceability over import-dependent competitors. ECHA REACH authorization requirements have eliminated grandfathering for legacy conversion coatings, triggering qualification sprints by surface engineering houses. The Düsseldorf-Dortmund industrial corridor anchors captive PEO finishing capacity for aerospace tier-one suppliers.
India
PLI scheme production-linked incentives for aerospace and defense hardware are attracting greenfield collar machining capacity. LME volatility exposes fabricators without backward integration into smelting to severe margin compression. Bangalore and Hyderabad industrial corridors concentrate EV thermal management and export-oriented precision component manufacturing.
France
EASA CS-25 certification requirements and single-source qualification cycles lock suppliers to Airbus platforms for multi-year terms. REACH substance restrictions on hexavalent chromium are forcing process shifts toward trivalent chromate alternatives. Toulouse-area aerospace suppliers mandate plasma electrolytic oxidation specifications for new platform introductions.
Japan
METI industrial policy supports domestic supply chain resilience for flight-critical fastening hardware. JIS standards alignment with EASA and FAA protocols reduces dual qualification burdens for export-oriented fabricators. Nagoya-area precision engineering clusters concentrate on high-reliability collar production for regional jet programs.
Aluminium Collars Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where integrated primary producers compete on supply chain control while component specialists compete on lot-size flexibility and qualification velocity. The market exhibits moderate consolidation around aerospace-certified tier-one vendors, with significant fragmentation in industrial and construction segments. Three strategic archetypes dominate: backward-integrated aluminium majors with captive smelting capacity, precision machining specialists with NADCAP special process certifications, and regional fabricators competing on logistics proximity. Dominant competitive moves include captive finishing capacity expansion to meet REACH and EPA compliance deadlines, and strategic partnerships with aerospace OEMs to secure multi-year platform qualification lock-ins.
Among integrated primary producers, Norsk Hydro and Hindalco Industries Ltd. exemplify the backward-integration archetype, leveraging captive bauxite-to-rod supply chains to compress lead times and shield margins from LME volatility. Aluminum Precision Products occupies a position within the specialist tier, competing on lot-size flexibility and foundry relationships that multi-nationals cannot replicate at sub-ten-thousand-unit orders. These three anchors illustrate the capability divergence between scale-driven upstream control and agility-driven downstream positioning.
| Leading Market Players |
|---|
| Howmet Aerospace |
| Bharat Forge |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| Aluminum Precision Products |
| Hindalco Industries Ltd. |
| UC RUSAL |
| Norsk Hydro |
| Vedanta Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between aerospace tier-one suppliers and certified collar manufacturers lock in both supply access and price visibility, insulating qualified vendors from LME spot volatility while freezing out non-certified competitors regardless of pricing advantage. These multi-year contracts concentrate procurement power among German and French aerospace clusters where EASA CS-25 qualification cycles create artificial scarcity.
Pricing Analysis
After-sales component revenue drives lifetime value in this market, with MRO unbundling fragmenting maintenance agreements into individual FAA 8130-3 tagged collar purchases. Three-tier pricing structure across aerospace-certified, industrial-standard, and construction-economy levels reflects certification burden divergence. Pricing pressure stems from Indian fabricators without backward integration facing severe margin compression during LME spikes. Construction buyers exhibit extreme price sensitivity, while aerospace OEMs prioritize qualification velocity over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam-Antwerp container corridors fluctuate with EU carbon-border adjustment implementation timelines, privileging European smelters with renewable energy traceability. Supply concentrates in Germany, India, and the United States for precision machining, drawing from bauxite feedstocks anchored in Guinea, Australia, and Brazil. Single-source qualification vulnerability threatens supply continuity when NADCAP auditor scarcity extends approval timelines. Distribution runs through certified tier-one distributors for aerospace, regional metal service centers for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantage. Three-to-five-year platform qualification cycles by Boeing and Airbus generate switching costs that protect incumbent positions regardless of technical parity from new entrants.
For Market Incumbents: Secure captive plasma electrolytic oxidation finishing capacity before REACH and EPA compliance deadlines eliminate outsourced alternatives. Deepen upstream control over bauxite-to-rod supply chains to compress lead times and shield margins from LME volatility. The threat of Indian PLI-subsidized entrants demands pre-emptive qualification lock-ins with expanding defense platforms. For New Entrants and Emerging Players: Aftermarket MRO direct procurement gaps where airlines disintermediate OEM channel partners offer accessible entry points. Target North American freight and regional carrier fleets where cost pressure overrides single-source loyalty. A go-to-market angle through FAA 8130-3 certified machine shops bypasses tier-one distributor gatekeeping. For Investors and Strategic Acquirers: NADCAP-specialist precision machining shops with heat treatment and chemical processing certifications represent priority acquisition targets. Long-term viability hinges on regulatory chemistry transition completion before hexavalent chromium phase-out deadlines. The signal to monitor is plasma electrolytic oxidation qualification velocity with EASA and FAA for next-generation aerospace platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Captive PEO Finishing Capacity | Eliminates hexavalent chromium exposure while exceeding legacy anodizing wear resistance for EASA qualification. |
| Backward Bauxite Integration | Compresses aerospace-grade collar lead times and insulates margins from LME spot price volatility. |
| Multi-Year Platform Lock-In | Secures revenue visibility through Boeing and Airbus single-source qualification cycles spanning three to five years. |
| Fluorosilicone Interface Development | Commands premium positioning in cryogenic LNG and hydrogen fuel system sealing collar specifications. |
| Indian PLI Scheme Utilization | Attracts greenfield aerospace machining capacity to Bangalore and Hyderabad with production-linked incentives. |
Research Methodology
Cross-validation between primary interviews with aerospace procurement directors, NADCAP-specialist plant managers, MRO aftermarket buyers, and surface engineering R&D leads anchors the qualitative findings against secondary validation from FAA airworthiness directives, EASA CS-25 certification databases, EPA toxicity threshold filings, and customs trade data. Bottom-up fabrication capacity assessments triangulate with top-down aerospace platform demand projections.
Sensitivity analysis across alloy substitution rates, REACH compliance timeline scenarios, and carbon-border adjustment implementation schedules informs the analytical framework. Segmentation dimensions span product type, industry vertical, application function, and installation method, with regional production cluster capacity serving as an additional modeling layer. CAGRs derive from installed base replacement cycles and new platform introduction schedules, incorporating 7075-T73 alloy displacement curves and PEO adoption trajectories as industry-specific inputs.
Underlying assumptions cover sustained aerospace airframe expansion, REACH-OSHA regulatory convergence, and LME price band stability, with deviation risk concentrated in NADCAP auditor availability and dual qualification timeline divergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zirconium Market
Metals
Brazing Strips Market
Metals
Electrolytic Manganese Metal Market
Metals
Global Aluminum Extruded Products Market
Metals
Steel Casting Market
Metals
Beryllium Copper Plate Market
Metals
Global Brass Rods Market
Metals
Colloidal Metal Particles Market
Metals
Copper Chromium Black Market
Metals
Arc Ferrite Magnet Market
Metals
Nickel Market
Metals
High Purity Tungsten Market
Metals
Global Copper Cathode Market
Metals
Osmium Market
Metals
Copper and Copper Alloy Market
Metals
Metal Casting Market