
 Global Alternative Sweeteners Market | 2026-2036
Global Alternative Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alternative Sweeteners Market Intelligence
Proprietary formulation development for specific food and beverage applications is fragmenting the value pool previously dominated by bulk ingredient supply. Cargill Incorporated leverages its vast agricultural supply chain to secure raw materials for sweeteners like erythritol. Tate & Lyle PLC specializes in creating customized sweetening solutions for beverage and dairy alternative clients. Ingredion Incorporated competes on the basis of its broad portfolio of both starch-based and high-intensity sweeteners.
Alternative sweeteners are food additives that replicate the sweet taste of sugar while containing significantly fewer calories. These compounds, which include polyols like erythritol and high-intensity sweeteners derived from plants like stevia, do not cause a significant increase in blood glucose levels. Natural sweeteners such as stevia and monk fruit are gaining share from artificial variants like aspartame due to consumer preferences for clean labels. The beverage category represents the largest application, with food processors reformulating products to reduce sugar content.
Regulatory bodies like the U.S. FDA and the European Food Safety Authority (EFSA) define safety standards and acceptable daily intake levels for each sweetener. These regulations, along with labeling mandates from agencies such as India's FSSAI, directly influence product formulation and market access for manufacturers. Success for suppliers depends on navigating the complex interplay between evolving consumer health perceptions and the patchwork of international food safety approvals.
Market Dynamics
The central tension shaping the alternative sweeteners market is the conflict between consumer demand for "clean label" ingredients and the industrial-scale bioprocessing required to produce them. This is driving a market-wide pivot from commodity artificial sweeteners to proprietary, application-specific natural sweetener systems.
Growth Catalysts
- Regulatory Pressure on Sugar:Government-led initiatives, including sugar taxes in the United Kingdom and front-of-pack warning labels in Mexico, compel beverage and snack manufacturers to reformulate products using non-caloric sweeteners.
- Clean Label Consumerism:A strong consumer preference for recognizable, plant-derived ingredients is accelerating the substitution of artificial sweeteners like aspartame with natural options such as stevia and monk fruit in processed foods.
- Fermentation Technology Advances:Innovations in precision fermentation are enabling scalable, cost-effective production of rare sweeteners like Reb M and tagatose, expanding the toolkit for food scientists and reducing reliance on agricultural inputs.
Market Restraints
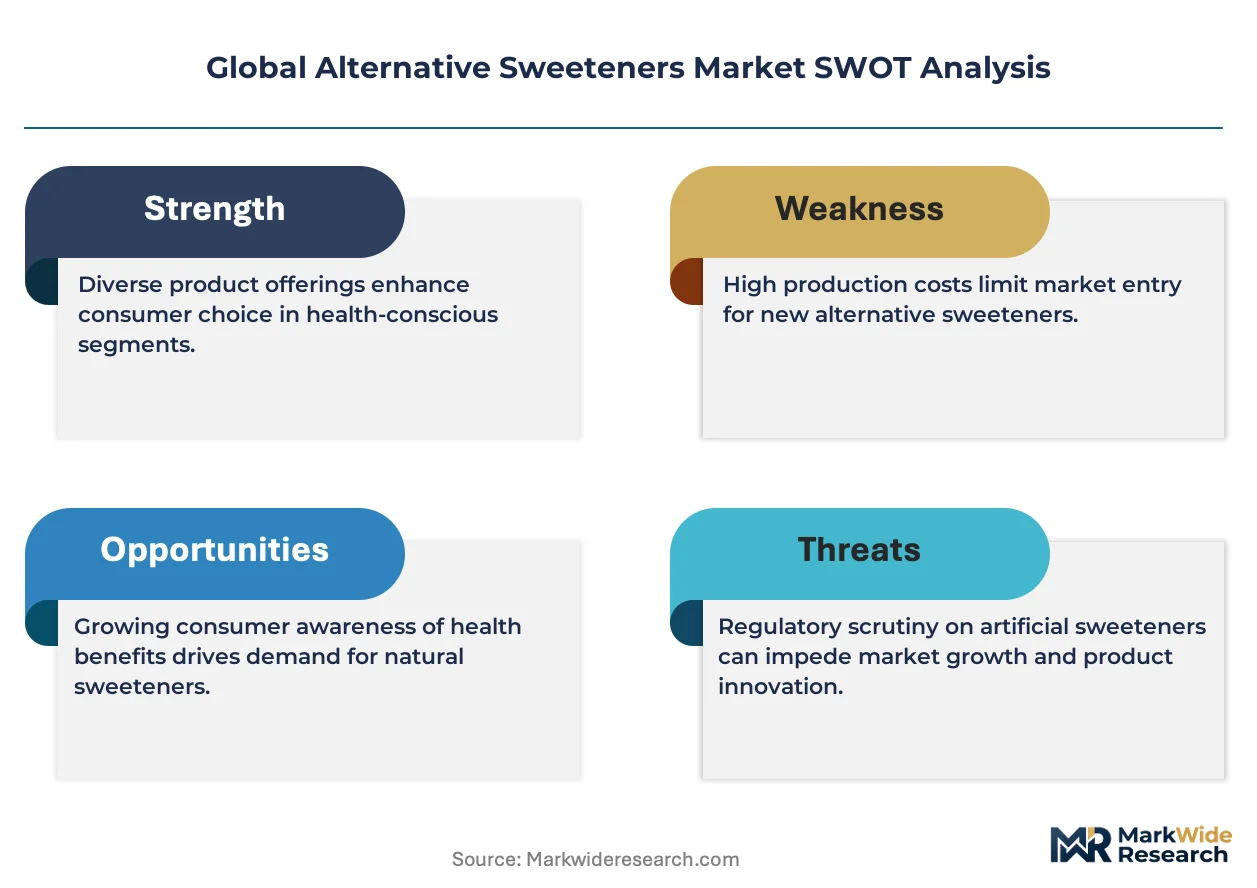
- Sensory Profile Limitations:The presence of bitter or metallic off-tastes in some high-intensity sweeteners, particularly steviol glycosides, restricts their use in delicately flavored applications like dairy products and certain beverages.
- Geographic Supply Concentration:The global supply of stevia leaf, a primary raw material, is heavily concentrated in China, exposing processors to geopolitical risks, weather-related disruptions, and price volatility.
- Fragmented Regulatory Approvals:Divergent safety assessments and acceptable daily intake (ADI) levels set by bodies like the U.S. FDA and the European Food Safety Authority (EFSA) create hurdles for global product launches.
Strategic Opportunities
- Pharmaceutical Excipients:The use of polyols like erythritol and xylitol to improve the palatability of oral medications, particularly for pediatric and geriatric populations, represents a significant, underpenetrated market.
- Savory Flavor Modulation:Low-concentration use of specific sweeteners to enhance and balance flavors in savory applications, such as sauces, dressings, and processed meats, opens a new avenue for growth beyond sweetness.
- Synergistic Blending:Developing proprietary blends of multiple sweeteners, such as combining stevia with erythritol or allulose, allows for the creation of customized solutions that mimic the sensory profile and functionality of sugar.
Industry Challenges
- Formulation Expertise Scarcity:A persistent shortage of food scientists with the specialized skills to reformulate complex products using alternative sweeteners without compromising texture, mouthfeel, or shelf stability acts as a development bottleneck.
- Consumer Perception and Labeling:Communicating the benefits and safety of novel sweeteners while navigating complex labeling regulations from agencies like India's FSSAI presents a continuous marketing and compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alternative Sweeteners Market |
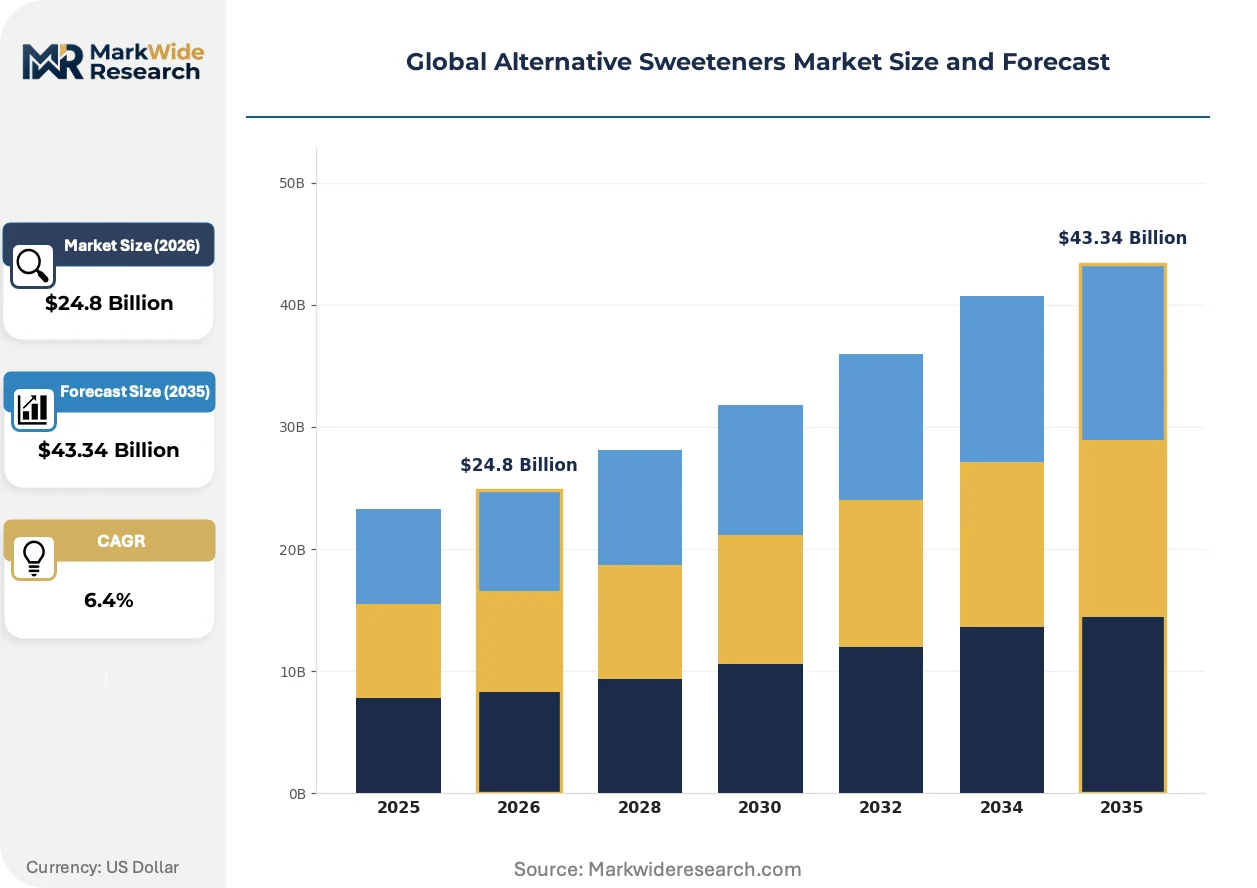
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Erythritol, Monk Fruit, Sucralose, Aspartame, Acesulfame-K Application: Beverages, Bakery & Confectionery, Dairy Alternatives, Pharmaceuticals, Personal Care End User: Food Processing Companies, Beverage Manufacturers, Pharmaceutical Firms, Personal Care Brands Packaging Type: Pouches, Bottles, Sachets, Bulk Containers, Tins |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères, Ajinomoto Co., Inc., DuPont Nutrition & Health, Associated British Foods PLC, FoodChem International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alternative Sweeteners Market Strategic Shifts & Innovations
The market's evolution is defined by a move from supplying single ingredients to providing integrated sweetening systems. This shift prioritizes functional and sensory performance in specific food and beverage matrices, favoring suppliers with deep formulation expertise over bulk commodity traders.
Precision fermentation technology enables the production of nature-identical sweetener molecules, such as Reb M from stevia, without relying on traditional agricultural cultivation. Food and beverage companies are adopting these ingredients to secure supply chain stability and manage costs. This technological shift is collapsing the historical divide between plant-extracted and chemically synthesized sweeteners, establishing a new category of bio-identical compounds defined by their production method.
Front-of-pack nutrition labeling systems, including Nutri-Score in several European Union countries and health warnings in Chile, are gaining traction globally. These regulations create direct commercial incentives for manufacturers to reduce the sugar content in their products. The beverage and confectionery segments are most affected, accelerating their adoption of high-intensity sweeteners and polyols to improve product health scores and avoid negative labeling.
A significant change in buying behavior sees food processors procuring complete, pre-blended sweetening solutions rather than individual bulk ingredients. This trend disrupts the role of traditional commodity distributors, elevating suppliers who offer co-development and application-specific formulation support. This pattern is particularly evident within the functional beverage and plant-based dairy alternative categories, where achieving a clean taste profile is paramount for consumer acceptance.
Global Alternative Sweeteners Market Segmentation
Segmentation provides a granular view of the Global Alternative Sweeteners Market, revealing distinct product compositions, application areas, end-user profiles, and packaging preferences. This detailed breakdown helps manufacturers align their offerings with specific market needs and consumer demands, from industrial-scale food reformulation to individual consumer-packaged goods.
Product Type:
The product type segment illustrates the maturity spectrum of alternative sweeteners, from established artificial compounds to emerging natural options.
- Stevia:This natural, plant-derived sweetener, primarily from the Stevia rebaudiana plant, contains steviol glycosides that provide intense sweetness without calories. Demand concentrates heavily in the beverage sector, driven by consumer preference for clean labels and sugar reduction initiatives across North America and Europe.
- Erythritol:A sugar alcohol (polyol) naturally found in some fruits, erythritol offers about 70% of sugar's sweetness with minimal calories and a high digestive tolerance. Its demand is significantly increasing within the bakery and confectionery industries in the United States and China, driven by its clean taste profile and bulking properties.
- Monk Fruit:Derived from Siraitia grosvenorii, monk fruit extract is a natural, high-intensity sweetener gaining traction for its zero-calorie profile and absence of off-tastes.
- Sucralose:This artificial sweetener is approximately 600 times sweeter than sugar and is widely used in diet soft drinks and various processed foods due to its heat stability.
- Aspartame:An artificial, low-calorie sweetener composed of two amino acids, aspartame finds extensive use in sugar-free chewing gum and powdered beverage mixes.
- Acesulfame-K:A calorie-free artificial sweetener often blended with other sweeteners to achieve a more sugar-like taste profile in beverages and dairy products.
Stevia retains volume leadership; erythritol holds the steepest expansion curve.
Application:
The application segment highlights where alternative sweeteners are integrated into consumer products.
- Beverages:This category includes soft drinks, juices, functional drinks, and flavored waters, where alternative sweeteners are crucial for sugar reduction without compromising taste. Government-led sugar taxes in the United Kingdom compel beverage manufacturers to reformulate products.
- Bakery & Confectionery:Alternative sweeteners provide sweetness and sometimes texture to baked goods, chocolates, and candies, catering to health-conscious consumers. Formulation expertise is critical to maintain product integrity in this segment.
- Dairy Alternatives:Plant-based milks, yogurts, and ice creams increasingly incorporate alternative sweeteners to achieve desired sweetness levels and mask off-notes from plant proteins.
- Pharmaceuticals:Alternative sweeteners improve the palatability of oral medications and supplements, particularly for pediatric and geriatric patient populations.
- Personal Care:Oral hygiene products like toothpaste and mouthwash utilize alternative sweeteners to enhance flavor and user acceptance.
Beverages concentrate the largest volume of alternative sweeteners, while dairy alternatives demonstrate rapid integration.
End User:
The end user segment differentiates the primary customer types procuring alternative sweeteners for their product lines.
- Food Processing Companies:These entities incorporate alternative sweeteners into a vast array of processed foods, including snacks, sauces, and ready meals, to meet consumer health trends. Cargill Incorporated leverages its agricultural supply chain to serve these industrial clients.
- Beverage Manufacturers:Companies producing soft drinks, juices, and other liquid refreshments are major consumers of alternative sweeteners for sugar reduction and calorie control. Tate & Lyle PLC specializes in customized sweetening solutions for these clients.
- Pharmaceutical Firms:These companies use alternative sweeteners as excipients to improve the taste and mouthfeel of medicinal products, enhancing patient compliance.
- Personal Care Brands:Manufacturers of oral care products and cosmetics utilize alternative sweeteners for flavor and product appeal.
Food processing companies drive substantial demand, with pharmaceutical firms representing a specialized, high-value segment.
Packaging Type:
The packaging type segment reflects how alternative sweeteners are distributed and utilized across different industrial scales and consumer formats.
- Bulk Containers:Large drums, sacks, and intermediate bulk containers (IBCs) are used for high-volume industrial clients, including major food and beverage manufacturers. This packaging optimizes logistics and cost-efficiency for industrial-scale operations.
- Pouches:Flexible pouches offer convenience and portion control for both industrial and consumer markets, especially for smaller-scale food service or individual retail sales. Consumer preferences for resealable and lightweight packaging influence this segment.
- Bottles:Typically used for liquid alternative sweeteners or tabletop formats, bottles provide easy dispensing for both household and commercial use.
- Sachets:Small, single-serving sachets are popular in food service, hospitality, and for individual consumer convenience.
- Tins:Metal tins provide robust protection and extended shelf life for powdered or granulated alternative sweeteners, often for premium or specialty products.
Bulk containers dominate industrial procurement, whereas pouches cater significantly to consumer and smaller-scale applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for alternative sweeteners vary significantly by geography, reflecting diverse dietary habits and regulatory landscapes. The United States and China drive demand for specific polyols like erythritol in food processing. European markets emphasize clean label natural sweeteners due to evolving consumer health perceptions.
United States
Demand for alternative sweeteners in the United States stems from health-conscious consumers seeking sugar reduction in beverages and bakery items. The U.S. FDA sets safety standards and acceptable daily intake levels for novel sweeteners. Food processing hubs in the Midwest, like Chicago, actively reformulate products with advanced sweetening systems.
China
China's food processing industries exhibit robust demand for erythritol, driven by its clean taste and bulking properties in confectionery. GB standards regulate the use and labeling of food additives, including alternative sweeteners. Major industrial zones in the Yangtze River Delta focus on large-scale production and application development for these ingredients.
United Kingdom
The United Kingdom's beverage sector accelerates alternative sweetener adoption due to government-led initiatives like the sugar tax. UK Food Standards Agency guidelines influence product formulation and consumer labeling for sugar-reduced items. London's food innovation ecosystem supports startups developing novel sweetening solutions for functional drinks.
India
Consumer preference for healthier food options in India fuels the integration of natural alternative sweeteners in packaged goods. India's FSSAI mandates comprehensive labeling requirements for products containing non-caloric sweeteners. Food manufacturers in Maharashtra concentrate on developing culturally relevant, sugar-free confectionery and dairy products.
Germany
Germany's food and beverage industry prioritizes natural and clean label alternative sweeteners, particularly in dairy and functional foods. The European Food Safety Authority (EFSA) rigorously assesses the safety of new sweetening compounds for market approval. Bavaria's strong agricultural and food processing sector integrates advanced sweetening technologies into diverse product lines.
Global Alternative Sweeteners Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the alternative sweeteners market. The competitive landscape exhibits a tiered structure, where large ingredient suppliers coexist with specialized formulation houses and biotechnology innovators. Strategic archetypes include global agricultural processors leveraging vast supply chains, specialized sweetening solution providers offering application-specific expertise, and technology-driven firms pioneering precision fermentation. Portfolio diversification through new product launches and strategic partnerships with food and beverage manufacturers represent dominant competitive moves among market participants.
Within the global agricultural processing tier, Cargill Incorporated represents large-scale raw material sourcing for sweeteners like erythritol, leveraging its vast supply chain. Tate & Lyle PLC exemplifies specialized sweetening solution providers, focusing on customized sweetening solutions for beverage and dairy alternative clients. Ingredion Incorporated occupies a position among diversified ingredient portfolios, offering a broad range of both starch-based and high-intensity sweeteners to a broad client base. These entities anchor the market through their extensive distribution networks, application development expertise, and ability to meet industrial-scale demand.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Roquette Frères |
| Ajinomoto Co., Inc. |
| DuPont Nutrition & Health |
| Associated British Foods PLC |
| FoodChem International Corporation |
| Others |
Cost & Logistics Intelligence
The global supply of stevia leaf, heavily concentrated in China, directly influences the cost structure and margin potential for natural sweetener producers and downstream food and beverage manufacturers. This upstream concentration creates both pricing power and supply chain vulnerabilities for specific ingredients.
Pricing Analysis
Long-term contract-based offtake agreements dominate industrial procurement of alternative sweeteners. Spot market transactions primarily occur for smaller volumes or emerging, less established sweetener compounds. Quality grade, specifically the purity of steviol glycosides like Reb M, drives premium pricing for natural options. Volume scale significantly influences per-unit costs for bulk buyers in the food processing sector. Pricing softness in commodity artificial sweeteners stems from intense competition and oversupply. Food processing companies are highly price-sensitive for bulk ingredients, while pharmaceutical firms prioritize purity and regulatory compliance.
Supply Chain Analysis
Upstream feedstock for alternative sweeteners, particularly stevia leaf, concentrates in China and Paraguay. Erythritol production relies heavily on starch-based inputs, primarily sourced from the United States and China. Corn starch and sugarcane serve as primary feedstocks for many polyols and fermentation-derived sweeteners. Geopolitical risks and weather-related disruptions in key agricultural regions pose a structural risk to natural sweetener availability. Distribution runs through a network of large ingredient distributors and specialized chemical suppliers, delivering to industrial food and beverage manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternative sweeteners market presents a defensive-moat story, primarily due to regulatory entrenchment and the high switching costs associated with product reformulation. Manufacturers face significant investment in R&D and regulatory approval for new ingredients.
For Market Incumbents:Insulate core product lines by deepening vertical integration into key raw material supply and investing in precision fermentation technologies. Expand application development expertise to counter emerging natural sweetener entrants. The threat of generic artificial sweeteners being displaced by clean label alternatives requires proactive innovation. Investment in advanced R&D for novel, taste-optimized blends offers a strategic lever.
For New Entrants and Emerging Players:Pursue niche applications in functional beverages and plant-based dairy alternatives where clean taste profiles are critical. Target specialized markets like pharmaceutical excipients for high-value, lower-volume opportunities. The dairy alternatives segment remains highly penetrable for novel, natural, and off-taste-free sweeteners. A co-development go-to-market angle with food and beverage formulators fosters early adoption and tailored solutions.
For Investors and Strategic Acquirers:Capital is best deployed toward technology-driven firms pioneering precision fermentation and specialized formulation houses with deep application expertise for long-term viability. These entities command premium valuations due to intellectual property and market access. Acquisition targets should include companies with proprietary blending technologies or novel sweetener molecules with clear regulatory pathways. The signal to watch is the increasing market share of bio-identical, fermentation-derived sweeteners displacing traditional plant extracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Secures cost-effective, sustainable supply of nature-identical sweeteners like Reb M. |
| Custom Formulation Partnerships | Develops application-specific sweetening solutions for complex food and beverage matrices. |
| Regulatory Approval Acceleration | Expands market access for novel sweeteners across key geographies like the EU and US. |
| Geographic Production Diversification | Mitigates supply chain risks associated with raw material concentration in single regions. |
| Sensory Profile Optimization R&D | Addresses off-tastes in high-intensity sweeteners, broadening their application range. |
Research Approach
A spread of perspectives from food scientists, procurement leads, regulatory affairs specialists, and R&D directors converged on the working assumptions for the alternative sweeteners market. This involved combining in-depth primary interviews with rigorous secondary validation. Publicly available data from regulatory bodies like the U.S. FDA and EFSA, alongside industry association reports and trade statistics, informed the analysis. Both bottom-up and top-down triangulation methods ensured data accuracy.
Demand-supply-balance models underpinned the quantitative forecast across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and packaging type, alongside regional consumption patterns. Compound Annual Growth Rates were derived from historical data trends and projected market drivers. Key forecast inputs included sugar reduction targets by major food and beverage companies and new sweetener regulatory approvals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major ingredient suppliers or biotechnology innovators would shift outcomes. Forecasts reflect assumptions documented at the time of publication, acknowledging potential disruptions from unforeseen regulatory changes or supply chain shocks. Cross-checking against major food and beverage company earnings calls is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
United States Food Sweetener Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Stevia Mints Market
Sweeteners
Sour Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Oligofructose Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
China Food Sweetener Market
Sweeteners
Mannitol Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Xylitol Market
Sweeteners
Sucrose Acetate Isobutyrate Market