
 China Food Sweetener Market | 2026-2036
China Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Sweetener Market Outlook
Project finance for greenfield fermentation facilities is reshaping competitive entry in China's food sweetener sector. Shandong Newnature Biotechnology leverages integrated starch-to-sweetener processing to control input costs. Cargill, Incorporated anchors its position through supply partnerships with domestic beverage bottlers in coastal provinces. Archer Daniels Midland Company competes via bulk aspartame and sucralose distribution networks serving food manufacturers.
Food sweeteners comprise caloric and non-caloric compounds that impart sweetness to consumable products, typically manufactured through fermentation of corn or sugar beet feedstocks, chemical synthesis, or extraction from stevia leaves, with functional parameters measured by relative sweetness intensity compared to sucrose and thermal stability under processing conditions. Their primary commercial purpose is to replicate or enhance sensory profiles while enabling calorie reduction, shelf-life extension, or cost optimization in packaged goods. Sucralose and Acesulfame K lead product type revenue due to heat stability advantages in baked and pasteurized applications, while beverage sector demand drives fastest growth in liquid form factors optimized for high-speed bottling lines. Powder and granular formats retain margin pools in bakery and confectionery segments where precise dosing and blend uniformity command premium positioning.
SAMR enforces GB 2760 food additive usage limits that directly constrain maximum sweetener concentrations in finished products, while MEE emissions standards raise capital requirements for fermentation-based manufacturers. The dual carbon policy framework pressures Shandong and Jiangsu producers to retrofit plants with carbon capture or switch to biomass energy inputs. NMPA oversight of novel sweetener safety assessments creates extended approval timelines for next-generation molecules. Stakeholders must monitor regulatory calibration between health-driven restriction and industrial growth targets as formulation decisions lock in multi-year supply contracts.
Market Dynamics
China's dual carbon policy framework is compressing margins for fermentation-based manufacturers while accelerating capital deployment into bioprocess upgrades. SAMR enforcement of GB 2760 usage limits and MEE emissions standards creates simultaneous compliance pressures that reshape facility economics.
Growth Catalysts
- Reformulation mandates:Beverage bottlers face consumer pressure and retail channel requirements to reduce sugar content, expanding procurement of heat-stable non-caloric alternatives for pasteurized products.
- Shandong biotech clustering:Concentrated starch processing and fermentation infrastructure in this province generates feedstock cost advantages that attract downstream formulators.
- GB standards harmonization:SAMR alignment of food additive regulations with international Codex frameworks reduces export friction for domestic manufacturers targeting Southeast Asian markets.
Market Restraints
- Corn price volatility:Starch feedstock costs fluctuate with grain procurement cycles and import dependency, compressing margin predictability for fermentation-based sweeteners.
- MEE emissions compliance:Carbon intensity caps on bioprocess facilities force capital-intensive retrofits or biomass energy transitions that extend payback periods.
- Stevia extraction yield limits:Natural leaf-based production faces agronomic constraints on rebaudioside concentration that synthetic chemistry bypasses.
Strategic Opportunities
- Western province expansion:Sichuan and Shaanxi fermentation capacity remains underdeveloped relative to coastal demand, offering greenfield sites with lower land and energy costs.
- Novel molecule pipelines:NMPA pre-submission pathways for next-generation sweeteners enable first-mover positioning ahead of GB 2760 schedule updates.
- Carbon credit monetization:Dual carbon policy compliance generates tradable emissions offsets that improve project finance terms for low-carbon bioprocess investments.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization expertise concentrates in Shandong and Jiangsu, creating recruitment bottlenecks for interior province facilities.
- Multi-agency approval synchronization:SAMR safety assessments, MEE environmental permits, and NMPA novel food registrations operate on uncoupled timelines that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Sweetener Market |
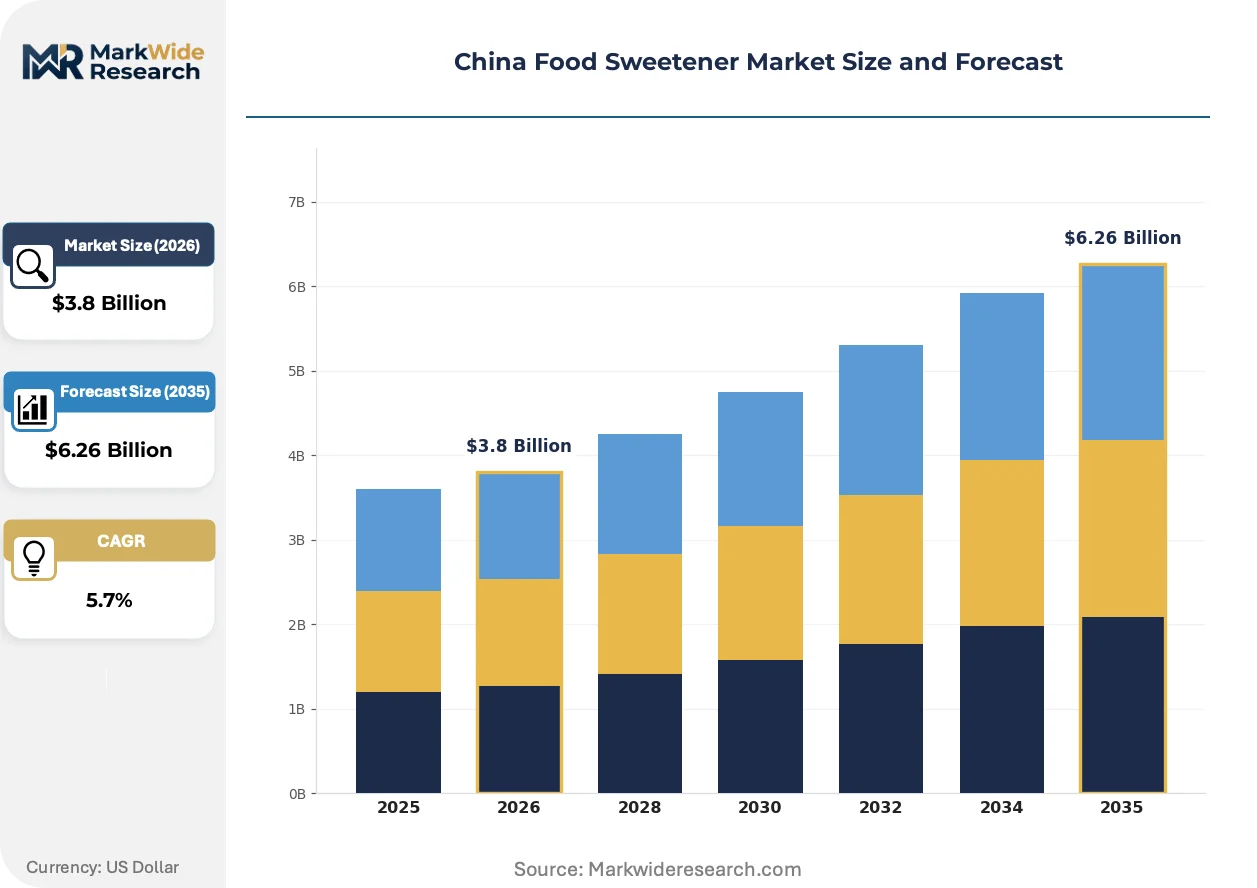
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saccharin, Aspartame, Sucralose, Acesulfame K Application: Beverages, Bakery Products, Dairy, Confectionery Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Retailers, Households |
| Companies Covered | Shandong Newnature Biotechnology Co., Ltd., Shandong Benyue Biological Technology Co., Ltd., Shandong Sanyuan Biotech Co., Ltd., Cargill, Incorporated, Archer Daniels Midland Company, Sunwin Stevia International, Inc., Ingredion Incorporated, Tate & Lyle Plc, Shandong Futaste Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Sweetener Market Strategic Shifts
Bioprocess intensification and regulatory tightening are converging to redefine manufacturing economics. Technology migration, compliance architecture, and procurement rationalization represent three vectors of structural change.
Continuous fermentation systems are migrating from batch processing to integrated bioreactor configurations with real-time metabolite monitoring. Large beverage formulators in Guangdong and Zhejiang are piloting these installations to reduce cycle times and contamination risk. The technology is migrating from pharmaceutical contract manufacturing into food-grade sweetener production, compressing capital requirements per unit output.
SAMR implementation of GB 2760-2024 revised schedules tightens maximum usage levels for certain synthetic sweeteners in dairy and confectionery applications. Manufacturers must reformulate existing product lines or pursue novel molecule approvals through NMPA extended safety protocols. Bakery segments face the steepest concentration constraints and are accelerating blends incorporating multiple lower-dose compounds.
Beverage sector procurement is consolidating supplier relationships from fragmented distributor networks toward direct mill contracts with Shandong fermentation facilities. This disintermediation transfers inventory risk to manufacturers while securing volume commitments for capacity planning. The pattern is most visible in carbonated soft drink and ready-to-drink tea categories where formulation consistency requirements dominate sourcing decisions.
China Food Sweetener Market Segmentation
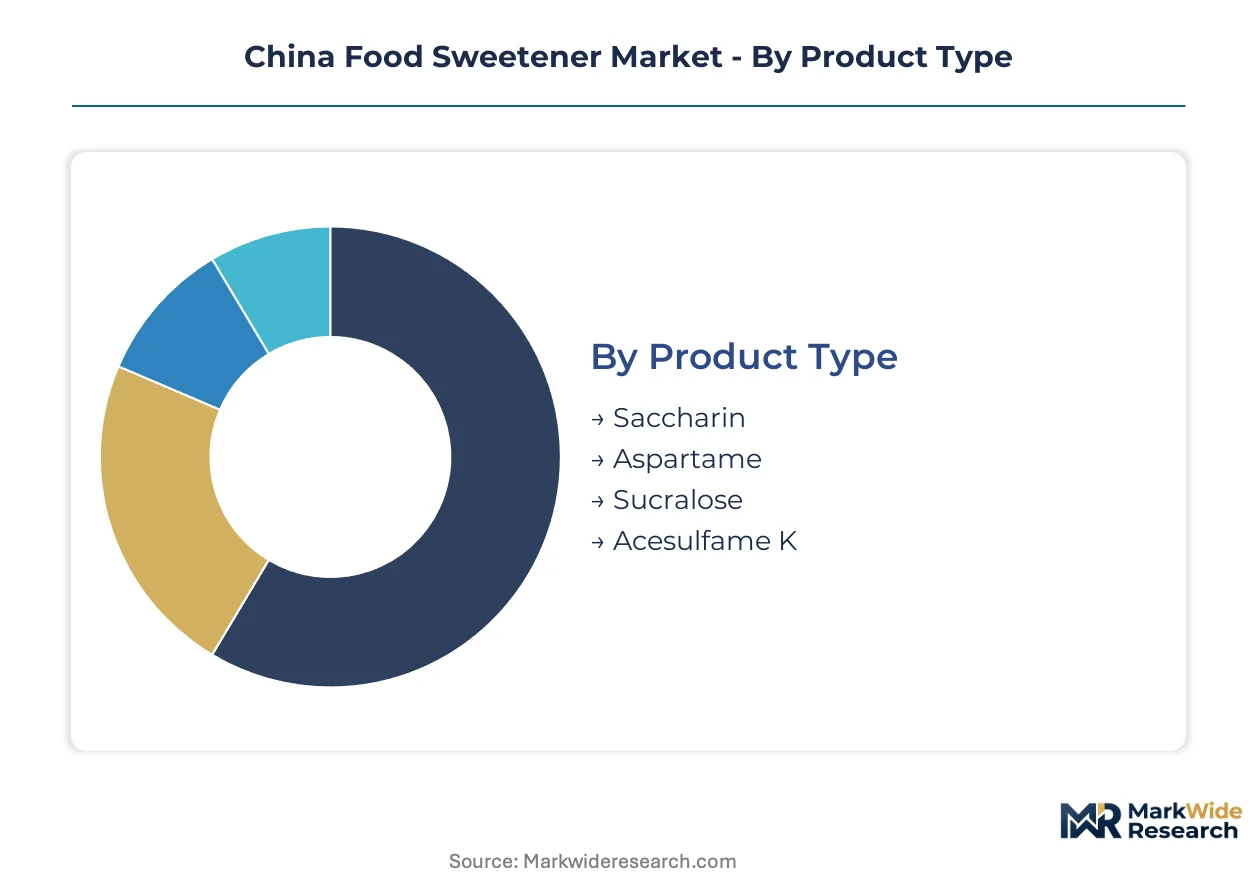
Sweetener procurement patterns vary sharply across downstream channels in China, with beverage bottlers demanding liquid formats optimized for high-speed lines while bakeries prioritize precise dosing control. Segmentation reveals how formulation requirements and regulatory constraints reshape supplier selection criteria across distinct buyer archetypes.
Product Type:
After-sales technical support intensity diverges substantially across synthetic chemistry platforms, with fermentation-derived molecules requiring sustained bioprocess troubleshooting while chemically synthesized alternatives need less ongoing engineering intervention.
- Sucralose:Chlorinated disaccharide derivative delivers 600x sucrose sweetness intensity with exceptional thermal stability above 200°C. Demand concentrates in Guangdong pasteurized beverage facilities where heat resistance during tunnel sterilization is non-negotiable. Reformulation programs at carbonated soft drink bottlers are expanding procurement volumes for this molecule.
- Acesulfame K:Potassium salt of 6-methyl-1,2,3-oxathiazine-4(3H)-one 2,2-dioxide provides 200x sweetness with synergistic blending properties. Shandong fermentation clusters supply bulk quantities to dairy processors in Jiangsu seeking cost-optimized sweetness enhancement in flavored milk applications. Dual carbon compliance costs are compressing margins for domestic manufacturers of this compound.
- Saccharin:Benzoic sulfimide with 300x sweetness intensity faces GB 2760 concentration caps in confectionery applications.
- Aspartame:Dipeptide methyl ester requires cold-chain distribution and shows thermal degradation above 80°C, limiting bakery penetration.
By volume, Sucralose leads procurement among Shandong fermentation facilities. By growth pace, Acesulfame K is climbing fastest as dairy reformulation accelerates.
Application:
Cost tier stratification separates premium positioning in health-oriented beverage segments from commodity procurement in mass-market bakery applications, with margin capture varying fourfold across these end-use categories.
- Beverages:High-speed bottling lines in Zhejiang and Guangdong provinces consume liquid sweetener concentrates at scale, with pasteurization requirements favoring heat-stable molecules. Ready-to-drink tea formulators are driving fastest segment expansion as sugar reduction mandates tighten.
- Bakery Products:Precise dosing requirements and Maillard reaction compatibility demand granular formats with uniform particle size distribution. Shandong ingredient distributors service pan-China bakery chains with blend formulations optimized for oven stability.
- Dairy:Flavored milk and yogurt applications require cold-soluble powder formats with clean taste profiles masking protein off-notes.
- Confectionery:Hard candy and chewing gum segments prioritize hygroscopic stability and sustained release characteristics in tablet and granular forms.
Beverage applications command the steepest volume growth trajectory, while bakery retains the deepest supplier relationship stickiness due to reformulation validation cycles.
Form:
Customer type differentiation separates industrial buyers seeking bulk liquid tanker deliveries from retail channel operators requiring consumer-portable packaging configurations.
- Liquid:Concentrated aqueous solutions enable direct injection into beverage mixing tanks without dissolution stages, reducing processing time for high-volume bottlers.
- Powder:Fine-milled particles below 100 mesh optimize dispersion in dry mix applications and support precise blending in bakery premix operations.
- Granular:Free-flowing crystalline structure prevents caking during storage and facilitates volumetric dosing in confectionery manufacturing.
- Tablet:Compressed single-serve formats target household and foodservice segments requiring portion control without measurement equipment.
Liquid formats dominate industrial procurement scale, while tablet configurations are expanding most quickly in e-commerce direct-to-consumer channels.
End User:
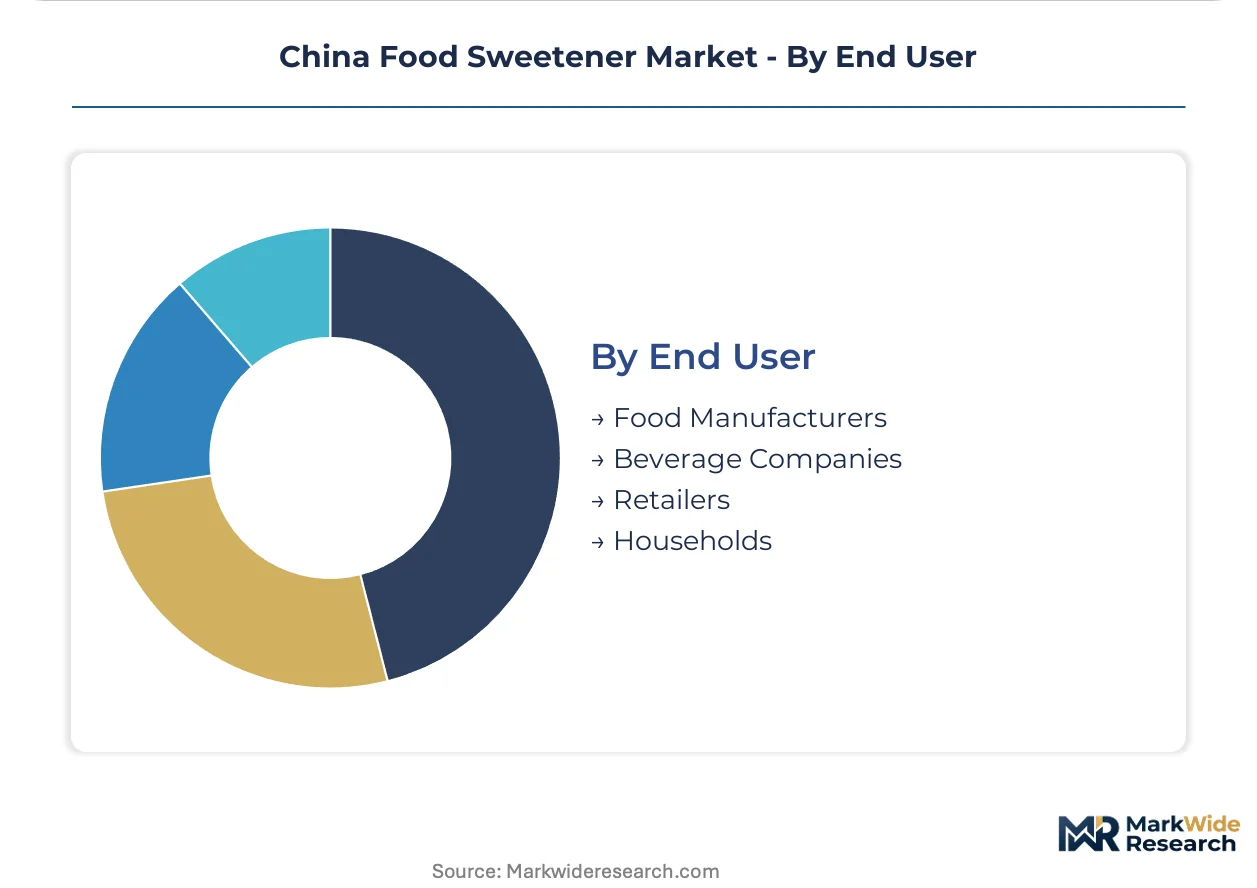
Supply concentration patterns concentrate manufacturing relationships around Shandong fermentation clusters for beverage companies, while food manufacturers maintain more distributed sourcing footprints across multiple provinces.
- Food Manufacturers:Bakery, confectionery, and processed food producers require multi-molecule portfolios with technical formulation support from ingredient distributors.
- Beverage Companies:Carbonated soft drink and ready-to-drink tea bottlers drive procurement consolidation toward direct mill contracts with fermentation facilities.
- Retailers:Private label sweetener products for supermarket chains demand cost-optimized sourcing with packaging flexibility for shelf-ready presentation.
- Households:Consumer-packaged tabletop sweeteners represent the smallest volume segment but highest per-unit margin pool in the channel structure.
Beverage companies anchor procurement volume, with retailers representing the steepest expansion trajectory as private label penetration deepens in tier-two cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy framework and provincial industrial clustering incentives are redistributing food sweetener production capacity across coastal and interior provinces. SAMR regulatory harmonization with international standards is accelerating regional specialization patterns.
Shandong Province
Beverage bottlers in Qingdao and Yantai drive concentrated demand for heat-stable sucralose and acesulfame K. MEE emissions standards force fermentation facilities to retrofit with biomass energy systems or carbon capture infrastructure. The Shandong Peninsula biotech corridor hosts integrated starch-to-sweetener processing clusters that supply downstream formulators across northern China.
Jiangsu Province
Dairy processors in Suzhou and Wuxi expand procurement of acesulfame K for flavored milk reformulation programs. GB 2760-2024 concentration caps on synthetic sweeteners in dairy applications push manufacturers toward multi-molecule blend strategies. The Yangtze River Delta chemical engineering base attracts fermentation capacity expansions seeking proximity to Shanghai port logistics.
Guangdong Province
Carbonated soft drink and ready-to-drink tea bottlers in Guangzhou and Shenzhen consume liquid sweetener concentrates at industrial scale. SAMR enforcement of sugar reduction labeling requirements tightens formulation specifications for pasteurized beverages. The Pearl River Delta manufacturing belt integrates high-speed bottling lines with direct mill contracts from Shandong fermentation facilities.
Zhejiang Province
Hangzhou-based beverage formulators pilot continuous fermentation systems with real-time metabolite monitoring to reduce cycle times. NMPA pre-submission pathways for novel sweeteners enable first-mover positioning ahead of GB 2760 schedule updates. The province's pharmaceutical contract manufacturing expertise migrates into food-grade bioprocess applications.
Sichuan-Chongqing
Western province fermentation capacity remains underdeveloped relative to coastal demand, offering greenfield sites with lower land and energy costs. Dual carbon policy compliance generates tradable emissions offsets that improve project finance terms for low-carbon bioprocess investments. Chengdu's emerging biotech zone recruits Shandong-trained fermentation engineering talent for interior province facility development.
China Food Sweetener Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement relationships. The vendor base organizes around fermentation-integrated manufacturers, international trading houses with domestic partnerships, and natural extraction specialists. Strategic archetypes include upstream feedstock controllers, downstream formulation partners, and regulatory navigation specialists. Capacity expansion and direct mill contracting represent dominant competitive moves as beverage bottlers consolidate supplier relationships.
Within the domestic fermentation tier, Shandong Newnature Biotechnology Co., Ltd. and Shandong Benyue Biological Technology Co., Ltd. represent integrated starch-to-sweetener processors controlling input costs through captive supply chains. Among international trading houses with China market presence, Cargill, Incorporated and Archer Daniels Midland Company exemplify archetypes built on bulk distribution networks and supply partnerships with coastal beverage bottlers. These named entities anchor competitive positioning without exclusive claim to technology leadership or segment dominance.
| Leading Market Players |
|---|
| Shandong Newnature Biotechnology Co., Ltd. |
| Shandong Benyue Biological Technology Co., Ltd. |
| Shandong Sanyuan Biotech Co., Ltd. |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Sunwin Stevia International, Inc. |
| Ingredion Incorporated |
| Tate & Lyle Plc |
| Shandong Futaste Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's integrated starch-to-sweetener fermentation clusters concentrate upstream capacity, granting domestic manufacturers leverage over downstream pricing negotiations with beverage bottlers in Guangdong and Zhejiang. GB 2760 compliance costs and dual carbon retrofit requirements feed into margin structures, compressing price flexibility for fermentation-derived molecules while chemical synthesis alternatives retain cost stability.
Pricing Analysis
Certification level creates the primary spread between food-grade and pharmaceutical-grade sweetener tiers, with SAMR-registered facilities commanding premiums over unregistered competitors. Three-tier pricing structure across premium, standard, and economy levels separates multinational brands from domestic bulk suppliers and gray-market distributors. Cost compression in standard-grade sucralose is intensifying because Shandong facilities face MEE emissions compliance investments. Beverage companies exhibit lowest price sensitivity due to reformulation lock-in effects, while bakery premix distributors negotiate aggressively on volume.
Supply Chain Analysis
Export-control regimes on bioprocess equipment from Germany and the United States constrain technology transfer into western Chinese provinces, limiting fermentation capacity expansion outside Shandong-Jiangsu corridors. Supply concentrates in China for fermentation-derived molecules, with India and Thailand contributing natural stevia extraction capacity. Corn starch feedstock draws from Heilongjiang and Jilin grain belts, while chlorinated sucrose precursors hinge on specialized chemical intermediates from Jiangsu. Single-source vulnerability runs through Shandong's concentrated fermentation engineering talent pool. Distribution runs through direct mill contracts with coastal beverage bottlers, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable advantages. SAMR registration timelines and GB 2760 compliance architectures embed switching costs that protect incumbent positions.
For Market Incumbents: Entrench through backward integration into captive corn starch processing in Shandong and certification investment for NMPA novel molecule pre-submissions. Emerging biotech entrants from Sichuan threaten coastal market share as western provinces recruit fermentation talent. Capacity addition in underdeveloped interior regions extends geographic moats while carbon credit monetization improves project returns. For New Entrants and Emerging Players: Pursue white-space positioning in Sichuan-Chongqing greenfield fermentation sites where land and energy costs undercut coastal benchmarks. Dairy reformulation programs in Jiangsu represent the most penetrable segment given acesulfame K demand acceleration. A go-to-market angle anchored to dual carbon compliance—biomass energy integration and tradable emissions offsets—differentiates proposals to sustainability-minded bottlers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement rationalization toward direct mill contracts favors scaled fermentation operators over fragmented distributors. Target acquisition archetypes include Shandong-based integrated processors with SAMR-registered product portfolios and unexploited western expansion rights. The signal to watch is NMPA approval velocity for next-generation sweeteners, which would reset competitive positioning ahead of GB 2760 schedule updates.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Energy Transition | Dual carbon compliance generates tradable emissions offsets that improve project finance terms for Shandong facilities. |
| Continuous Fermentation Deployment | Real-time metabolite monitoring systems from Zhejiang pharmaceutical contract manufacturers reduce cycle times and contamination risk. |
| Direct Mill Contracting | Disintermediation transfers inventory risk to manufacturers while securing volume commitments from Guangdong beverage bottlers. |
| Novel Molecule Pre-Submission | NMPA early engagement pathways enable first-mover positioning before GB 2760 schedule updates restrict synthetic alternatives. |
| Western Province Capacity Buildout | Sichuan greenfield sites with lower land and energy costs exploit underdeveloped fermentation infrastructure relative to coastal demand. |
Study Parameters
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged fermentation plant managers, beverage procurement leads at Guangdong bottlers, SAMR regulatory affairs specialists, and Shandong ingredient distribution channel partners. Secondary sources incorporated SAMR GB standard publications, MEE emissions compliance disclosures, NMPA novel food registration databases, and provincial biotech cluster development filings. Bottom-up facility capacity assessments and top-down consumption estimates triangulate market sizing.
Calibration against historical CAGRs from adjacent fermentation-derived ingredient categories shapes the projection framework across the analysis window. Segmentation dimensions span product type, application, form factor, and end-user archetype, with regional regulatory cluster intensity as an industry-specific overlay. CAGRs derive from trend extrapolation moderated by policy inflection assumptions. Forecast inputs include corn price volatility cycles, MEE enforcement trajectory, and beverage reformulation program commitments.
Macroeconomic conditions sit as an overlay; deviation in grain procurement costs, energy pricing, or carbon credit market liquidity would shift the trajectory. Forecasts reflect documented assumptions about SAMR regulatory pacing and dual carbon implementation intensity. Cross-checking against customs trade data for sweetener intermediate imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Stevia Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
South Korea Allulose Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
India Food Sweetener Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Xylitol Injection Market
Sweeteners
Sucrose Esters Market