
 Feed Flavors and Sweeteners Market | 2026-2036
Feed Flavors and Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Flavors and Sweeteners Market Analysis
FAMI-QS certification is reorganizing supplier eligibility across the European feed additive space, forcing reformulation investments and third-party audit cycles. Symrise leverages its integrated taste-modulation platform to sustain premium positioning in swine and poultry palatants. Kerry Group anchors Western European supply through its nutritional solutions division, while Pancosma competes on synthetic and nature-identical molecule specialization.
Feed flavors and sweeteners comprise volatile aromatic compounds, high-intensity sweetening agents, and taste-modulating substances designed to enhance voluntary feed intake and mask bitter pharmaceutical or nutritional actives in compound feeds. Manufacturing relies on spray-drying encapsulation and lipid-matrix coating to protect thermolabile molecules during pelleting at temperatures exceeding 80°C. Natural flavors and sweeteners command expanding share as livestock producers face retailer-driven antibiotic-reduction commitments that elevate feed palatability requirements. Powder and liquid forms dominate volume, though granular formats are gaining traction in automated premix operations where dust control and flowability determine blending precision.
EFSA, the EU Green Deal framework, and REACH collectively govern molecular safety thresholds, environmental release limits, and novel ingredient authorization timelines across European supply chains. The US FDA and EPA maintain parallel jurisdiction over GRAS self-affirmation pathways and manufacturing effluent standards respectively. Stakeholders must monitor evolving residue-definition protocols and regional divergence in clean-label claim enforceability to anticipate reformulation costs and market-access barriers.
Market Dynamics
EU Green Deal's Farm to Fork strategy is compressing additive approval timelines while Brazil's integrated poultry sector concentrates procurement power, forcing suppliers to absorb reformulation costs and accelerate third-party certification cycles simultaneously.
Growth Catalysts
- Antibiotic-reduction mandates:Retailer-driven commitments across European livestock chains elevate feed palatability requirements, expanding demand for masking agents that improve voluntary intake in medicated rations.
- EFSA novel food pathways:Streamlined safety assessments for nature-identical molecules accelerate commercialization timelines for synthetic sweeteners targeting swine and poultry segments.
- Spray-drying encapsulation:Advances in lipid-matrix coating protect thermolabile compounds during high-temperature pelleting, enabling broader application in extruded feed formats.
Market Restraints
- REACH environmental release limits:Stringent effluent standards for volatile aromatic compound manufacturing elevate compliance costs and extend facility permitting timelines in European production hubs.
- Feed-grade sweetener concentration:Supply of high-intensity sweetening agents clusters among specialized chemical producers, creating vulnerability to input price volatility and allocation constraints.
- Thermal degradation ceiling:Natural flavor compounds face stability limitations above 80°C pelleting temperatures, restricting their deployment in certain compound feed processes.
Strategic Opportunities
- Automated premix operations:Granular format adoption in robotic blending systems creates demand for dust-controlled, flow-optimized palatant delivery systems with precise dosing compatibility.
- FAMI-QS certification gaps:Supplier eligibility reorganization under revised feed safety schemes opens positioning windows for audit-ready manufacturers in Eastern European markets.
- Taste-modulation convergence:Integration of bitter-masking technology with pharmaceutical actives addresses expanding medicated feed segments in intensive livestock systems.
Industry Challenges
- Reformulation talent scarcity:Shortage of flavor chemists with feed-specific stability expertise delays product adaptation cycles as regulatory residue definitions evolve.
- Third-party audit intensity:Compressed FAMI-QS recertification timelines strain quality assurance departments and elevate ongoing compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Flavors and Sweeteners Market |
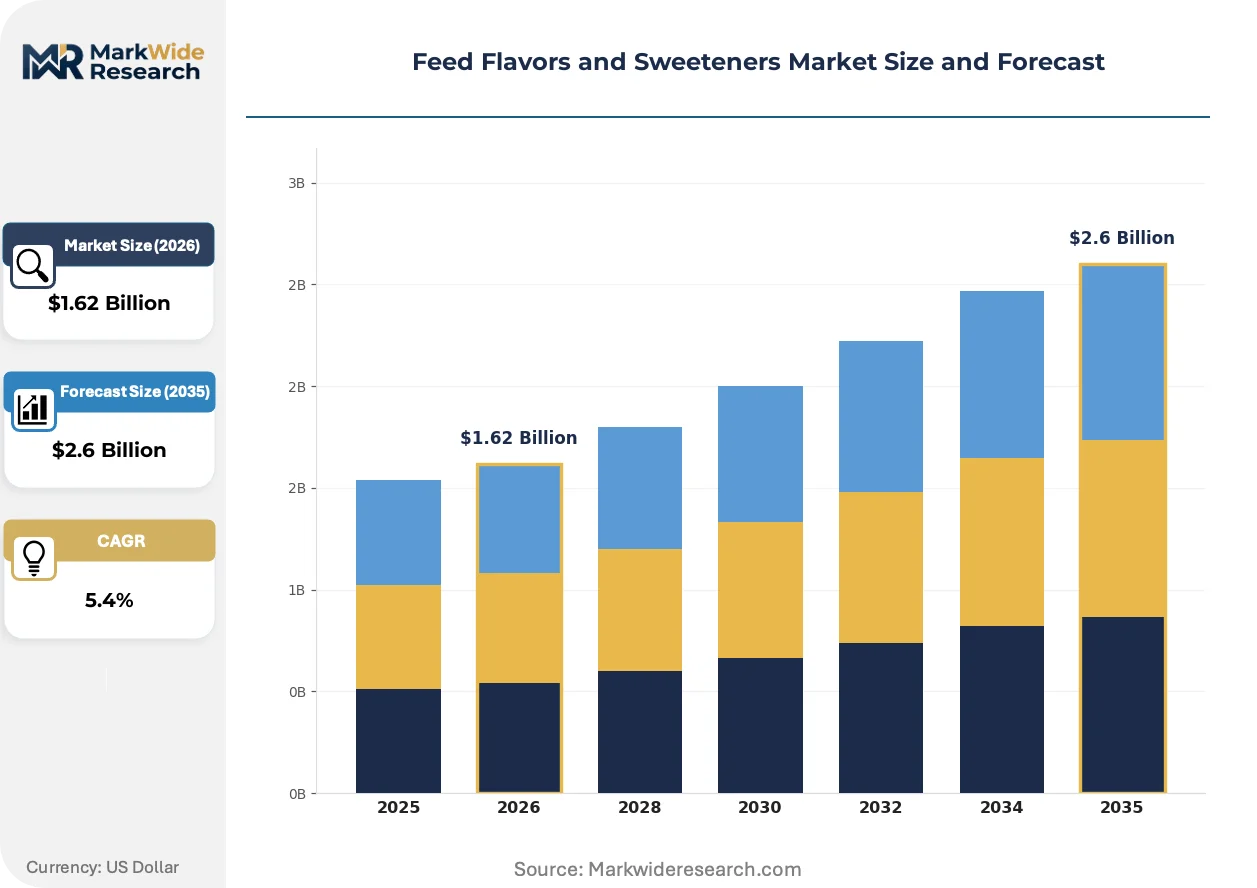
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Sweeteners, Flavor Enhancers Application: Animal Feed, Aquaculture, Pet Food, Livestock Form: Liquid, Powder, Granular, Pellet End User: Feed Manufacturers, Livestock Producers, Aquaculture Farmers, Pet Food Companies |
| Companies Covered | Symrise, Pancosma, Kerry Group, DuPont, Alltech, ADM, Givaudan, International Flavors & Fragrances, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Flavors and Sweeteners Market Emerging Trajectories
Active reformulation investments are reshaping competitive positioning as natural extracts gain formulation share and encapsulation technologies advance thermal protection standards across compound feed manufacturing.
Lipid-matrix microencapsulation is supplanting conventional spray-drying for thermolabile flavor compounds, enabling broader deployment in high-temperature pelleting operations. Poultry integrators in Brazil and Thailand are adopting these systems at accelerated procurement cycles. This migration is compressing margins for legacy coating suppliers while rewarding integrated taste-modulation platforms with captive encapsulation capabilities.
REACH authorization requirements for novel molecular entities are extending pre-market safety dossier preparation timelines. European compound feed manufacturers face reformulation lock-in risks as pending substance evaluations create regulatory uncertainty. Nature-identical sweetener categories bear the highest compliance burden, with suppliers accelerating parallel dossier submissions to ECHA and EFSA.
Buyer concentration among vertically integrated protein producers is compressing supplier negotiation leverage and elongating payment terms. Direct procurement relationships between Brazilian poultry processors and flavor houses are displacing traditional distributor intermediaries. This channel consolidation is most pronounced in São Paulo state's integrated production corridor, where three processors account for dominant volume allocation.
Feed Flavors and Sweeteners Market Segmentation
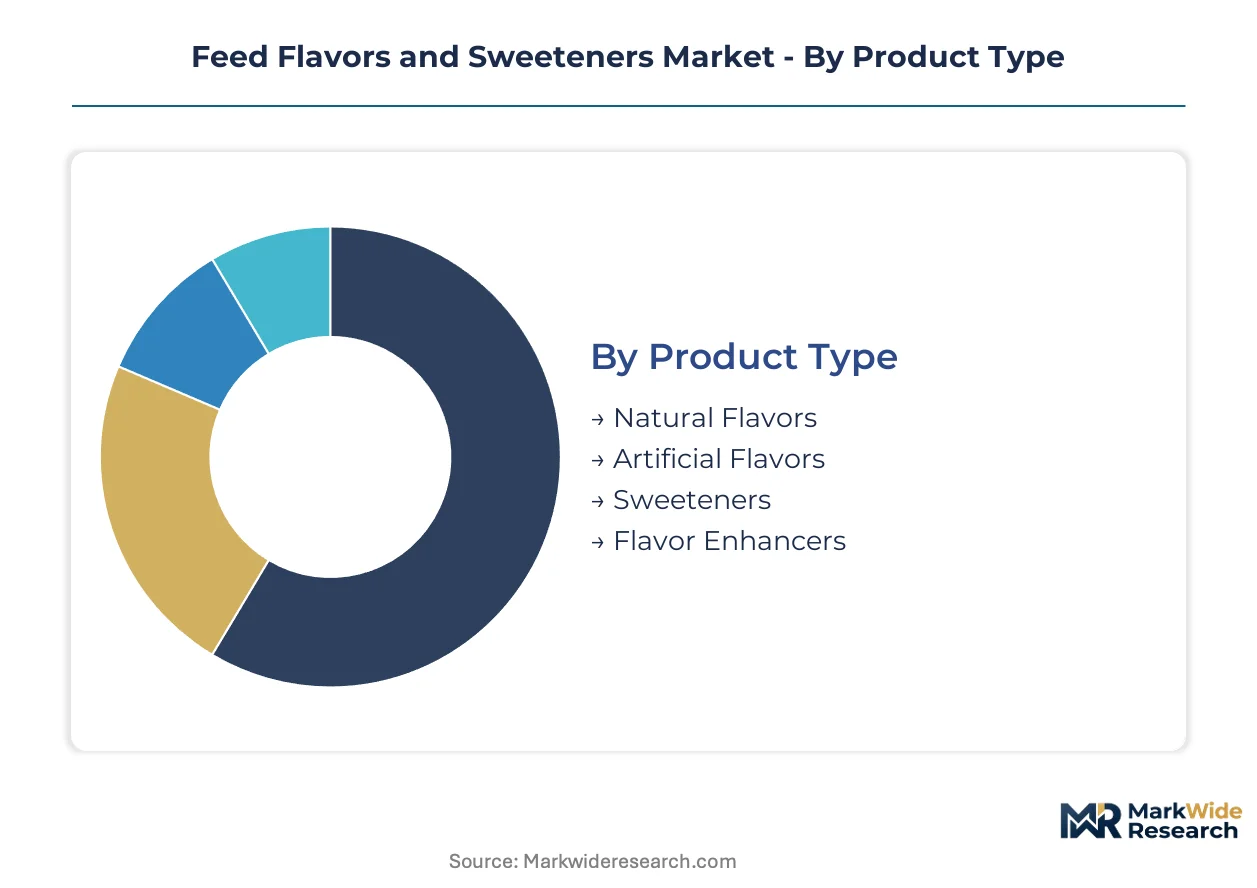
Feed flavor and sweetener suppliers configure product portfolios around thermal stability requirements, species-specific palatability thresholds, and automated dosing compatibility. Segment boundaries blur as encapsulation technologies enable cross-format deployment and species-adjacent formulations.
Product Type:
Margin pools concentrate in synthetic molecule platforms where manufacturing scale and regulatory dossier amortization create defensible cost positions.
- Natural Flavors:Botanical extracts and essential oil distillates deliver volatile aromatic compounds for masking bitter pharmaceutical actives. Poultry integrators in Brazil's São Paulo corridor specify these for antibiotic-free ration programs under retailer-driven commitments.
- Sweeteners:High-intensity sweetening agents including saccharin, neohesperidin dihydrochalcone, and stevia glycosides enhance voluntary feed intake in medicated swine rations. Demand concentrates in European livestock chains facing EFSA novel food pathway timelines for nature-identical approvals.
- Artificial Flavors:Synthetic aromatic compounds manufactured through chemical synthesis offer standardized potency and extended shelf stability.
- Flavor Enhancers:Taste-modulating substances amplify inherent feed palatability without contributing standalone flavor profiles.
The dominant share belongs to Sweeteners, while Natural Flavors is closing the gap fastest.
Application:
Species-specific digestive physiology and production intensity determine formulation specifications and dosing economics across application categories.
- Animal Feed:Compound feed manufacturing for swine, poultry, and ruminant species represents the foundational demand base. Pelleting temperatures exceeding 80°C drive encapsulation technology selection across European and Brazilian production hubs.
- Aquaculture:Water-soluble flavor systems for shrimp and finfish feeds require leaching-resistant delivery mechanisms. Asian production clusters in Thailand and Vietnam specify lipid-matrix coatings for extruded aquafeed formats.
- Livestock:Intensive production systems for dairy and beef cattle utilize molasses-based sweeteners and fermentation-derived flavor precursors.
- Pet Food:Premiumization trends in companion animal nutrition elevate palatant complexity for kibble and wet food applications.
Animal Feed commands the volume base, though Aquaculture demonstrates the steepest expansion trajectory.
Form:
Physical format selection hinges on blending equipment compatibility, dust exposure regulations, and thermal processing requirements in downstream feed manufacturing.
- Powder:Spray-dried or ground particulate formats dominate legacy premix operations. Dust generation during handling necessitates respiratory protection protocols and containment infrastructure.
- Liquid:Pumpable concentrates enable precise volumetric dosing in continuous mixing systems. Brazilian integrated poultry processors favor liquid delivery for automated ration preparation.
- Granular:Dust-controlled, free-flowing particles suit robotic blending systems where flowability determines dosing precision. REACH environmental release limits accelerate granular adoption in European facilities.
- Pellet:Compressed flavor cores withstand mechanical stress during feed pelleting without premature release.
Powder retains installed-base dominance, yet Granular is gaining share fastest among automated operations.
End User:
Procurement sophistication and formulation control vary sharply between integrated protein producers and independent compound feed manufacturers.
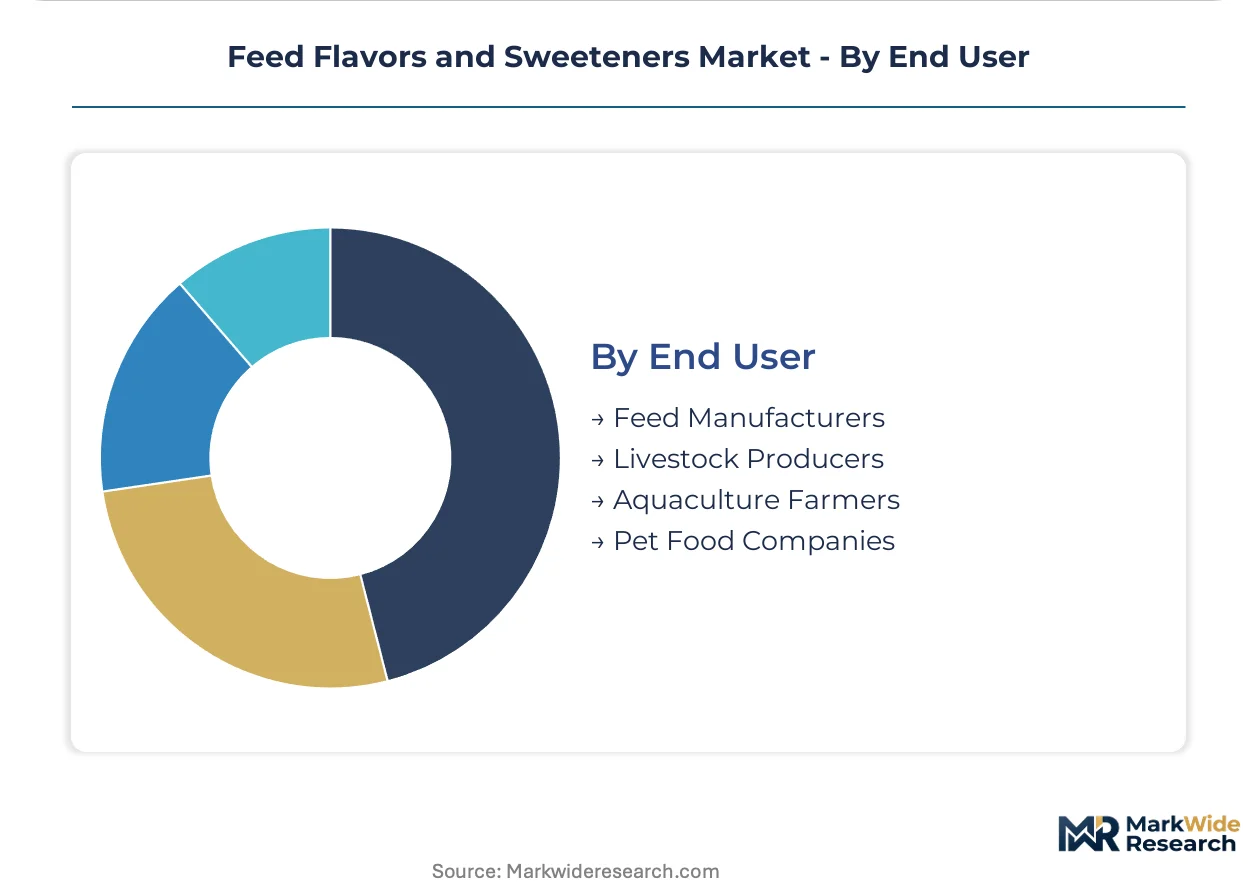
- Feed Manufacturers:Compound feed mills serving fragmented livestock producer bases require cost-optimized, multi-species compatible flavor systems. FAMI-QS certification requirements compress supplier eligibility across European procurement.
- Livestock Producers:Vertically integrated protein processors in Brazil's poultry sector conduct direct flavor house negotiations, displacing traditional distributor intermediaries.
- Aquaculture Farmers:Shrimp and finfish producers in Southeast Asian clusters specify species-specific palatant systems with water stability requirements.
- Pet Food Companies:Branded pet food manufacturers prioritize sensory differentiation for premium positioning in retail channels.
Feed Manufacturers anchor volume demand, while Livestock Producers are consolidating procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertically integrated poultry processors in Brazil's São Paulo corridor wield dominant procurement leverage, while European compound feed manufacturers navigate compressed additive approval timelines under the EU Green Deal. Feed flavor and sweetener suppliers must simultaneously absorb reformulation costs, accelerate FAMI-QS certification cycles, and absorb elongated payment terms from concentrated buyer bases across both markets.
Brazil
Integrated poultry processors in São Paulo state specify natural flavor systems for antibiotic-free ration programs under retailer-driven commitments. ANVISA maintains parallel jurisdiction with Ministry of Agriculture oversight for feed additive safety assessments. Direct procurement relationships between three dominant processors and flavor houses displace traditional distributor intermediaries in the state's production corridor.
Germany
Compound feed manufacturers serving fragmented livestock producer bases require cost-optimized, multi-species compatible flavor systems with FAMI-QS certification. EFSA novel food pathways govern nature-identical sweetener approvals, while REACH authorization requirements extend pre-market safety dossier timelines. Production hubs in North Rhine-Westphalia face elevated compliance costs from stringent effluent standards for volatile aromatic compound manufacturing.
United States
Swine and poultry integrators specify high-intensity sweetening agents for medicated rations amid FDA oversight of GRAS self-affirmation pathways. EPA jurisdiction over manufacturing effluent standards elevates facility permitting timelines in Midwestern production clusters. Iowa and North Carolina feed mills drive granular format adoption for automated premix operations with robotic blending compatibility.
China
Aquaculture feed manufacturers in Guangdong and Fujian provinces specify water-stable flavor systems for extruded shrimp and finfish feeds. NMPA and Ministry of Agriculture standards govern feed additive safety thresholds and environmental release limits. Yangtze River Delta production clusters are migrating toward lipid-matrix microencapsulation technologies for thermolabile compounds in high-temperature pelleting.
Thailand
Shrimp feed processors specify leaching-resistant palatant delivery mechanisms for extruded aquafeed formats under national agricultural standards. Ministry of Agriculture and Cooperatives oversight converges with export-market residue requirements from EU and US buyers. Bangkok-centered production clusters accelerate procurement cycles for encapsulated flavor systems as integrated aquaculture operations expand.
Feed Flavors and Sweeteners Market Vendor Landscape
Player mix skews toward integrated taste-modulation platforms with captive encapsulation capabilities and specialized synthetic molecule manufacturers with regulatory dossier expertise. Market structure concentrates procurement leverage among vertically integrated protein producers, compressing supplier negotiation power and elongating payment terms. Three archetypes dominate: integrated nutritional solutions providers, nature-identical molecule specialists, and captive encapsulation technology owners. Competitive moves center on FAMI-QS certification acceleration and lipid-matrix coating capacity expansion.
Within the integrated platform tier, Symrise leverages its taste-modulation capabilities across swine and poultry palatants, while Kerry Group anchors Western European supply through its nutritional solutions division. Pancosma occupies a position among nature-identical molecule specialists competing on synthetic and regulatory dossier expertise. These three exemplify divergent strategic archetypes responding to compressed approval timelines and buyer concentration pressures.
| Leading Market Players |
|---|
| Symrise |
| Pancosma |
| Kerry Group |
| DuPont |
| Alltech |
| ADM |
| Givaudan |
| International Flavors & Fragrances |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for high-intensity sweetening agents tie Brazilian poultry integrators to volatile aromatic compound suppliers, compressing margin buffers as REACH compliance costs escalate and buyer concentration shifts pricing power toward São Paulo's vertically integrated processors.
Pricing Analysis
Cost-plus contracts indexed to benzene and petrochemical feedstock benchmarks dominate synthetic sweetener procurement, with premium tiers separating FAMI-QS-certified suppliers from uncertified competitors. Price differentiation hinges on encapsulation technology grade and volume scale, with automated premix-compatible granular formats commanding fifteen to twenty percent premiums over legacy powder. Pricing pressure stems from Brazilian buyer consolidation elongating payment terms to ninety days. Small compound feed manufacturers exhibit highest price sensitivity, while multinational protein processors absorb premiums for audit-ready supply security.
Supply Chain Analysis
Inventory compression to sixty-day cycles for thermolabile natural extracts reflects just-in-time pressures from European feed mills facing EFSA authorization delays. Manufacturing concentrates in Germany, Brazil, and China, with lipid-matrix coating capacity anchoring in North Rhine-Westphalia and Guangdong province. Raw material flows draw from Indian botanical extract suppliers, Chinese stevia glycoside processors, and Belgian petrochemical intermediates. Single-source vulnerability concentrates in neohesperidin dihydrochalcone supply. Distribution runs through direct procurement relationships displacing traditional distributor networks in São Paulo state's integrated poultry corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed flavor and sweetener incumbents face substitution pressure from in-house encapsulation investments by Brazilian poultry integrators seeking captive taste-modulation capabilities, requiring defensive repositioning across certification and technology axes.
For Market Incumbents: Consolidate FAMI-QS certification advantages by accelerating third-party audit cycles ahead of EU Green Deal implementation deadlines. Acquire lipid-matrix microencapsulation specialists in Germany or Thailand to defend against backward integration by protein processors. Lock in multi-year supply agreements with Brazilian integrators before direct flavor house negotiations displace remaining distributor intermediaries.
For New Entrants and Emerging Players: Differentiate on nature-identical molecule dossier expertise targeting EFSA novel food pathway bottlenecks delaying competitor approvals. Penetrate Eastern European compound feed manufacturers facing supplier eligibility gaps under revised feed safety schemes. Deploy automated premix-compatible granular formats as the primary go-to-market wedge against legacy powder incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration and regulatory compliance burdens favor scaled platforms with captive encapsulation capabilities and amortized dossier libraries. Target acquisition candidates with integrated taste-modulation technology and established Brazilian direct procurement relationships. Watch for inflection when ANVISA harmonizes additive approval timelines with EU standards, compressing competitive windows for nature-identical specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Lipid-Matrix Coating Capacity Expansion | Captive encapsulation technology protects thermolabile compounds during Brazilian high-temperature pelleting operations. |
| FAMI-QS Certification Acceleration | Third-party audit readiness opens procurement eligibility with European compound feed manufacturers facing supplier reorganization. |
| Direct Procurement Relationship Development | Bypassing distributor intermediaries captures margin from São Paulo poultry integrators consolidating supply base. |
| Nature-Identical Dossier Portfolio Buildout | Parallel EFSA and ECHA submissions compress approval timelines for synthetic sweetener commercialization. |
| Automated Premix Format Innovation | Granular dust-controlled delivery systems align with robotic blending adoption in European and US feed mills. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across feed flavor and sweetener value chains, including procurement directors at Brazilian poultry integrators, quality assurance managers at German compound feed mills, encapsulation technology specialists, and regulatory affairs leads navigating EFSA novel food pathways. Secondary validation drew from FAMI-QS certification databases, REACH authorization filings, ANVISA additive registrations, and trade flow records for high-intensity sweetening agents. Bottom-up volume estimates triangulated against top-down market sizing from feed production statistics and palatant inclusion rate assumptions.
Across the analysis window, forecasts segment by product type, application species, physical form, and end-user procurement sophistication, with CAGRs derived from elasticity modeling against livestock production growth and regulatory-driven reformulation cycles. Modeled inputs include pelleting temperature thresholds by feed format, EFSA approval timeline distributions for nature-identical molecules, and buyer concentration indices by regional protein sector structure.
Decision-makers should treat outputs as directional under stable regulatory trajectory assumptions; material deviation in EU Green Deal implementation pace or Brazilian real exchange rate volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Winter Melon Peel Extract Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Naringin Market