
 Sour Sugar Market | 2026-2036
Sour Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Sugar Market Analytics
Confectionery flavor chemists and acidulant technicians is reorganizing supply priorities as sour sugar formulations grow more complex. Ferrara Candy Company leverages captive acid blending capabilities to protect margin pools on sour gummy lines. Haribo anchors European production networks with specialized malic acid coating expertise. Mondelez International, Inc. competes through scaled citric acid procurement across multiple hemispheres.
Sour sugar denotes acid-coated or acid-infused sucrose and glucose substrates, typically incorporating citric acid, malic acid, tartaric acid, or fumaric acid at concentrations between one and eight percent by weight, engineered to deliver controlled pH drop and salivary stimulation in finished goods. The ingredient serves confectionery manufacturers seeking programmable sour intensity curves and extended shelf-stable tang profiles. Sour gummies within the product type dimension command premium positioning due to higher acidulant loading and specialized coating equipment requirements. Food manufacturers among end users represent the fastest-expanding demand pool, as commercial bakeries and snack houses adopt sour sugar for limited-run flavor extensions.
FDA acidulant GRAS determinations and FSSAI food additive maximum level notifications shape permissible formulation ranges and cross-border shipment compliance burdens for sour sugar suppliers. ISO 22000 and HACCP frameworks govern acid handling, cross-contamination protocols, and finished goods microbial stability in contract manufacturing environments. Stakeholders must monitor evolving acidulant threshold adjustments across multiple jurisdictions to anticipate reformulation cost impacts and qualification timeline shifts.
Market Dynamics
Acidulant procurement concentration is forcing reformulation investments across confectionery supply chains as FDA and FSSAI tighten labeling thresholds. Manufacturers now face margin compression from dual compliance burdens and specialized coating equipment requirements.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for food processing infrastructure is accelerating domestic acid blending capacity expansion. Contract manufacturers are qualifying new sour sugar lines for export markets.
- Malic acid coating expertise:Specialized equipment for controlled acid crystallization on glucose substrates is enabling programmable sour intensity curves. European confectionery houses are licensing this process technology.
- Snack house adoption:Commercial bakeries and limited-run flavor extension programs are expanding sour sugar procurement beyond traditional candy applications. Food manufacturers represent the fastest-expanding demand pool.
Market Restraints
- Citric acid input volatility:Fermentation-based citric acid supply from Chinese producers faces periodic export quota adjustments. Price swings compress margin pools for acid-dependent formulations.
- Cross-border compliance burdens:Divergent maximum level notifications between FDA GRAS determinations and FSSAI food additive rules create shipment qualification delays. Reformulation costs accumulate across jurisdictions.
- Tartaric acid substitution pressure:Synthetic tartaric acid from petroleum-derived routes competes with fermentation citric acid on cost in certain coating applications. Natural-origin positioning faces price resistance.
Strategic Opportunities
- Underpenetrated bakery segment:Sour sugar incorporation into laminated dough and filled pastry applications remains below potential. Artisan and industrial bakeries in North America lack formulation guidance.
- ISO 22000 certification tailwinds:HACCP-aligned acid handling protocols are becoming mandatory for contract manufacturing qualification. Early certification investments unlock preferred supplier status.
- Clean-label acidulant convergence:Natural fermentation-derived malic acid paired with organic glucose substrates addresses premium channel positioning. Health-conscious retailers are mandating this specification.
Industry Challenges
- Acidulant technician scarcity:Formulation chemists with pH curve engineering and salivary stimulation measurement capabilities are concentrated among legacy confectionery houses. Recruitment competition intensifies.
- Coating equipment capex intensity:Specialized fluidized bed systems for uniform acid distribution require seven-figure investments. Mid-scale manufacturers face capacity qualification barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Sugar Market |
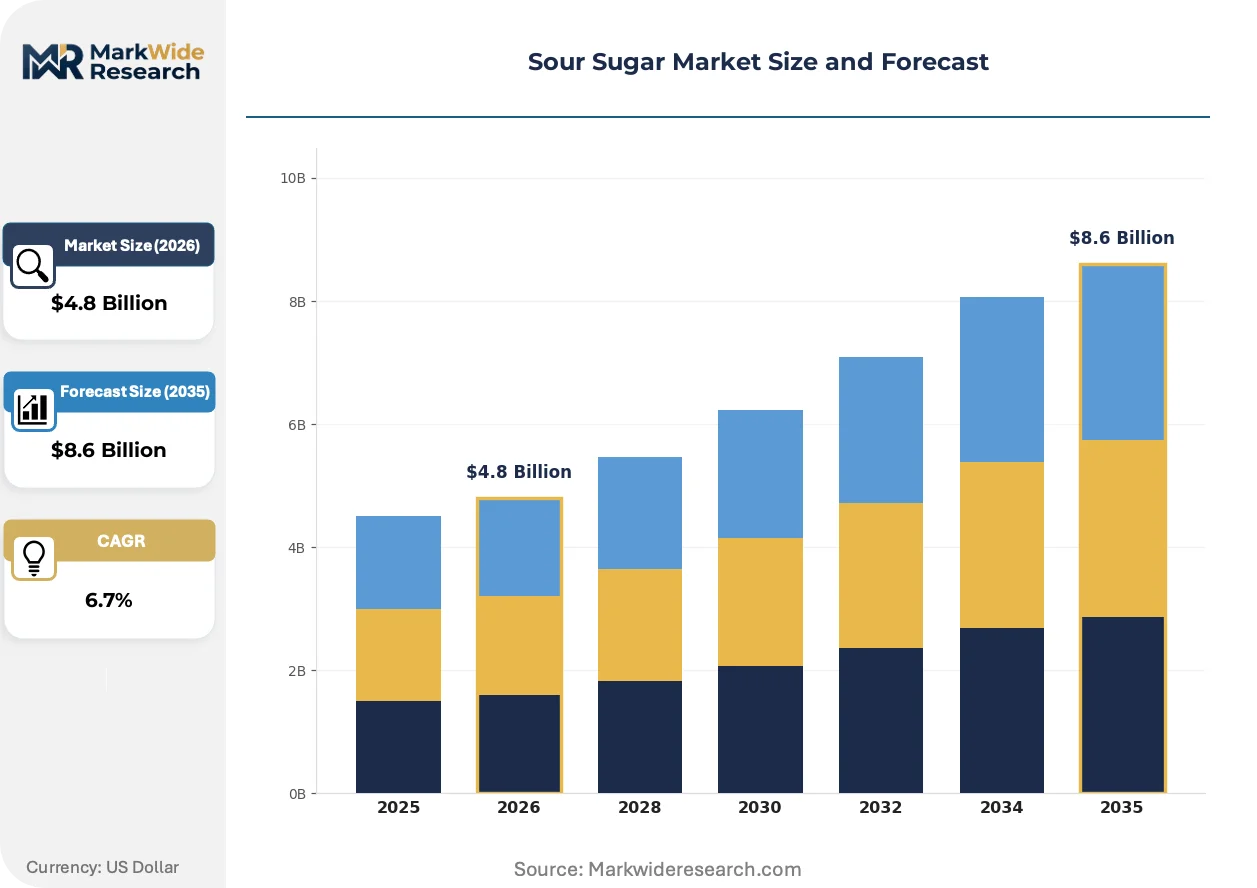
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sour Powder, Sour Syrup, Sour Crystals, Sour Gummies Application: Beverages, Confectionery, Baking, Snacks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores End User: Households, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | Ferrara Candy Company, Haribo, Mondelez International, Inc., The Hershey Company, Perfetti Van Melle, Albanese Confectionery Group, Inc., Jelly Belly Candy Company, Trolli, Tootsie Roll Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Sugar Market Evolving Landscape
Encapsulation technologies and precision acid delivery systems are reshaping how sour intensity is engineered into finished goods. These advances are compressing traditional formulation timelines.
Layered acid release microencapsulation is displacing conventional surface-coating methods for extended sour profile duration. Premium gummy manufacturers in Germany and the United States are adopting this technology at pilot scale. The approach is displacing single-acid formulations by enabling sequential citric-tartaric-malic activation curves.
EFSA additive re-evaluation protocols are tightening maximum permissible acidulant levels in children's confectionery categories. Manufacturers must submit extended toxicological dossiers for existing formulations. Sour gummy lines targeting European retail channels are responding with reduced-acid variants and alternative sensory stimulation ingredients.
Direct procurement relationships between acidulant blenders and regional candy houses are shortening traditional distribution hierarchies. Large-format retailers are mandating supplier transparency on acid sourcing and coating process documentation. This pattern is most visible in India's domestic market, where contract manufacturers bypass import distributors to secure fermentation-grade citric acid.
Sour Sugar Market Segmentation
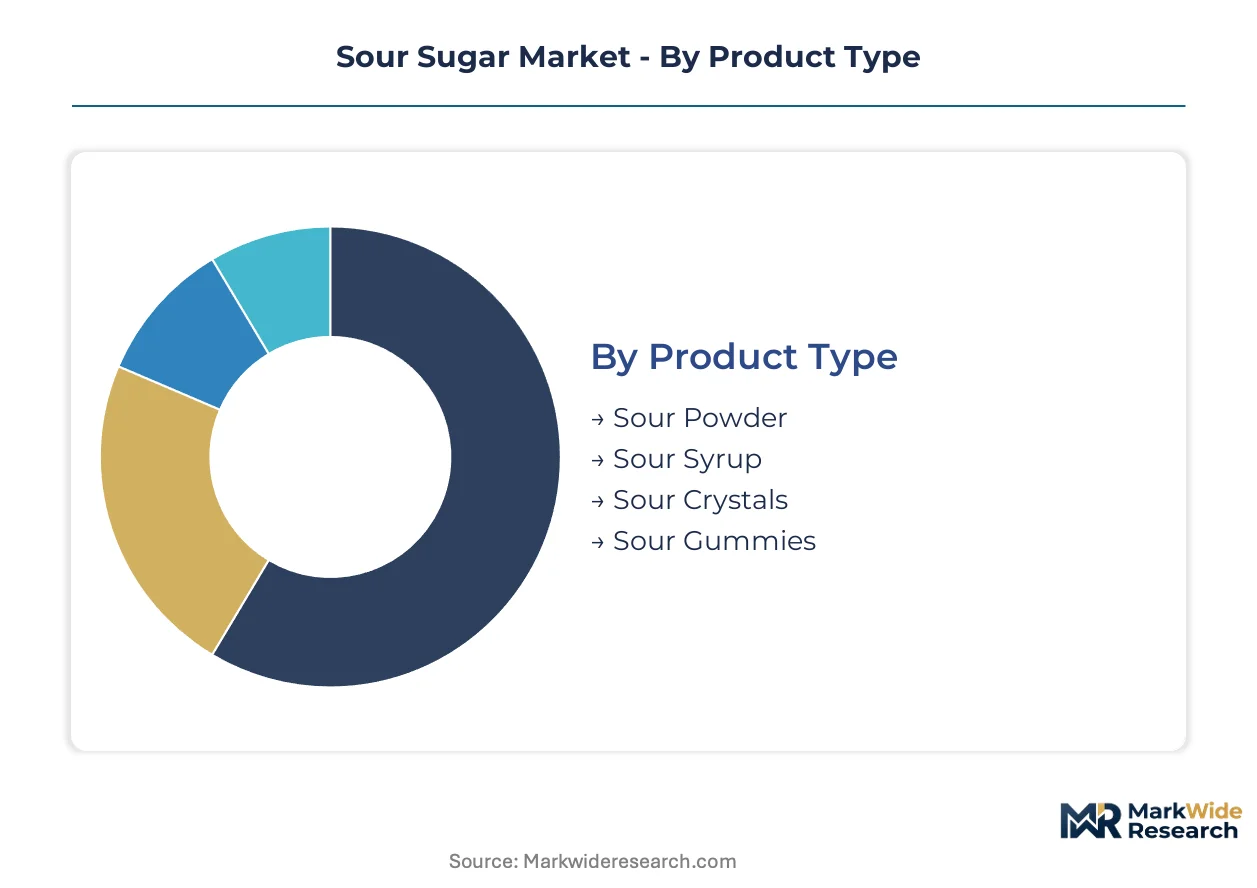
Sour sugar procurement patterns diverge sharply across formulation formats and end-use specifications. Manufacturers prioritize acidulant loading rates, coating uniformity, and shelf-stable pH curves when selecting segment-aligned supply contracts.
Product Type:
Sour powder faces the most acute substitution pressure from acidulant blends and direct acid spray technologies that bypass crystalline sugar substrates entirely. Coated formats compete with encapsulated acid systems for controlled-release applications.
- Sour Gummies:Gelatin or pectin matrices infused with citric-malic acid combinations at three-to-eight percent loading by weight. European confectionery houses in Germany and the Netherlands concentrate demand here, driven by premium positioning and specialized coating equipment requirements that create supplier stickiness.
- Sour Crystals:Large-grain sucrose substrates with surface acid crystallization enabling gradual dissolution curves. India's contract manufacturers are scaling capacity for export markets, attracted by PLI scheme incentives and lower fermentation-grade citric acid procurement costs.
- Sour Powder:Fine-milled acid-sugar blends for dry-mix beverage and baking applications. FSSAI labeling requirements on acidulant concentration are tightening formulation windows.
- Sour Syrup:Liquid acid-glucose solutions for industrial confectionery coating lines. Beverage manufacturers in the United States favor this format for fountain drink acidulation.
Sour gummies retain volume leadership; sour crystals hold the steepest expansion curve.
Application:
Cost tier stratification separates industrial-scale acidulant procurement from artisan batch purchases. High-volume confectionery operations negotiate direct acid blender relationships, while bakery and snack applications fragment across distributor networks.
- Confectionery:Hard candy, gummy, and pressed tablet formats requiring precise acidulant distribution for salivary stimulation measurement. Ferrara Candy Company and Haribo anchor demand through captive acid blending and specialized malic acid coating expertise.
- Baking:Laminated dough and filled pastry applications with limited-run flavor extension potential. Artisan bakeries in North America lack formulation guidance, constraining penetration.
- Beverages:Powdered drink mixes and fountain syrup acidulation. FDA GRAS determinations on citric acid maximum levels shape permissible formulation ranges.
- Snacks:Seasoning blends for extruded and puffed products. Commercial snack houses represent an expanding demand pool beyond traditional candy applications.
Confectionery commands the highest acidulant loading per unit; baking is climbing the fastest as formulation guidance spreads.
Distribution Channel:
Supply concentration in fermentation-grade citric acid from Chinese producers shapes channel economics. Direct procurement relationships are shortening traditional distribution hierarchies, particularly in India's domestic market.
- Online Retail:Direct-to-consumer acid-coated candy and specialty baking ingredients. Large-format retailers mandate supplier transparency on acid sourcing documentation.
- Supermarkets:Mass-market sour gummy and powdered drink mix placement. EFSA additive re-evaluation protocols are tightening maximum permissible acidulant levels in children's categories.
- Specialty Stores:Premium natural fermentation-derived malic acid products with organic glucose substrates. Health-conscious retailers mandate clean-label specifications.
- Convenience Stores:Impulse-format sour candy single-serve packaging. Price compression from synthetic tartaric acid substitution pressure affects margin pools.
Supermarkets retain volume leadership; online retail holds the steepest expansion trajectory.
End User:
Customer type determines acid handling protocol requirements and certification burdens. ISO 22000 and HACCP frameworks become mandatory thresholds for contract manufacturing qualification.
- Food Manufacturers:Industrial-scale confectionery, bakery, and snack production with seven-figure coating equipment investments. Mid-scale manufacturers face capacity qualification barriers from specialized fluidized bed system requirements.
- Bakeries:Artisan and industrial operations adopting sour sugar for limited-run flavor extensions. Underpenetration in laminated dough applications remains below potential.
- Households:Home baking and beverage preparation with retail-format sour sugar procurement. Consumer education on acidulant concentration measurement lags industrial segments.
- Restaurants:Dessert and cocktail program acidulation with small-batch specialty sourcing. Cross-border compliance burdens accumulate for imported acidulant blends.
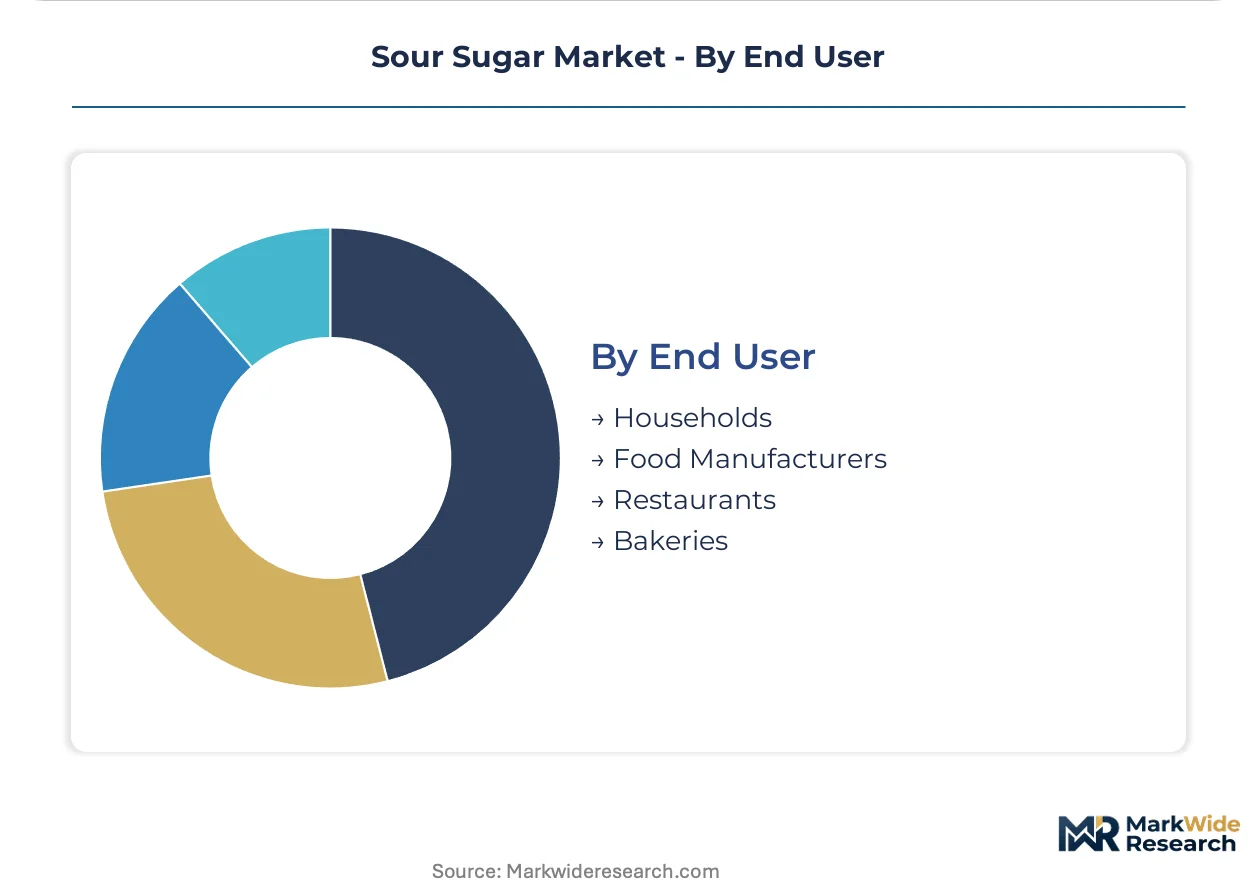
Food manufacturers retain volume leadership; bakeries hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes sour sugar primarily through industrial confectionery channels, while the United States and Germany favor direct retail formats with higher acidulant concentrations per unit. This consumption-mix differential shapes procurement patterns and regulatory compliance burdens across geographies.
United States
FDA GRAS determinations on citric acid maximum levels drive reformulation investments among mass-market confectioners. The agency's tightened labeling requirements for acidulant concentration have prompted specialized coating equipment upgrades. Chicago and New Jersey industrial corridors concentrate sour gummy production capacity for domestic and export markets.
Germany
EFSA additive re-evaluation protocols are compressing permissible acidulant thresholds in children's confectionery categories. Manufacturers submit extended toxicological dossiers for existing sour sugar formulations. The Cologne-Düsseldorf confectionery cluster hosts specialized malic acid coating expertise licensed across European production networks.
India
FSSAI food additive maximum level notifications create cross-border shipment qualification delays for acid-dependent formulations. The PLI scheme for food processing infrastructure accelerates domestic acid blending capacity expansion. Maharashtra and Gujarat contract manufacturers scale sour crystal output for Middle East and Southeast Asia export markets.
China
Fermentation-based citric acid supply faces periodic export quota adjustments from SAMR oversight, generating input price volatility. The country's dual carbon goals pressure petroleum-derived synthetic tartaric acid routes. Shandong Peninsula fermentation facilities supply acidulant raw materials to regional coating operations.
Brazil
ANVISA pharmaceutical-grade acidulant standards spill into confectionery additive classifications, raising import documentation requirements. Domestic candy houses source sour sugar through distributor networks rather than direct acid blender relationships. São Paulo industrial bakeries pilot limited-run sour-profile pastry lines for premium retail channels.
Sour Sugar Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the sour sugar competitive structure. The upper tier combines captive acid blending with specialized coating equipment ownership, while mid-scale players face capacity qualification barriers from seven-figure fluidized bed system requirements. Three archetypes dominate: vertically integrated confectionery houses with in-house acidulant procurement, contract manufacturers leveraging PLI scheme incentives for export qualification, and regional specialists licensing precision coating process technology. Competitive moves concentrate on strategic partnerships for acidulant supply security and geographic expansion into underpenetrated bakery segments.
Among North American confectionery houses, Ferrara Candy Company and The Hershey Company occupy positions within the integrated leader tier, representing backward integration into acid blending capabilities. Haribo anchors the European specialist vector with demonstrated malic acid coating expertise. These three exemplify how scale and captive supply relationships protect margin pools amid input volatility and regulatory tightening.
| Leading Market Players |
|---|
| Ferrara Candy Company |
| Haribo |
| Mondelez International, Inc. |
| The Hershey Company |
| Perfetti Van Melle |
| Albanese Confectionery Group, Inc. |
| Jelly Belly Candy Company |
| Trolli |
| Tootsie Roll Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day fermentation-grade citric acid inventory cycles in Shandong Province concentrate pricing power among acidulant blenders serving European and Indian contract manufacturers. This lead-time band tightens margin pools for mid-scale confectionery houses lacking direct procurement relationships with Chinese fermentation facilities.
Pricing Analysis
Long-term offtake contracts dominate acidulant procurement between Indian contract manufacturers and Shandong fermentation facilities, insulating volume buyers from spot-market volatility in citric acid pricing. Three-tier pricing structure across fermentation-grade, synthetic-grade, and food-grade certification levels separates Ferrara Candy Company's captive blending operations from distributor-dependent mid-scale players. Pricing pressure stems from FSSAI maximum level notification compliance costs accumulating across reformulation cycles. Artisan bakeries in North America exhibit highest price sensitivity due to limited-run volume scale, while European confectionery houses absorb premium positioning for malic acid coating expertise.
Supply Chain Analysis
Forty-five-day shipment qualification delays from divergent FDA and FSSAI acidulant thresholds fragment inventory planning for cross-border sour sugar movements. Geographic supply concentrates in China for fermentation-grade citric acid, India for PLI-scheme accelerated acid blending capacity, and Germany for specialized malic acid coating equipment. Raw material dependencies rest on corn-derived glucose substrates, petroleum-derived synthetic tartaric acid, and fermentation-grade malic acid from Aspergillus niger cultures. Single-source vulnerability in Chinese citric acid export quota administration generates periodic input price spikes. Distribution runs through direct procurement relationships shortening traditional import distributor hierarchies, particularly visible in Maharashtra and Gujarat contract manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. Specialized coating equipment requirements and evolving acidulant threshold notifications across multiple jurisdictions create switching costs that protect incumbent positioning.
For Market Incumbents: Secure captive acid blending capabilities to defend margin pools against citric acid input volatility from Chinese export quota adjustments. Invest in ISO 22000 certification ahead of mandatory HACCP-aligned qualification timelines for contract manufacturing preference. Capacity expansion in Maharashtra and Gujarat production corridors captures PLI scheme incentives before incentive windows compress competitive positioning. For New Entrants and Emerging Players: Formulation guidance scarcity for artisan and industrial bakeries in North America represents the most penetrable white-space target, as laminated dough applications remain below potential adoption curves. License precision coating process technology from European specialists rather than deploying seven-figure fluidized bed system capex independently. Direct-to-bakery technical service partnerships bypass established confectionery distribution hierarchies and build switching-cost moats through embedded formulation support. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized malic acid coating expertise concentrates among legacy European houses and integrated North American confectionery leaders, with mid-scale manufacturers facing capacity qualification barriers. Target acquisition archetypes include contract manufacturers with PLI scheme export qualification and regional acidulant blenders with fermentation-grade citric acid direct procurement relationships. Monitor FSSAI maximum level notification adjustments as the signal for reformulation cost inflection and qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Blending | Ferrara Candy Company's captive citric-malic procurement protects margin pools against Chinese export quota volatility. |
| ISO 22000 Certification Investment | Early HACCP-aligned qualification unlocks preferred supplier status with large-format retailers mandating acid handling transparency. |
| Precision Coating Technology Licensing | Haribo's malic acid crystallization expertise transfers to mid-scale manufacturers without seven-figure fluidized bed capex. |
| Direct Procurement Relationship Development | Maharashtra contract manufacturers bypass import distributors to secure fermentation-grade citric acid from Shandong facilities. |
| Clean-Label Acidulant Convergence | Natural fermentation-derived malic acid paired with organic glucose substrates addresses health-conscious retailer mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with confectionery flavor chemists, acidulant technicians, contract manufacturing procurement leads, and FSSAI regulatory affairs specialists. Secondary validation drew from FDA GRAS determination filings, EFSA additive re-evaluation protocols, FSSAI maximum level notifications, and PLI scheme infrastructure disbursement records. Bottom-up segment sizing triangulated against top-down acidulant consumption estimates from fermentation facility output disclosures.
Across the analysis window, forecasts incorporate product type segmentation by sour gummies, sour crystals, sour powder, and sour syrup formats alongside application splits across confectionery, baking, beverages, and snacks. CAGRs derive from acidulant loading rate trajectories, coating equipment deployment curves, and regional regulatory threshold adjustment probabilities. Industry-specific inputs include salivary stimulation measurement methodologies, pH curve engineering specifications, and encapsulation technology adoption rates at pilot scale.
Underlying assumptions cover stable FDA GRAS determination frameworks and FSSAI notification enforcement intensity, with deviation risk concentrated in Chinese SAMR export quota administration and EFSA children's category acidulant threshold compression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Smoked Sugar Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Agave Syrup Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Isomaltulose Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Aspartame Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Coconut Sugar Market
Sweeteners
Tagatose Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Fructose Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Middle East and Africa Sugar Substitutes Market