
 Middle East and Africa Sugar Substitutes Market | 2026-2036
Middle East and Africa Sugar Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sugar Substitutes Market Foresight
Consolidation among Gulf-based beverage manufacturers is repositioning procurement power toward fewer, larger reformulation contracts. Cargill, Incorporated leverages its regional sweetener blending facilities to secure multi-year supply agreements with these consolidated buyers. Tate & Lyle PLC anchors its position through specialized texturant systems that compensate for sugar reduction in ambient-stable beverages. Ajinomoto Co. competes on amino acid-based sweetener purity grades tailored to halal-certified production lines.
Middle East and Africa sugar substitutes encompass high-intensity sweeteners, bulk sweeteners, and natural extracts engineered to replicate sucrose's sweetness profile, caloric contribution, and functional properties in food matrices; stevia glycosides and erythritol formulations now achieve temporal sweetness curves within 15% of sucrose equivalence for most applications. Stevia-derived products lead volume adoption due to plant-origin positioning aligned with regional clean-label preferences. Sucralose maintains cost-sensitive segments where thermal stability in baked goods applications overrides premium positioning. The beverages application category captures disproportionate margin pools as carbonated and dairy-based drink reformulation accelerates across Gulf Cooperation Council markets.
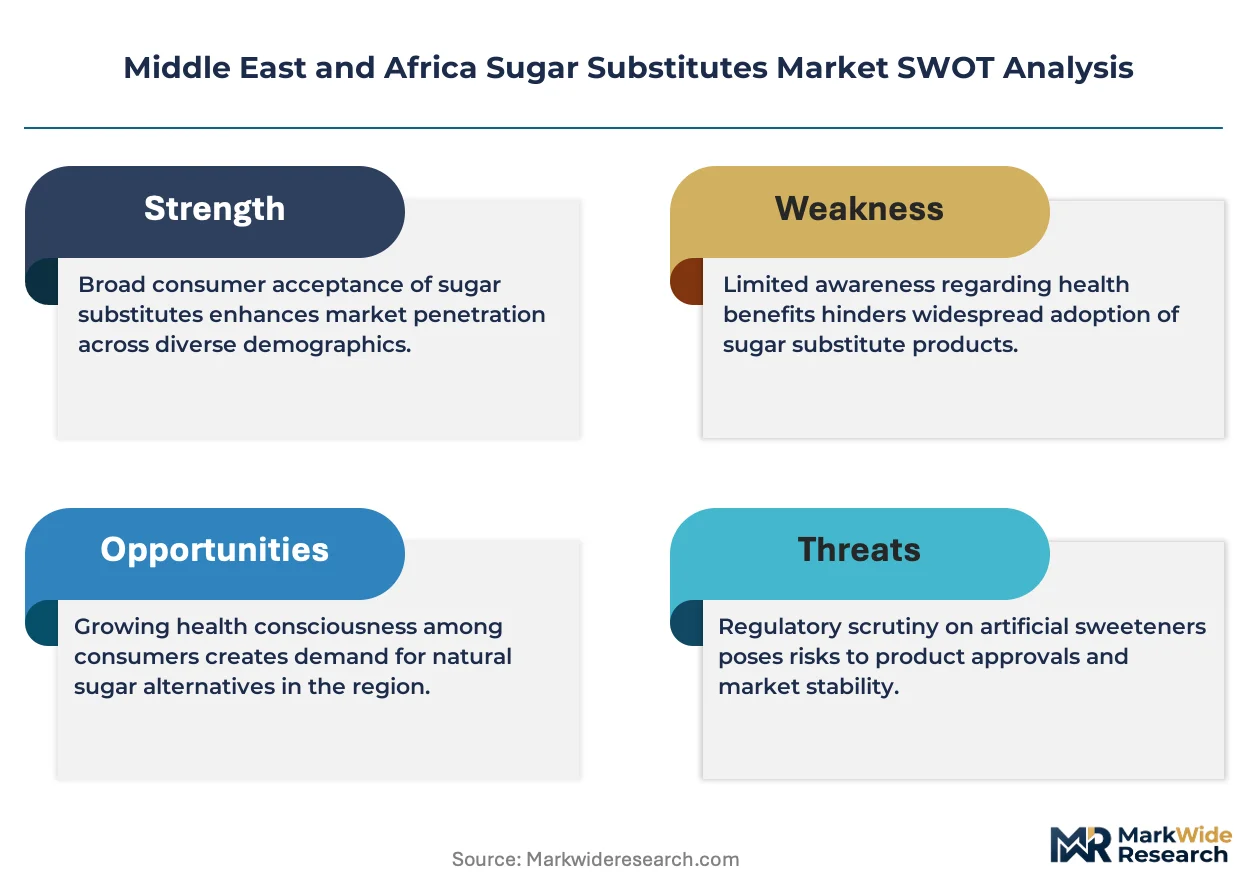
Saudi Arabia's SFDA, South Africa's Department of Health through sugar tax enforcement, and UAE's MOHAP collectively shape product standards through differential taxation, permissible daily intake thresholds, and front-of-pack labeling mandates. These frameworks push manufacturers toward multi-ingredient sweetener systems that achieve deeper sugar reduction without crossing regulatory additive ceilings. Stakeholders must monitor evolving permissible limits across national regulators while building formulation flexibility that accommodates simultaneous compliance with South African fiscal measures and Gulf technical standards.
Market Dynamics
Saudi Arabia's SFDA labeling mandates and South Africa's sugar tax enforcement are compressing formulation timelines across the Middle East and Africa sugar substitutes market. Beverage manufacturers must now achieve deeper sugar reduction without breaching additive thresholds, forcing multi-ingredient sweetener system adoption.
Growth Catalysts
- SFDA Front-of-Pack Labeling:Saudi Arabia's tightened requirements for reduced-sugar products accelerate reformulation investments by Gulf beverage producers seeking competitive positioning through clean-label claims.
- Johannesburg-Cape Town Processing Corridor:Concentrated food manufacturing infrastructure in South Africa creates demand density for bulk sweetener supply contracts and technical service proximity.
- Thermal-Stable Sweetener Blends:Erythritol-stevia combinations achieving ambient beverage stability enable extended shelf-life products for GCC distribution networks.
Market Restraints
- High-Intensity Sweetener Input Volatility:Stevia leaf and sucralose precursor chemical prices fluctuate with agricultural yields and petrochemical feedstock costs, compressing margin predictability for regional blenders.
- Gulf Procurement Consolidation:Fewer, larger beverage manufacturers concentrate buying power, squeezing supplier pricing flexibility and contract term leverage.
- South African Fiscal Ceiling:The Department of Health's sugar tax enforcement creates formulation cost floors that price out premium natural extracts in mass-market applications.
Strategic Opportunities
- UAE MOHAP Halal Certification Pathways:Streamlined approval processes for amino acid-based sweeteners open specialized positioning in certified dairy and beverage segments.
- East African Bakery Expansion:Underpenetrated markets in Kenya and Ethiopia present white space for sucralose thermal-stability applications in ambient-stable baked goods.
- Direct-to-Processor Digital Channels:B2B platform procurement of sweetener systems bypasses traditional distributor markups for mid-size food manufacturers.
Industry Challenges
- Multi-Regulatory Formulation Complexity:Simultaneous compliance with South African sugar tax thresholds and Gulf additive ceilings requires dedicated regulatory affairs capacity and flexible production lines.
- Sweetener-Receptor Matching Expertise:Shortage of flavor chemists trained in temporal sweetness curve optimization limits regional development of sucrose-mimetic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sugar Substitutes Market |
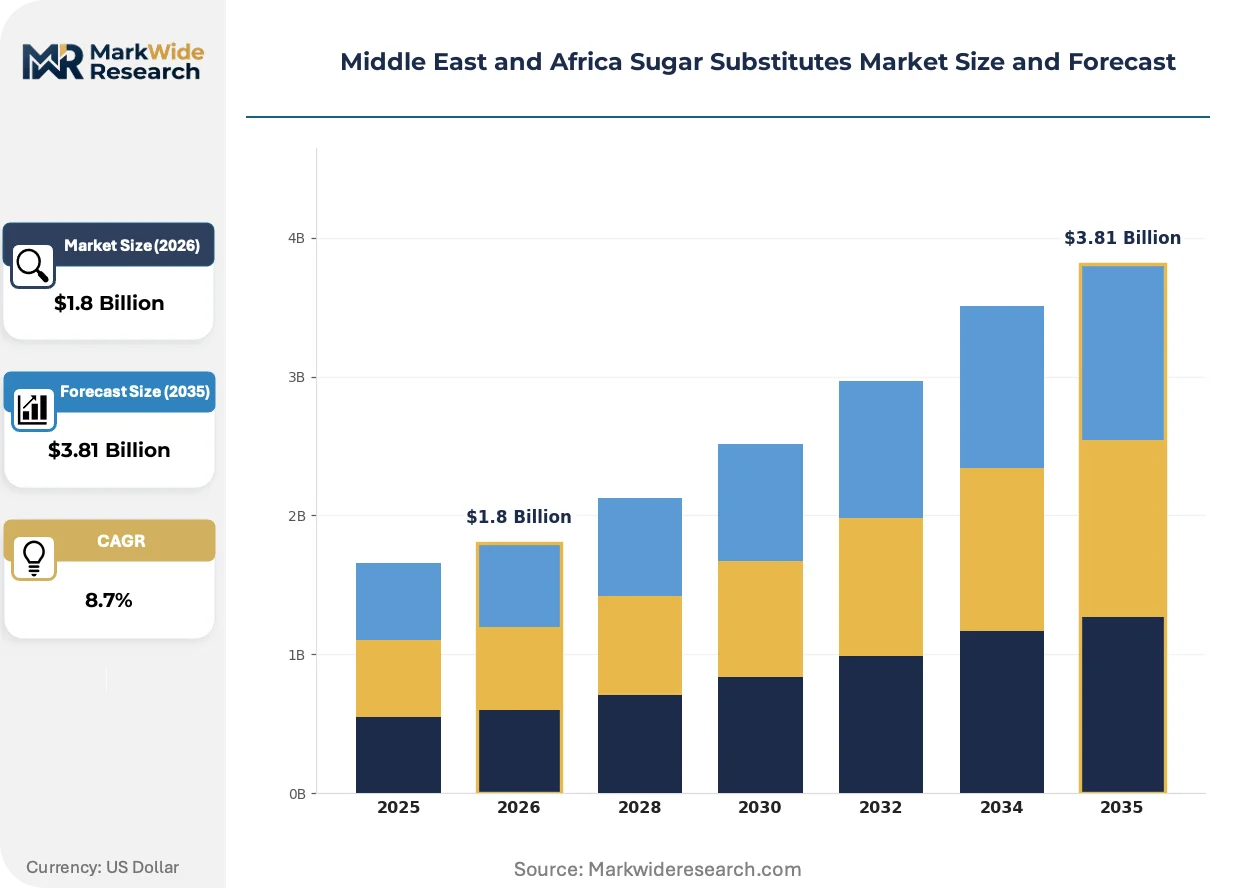
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Sucralose, Erythritol Application: Beverages, Baked Goods, Dairy Products, Confectionery End User: Food Industry, Beverage Manufacturers, Personal Care, Pharmaceutical Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Ingredion Incorporated, Ajinomoto Co., Cargill, Incorporated, International Flavors & Fragrances Inc., Archer Daniels Midland Company, Tate & Lyle PLC, PureCircle Ltd, Roquette Frères, DuPont de Nemours, Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sugar Substitutes Market Shifts & Advancements
Enzymatic bioconversion and precision fermentation are displacing traditional extraction methods across stevia and rare sugar production. Regional manufacturers now face technology investment decisions that will determine cost position through 2035.
Enzymatic stevia glycoside conversion is converging with precision fermentation platforms to produce rebaudioside M at purity grades previously unattainable through leaf extraction. Gulf beverage formulators are adopting these inputs for clean-label positioning in premium carbonated drinks. The technology is converging with regional halal certification requirements, enabling amino acid-based sweetener production in certified facilities that bypass import dependency.
South Africa's Department of Health sugar tax enforcement has triggered cascading reformulation mandates across neighboring SADC markets. Industrial consequence includes accelerated multi-sweetener system adoption to achieve tax thresholds without sensory degradation. Carbonated soft drink manufacturers in Johannesburg and Cape Town are responding through partnerships with regional texturant suppliers to rebuild mouthfeel profiles.
Food service operators across Dubai and Riyadh are unbundling sweetener procurement from traditional broadline distributor contracts. Independent bakery chains and café groups now source high-intensity sweeteners directly from UAE-based blending facilities, compressing channel margins and forcing distributor repositioning toward technical formulation support. This pattern is most visible in the premium coffee shop vertical, where customized sweetness profiles differentiate regional chains.
Middle East and Africa Sugar Substitutes Market Segmentation
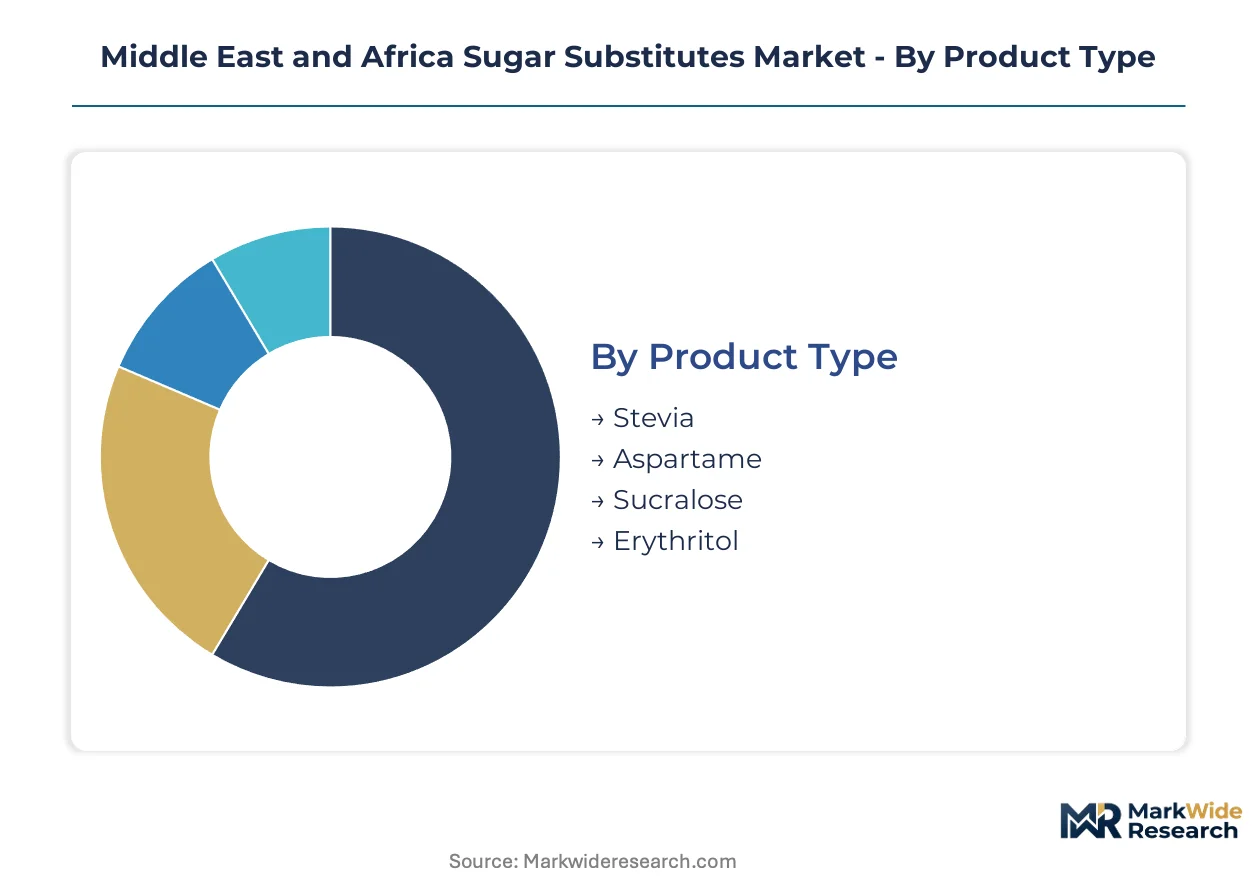
Reformulation cycles across Gulf beverage plants and South African food processors create divergent upgrade paths for sweetener procurement. Manufacturers prioritize segments offering regulatory pre-approval and thermal stability to compress qualification timelines.
Product Type:
Replacement decisions track reformulation intensity and clean-label positioning across ambient-stable applications.
- Stevia:Enzymatically converted glycoside formulations achieve rebaudioside M purity grades that replicate sucrose temporal curves. Demand clusters in Saudi Arabia's carbonated beverage sector where SFDA labeling mandates favor plant-origin claims.
- Sucralose:Chlorinated sucrose derivative maintains thermal stability above 200°C for baked goods and UHT dairy applications. Johannesburg-based industrial bakeries specify this input for tax-compliant reformulations that preserve Maillard reaction profiles.
- Aspartame:Dipeptide methyl ester restricted by phenylketonuria labeling requirements; pharmaceutical tablet coatings represent residual demand pockets.
- Erythritol:Fermentation-derived bulk sweetener provides crystallization control and cooling effects in sugar-free confectionery.
Volume placements concentrate in sucralose for cost-sensitive thermal applications; the faster expansion belongs to stevia glycoside systems.
Application:
Margin capture varies sharply by processing complexity and reformulation depth required.
- Beverages:Carbonated soft drinks, flavored waters, and dairy-based drinks dominate procurement volumes across Dubai and Riyadh manufacturing corridors. Multi-sweetener systems combining stevia with erythritol achieve deep sugar reduction while maintaining shelf stability in GCC distribution networks.
- Baked Goods:Ambient-stable cookies and crackers in Kenya and Ethiopia drive sucralose uptake where thermal processing degrades natural alternatives. Regional formulators compensate for sugar's structural roles through specialized texturant co-ingredients.
- Dairy Products:Yogurt and flavored milk applications in South Africa's Cape Town processing cluster face sugar tax thresholds that accelerate high-intensity sweetener adoption.
- Confectionery:Hard candies and chewing gums require precise crystallization control that erythritol and polyol blends provide.
Reformulation investment pools deepest in beverages; confectionery applications climb fastest as sugar-free positioning penetrates premium gifting segments.
End User:
Procurement sophistication separates commodity buyers from technical specification partners.
- Beverage Manufacturers:Consolidated Gulf producers leverage multi-year supply agreements for blended sweetener systems. Technical service requirements include temporal sweetness curve matching and halal certification documentation.
- Food Industry:Industrial bakeries and sauce manufacturers in South Africa's Johannesburg corridor specify bulk sweetener grades with defined particle size distributions for automated dosing.
- Pharmaceutical:Tablet excipient and syrup applications demand pharmacopeial-grade aspartame and sucralose with batch-specific purity certificates.
- Personal Care:Toothpaste and mouthwash formulators utilize high-intensity sweeteners at sub-threshold levels for taste masking without caloric contribution.
Contract values concentrate with beverage manufacturers; pharmaceutical qualification cycles are extending fastest as purity standards tighten.
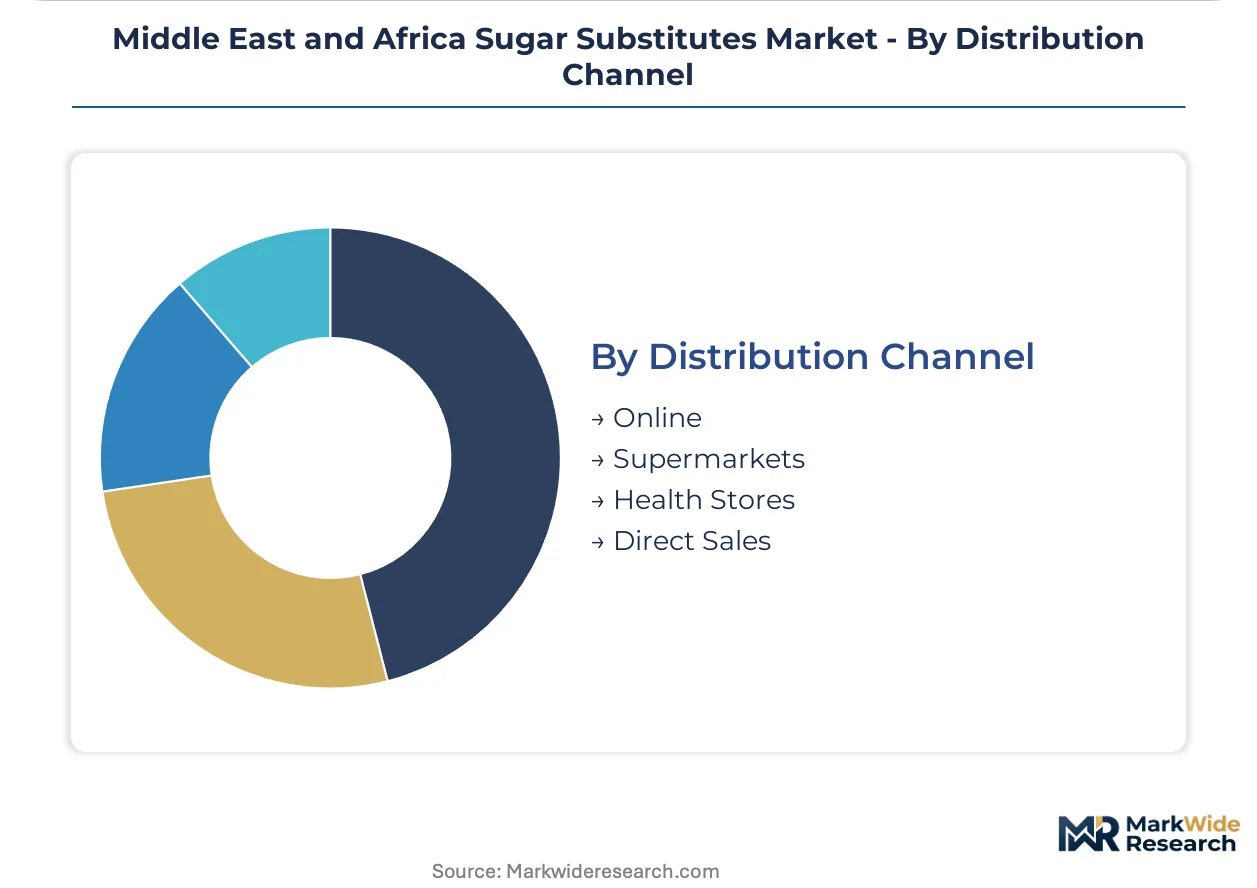
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to blending facilities.
- Direct Sales:Large-volume beverage and food manufacturers in Saudi Arabia and UAE negotiate directly with regional sweetener blenders. Technical formulation support and customized bulk delivery schedules justify bypassing distributor markups.
- Online:B2B procurement platforms serve mid-size Johannesburg and Cape Town processors seeking transparent pricing and rapid sample fulfillment.
- Supermarkets:Packaged consumer sweetener products for retail sale; limited industrial relevance outside small-scale food service.
- Health Stores:Premium-positioned natural extracts and organic-certified stevia products targeting clean-label consumers.
Transaction volumes flow heaviest through direct sales; online channel infrastructure is scaling fastest as digital procurement penetrates tier-2 manufacturing centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugar substitute procurement concentrates in Gulf beverage manufacturing corridors and South Africa's food processing belt. Regional reformulation timelines diverge sharply between Saudi Arabia's labeling-driven acceleration and South Africa's tax-enforced reduction mandates. These differential regulatory pressures fragment supply chain standardization across the region.
Saudi Arabia
Carbonated beverage producers in Riyadh and Jeddah drive stevia glycoside procurement for clean-label reformulation. SFDA front-of-pack labeling mandates compress product development cycles to under eighteen months. The Eastern Province petrochemical corridor supplies precursor chemicals for sucralose production, anchoring regional high-intensity sweetener manufacturing.
United Arab Emirates
Dubai-based beverage blenders and specialty coffee chains create concentrated demand for customized sweetener systems. MOHAP halal certification pathways streamline amino acid-based sweetener approvals for dairy applications. Jebel Ali's free zone infrastructure hosts regional sweetener blending and re-export operations serving Gulf markets.
South Africa
Johannesburg-Cape Town food processing corridor dominates regional bulk sweetener consumption for tax-compliant reformulation. Department of Health sugar tax enforcement pushes manufacturers toward multi-ingredient systems that preserve mouthfeel. Port Elizabeth's pharmaceutical manufacturing cluster generates pharmacopeial-grade demand for tablet excipient applications.
Kenya
Nairobi-based industrial bakeries and confectioners represent emerging demand for thermal-stable sweeteners in ambient-stable goods. National food safety authority standards on additive thresholds shape procurement specifications for regional manufacturers. Mombasa's port infrastructure facilitates sucralose importation for East African distribution networks.
Egypt
Cairo-Alexandria manufacturing belt sustains demand for cost-optimized sweetener blends in mass-market beverages. National food safety authority permissible daily intake guidelines influence formulation ceilings for carbonated drinks. Suez Canal Economic Zone logistics hubs enable re-export positioning for North African markets.
Middle East and Africa Sugar Substitutes Market Competitive Landscape
North American and European multinationals anchor the premium formulation tier; Asian specialists hold cost-optimized supply positions. Gulf procurement consolidation concentrates contract value among fewer buyers, squeezing supplier pricing leverage. Three archetypes dominate: integrated agribusiness conglomerates with regional blending assets, specialized texturant and sweetener system houses, and fermentation-based rare sugar producers. Competitive positioning hardens through multi-year supply agreements and halal-certified production line investments.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven procurement consolidation plays. Tate & Lyle PLC occupies a position among specialized texturant system providers compensating for sugar's functional loss. Ajinomoto Co. anchors the amino acid-based sweetener specialization vector, with halal certification pathways reinforcing Gulf market access.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Ajinomoto Co. |
| Cargill, Incorporated |
| International Flavors & Fragrances Inc. |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| PureCircle Ltd |
| Roquette Frères |
| DuPont de Nemours, Inc |
| Others |
Supply & Pricing Matrix
Enzymatic bioconversion and precision fermentation platforms are displacing legacy leaf-extraction methods across stevia glycoside production, simultaneously compressing unit economics and concentrating supply among capital-intensive fermentation operators in Saudi Arabia's Eastern Province and UAE's Jebel Ali free zone. This technological pivot redraws cost curves for high-purity rebaudioside M while locking out smaller regional blenders dependent on imported leaf-derived inputs.
Pricing Analysis
Volume placements concentrate in sucralose for cost-sensitive thermal applications, while margin capture clusters in enzymatically converted stevia glycosides. Price differentiation rests on purity grade certification and halal production line compliance. Pricing pressure intensifies in bulk erythritol as fermentation capacity additions outpace beverage reformulation demand. Gulf beverage manufacturers exhibit lowest price sensitivity due to consolidated procurement power; East African industrial bakeries face acute cost compression from sugar tax compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Arabia's SFDA and South Africa's Department of Health mandate multi-supplier qualification for high-intensity sweetener inputs, fragmenting procurement across Indian enzymatic stevia producers, Chinese sucralose precursor manufacturers, and European erythritol fermentation specialists. Raw material dependencies center on stevia leaf biomass, chlorinated sucrose precursors, and glucose feedstock for fermentation. Single-source vulnerability runs through petrochemical-derived sucralose intermediates. Distribution feeds from Jebel Ali and Mombasa port hubs into Gulf and East African manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are displacing solvent-based extraction across high-purity sweetener manufacturing, creating a technology-transition window where capital deployment determines cost position through the projection horizon.
For Market Incumbents: Cement multi-year supply agreements with consolidated Gulf beverage manufacturers before fermentation capacity rationalization eliminates spot market premiums. Backward integration into enzymatic conversion technology in Saudi Arabia's Eastern Province defends margin position against Asian fermentation specialists. Halal-certified production line investments in UAE facilities lock in dairy segment access as MOHAP streamlines amino acid-based sweetener approvals.
For New Entrants and Emerging Players: Capture white space in Kenya and Ethiopia's ambient-stable baked goods segments where sucralose thermal stability requirements exceed local formulation expertise. Direct-to-processor digital procurement platforms bypass traditional distributor markups for mid-size Johannesburg food manufacturers. Technical service partnerships with regional texturant suppliers accelerate qualification timelines for sugar tax-compliant reformulations.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness conglomerates seeking regional blending assets and halal certification infrastructure. Long-term viability favors fermentation-based rare sugar producers with enzymatic platform flexibility across stevia glycosides and amino acid sweeteners. Watch for inflection in South Africa's sugar tax threshold adjustments, which would cascade reformulation intensity across SADC markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Scale-Up | Precision fermentation capacity in Jebel Ali free zone captures premium clean-label positioning for Gulf beverage reformulation. |
| Halal Certification Investment | MOHAP-approved production lines unlock amino acid-based sweetener access to UAE dairy and beverage segments. |
| Direct-to-Processor Digital Channel | B2B procurement platforms bypass distributor markups for mid-size Johannesburg and Cape Town food manufacturers. |
| Multi-Sweetener System Partnerships | Technical alliances with texturant suppliers rebuild mouthfeel profiles for South African sugar tax-compliant formulations. |
| East African Distribution Buildout | Mombasa port hub infrastructure enables sucralose supply to Kenya and Ethiopia's expanding industrial bakery sectors. |
Research Methodology
Document review covered SFDA labeling guidelines, South African Department of Health sugar tax enforcement circulars, and UAE MOHAP halal certification protocols, complemented by interviews with beverage formulation directors, industrial bakery procurement managers, and sweetener blending facility technical leads. Secondary validation drew from customs trade data, food processing industry association reports, and national food safety authority additive threshold publications. Bottom-up volume estimates from individual manufacturing facilities triangulated against top-down market sizing from regional production capacity assessments.
Cross-referencing historical reformulation cycle timing against expert panel input on regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user procurement sophistication, and distribution channel structure. CAGRs derived from weighted average of volume trajectory and value-per-unit evolution. Industry-specific forecast inputs incorporated SFDA front-of-pack labeling implementation pace and SADC market sugar tax contagion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stevia leaf agricultural yield volatility, petrochemical feedstock cost swings, and divergent national regulator permissible daily intake adjustments. Deviation in Gulf beverage manufacturer consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Corn Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Methyl Glucose Market
Sweeteners
Stevia Mints Market
Sweeteners
Granulated Sugar Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Icing Sugar Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Galactose Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Africa Stevia Market
Sweeteners
Invert Sugar Market
Sweeteners
Europe Low-Calorie Sweeteners Market