
 Non Sugar Sweeteners Market | 2026-2036
Non Sugar Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Non Sugar Sweeteners Market Outlook
Beverage producers is repositioning procurement priorities toward high-intensity sweetener blends that maintain taste profiles while cutting sugar content. Cargill Incorporated leverages its vertically integrated stevia supply chain to secure consistent raw material flows across Latin American growing regions. Tate & Lyle PLC anchors its competitive stance through specialized expertise in sucralose modification for heat-stable bakery applications.
Non sugar sweeteners comprise synthetic and naturally derived compounds that provide sweetness without metabolizable carbohydrates, typically exhibiting sweetness intensities 200 to 600 times that of sucrose on a weight basis. These ingredients serve primarily to reduce caloric density in processed foods while preserving consumer-acceptable taste profiles. Stevia-derived products occupy expanding shelf space as clean-label preferences intensify across North American and European retail channels. Sucralose maintains dominant volume position in carbonated beverage applications where thermal stability and acid tolerance prove critical to formulation success.
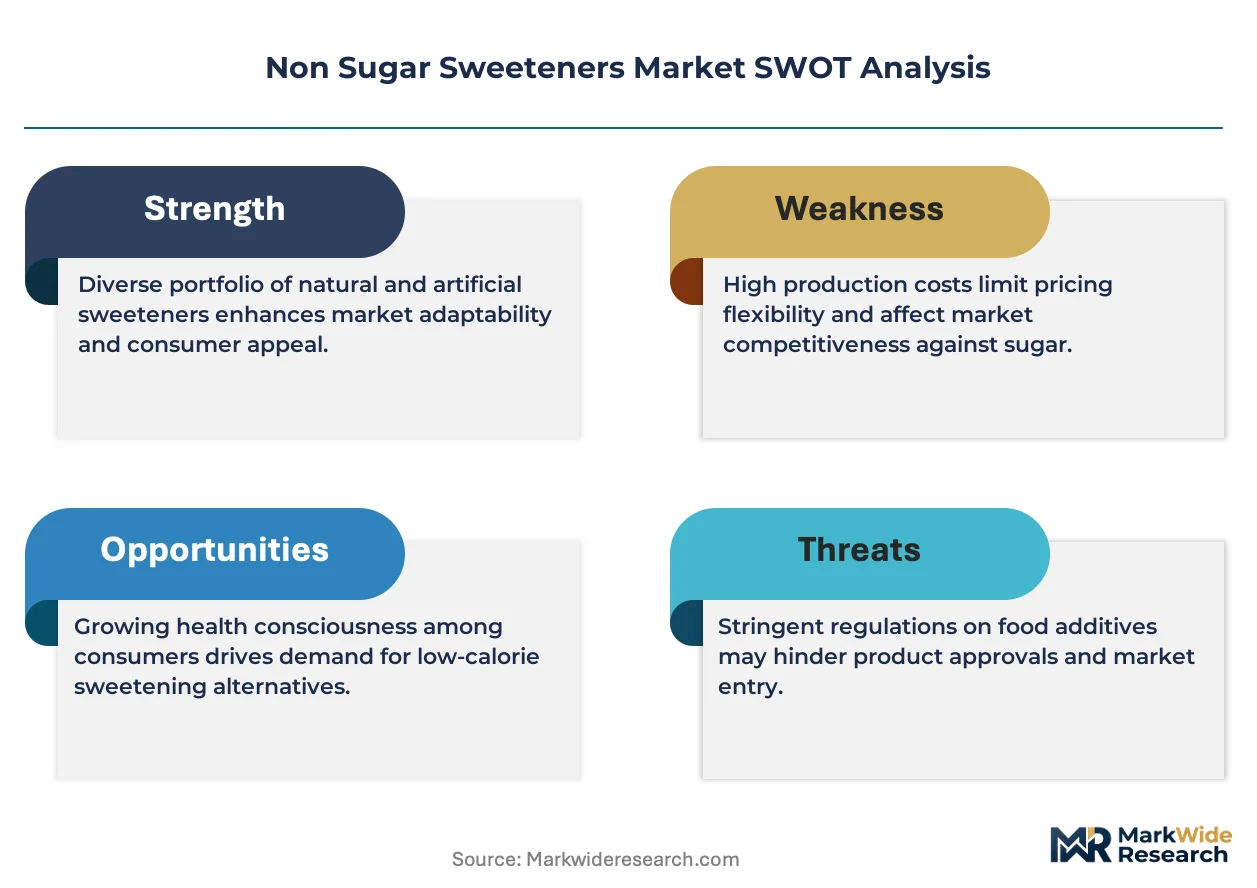
The FDA regulates sweetener safety through its food additive petition process and Generally Recognized As Safe determinations, while the EFSA establishes acceptable daily intake thresholds that directly constrain European product formulation strategies. The FSSAI in India enforces progressively stricter labeling requirements for products carrying sugar-free claims, reshaping how multinational suppliers structure their regional product portfolios. Stakeholders must monitor evolving toxicological reassessments and front-of-pack labeling mandates that threaten to disqualify legacy artificial sweeteners from key formulation opportunities.
Market Dynamics
Beverage manufacturers are accelerating reformulation timelines as front-of-pack labeling mandates in major markets force rapid sugar reduction without sacrificing taste parity with legacy formulations.
Growth Catalysts
- EFSA Acceptable Daily Intake Reviews:Updated toxicological thresholds for steviol glycosides expand permissible formulation ranges across European dairy and confectionery applications.
- Carbonated Beverage Reformulation:Major soft drink producers are replacing high-fructose corn syrup with sucralose-acesulfame potassium blends to achieve calorie targets.
- Clean-Label Retail Shelf Expansion:North American grocery chains are dedicating premium shelf space to products bearing plant-derived sweetener claims.
Market Restraints
- Stevia Leaf Supply Concentration:Raw material sourcing clusters in Paraguay and China creates price volatility during regional harvest disruptions.
- Taste Profile Limitations:Reb-A stevia extracts retain bitter aftertastes that require expensive flavor maskers in citrus-flavored applications.
- FSSAI Labeling Stringency:India's progressive disclosure requirements for sugar-free claims extend product registration timelines by 8-14 months.
Strategic Opportunities
- Bakery Heat-Stability Gap:Sucralose-modified variants capable of withstanding 180°C oven temperatures unlock untapped cookie and cake segments.
- Monk Fruit Extraction Scale-Up:Guilin growing region expansion in China enables cost-competitive positioning against premium stevia isolates.
- Pharmaceutical Excipient Adoption:Sugar-free chewable tablet and syrup formulations are incorporating high-intensity sweeteners as pediatric compliance enhancers.
Industry Challenges
- Flavor Chemist Scarcity:Formulation expertise in bitter-blocking compound integration commands premium salaries and extended recruitment cycles.
- GRAS Self-Determination Complexity:Novel sweetener entrants face multi-year FDA food additive petition processes with uncertain evidentiary requirements.
- Legacy Equipment Retrofit Costs:Powder handling systems designed for sucrose require pneumatic conveying modifications to prevent hygroscopic clumping with alternative sweeteners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Sugar Sweeteners Market |
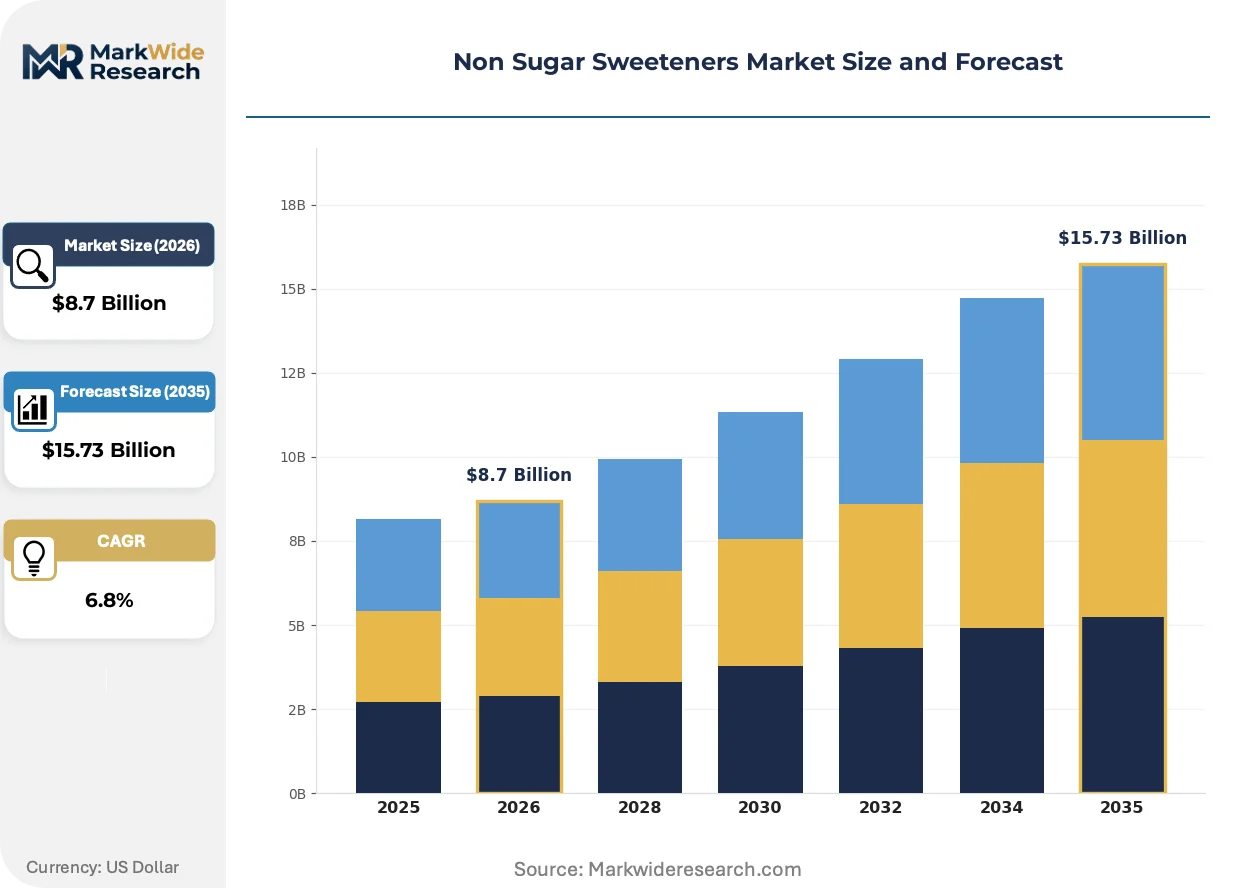
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acesulfame K, Aspartame, Sucralose, Stevia Application: Beverages, Bakery, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Producers, Retail Consumers, Restaurants Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, DuPont de Nemours Inc., Ajinomoto Co. Inc., Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Südzucker AG, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Sugar Sweeteners Market Strategic Shifts
Enzymatic bioconversion methods are reshaping how manufacturers extract and modify sweet compounds, collapsing cost structures for next-generation natural alternatives.
Fermentation-derived sweeteners is overtaking agricultural extraction as the dominant production pathway for rare sugar molecules. Precision fermentation platforms using engineered yeast strains produce allulose and tagatose at purity levels exceeding 99.5%. Beverage formulators in the United States are adopting these inputs three times faster than European counterparts due to favorable FDA GRAS determinations.
REACH authorization requirements for synthetic high-intensity sweeteners are tightening purity specifications for contaminants including 5-hydroxymethylfurfural. European manufacturers must now certify batch-level compliance through accredited third-party laboratories. This regulatory compression favors suppliers with captive analytical capabilities and disadvantages import-reliant blenders in Eastern European markets.
Direct-to-manufacturer ingredient sourcing is fragmenting traditional distributor networks as large beverage conglomerates establish preferred supplier agreements with stevia and monk fruit processors. Bulk procurement teams are negotiating multi-year offtake contracts with embedded price collars. This channel compression is most pronounced in California and Texas, where concentrated beverage production clusters enable logistics optimization.
Non Sugar Sweeteners Market Segmentation
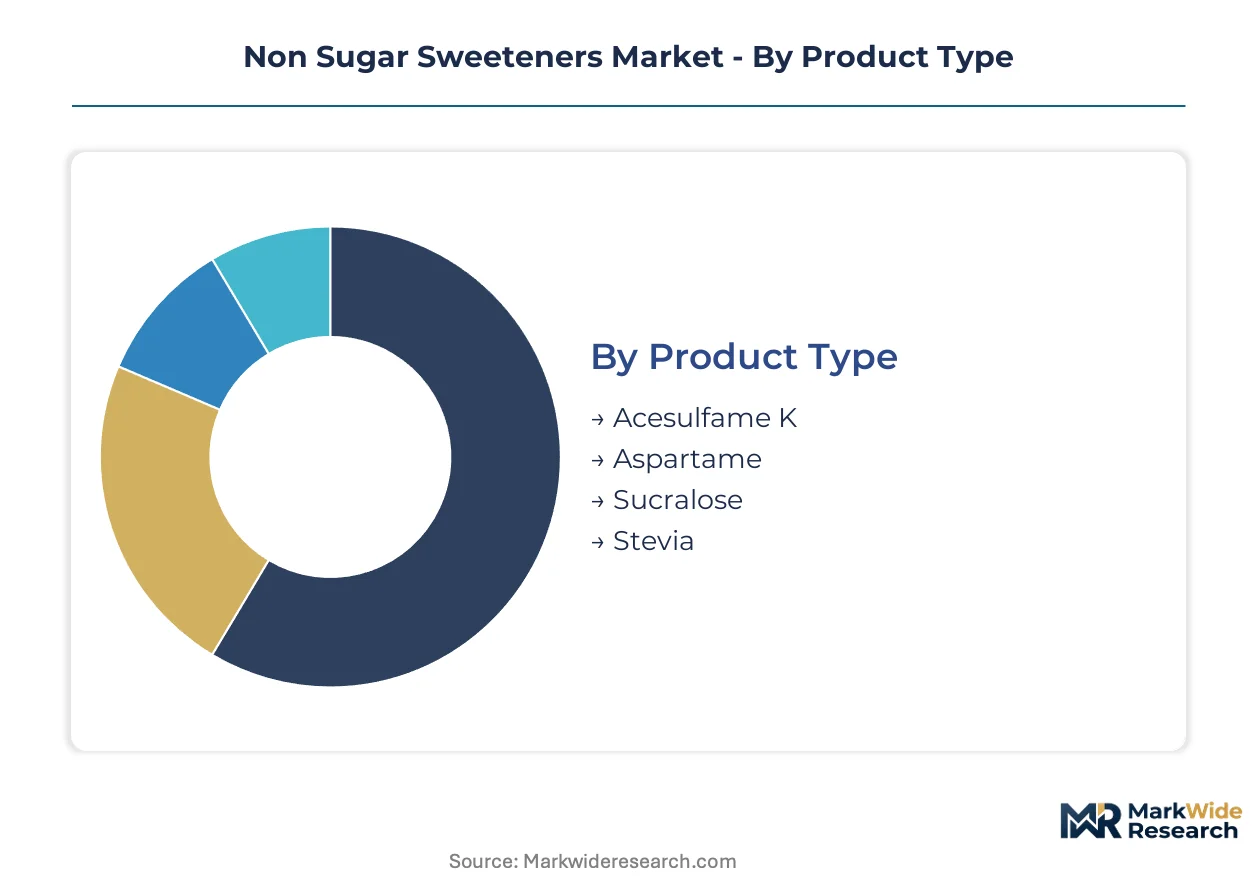
Non sugar sweeteners serve distinct functional requirements across formulation types, with thermal stability, acid tolerance, and clean-label positioning driving procurement decisions. Segmentation reveals how ingredient specifications align with processing constraints and consumer positioning strategies.
Product Type:
Volume concentration favors mature synthetic molecules, while premium positioning attaches to plant-derived extracts with traceable supply chains.
- Sucralose:A heat-stable chlorinated sugar derivative maintaining sweetness integrity at 180°C baking temperatures. Beverage producers in the United States rely on sucralose for carbonated soft drink reformulation where acid tolerance and shelf stability prove critical to maintaining taste parity with legacy high-fructose corn syrup formulations.
- Stevia:Glycoside extracts from Stevia rebaudiana leaves delivering clean-label positioning with 200-400x sucrose sweetness intensity. European dairy and confectionery manufacturers are expanding procurement of enzymatically modified steviol glycosides after EFSA raised acceptable daily intake thresholds, enabling broader formulation ranges in yogurt and chocolate applications.
- Acesulfame K:Synthetic oxathiazinone compound with rapid onset sweetness and excellent baking stability.
- Aspartame:Dipeptide methyl ester requiring phenylketonuria labeling and showing thermal degradation above 80°C.
Mature deployment sits with Sucralose. Newer deployment is concentrated in Stevia.
Application:
Carbonated beverages anchor volume demand, while bakery and dairy segments command formulation complexity premiums due to processing stress requirements.
- Beverages:The dominant volume channel encompassing carbonated soft drinks, flavored waters, and ready-to-drink teas where rapid dissolution and acid stability determine ingredient selection. Major producers in Texas and California procurement clusters negotiate multi-year offtake contracts for sucralose-acesulfame potassium blends to achieve calorie reduction targets without sacrificing taste profiles.
- Bakery:Heat-intensive processing segment requiring sweeteners capable of withstanding Maillard reaction temperatures without degradation or off-flavor generation. Cookie and cake manufacturers are driving demand for thermally modified sucralose variants that maintain sweetness through 180°C oven cycles where standard formulations lose potency.
- Dairy Products:pH-sensitive applications including yogurt and ice cream where sweetness perception interacts with protein matrices and fermentation byproducts.
- Confectionery:Hard candy and chewing gum formulations requiring crystallization control and sustained release characteristics.
Volume leadership belongs to Beverages. Steepest expansion trajectory is occurring in Bakery.
End User:
Procurement scale separates industrial compounders from fragmented foodservice operators, with regulatory compliance capabilities determining supplier access tiers.
- Food Manufacturers:Large-scale compounders of processed foods, snack bars, and prepared meals with dedicated R&D formulation teams and GRAS self-determination capabilities. These buyers negotiate direct supply agreements with stevia processors in Paraguay and monk fruit extractors in China's Guilin region, bypassing traditional distributor networks.
- Beverage Producers:Concentrated manufacturing clusters in the United States with specialized requirements for high-intensity sweetener blends and rapid reformulation cycles. Procurement teams in these organizations command premium shelf space negotiations with retail grocery chains for clean-label product lines.
- Retail Consumers:Individual purchasers of table-top sweetener packets and bulk substitutes for home baking applications.
- Restaurants:Foodservice operators sourcing portion-controlled packets and bulk dispensers for front-of-house beverage stations.
Contract sophistication peaks with Food Manufacturers. Direct procurement adoption is climbing fastest among Beverage Producers.
Distribution Channel:
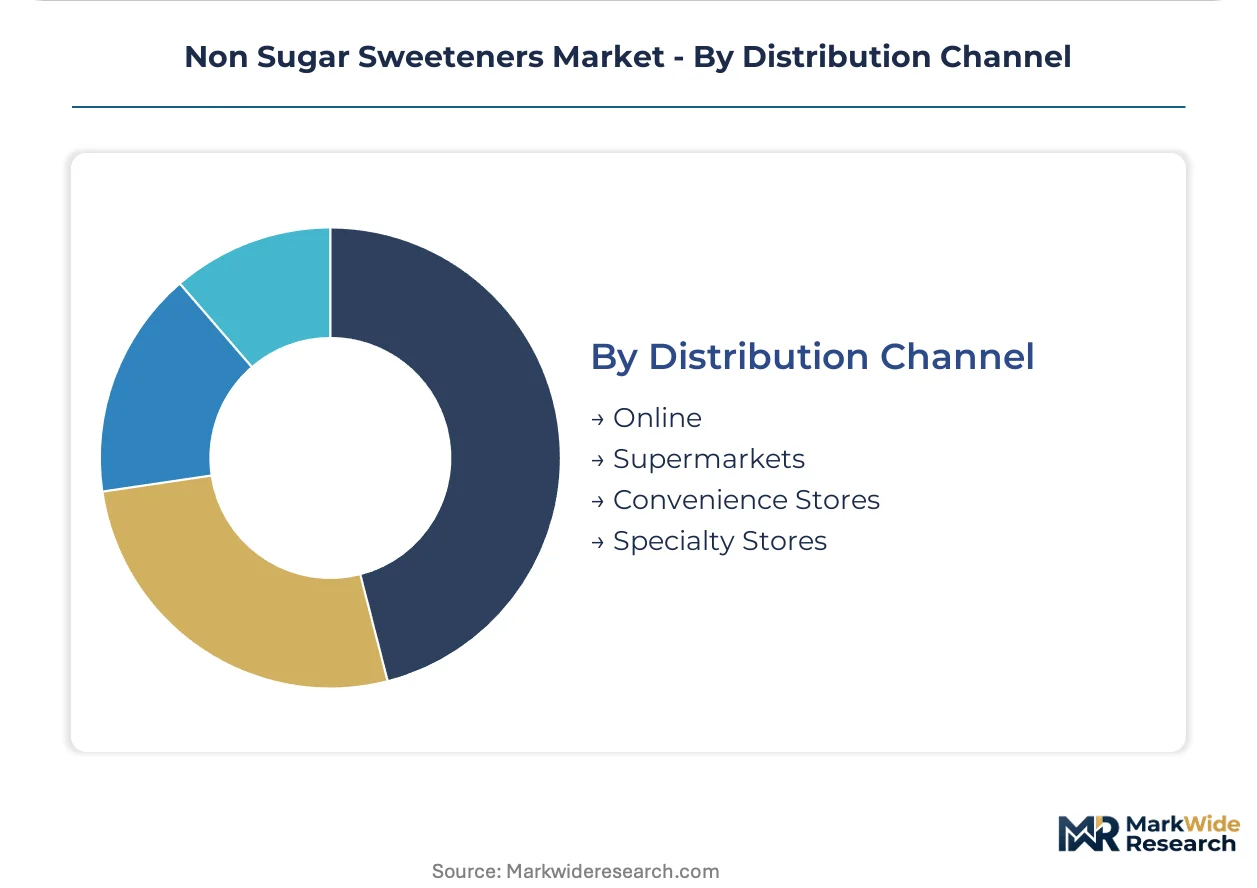
Channel selection correlates with purchase scale and technical support requirements, with industrial buyers favoring direct relationships while fragmented endpoints rely on intermediary infrastructure.
- Supermarkets:Primary retail channel for table-top sweeteners and consumer-packaged goods, with shelf space allocation increasingly favoring plant-derived positioning claims. North American grocery chains are dedicating premium placement to products bearing stevia and monk fruit extracts as clean-label preferences intensify.
- Online:Growing channel for bulk ingredient procurement by small-scale food manufacturers and direct-to-consumer specialty sweetener sales.
- Convenience Stores:Impulse-oriented channel for single-serve packet sales and ready-to-drink reduced-calorie beverages.
- Specialty Stores:Health food and natural product retailers catering to clean-label and organic positioning requirements.
Scale concentration rests with Supermarkets. Digital penetration is expanding most quickly through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraguay's Alto Paraná special economic zone stevia cultivation incentives concentrate raw material flows for global extract processors. Tax-advantaged growing operations in this region supply enzymatically modified glycoside refiners across three continents.
United States
Beverage reformulation mandates from Texas and California procurement clusters drive sucralose-acesulfame potassium blend demand. The FDA's GRAS self-determination framework accelerates novel sweetener market entry timelines. Atlanta and Chicago headquarters of major soft drink producers negotiate multi-year offtake contracts with direct processor relationships.
Germany
REACH authorization tightening for synthetic sweetener purity specifications reshapes batch certification requirements. Südzucker AG's Mannheim facilities anchor European sucralose modification capacity for heat-stable bakery applications. Bavarian analytical laboratories now handle third-party contaminant verification for Eastern European blenders lacking captive testing infrastructure.
China
Guilin monk fruit extraction scale-up and Shandong enzymatic bioconversion platforms dominate rare sugar molecule supply. The SAMR's progressively stricter food additive labeling enforcement extends product registration timelines for imported formulations. Yangtze River Delta fermentation facilities produce allulose at purity levels exceeding 99.5% for North American beverage clients.
India
FSSAI disclosure requirements for sugar-free claims reshape multinational regional portfolio structures. Maharashtra and Gujarat dairy processors expand steviol glycoside procurement after reformulation investments in yogurt segments. Mumbai-based procurement teams now require 8-14 month lead times for regulatory-compliant product launches.
Non Sugar Sweeteners Market Competitive Environment
Top-tier vendors anchor integrated supply chains, while mid-scale processors compete on specialized modification capabilities. The vendor base stratifies between agricultural extraction operators and fermentation-platform specialists. Three archetypes dominate: stevia leaf processors with captive Latin American growing contracts, enzymatic bioconversion technology licensors, and synthetic molecule manufacturers with REACH-compliant European production assets. Capacity expansion and direct-to-manufacturer offtake agreements constitute the dominant competitive moves.
Within the integrated agricultural processor archetype, Cargill Incorporated and Tate & Lyle PLC exemplify backward control over raw material sourcing. Ajinomoto Co. Inc. occupies a distinct position representing Japanese fermentation-derived amino acid sweetener expertise. These three entities anchor competitive positioning across divergent production pathways—leaf extraction, synthetic modification, and microbial fermentation—without overlapping core technology bases.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc. |
| Ajinomoto Co. Inc. |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Südzucker AG |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
Stevia leaf price indices in Paraguay and China cascade through enzymatic refinement costs into three-tier pricing structures across premium, standard, and economy levels. Contract duration and volume commitments separate multinational beverage offtake agreements from spot-market purchases by regional blenders.
Pricing Analysis
Lead-time compression commands premium pricing, with 90-day contract windows attracting 15-20% markups over annual offtake agreements. Price differentiation hinges on enzymatic modification grade and EFSA certification tier, with thermally stabilized variants capturing margins above standard Reb-A extracts. Cost compression in synthetic sucralose runs through Shandong fermentation scale-up, eroding legacy manufacturer positions. Food manufacturers with captive formulation teams exhibit lowest price sensitivity, while fragmented foodservice operators negotiate aggressively on packet-level procurement.
Supply Chain Analysis
Single-source vulnerability sits with Paraguayan stevia leaf concentration, where Alto Paraná growing regions supply 60% of global enzymatic modification feedstock. Raw material flows draw from Chinese monk fruit extraction in Guilin and Indian sucralose modification at Gujarat chemical parks. Tariff exposure on US-bound fermentation-derived allulose threatens Yangtze River Delta facility economics. Distribution runs through direct-to-manufacturer contracts with California and Texas beverage clusters, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization tightening and FSSAI labeling stringency erect regulatory moats favoring incumbent players with captive analytical capabilities and established GRAS determinations.
For Market Incumbents: Hedge against fermentation-derived sweetener displacement by securing multi-year offtake contracts with Paraguayan stevia processors and Chinese monk fruit extractors. Backward integration into enzymatic bioconversion technology licensing protects margin structures threatened by precision fermentation scale-up in Yangtze River Delta facilities. For New Entrants and Emerging Players: Begin with bakery heat-stability applications where thermally modified sucralose variants face limited incumbent specialization and pricing remains above commodity carbonated beverage grades. Direct-to-manufacturer channel access in Texas and California procurement clusters offers the most penetrable entry vector against entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-platform specialists with SAMR-registered facilities in China and FDA GRAS self-determination capabilities. Watch EFSA acceptable daily intake threshold adjustments as the critical inflection signal for European dairy and confectionery formulation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Scale-Up | Collapses production costs for rare sugar molecules through engineered yeast strain optimization at Yangtze River Delta facilities. |
| Direct-to-Manufacturer Supply Agreements | Bypasses traditional distributor networks by securing multi-year offtake contracts with concentrated California and Texas beverage production clusters. |
| Heat-Stability Modification Investment | Unlocks untapped cookie and cake segments through sucralose variants maintaining sweetness integrity at 180°C oven temperatures. |
| Regulatory Certification Pathway | Accelerates market entry timelines through FDA GRAS self-determination and EFSA acceptable daily intake threshold navigation. |
| Captive Agricultural Contracting | Secures consistent raw material flows through tax-advantaged growing operations in Paraguay's Alto Paraná special economic zone. |
Study Parameters
Document review covered FDA GRAS determinations, EFSA toxicological assessments, and FSSAI labeling directives, complemented by interviews with formulation chemists at major beverage producers, procurement leads at stevia extraction facilities, regulatory affairs specialists, and flavor chemists specializing in bitter-blocking compound integration. Secondary validation drew from customs trade data, food additive petition filings, and industry association technical reports. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type (sucralose, stevia, acesulfame K, aspartame), application (beverages, bakery, dairy, confectionery), and end-user procurement sophistication. CAGRs were derived from trend extrapolation moderated by regulatory event probability weighting. Forecast inputs incorporated EFSA acceptable daily intake revision schedules and SAMR enforcement intensity trajectories.
EFSA threshold recalibrations, SAMR labeling enforcement escalations, and stevia harvest disruption events are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory timelines and agricultural yield stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Maltodextrin Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Rare Sugar Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Sugar Syrups Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
South Korea Allulose Market
Sweeteners
Fructose Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Xylitol Market
Sweeteners
China Saccharin Market