
 Sucrose Acetate Isobutyrate Market | 2026-2036
Sucrose Acetate Isobutyrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sucrose Acetate Isobutyrate Market Outlook
Technical-grade formulation services is consolidating around sucrose acetate isobutyrate supply, shifting value capture from commodity chemical sales toward certified compliance packages. Eastman Chemical Company leverages backward integration into sucrose ester feedstocks to control batch consistency. Celanese Corporation anchors North American pharmaceutical excipient supply through dedicated SAIB compounding lines. Merck KGaA specializes in ultra-high-purity grades for European flavor houses navigating EFSA purity thresholds.
Sucrose acetate isobutyrate is a sucrose ester synthesized through acetylation and isobutyrylation, yielding a clear viscous liquid with a molecular weight near 846 g/mol and a refractive index of 1.454; it functions primarily as a density-matching agent and stabilizer in beverage emulsions and as a controlled-release matrix in pharmaceutical coatings. Food Grade product type dominates volume due to carbonated soft drink and flavor emulsion demand, though Pharmaceutical Grade commands the widest margin pool as oral drug delivery formulations require sub-ppm residual solvent certification. The Application split shows Coatings maturing in wood-finish segments while Personal Care accelerates as cosmetic brands seek silicone-alternative film formers.
REACH registration requirements and FDA food-contact notifications shape purity specifications and testing burdens for manufacturers serving European and North American buyers. BIS standards in India and GB standards in China add parallel compliance layers for suppliers targeting Asia-Pacific formulation houses. Stakeholders must monitor evolving pharmaceutical excipient monographs and regional clean-label definitions to anticipate grade-mix shifts before capacity commitments lock in.
Market Dynamics
Clean-label beverage reformulation is compressing formulation windows for sucrose acetate isobutyrate suppliers, forcing simultaneous compliance with FDA food-contact notifications and EFSA purity thresholds while maintaining batch-to-batch density-matching consistency for carbonated soft drink emulsions.
Growth Catalysts
- REACH registration tiers:European flavor houses now specify sub-ppm residual solvent grades to preempt ECHA substance evaluation, pulling pharmaceutical-grade capacity into food-contact applications.
- Carbonated soft drink emulsion stabilization:Bottlers in the United States source SAIB to replace brominated vegetable oil in citrus-flavored formulations, creating dedicated demand lines.
- Wood-finish coating segments:SAIB functions as a non-yellowing film former in clear lacquers, displacing traditional nitrocellulose modifiers in furniture manufacturing clusters.
Market Restraints
- Sucrose ester feedstock volatility:Raw sugar price swings and acetic anhydride supply tightness squeeze margin structures for non-integrated compounders.
- Supplier concentration in North America:Backward-integrated producers control batch consistency certification, limiting second-tier entrants in pharmaceutical excipient supply.
- Silicone-alternative performance gaps:Personal care formulators encounter film-forming durability limitations when substituting SAIB for dimethicone in long-wear cosmetic applications.
Strategic Opportunities
- Indian beverage formulation houses:BIS standards adoption lags FDA benchmarks, creating first-mover windows for compliant SAIB suppliers ahead of enforcement tightening.
- Oral drug controlled-release matrices:SAIB compounding lines can pivot to sustained-release coatings as pharmaceutical outsourcing concentrates in North American CMO networks.
- EU Green Deal solvent reduction mandates:SAIB's low-VOC profile aligns with industrial coating reformulation incentives, opening technical-grade volume in wood-finish segments.
Industry Challenges
- Residual solvent certification timelines:Pharmaceutical-grade validation requires 18-24 month stability studies, locking working capital before revenue recognition.
- Cross-functional regulatory expertise:Formulation houses lack personnel fluent in both FDA food-contact notifications and REACH dossier preparation, delaying multi-market launches.
- Legacy emulsion equipment compatibility:High-viscosity SAIB grades demand heated transfer lines that older beverage plants cannot retrofit without significant capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sucrose Acetate Isobutyrate Market |
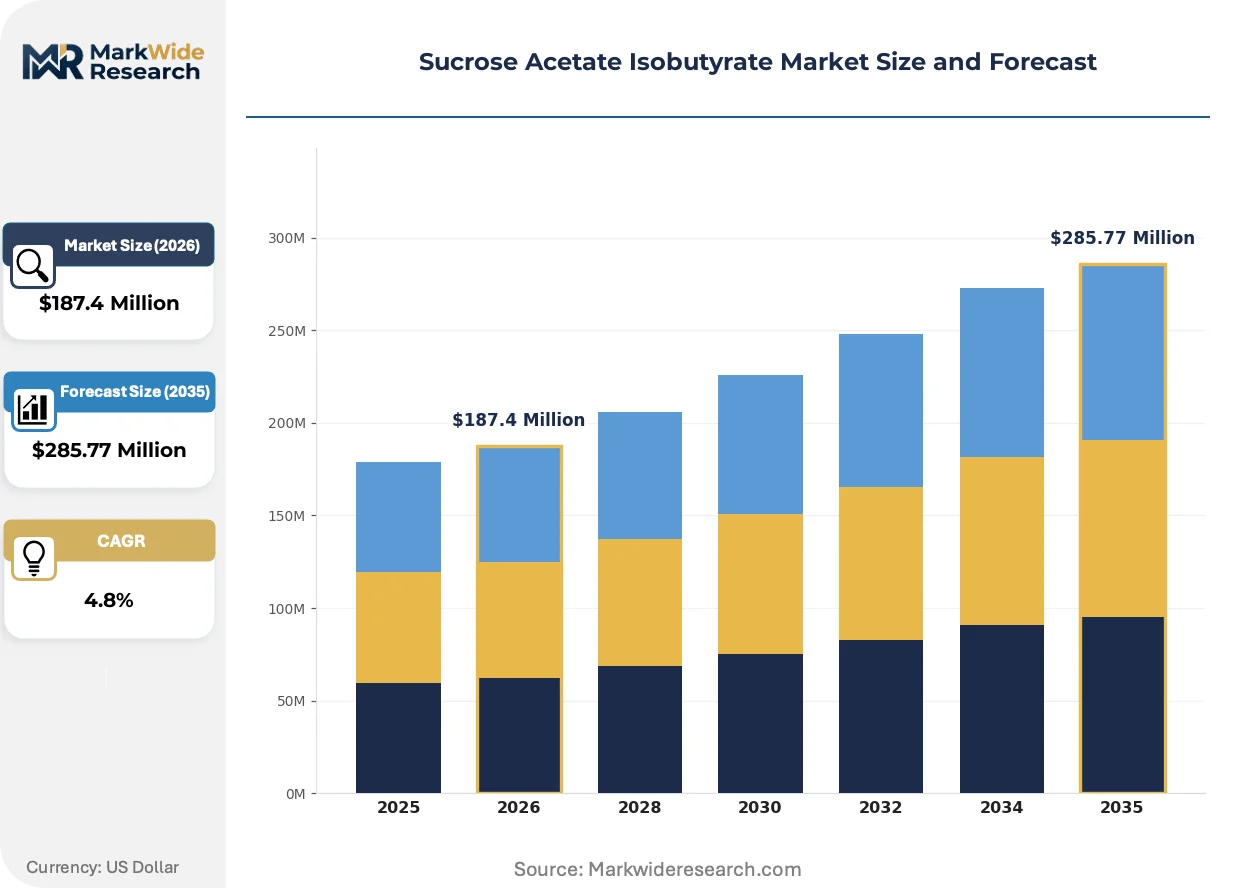
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food Additive, Pharmaceutical Excipients, Coatings, Personal Care End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Research Institutions Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Supermarkets |
| Companies Covered | Eastman Chemical Company, Celanese Corporation, BOC Sciences, Shanghai Jiulin Industrial Co., Ltd., Merck KGaA, Sigma-Aldrich, Dow Chemical Company, Fooding Group Limited, DURECT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sucrose Acetate Isobutyrate Market Strategic Shifts
Reformulation chemistry and regulatory harmonization pressures are reshaping how sucrose acetate isobutyrate grades are specified, tested, and supplied across beverage, pharmaceutical, and industrial coating segments.
Continuous processing technology for sucrose ester synthesis is expanding into commercial-scale SAIB production, replacing batch reactors with plug-flow systems that reduce solvent residuals by an order of magnitude. Pharmaceutical excipient manufacturers in Germany and Switzerland are adopting these lines to preempt EMA impurity guideline revisions. The technology is expanding into food-grade supply as bottlers demand certificate-of-analysis consistency that batch variability cannot deliver.
REACH Annex XV dossier preparation for sucrose esters is compressing formulation timelines as ECHA evaluates endocrine disruption potential, forcing suppliers to generate extended one-generation reproductive toxicity studies ahead of regulatory deadlines. Flavor houses in France and the Netherlands are qualifying alternative emulsion stabilizers simultaneously to mitigate authorization risk. The policy shift most affects mid-tier compounders lacking dedicated regulatory affairs functions.
Direct procurement from compounders by beverage brand owners is disintermediating traditional distributor channels, with procurement teams now requiring audit rights over sucrose ester feedstock sourcing. This pattern concentrates in the United States where consolidated bottler networks negotiate multi-year supply agreements locking in purity specifications. The shift pressures smaller flavor houses to consolidate purchasing or absorb compliance costs previously borne by intermediaries.
Sucrose Acetate Isobutyrate Market Segmentation
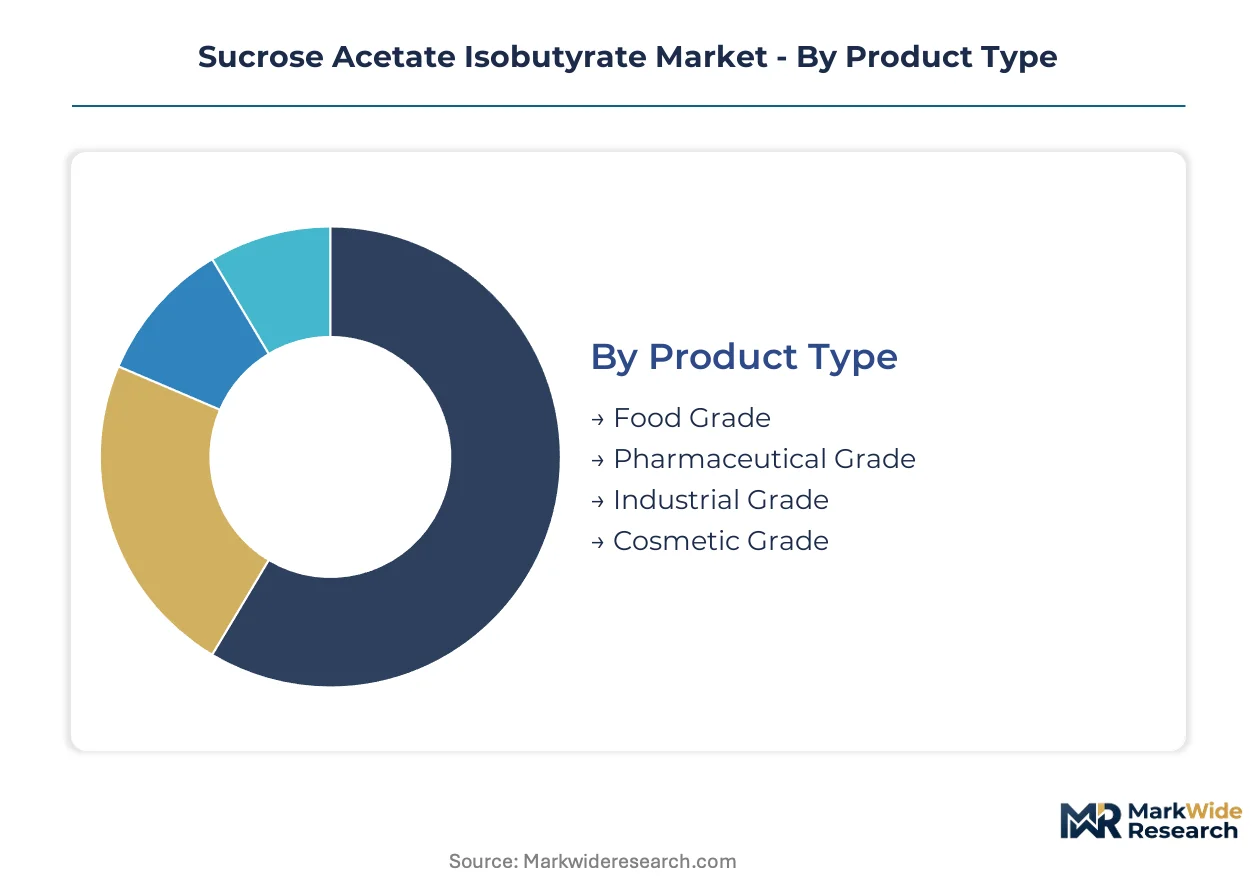
Sucrose acetate isobutyrate specifications diverge sharply across end-use applications, with pharmaceutical and food-contact grades commanding distinct purity certifications and testing protocols. Grade selection determines regulatory pathway, margin structure, and supplier qualification requirements for compounders.
Product Type:
Cost tier separates buyers seeking certificate-of-analysis consistency from those tolerating wider batch variability for price-sensitive applications.
- Food Grade:Formulated to FDA food-contact notification standards with density-matching precision for beverage emulsion stabilization. Carbonated soft drink bottlers in the United States source this grade to replace brominated vegetable oil in citrus flavor systems, pulling capacity from technical-grade lines.
- Pharmaceutical Grade:Manufactured under ICH Q3C residual solvent guidelines with sub-ppm certification for oral drug delivery matrices. European oral solid dosage formulators specify this grade for controlled-release coatings, creating dedicated demand insulated from commodity pricing swings.
- Industrial Grade:Technical formulation for wood-finish lacquers and coating modifiers where VOC reduction drives substitution.
- Cosmetic Grade:Film-forming agent for silicone-alternative personal care applications with sensory performance requirements.
Volume sits with Food Grade; growth tilts toward Pharmaceutical Grade.
Application:
Application maturity determines whether SAIB functions as a reformulation substitute or a formulation-native ingredient.
- Food Additive:Density-matching agent in flavor emulsions for carbonated beverages, replacing legacy stabilizers under clean-label pressure. Bottlers demand heated transfer line compatibility, limiting adoption at older production facilities.
- Pharmaceutical Excipients:Controlled-release matrix material in sustained-release tablet coatings, requiring 18-24 month stability studies for regulatory filing.
- Coatings:Non-yellowing film former in furniture lacquers, expanding under EU Green Deal solvent reduction mandates.
- Personal Care:Silicone-alternative film former in color cosmetics, facing durability performance gaps against dimethicone benchmarks.
Coatings applications expand most quickly; Food Additive captures current volume concentration.
End User:
Customer scale dictates procurement modality and compliance burden allocation.
- Food Manufacturers:Flavor houses and bottlers with direct compounder auditing rights, consolidating purchasing through multi-year supply agreements.
- Pharmaceutical Companies:Outsourced manufacturing organizations and innovator firms requiring excipient master file documentation.
- Cosmetic Brands:Clean-label formulators seeking silicone alternatives with sensory performance trade-offs.
- Research Institutions:Academic and contract research organizations sourcing small-batch grades for formulation development.
Procurement concentrates with Food Manufacturers; qualification activity climbs fastest among Pharmaceutical Companies.
Distribution Channel:
Channel selection reflects buyer technical capability and volume scale.
- Online Retail:Small-laboratory and research-grade sourcing with certificate-of-analysis download functionality.
- Wholesale Distributors:Traditional intermediaries losing share as direct procurement disintermediates beverage supply chains.
- Direct Sales:Multi-year agreements with audit rights over sucrose ester feedstock sourcing, dominating pharmaceutical and large bottler procurement.
- Supermarkets:Limited consumer-facing presence for specialty chemical grades.
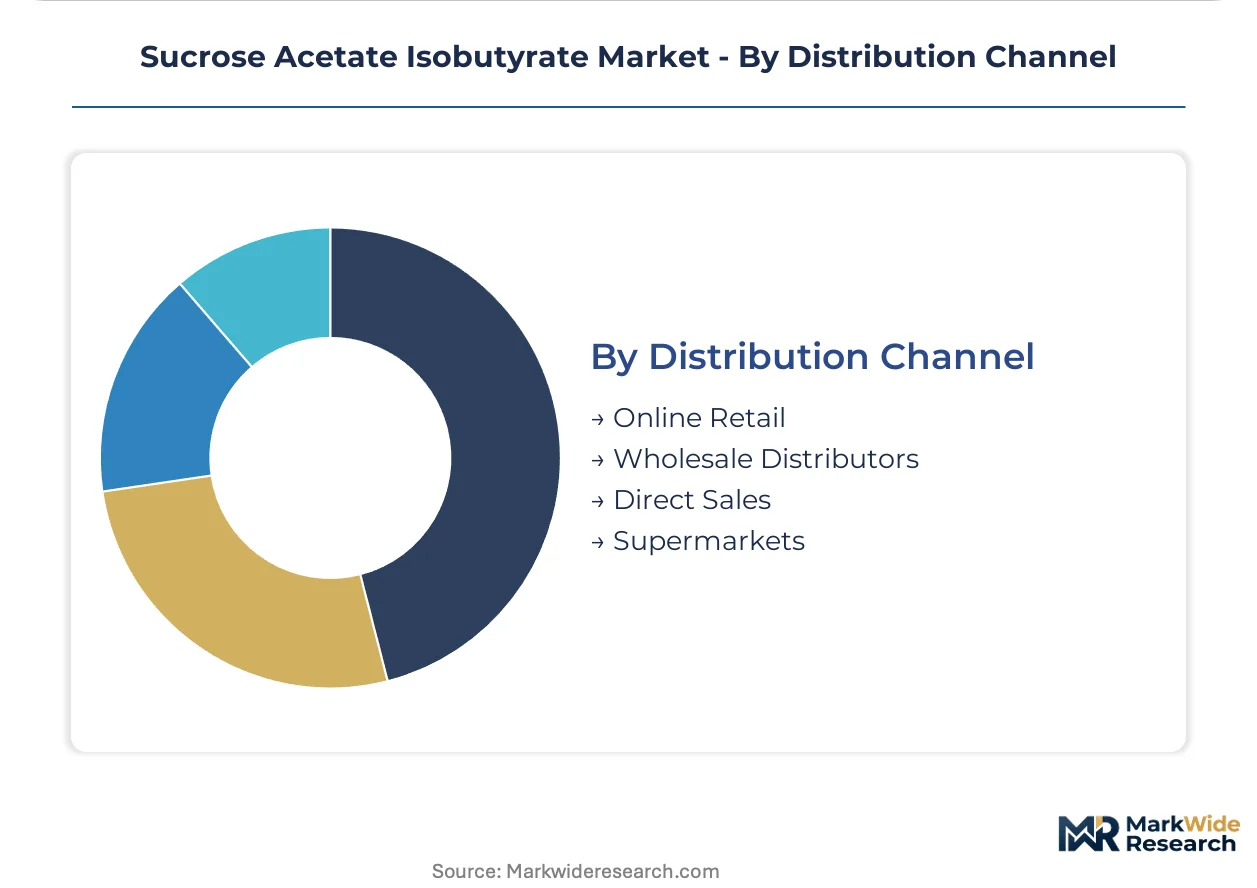
Direct Sales channels capture volume leadership; Online Retail posts steepest expansion trajectory for small-batch qualification samples.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's chemical corridor anchors North American sucrose acetate isobutyrate formulation activity, with flavor houses and pharmaceutical excipient compounders clustering near Port Newark for sucrose ester feedstock access.
United States
Citrus-flavored carbonated beverage reformulation drives SAIB procurement as bottlers replace brominated vegetable oil under FDA food-contact notification requirements. The FDA maintains strict density-matching specifications for emulsion stabilizers. New Jersey and Ohio host concentrated flavor house operations where heated transfer line retrofits enable high-viscosity grade adoption.
Germany
Pharmaceutical excipient manufacturers prioritize sub-ppm residual solvent certification for oral controlled-release matrices. EMA impurity guideline revisions under ICH Q3C standards tighten validation protocols. The Rhine-Main industrial region houses specialized SAIB compounding facilities serving European oral solid dosage formulators.
China
Wood-finish coating manufacturers adopt SAIB as a non-yellowing film former under GB standards for VOC reduction in furniture lacquers. SAMR oversees food-contact substance notifications parallel to FDA benchmarks. The Yangtze River Delta contains concentrated technical-grade production serving both domestic coating houses and export pharmaceutical customers.
India
Beverage formulation houses prepare for BIS standards enforcement tightening ahead of current FDA-equivalent benchmarks. FSSAI regulates food additive purity while CDSCO governs pharmaceutical excipient import quality. Maharashtra and Gujarat host emerging flavor emulsion operations where first-mover SAIB suppliers establish compliance credentials.
Switzerland
Ultra-high-purity SAIB grades serve European flavor houses navigating EFSA purity thresholds for clean-label positioning. Swissmedic oversees pharmaceutical-grade certification timelines requiring extended stability studies. Basel's pharmaceutical cluster demands excipient master file documentation for oral drug delivery outsourcing contracts.
Sucrose Acetate Isobutyrate Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the sucrose acetate isobutyrate value chain. The supplier base concentrates around backward-integrated chemical conglomerates controlling sucrose ester feedstock production. Three archetypes dominate: integrated petrochemical majors with captive acetic anhydride supply, specialized excipient houses with pharmaceutical-grade certification infrastructure, and regional compounders serving technical coating applications. Capacity expansion and regulatory dossier preparation represent the primary competitive moves as REACH registration tiers and FDA notification requirements escalate compliance barriers.
Among integrated chemical producers, Eastman Chemical Company and Celanese Corporation exemplify the backward-integrated archetype with in-house control over sucrose ester feedstock consistency. Merck KGaA occupies a position within the ultra-high-purity specialist tier, anchoring European pharmaceutical-grade supply through dedicated compounding lines. These three entities represent distinct strategic positions: feedstock-integrated volume leadership, North American pharmaceutical excipient dominance, and European purity-threshold specialization respectively.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Celanese Corporation |
| BOC Sciences |
| Shanghai Jiulin Industrial Co., Ltd. |
| Merck KGaA |
| Sigma-Aldrich |
| Dow Chemical Company |
| Fooding Group Limited |
| DURECT |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal solvent reduction mandates gate qualified supply and premium-tier pricing access, as wood-finish coating manufacturers must source low-VOC SAIB grades to comply with industrial reformulation incentives. Buyers seeking pharmaceutical-grade certification face extended validation timelines that compress available supplier pools and sustain margin premiums for qualified compounders.
Pricing Analysis
Yield-based pricing anchors SAIB procurement, with beverage bottlers paying premiums for density-matching consistency that prevents emulsion separation in carbonated soft drinks. Pharmaceutical-grade certification under ICH Q3C guidelines commands the widest spreads, while food-grade volume contracts compete on acetic anhydride pass-through economics. Cost compression in technical-grade lines is intensifying because sucrose ester feedstock volatility squeezes non-integrated compounders. Mid-tier flavor houses show highest price sensitivity; pharmaceutical outsourcers demonstrate least.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated beverage bottlers mandate multi-supplier qualification, forcing compounders to maintain redundant production lines. Manufacturing concentrates in the United States, Germany, and China, with New Jersey's chemical corridor anchoring North American formulation. Supply draws from raw sugar, acetic anhydride, and isobutyric anhydride inputs. Single-source vulnerability persists for pharmaceutical-grade certification capacity. Distribution runs through direct sales channels with audit rights over sucrose ester feedstock sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade validation bottlenecks prop pricing across all tiers, as 18-24 month stability studies lock working capital and constrain qualified supply expansion.
For Market Incumbents: Deepen backward integration into sucrose ester feedstocks to insulate margin structures from raw sugar and acetic anhydride volatility. Expand dedicated SAIB compounding lines in the Rhine-Main region to capture European pharmaceutical outsourcing concentration. Lock multi-year supply agreements with consolidated US bottlers before BIS standards enforcement tightens in India.
For New Entrants and Emerging Players: Regional beverage formulation houses in Maharashtra and Gujarat present the most penetrable entry point, as BIS standards adoption lags FDA benchmarks and first-mover compliance credentials remain unclaimed. Target wood-finish coating technical-grade supply under EU Green Deal mandates where incumbent capacity is absorbed by pharmaceutical queues. Lead with heated transfer line retrofit partnerships to overcome legacy plant compatibility barriers.
For Investors and Strategic Acquirers: REACH Annex XV dossier preparation acceleration is the leading indicator that regulatory compliance costs will consolidate mid-tier compounders into acquisition targets. The five-to-ten year viability window favors ultra-high-purity specialists with dedicated regulatory affairs functions over commodity-grade producers. Watch for ECHA substance evaluation outcomes on sucrose esters as the signal for authorization risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sucrose Ester Feedstocks | Eastman Chemical's captive supply controls batch consistency certification for beverage emulsion customers. |
| Pharmaceutical-Grade Capacity Expansion | Celanese Corporation anchors North American oral drug delivery outsourcing through dedicated compounding lines. |
| Continuous Processing Technology Adoption | Plug-flow systems reduce solvent residuals by an order of magnitude, preempting EMA impurity guideline revisions. |
| Direct Procurement Channel Development | Audit rights over sucrose ester sourcing disintermediate traditional distributors for consolidated bottler networks. |
| REACH Dossier Preparation Investment | Extended one-generation reproductive toxicity studies mitigate authorization risk for European flavor house supply. |
Study Parameters
Multi-period observation of FDA food-contact notification filings, REACH registration tiers, and EMA impurity guideline revisions anchored the trend analysis, supplemented by interviews with flavor house procurement directors, pharmaceutical excipient compounders, beverage bottler technical managers, and wood-finish coating formulators. Secondary validation drew from ECHA substance evaluation databases, FDA GRAS notices, SEC 10-K chemical segment disclosures, and customs trade data. Bottom-up volume estimates triangulated against top-down industry consumption models.
Segment-weighting across product type, application, and end-user dimensions structured the analytical framework, with grade-specific purity certification tiers receiving differential growth assumptions. CAGRs derived from elasticity-adjusted demand projections for carbonated beverage emulsion stabilization, oral controlled-release pharmaceutical matrices, and EU Green Deal-driven coating reformulation. Feedstock cost pass-through coefficients and regulatory compliance timeline distributions informed scenario boundaries.
Revisions become necessary when ECHA substance evaluation outcomes, FDA notification requirement changes, or sucrose ester feedstock supply disruptions materialize. Deviation in pharmaceutical-grade validation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar Syrups Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Corn Syrup Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Allulose Market
Sweeteners
Rare Sugar Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Tagatose Market
Sweeteners
Aspartame Market
Sweeteners
Saccharin Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Erythritol Market