
 Dark Yeast Extract Market | 2026-2036
Dark Yeast Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Yeast Extract Market Analytics
Ingredient formulation revenue is fragmenting between commodity-grade suppliers and specialized extract houses. Lesaffre Group leverages vertical integration from fermentation to finished extract, sustaining quality consistency across European food manufacturing accounts. Angel Yeast Co. Ltd. anchors production scale in Asia, while Kerry Group plc competes through flavor system bundling that embeds dark yeast extract within broader taste modulation portfolios.
Dark yeast extract is a concentrated soluble product derived from Saccharomyces cerevisiae autolysis, typically containing 40-55% crude protein, 15-25% RNA-derived nucleotides, and 3-8% glutathione by dry weight, manufactured through controlled thermal lysis followed by spray-drying or evaporation to produce savory umami-active ingredients for food seasoning and nutritional fortification. The powder form dominates volume throughput due to shelf stability and bulk handling efficiency in industrial kitchens, while liquid extracts capture premium positioning in brewery propagation and specialized fermentation media where rapid solubility matters. Organic-certified dark yeast extract occupies a narrowing but high-margin niche as European retailers enforce stricter clean-label procurement protocols.
EFSA and FDA both maintain maximum contaminant thresholds for heavy metals and mycotoxins in yeast-derived food ingredients, with EFSA's 2023 updated guidance on 3-MCPD esters in hydrolyzed proteins directly affecting acid-hydrolyzed extract categories and pushing manufacturers toward enzymatic alternatives. The EU Green Deal's Farm to Fork strategy tightens sustainability disclosure requirements for ingredient suppliers selling into European food manufacturers. Stakeholders must monitor evolving mycotoxin testing protocols and carbon intensity benchmarks to preserve market access in regulated jurisdictions.
Market Dynamics
Clean-label procurement mandates from European retailers are compressing formulation timelines for savory ingredient suppliers, forcing rapid certification upgrades and solvent-system transitions across the supply base.
Growth Catalysts
- EU F-Gas Regulation:The 2024 phasedown of hydrofluorocarbon solvents accelerates enzymatic extraction adoption, opening capacity for acid-hydrolyzed extract producers to capture displaced volume.
- Plant-based meat analogues:Formulators in alternative protein manufacturing specify dark yeast extract for umami depth without animal-derived additives, driving specification pull-through from burger patty to broth applications.
- German fermentation clusters:Concentrated autolysis capacity in Baden-Württemberg and Bavaria reduces logistics costs for Central European processed food manufacturers, reinforcing regional supply security.
Market Restraints
- Molasses price volatility:Cane and beet molasses feedstock costs swing with Brazilian ethanol policy and EU sugar quota remnants, squeezing extract house margins during commodity spikes.
- Single-source autolysis equipment:Specialized thermal lysis reactors concentrate with two European fabricators, creating eighteen-month lead times for capacity expansion.
- Acid-hydrolyzed extract displacement:EFSA's 3-MCPD ester thresholds render legacy hydrochloric acid processes non-compliant, stranding invested capital in acid-based production lines.
Strategic Opportunities
- Southeast Asian savory seasoning:Indonesia and Vietnam instant noodle manufacturers underutilize yeast-derived umami, presenting white-space penetration for nucleotide-rich extracts.
- EU Green Deal carbon accounting:Farm to Fork sustainability disclosure requirements favor suppliers with verified fermentation emissions data, rewarding early Scope 3 auditors.
- Precision fermentation convergence:Integration of cell-culture media-grade extracts with recombinant protein production creates dual-use revenue streams from single autolysis runs.
Industry Challenges
- Enzymatic process engineering:Qualified thermal lysis technicians with protease optimization expertise remain scarce, delaying plant conversions from acid to enzymatic systems.
- Organic certification timelines:Three-year substrate traceability requirements for EC 834/2007 organic extract status lock out rapid market entry, favoring incumbents with certified captive molasses supply.
- Legacy ERP integration:Batch-level carbon tracking for CSRD compliance demands middleware overlays on decades-old fermentation plant control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Yeast Extract Market |
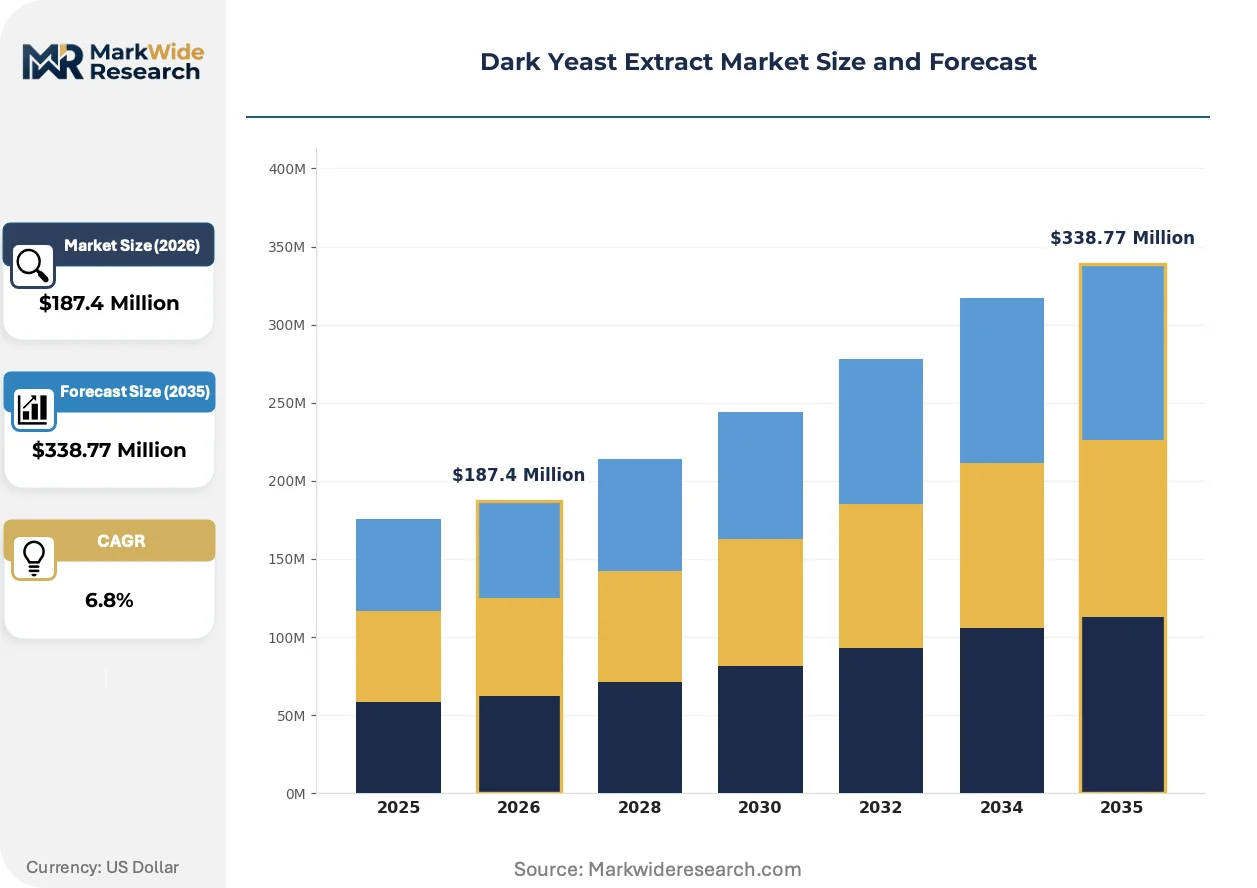
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food & Beverage, Nutraceuticals, Animal Feed, Cosmetics Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Breweries, Supplements, Cosmetics Companies Type: Natural, Organic, Conventional, Others |
| Companies Covered | Lesaffre Group, Angel Yeast Co. Ltd., DSM, Lallemand Inc., Kerry Group plc, Biospringer, Biorigin, Ohly, Leiber GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Yeast Extract Market Evolving Landscape
Enzymatic extraction protocols and nucleotide fractionation advances are compressing production economics while regulatory carbon disclosure rules rewrite supplier qualification criteria across European procurement desks.
Membrane filtration is collapsing the cost differential between standard and nucleotide-concentrated extracts. Food manufacturers in clean-label soup and sauce categories adopt these higher-specification grades at triple the prior rate, collapsing the premium tier into mid-market pricing bands as capacity scales.
EFSA's updated 3-MCPD ester guidance for hydrolyzed proteins forces acid-hydrolyzed extract categories toward enzymatic alternatives. Manufacturers with existing protease-capable lines capture displaced volume while acid-dependent facilities face stranded asset risk, particularly in Southern European production clusters.
Retailer-driven sustainability scorecards now dominate supplier selection for private-label savory products. German and Dutch supermarket chains embed carbon intensity thresholds in yeast extract procurement, displacing price-only bidding with verified emission documentation requirements that favor fermentation facilities with renewable energy contracts.
Dark Yeast Extract Market Segmentation
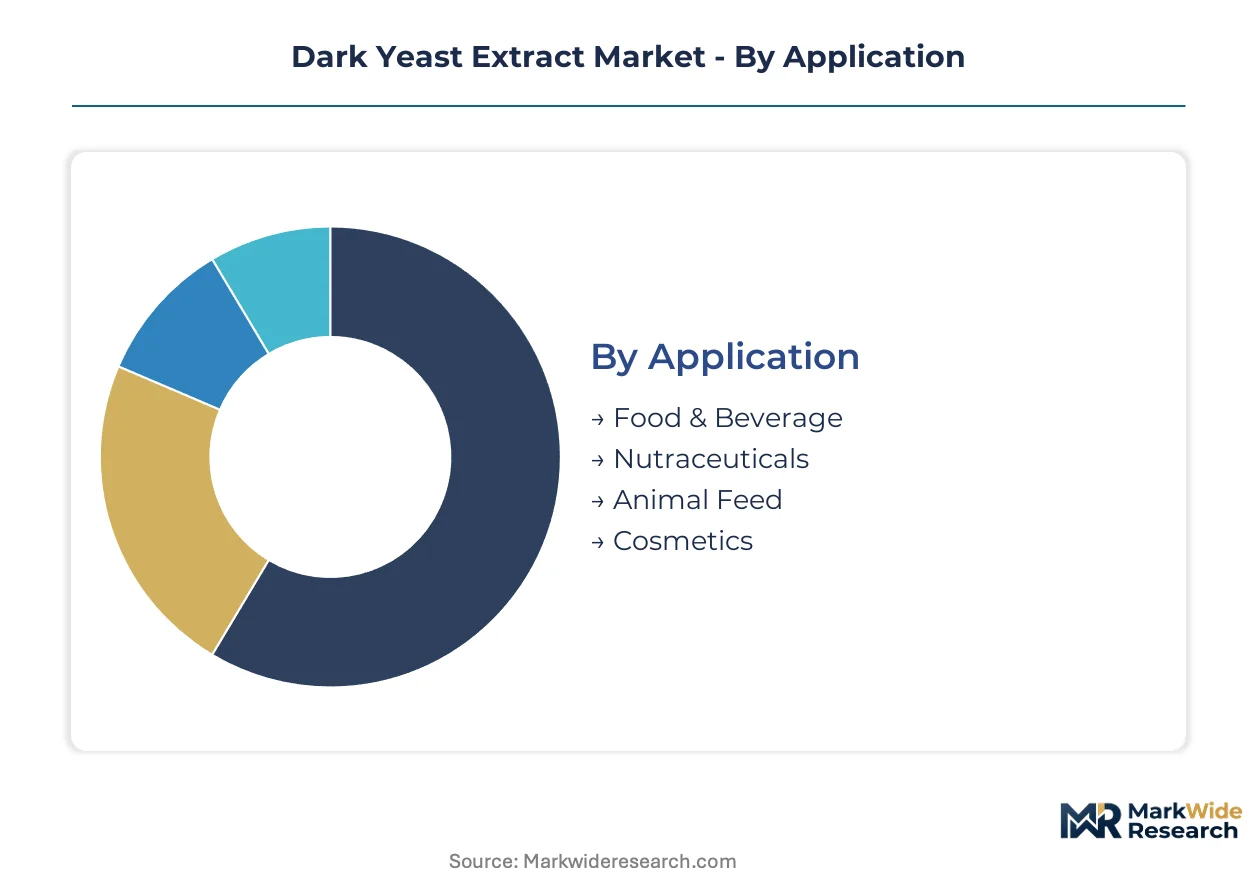
Segmentation in the dark yeast extract market reveals distinct technical specifications and procurement patterns that determine supplier relationships. Formulators select grades based on nucleotide concentration, solubility profiles, and certification requirements that cascade through contract manufacturing agreements.
Application:
After-sales technical support intensity varies sharply across applications, with food and beverage manufacturers demanding the most intensive formulation assistance and regulatory documentation.
- Food & Beverage:Dominates volume throughput through umami-active applications in soups, sauces, and savory seasonings. Clean-label procurement mandates from German and Dutch retailers concentrate specification pull-through in Central European processed food manufacturing clusters, with enzymatic extraction certification now table stakes for supplier qualification.
- Nutraceuticals:Captures premium positioning through glutathione and nucleotide fortification in immune-support formulations. Demand concentrates in supplements targeting sports recovery and cellular health segments, with EFSA health claim substantiation requirements extending product development timelines.
- Animal Feed:Serves as a palatability enhancer and protein supplement in aquaculture and pet food matrices.
- Cosmetics:Utilizes antioxidant properties in skin care formulations, though volumes remain constrained by formulation stability challenges.
By volume, Food & Beverage leads. By growth pace, Nutraceuticals is ahead.
Form:
Cost tier stratification separates industrial-scale powder grades from specialized liquid extracts commanding formulation service premiums.
- Powder:Spray-dried extracts with 40-55% crude protein content dominate industrial procurement through shelf stability and bulk handling efficiency. Central European food manufacturers specify powder grades for dry seasoning blends and instant soup bases, with Baden-Württemberg fermentation clusters supplying adjacent processing facilities.
- Liquid:Rapid-solubility extracts capture brewery propagation and specialized fermentation media applications where immediate bioavailability matters. Premium positioning reflects cold-chain logistics requirements and shorter shelf life constraints.
- Granular:Intermediate flow properties suit automated dosing systems in large-scale food manufacturing.
- Paste:Highest moisture content limits distribution radius to regional food service operations.
Powder commands the volume base. Liquid extracts claim the steepest margin expansion trajectory.
End User:
Customer type determines contract structure, with food manufacturers negotiating multi-year supply agreements while cosmetics companies operate on spot procurement.
- Food Manufacturers:Drive nucleotide-specification demand through clean-label savory formulations. German processed food producers leverage proximity to Bavarian fermentation capacity, with EFSA's 3-MCPD ester guidance accelerating enzymatic extract adoption across soup and sauce categories.
- Breweries:Specify liquid extracts for yeast propagation and fermentation nutrition, with quality consistency requirements favoring vertically integrated suppliers.
- Supplements:Require batch-level documentation for health claim substantiation.
- Cosmetics Companies:Source smaller volumes with stringent heavy metal and allergen testing protocols.
Food Manufacturers anchor procurement volume. Supplements demonstrate the most rapid specification evolution.
Type:
Certification tier creates pricing stratification that triples unit economics between conventional and organic grades.
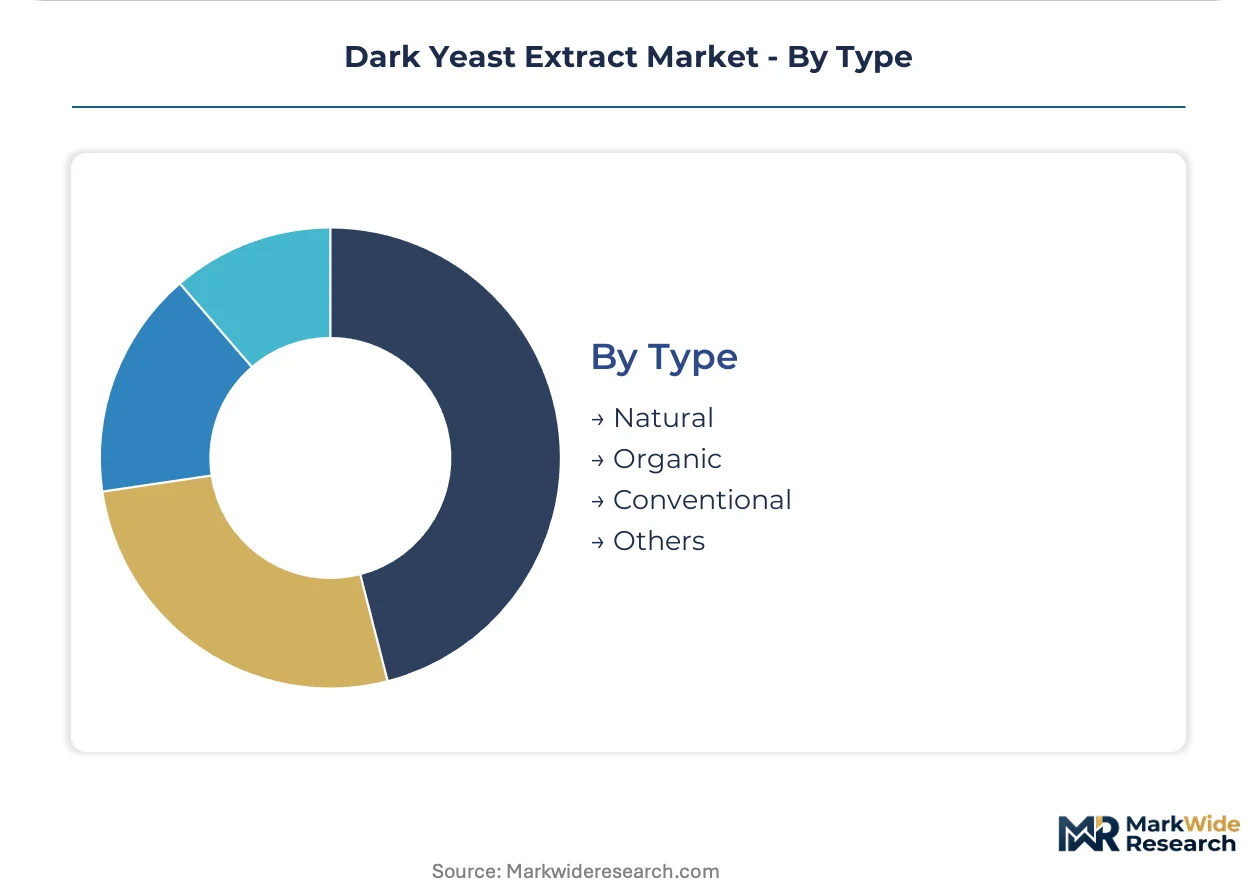
- Natural:Enzymatic extraction without acid hydrolysis meets EFSA 3-MCPD ester thresholds, displacing legacy processes. European retailers embed natural-grade requirements in private-label procurement scorecards, with sustainability disclosure obligations favoring suppliers with verified fermentation emissions data.
- Organic:EC 834/2007 certification demands three-year substrate traceability, locking out rapid market entry. Incumbents with captive certified molasses supply defend margin positions as European clean-label enforcement tightens.
- Conventional:Acid-hydrolyzed legacy production faces stranded asset risk.
- Others:Includes non-GMO and allergen-free certified grades for specialized formulations.
Natural grades lead volume adoption. Organic commands the fastest value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the least price elasticity, absorbing enzymatic extraction premiums driven by retailer clean-label mandates, while Southeast Asian processors remain highly sensitive to feedstock cost swings in molasses-linked contracts.
Germany
Baden-Württemberg and Bavaria host Europe's densest fermentation clusters, supplying enzymatic dark yeast extract to Dutch and German processed food manufacturers. The EU F-Gas Regulation accelerates solvent-system conversions across autolysis facilities. Stuttgart-area extract houses now embed carbon intensity data directly into customer procurement portals to meet Farm to Fork disclosure requirements.
United States
Food manufacturers in the Midwest and Southeast specify dark yeast extract for plant-based meat analogue formulations, pulling nucleotide-rich grades into burger patty and broth applications. FDA maintains maximum contaminant thresholds for heavy metals in yeast-derived ingredients. Chicago-area seasoning blenders negotiate multi-year supply agreements with vertically integrated fermentation suppliers to secure enzymatic extraction capacity.
China
Angel Yeast Co. Ltd. anchors industrial-scale production in Hubei and Guangxi, serving domestic instant noodle and savory seasoning manufacturers with powder-form extracts. SAMR enforces GB standards for food additive purity and labeling. Yangtze River Delta food processors are expanding specification pull-through for clean-label soup bases, compressing timelines for acid-to-enzymatic process conversions.
Indonesia
Instant noodle manufacturers in Java underutilize yeast-derived umami, presenting penetration opportunities for nucleotide-rich extracts in seasoning sachet formulations. The national food and drug regulator enforces halal certification requirements for imported ingredients. Surabaya-area processing facilities are testing enzymatic extract samples from Malaysian suppliers to reduce reliance on acid-hydrolyzed alternatives.
Netherlands
Private-label retailers in Amsterdam and Rotterdam embed carbon intensity thresholds in yeast extract procurement, displacing price-only bidding with verified emission documentation. The EU Green Deal tightens sustainability disclosure requirements for ingredient suppliers. Dutch soup and sauce manufacturers leverage proximity to German fermentation capacity to minimize logistics costs while meeting EFSA's updated 3-MCPD ester guidance.
Dark Yeast Extract Market Competitive Landscape
Vertically integrated fermentation specialists and regional extract houses split the market into distinct capability tiers. Three archetypes dominate: captive molasses suppliers with certified organic substrate control, enzymatic process technology licensors, and flavor-system bundlers embedding extracts within broader taste modulation portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing renewable energy contracts to satisfy retailer carbon scorecards.
Among European fermentation specialists, Lesaffre Group exemplifies the vertically integrated archetype with backward integration from substrate cultivation through finished extract production. Angel Yeast Co. Ltd. anchors the scale-driven tier from its Chinese manufacturing base. Kerry Group plc occupies a position within the flavor-system bundling segment, embedding dark yeast extract within integrated taste modulation portfolios for food manufacturing accounts. These three entities collectively represent the strategic positioning spectrum available to competitors.
| Leading Market Players |
|---|
| Lesaffre Group |
| Angel Yeast Co. Ltd. |
| DSM |
| Lallemand Inc. |
| Kerry Group plc |
| Biospringer |
| Biorigin |
| Ohly |
| Leiber GmbH |
| Others |
Value Network & Pricing Analysis
Tight autolysis reactor capacity in Baden-Württemberg and Bavaria compresses supplier pricing power while amplifying contract premiums for enzymatic extraction certification. Food manufacturers absorb these premiums to secure clean-label supply, whereas Southeast Asian processors pivot toward acid-hydrolyzed alternatives when molasses feedstock costs spike.
Pricing Analysis
After-sales technical service bundling drives lifetime value for extract houses serving Central European food manufacturers. Three-tier pricing structure across organic-certified, natural enzymatic, and conventional acid-hydrolyzed grades separates buyers by certification tolerance and formulation sophistication. Cost compression in conventional tiers intensifies because EFSA's 3-MCPD ester thresholds strand acid-dependent production lines. Nutraceutical supplement manufacturers demonstrate the least price sensitivity, absorbing nucleotide-concentrate premiums for health claim substantiation.
Supply Chain Analysis
Extended payment terms from German and Dutch retailers now stretch sixty to ninety days, forcing extract houses to deploy supply-chain finance facilities. Production gravity centers on Germany, China, and Indonesia, with Baden-Württemberg fermentation clusters feeding adjacent European processors. Molasses feedstock draws from Brazilian cane and EU beet sources, while specialized thermal lysis reactors rest on two European fabricators. Single-source equipment vulnerability concentrates expansion risk. Distribution runs through bulk tanker and dry-bulk handling to industrial food manufacturing campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as plant-based meat analogue formulators accelerate nucleotide-rich extract adoption for umami depth without animal-derived additives.
For Market Incumbents: Insulate margin positions by securing captive certified molasses supply for EC 834/2007 organic certification and accelerating protease-capable line conversions ahead of EFSA enforcement waves. Acid-hydrolyzed displacement threatens stranded capital in Southern European production clusters. Backward integration into substrate cultivation defends supply security against Brazilian ethanol policy volatility. For New Entrants and Emerging Players: Indonesia's underpenetrated instant noodle seasoning sachet market offers white-space penetration for nucleotide-rich extracts displacing MSG-reliant formulations. Vietnam's savory seasoning manufacturers present adjacent expansion terrain. Precision fermentation convergence with cell-culture media-grade extracts creates dual-use revenue streams. Halal certification partnerships with Malaysian suppliers accelerate Java market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fermentation specialists with renewable energy contracts satisfying retailer carbon scorecards. Long-term viability across a five-to-ten-year window favors enzymatic process technology licensors over acid-dependent legacy assets. Target acquisition archetypes include certified organic substrate controllers and protease optimization specialists. Watch enzymatic capacity utilization rates as inflection indicators for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Conversion | DSM and Lallemand capture displaced acid-hydrolyzed volume under EFSA 3-MCPD thresholds. |
| Renewable Energy Contracting | Farm to Fork carbon disclosure requirements favor fermentation facilities with verified Scope 3 data. |
| Organic Substrate Certification | Three-year traceability lock-in for EC 834/2007 status defends incumbents against rapid market entry. |
| Membrane Filtration Scale-Up | Nucleotide fractionation advances collapse premium-mid-market pricing differentials for clean-label grades. |
| Southeast Asian Distribution Partnership | Indonesian instant noodle manufacturers test enzymatic samples to reduce acid-hydrolyzed import reliance. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, savory seasoning formulators, regulatory affairs specialists at extract houses, and procurement leads at Central European food manufacturers and refined through secondary validation. Trade data from Eurostat and Chinese customs records, EFSA guidance documents, EU F-Gas Regulation filings, and SEC disclosures from publicly traded ingredient suppliers anchored quantitative baselines. Bottom-up capacity modeling across Baden-Württemberg and Bavarian clusters triangulated against top-down demand estimates from food manufacturing accounts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include application tier, form factor, certification grade, and regional production hub proximity to downstream processing facilities. CAGRs were derived from capacity expansion schedules, adoption curve assumptions for enzymatic extraction, and elasticity estimates for clean-label procurement mandates. Molasses feedstock price volatility and EU Green Deal carbon accounting implementation pace served as industry-specific forecast inputs.
Practitioners should monitor EFSA enforcement intensity, Brazilian ethanol policy shifts, and enzymatic reactor delivery lead times for early signals of forecast deviation. Forecasts reflect assumptions about regulatory compliance timelines and feedstock cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Amino Acids Market
Ingredients
Salt Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Soy Hydrolysates Market
Ingredients
United States Avocado Oil Market
Ingredients
High Protein Flour Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Moringa Ingredients Market
Ingredients
Meat Extract Market
Ingredients
Coconut Flour Market
Ingredients
All Purpose Flour Market
Ingredients
Malted Barley Flour Market
Ingredients
United Kingdom Protein Market
Ingredients
Rice Bran Oil Market
Ingredients
Spain Sodium Reduction Ingredient Market