
 South America Low-Calorie Sweeteners Market | 2026-2036
South America Low-Calorie Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
South America Low-Calorie Sweeteners Market Analytics
Multi-source procurement of stevia leaf and fermentation-derived sweeteners is restructuring supply economics for South American food manufacturers. Cargill Incorporated leverages its integrated agricultural sourcing networks across Brazil and Argentina to secure raw material consistency. Tate & Lyle PLC sustains technical service capabilities that anchor formulation partnerships with regional beverage producers. Ingredion Incorporated competes through specialty sweetener blends that address clean-label requirements in local markets.
Low-calorie sweeteners comprise high-intensity compounds—steviol glycosides, sucralose, aspartame, and acesulfame potassium—that deliver sweetness at substantially reduced caloric contribution compared to sucrose, typically requiring concentrations below one percent by weight in finished products. These compounds serve primarily to reduce sugar content in processed foods and beverages while maintaining consumer-acceptable taste profiles. The stevia segment leads volume adoption as extraction yields improve and bitter aftertaste issues diminish through enzymatic modification processes. Sucralose maintains margin concentration in industrial-scale beverage applications where thermal stability during pasteurization proves critical. The bakery application segment shows accelerated growth as reformulation challenges around Maillard browning and moisture retention yield to modified sweetener systems.
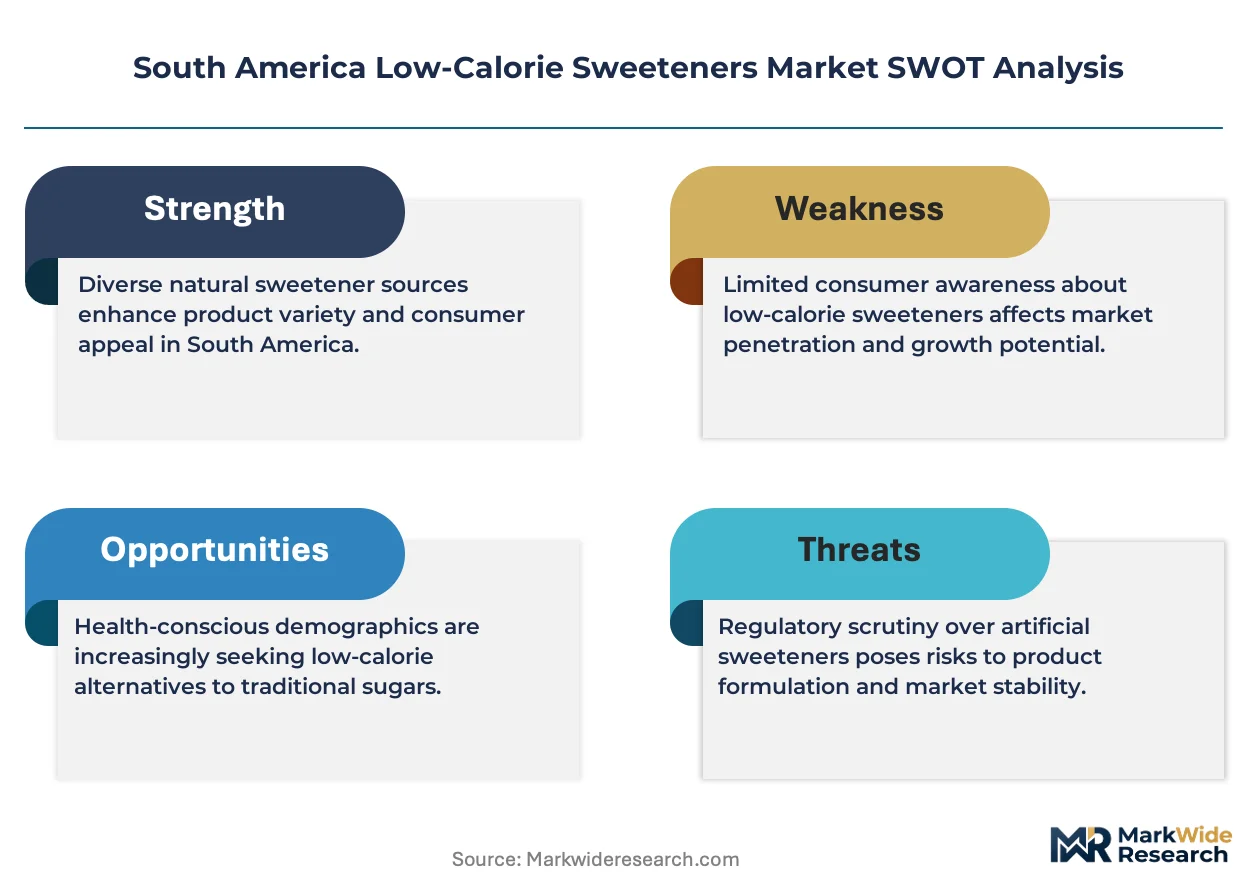
ANVISA governs food additive approvals and maximum usage levels across Brazil, while Argentina's national food safety authority enforces parallel standards that manufacturers must navigate for cross-border distribution. The Mercosur harmonization process for food additive regulations creates compliance complexity but also pathway opportunities for unified product registrations. Stakeholders must monitor evolving front-of-package labeling requirements and sugar reduction mandates that will determine which sweetener technologies receive prioritized investment across the region.
Market Dynamics
ANVISA's updated front-of-package labeling requirements and stevia extraction yield improvements are compressing formulation timelines for Brazilian beverage manufacturers, forcing simultaneous reformulation across multiple product lines.
Growth Catalysts
- Clean-label mandates:ANVISA's sugar reduction targets for processed beverages accelerate reformulation demand across São Paulo's manufacturing corridor.
- Enzymatic stevia modification:Bitterness reduction technologies expand addressable applications into premium confectionery segments previously closed to plant-derived sweeteners.
- Argentina's cross-border distribution:Mercosur harmonization discussions create pathway efficiencies for unified product registrations spanning Brazil and Argentina.
Market Restraints
- Stevia leaf supply volatility:Raw material sourcing concentrates in Paraguay and southern Brazil, exposing processors to climate-driven harvest fluctuations.
- Thermal stability limitations:Aspartame degradation above 30°C restricts high-temperature bakery applications without encapsulation investments.
- Dual compliance burden:Divergent maximum usage levels between ANVISA and Argentina's national food safety authority inflate registration costs for regional brands.
Strategic Opportunities
- Colombia's underdeveloped beverage sector:Sugar reduction lag in Andean markets creates first-mover positioning for stevia-based formulations.
- Fermentation-derived sweeteners:Precision fermentation convergence with Brazilian sugarcane ethanol infrastructure enables novel production economics.
- E-commerce ingredient channels:Direct procurement platforms bypass traditional distributor markups for mid-sized Argentine food processors.
Industry Challenges
- Maillard reaction expertise gap:Bakery reformulation demands specialized food chemists scarce in regional labor markets.
- Encapsulation capex requirements:Heat-stable sweetener production demands spray-drying equipment beyond mid-tier manufacturer balance sheets.
- Cross-border certification timelines:Mercosur mutual recognition delays extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Low-Calorie Sweeteners Market |
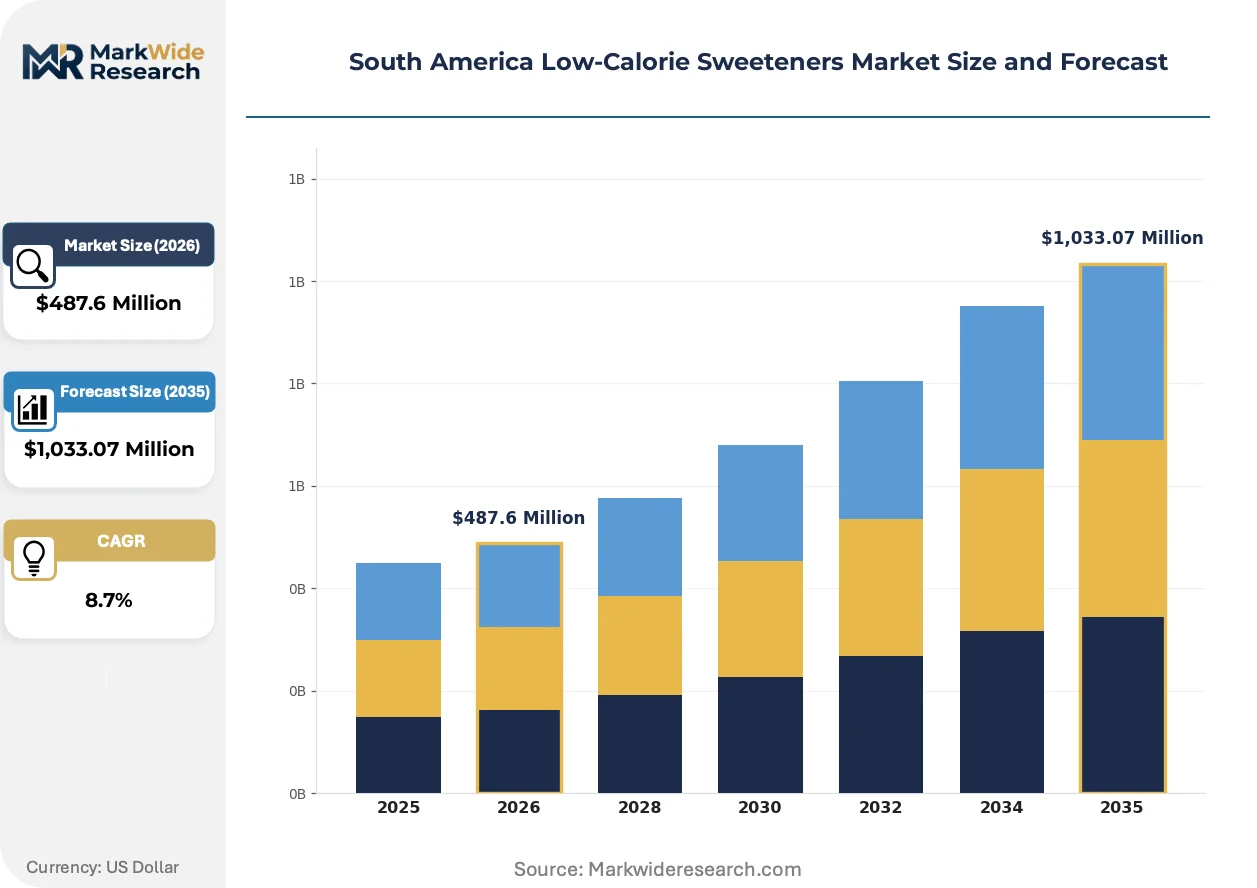
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Sucralose, Aspartame, Acesulfame Potassium Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Producers, Health Food Brands, Restaurants Distribution Channel: Online Retail, Supermarkets, Health Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion Incorporated, PureCircle, Roquette Frères, GLG Life Tech Corp, DuPont de Nemours, Inc., Ajinomoto Co., Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Low-Calorie Sweeteners Market Evolving Landscape
Bioprocessing advances and regulatory labeling pressure are collapsing traditional boundaries between natural and synthetic sweetener categories across South American formulation labs.
Enzymatic glycosylation systems is unifying stevia taste profiles across Reb-A and Reb-M variants, eliminating the bitter linger that previously segmented applications. Brazilian beverage giants in Minas Gerais deploy these systems at pilot scale, compressing the premium-natural versus cost-engineered formulation divide into a single ingredient platform.
ANVISA's 2023 front-of-package warning label expansion forces sugar content disclosure above 10g per serving, accelerating reformulation cycles. Industrial-scale beverage producers respond by locking multi-year stevia supply contracts, while smaller Argentine competitors delay launches awaiting regulatory clarity on blended sweetener classification thresholds.
Ingredient procurement through digital B2B platforms fragments traditional distributor relationships, with São Paulo-based manufacturers sampling fermentation-derived sweeteners directly from biotech suppliers. This channel shift compresses technical service access but halves raw material lead times, concentrating most visibly in mid-sized confectionery operations lacking legacy supplier entrenchment.
South America Low-Calorie Sweeteners Market Segmentation
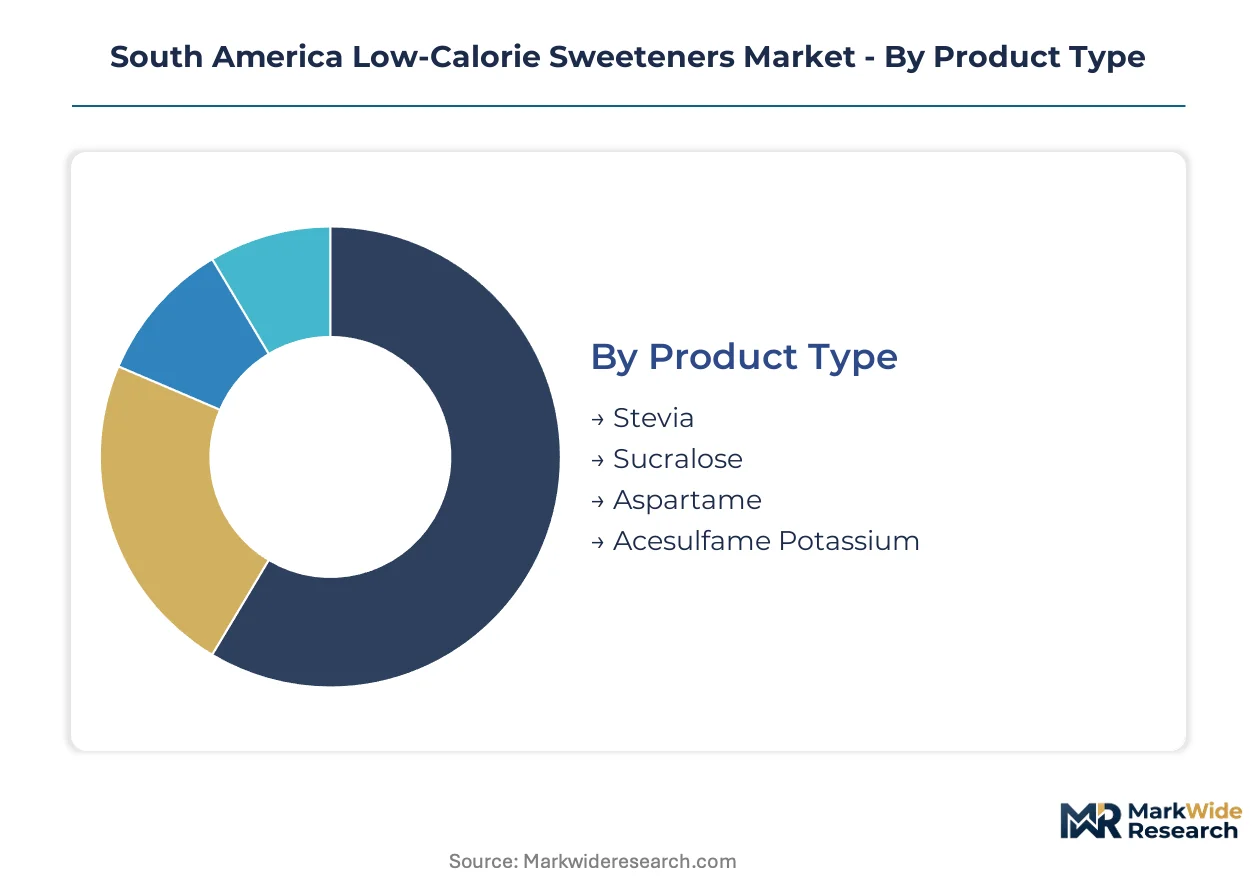
Sweetener selection across South American formulation labs hinges on thermal stability thresholds and clean-label positioning. Procurement patterns diverge sharply between multinational beverage giants in São Paulo and mid-sized Argentine bakery operations with limited reformulation budgets.
Product Type:
Reformulation cycles are accelerating as enzymatic modification upgrades stevia from niche natural positioning to mainstream sugar replacement across temperature-sensitive applications.
- Stevia:Reb-M and Reb-D glycoside variants now dominate premium beverage formulations through enzymatic conversion that eliminates bitter aftertaste. São Paulo's manufacturing corridor locks multi-year supply contracts for enzymatically modified extracts as ANVISA's sugar warning labels compress reformulation timelines.
- Sucralose:This chlorinated disaccharide maintains thermal stability above 120°C, securing its position in pasteurized soft drinks and baked goods where Maillard browning must be controlled. Argentine industrial bakeries rely on sucralose for cross-border Mercosur distribution where unified heat-process standards apply.
- Aspartame:Methyl ester instability above 30°C restricts deployment to ambient-stable beverages and tabletop packets in Brazilian retail channels.
- Acesulfame Potassium:Heat-stable synergist blends with sucralose in cost-engineered formulations for mass-market confectionery.
Volume placements concentrate in Sucralose; the faster expansion belongs to Stevia.
Application:
Application selection tracks the technical complexity of sugar replacement—beverages offer the lowest barrier, while bakery demands specialized food chemistry expertise scarce in regional labor markets.
- Beverages:Carbonated and still drinks absorb the majority of high-intensity sweetener volume as ANVISA's front-of-package warning system forces rapid sugar reduction. Brazilian giants in Minas Gerais deploy stevia-sucralose blends to maintain sweetness intensity without caloric load.
- Bakery:Reformulation challenges around moisture retention, browning control, and bulk replacement slow adoption despite health positioning demand. Argentine manufacturers face acute shortages of food chemists capable of optimizing Maillard reactions with alternative sweetener systems.
- Dairy:Fermentation-compatible sweeteners face pH stability constraints in yogurt and flavored milk applications across Brazil's southeastern states.
- Confectionery:Hard candy and chewing gum formulations exploit heat-stable compounds for sustained sweetness release in premium segments.
Revenue concentration sits with Beverages; the steepest expansion trajectory runs through Bakery as technical barriers yield.
End User:
Customer scale determines procurement channel access—multinationals negotiate direct supply agreements while smaller operators remain dependent on distributor markups.
- Food Manufacturers:Industrial-scale processors across Brazil's southeastern corridor drive bulk sweetener volume through integrated supply contracts with agricultural processors.
- Beverage Producers:Reformulation urgency from ANVISA compliance deadlines positions this segment for fastest technology adoption and premium ingredient sourcing.
- Health Food Brands:Clean-label positioning demands steer these buyers toward stevia and fermentation-derived alternatives with organic certification pathways.
- Restaurants:Tabletop packet demand and fountain beverage syrup procurement represent fragmented, price-sensitive volume with limited formulation influence.
Procurement scale clusters with Food Manufacturers; Health Food Brands are climbing the fastest as premium positioning expands.
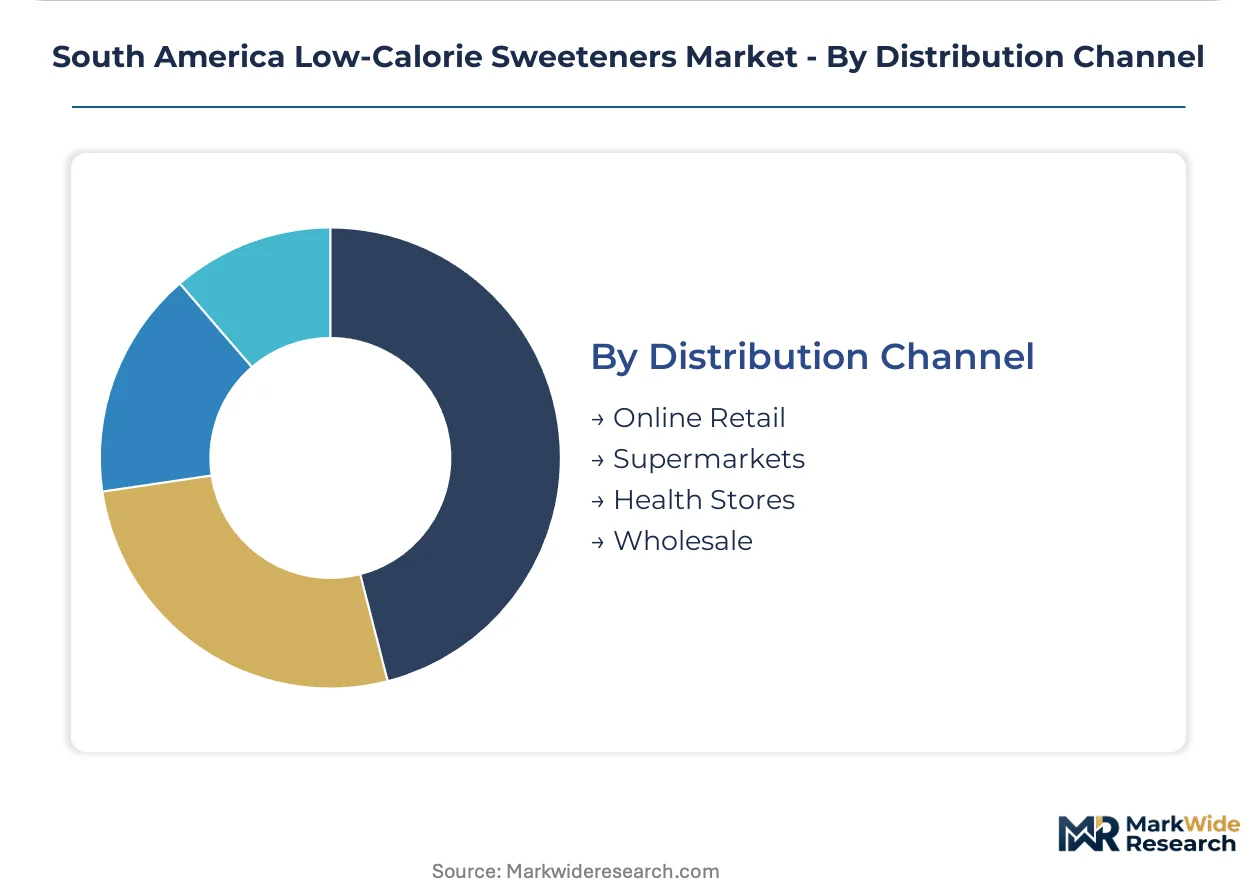
Distribution Channel:
Channel selection reflects buyer technical sophistication—direct biotech supplier relationships bypass traditional intermediaries for mid-sized operators with in-house formulation capability.
- Online Retail:B2B ingredient platforms enable Argentine and Colombian mid-tier processors to sample fermentation-derived sweeteners without legacy distributor relationships, compressing lead times by fifty percent.
- Supermarkets:Mass-market tabletop sweetener sales dominate consumer-facing volume through private-label and branded packets in Brazilian retail chains.
- Health Stores:Premium stevia extracts and organic-certified alternatives target clean-label consumers in São Paulo and Buenos Aires metropolitan areas.
- Wholesale:Traditional distributor networks retain lock on technical service and credit terms for smaller manufacturers lacking direct supplier relationships.
Transaction volume flows through Wholesale; Online Retail is gaining share fastest as digital procurement platforms fragment established channel structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs the majority of regional sweetener volume through its southeastern manufacturing corridor, while Argentina, Colombia, Chile, and Peru exhibit divergent adoption timelines tied to regulatory maturity and industrial infrastructure depth.
Brazil
ANVISA's front-of-package sugar warning labels and maximum usage level revisions are compressing reformulation cycles for beverage producers. São Paulo and Minas Gerais states anchor procurement concentration, with industrial-scale manufacturers locking multi-year stevia supply contracts to secure raw material consistency ahead of compliance deadlines.
Argentina
Cross-border Mercosur distribution requirements and inflation-driven cost pressures are reshaping procurement strategies for mid-sized food processors. The national food safety authority maintains parallel maximum usage standards that complicate unified product registrations, while Buenos Aires metropolitan manufacturers face acute shortages of specialized food chemists for bakery reformulation.
Colombia
Sugar reduction mandates lag regional peers, creating positioning windows for stevia-based formulations in Bogotá and Medellín beverage operations. The underdeveloped industrial infrastructure limits large-scale fermentation-derived sweetener production, though direct B2B procurement platforms are fragmenting traditional distributor relationships for mid-tier processors.
Chile
Stringent front-of-package labeling laws and consumer health awareness elevate clean-label positioning for premium confectionery segments. Santiago-based manufacturers source enzymatically modified stevia extracts to address bitterness thresholds in high-altitude distribution conditions that stress thermal stability requirements.
Peru
Lima's food manufacturing base remains dependent on imported sweetener intermediates due to limited domestic extraction capacity. Regulatory harmonization discussions with neighboring Andean Community members are creating pathway efficiencies for cross-border product registrations, though enforcement capacity gaps delay implementation timelines.
South America Low-Calorie Sweeteners Market Competitive Landscape
Supply contract consolidation dominates the current landscape as beverage manufacturers secure multi-year commitments ahead of ANVISA compliance deadlines. The vendor base organizes around three strategic archetypes: integrated agricultural processors with captive leaf sourcing, specialty ingredient blenders with technical service capabilities, and fermentation technology developers leveraging Brazilian ethanol infrastructure. Capacity expansion and enzymatic modification technology licensing represent the two dominant competitive moves reshaping positioning.
Within the integrated agricultural processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify upstream control strategies through Brazilian and Argentinian sourcing networks. Tate & Lyle PLC occupies a position anchoring formulation partnerships with regional beverage producers, while Ingredion Incorporated represents the specialty blending archetype addressing clean-label requirements. These four entities collectively illustrate the competitive tension between scale-driven procurement and technical service differentiation that defines current market structure.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| PureCircle |
| Roquette Frères |
| GLG Life Tech Corp |
| DuPont de Nemours, Inc. |
| Ajinomoto Co., Inc. |
| Others |
Value Network & Pricing Analysis
Enzymatic glycosylation technology adoption is collapsing the cost premium between Reb-A and Reb-M stevia variants while concentrating processing capacity among Brazilian and Paraguayan extraction facilities with capital-scale modification capabilities. This production-method transition simultaneously compresses per-kilogram sweetener economics and locks in supply-side power for integrated agricultural processors with captive leaf sourcing networks across the southern cone.
Pricing Analysis
Technical service bundling separates formulation partnership pricing from unbundled commodity spot transactions in the South American market. Three-tier pricing structure across premium enzymatically-modified stevia, standard Reb-A extracts, and economy-grade sucralose-acesulfame blends reflects certification grade and volume scale differentiation. Pricing pressure stems from ANVISA compliance deadlines compressing buyer procurement timelines. Mid-sized Argentine food processors exhibit highest price sensitivity due to inflation-driven working capital constraints, while Brazilian beverage giants in Minas Gerais prioritize supply security over unit cost optimization.
Supply Chain Analysis
Reverse logistics for spent stevia biomass and fermentation-derived sweetener byproduct streams remains underdeveloped across South American processing hubs. Raw material sourcing draws from Paraguayan leaf cultivation zones, southern Brazilian contract farming networks, and Argentine sugarcane ethanol infrastructure for fermentation feedstocks. Stevia leaf supply concentrates geographically, exposing processors to climate-driven harvest volatility in the Gran Chaco region. Distribution runs through São Paulo-based wholesale networks with technical service capabilities, though direct B2B platforms are fragmenting traditional channel structures for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's front-of-package sugar warning labels function as a cost-of-compliance barrier that entrenches incumbent processors with pre-registered formulation libraries and technical service capabilities. This regulatory moat advantages established players while elevating capital requirements for new market entry.
For Market Incumbents: Anticipate fermentation-derived sweetener substitution threats by securing multi-year supply contracts with Paraguayan leaf cooperatives and licensing enzymatic modification patents from biotech developers. Capacity addition in Minas Gerais processing corridors anchors regional supply security against Argentine cross-border competitors. Certification investment in organic and clean-label standards defends premium positioning as health food brands proliferate.
For New Entrants and Emerging Players: The premium-economy price gap in stevia extracts creates positioning room for mid-tier enzymatically-modified offerings targeting Colombian beverage manufacturers lagging regional sugar reduction mandates. Colombia's underdeveloped Andean supply infrastructure represents the most penetrable geography for first-mover stevia-based formulation partnerships. Direct B2B platform go-to-market angles bypass entrenched São Paulo distributor relationships and compress customer acquisition costs.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated agricultural processors seeking captive stevia extraction capabilities. Long-term viability in this market hinges on backward integration into leaf sourcing or forward integration into branded formulation services. The signal to watch is ANVISA's enforcement intensity on front-of-package compliance deadlines, which will determine which processing technologies receive prioritized capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Technology Licensing | Reb-M and Reb-D glycoside conversion eliminates bitter aftertaste barriers in premium beverage applications. |
| Backward Integration into Stevia Leaf Sourcing | Paraguayan and southern Brazilian contract farming networks secure raw material consistency against climate volatility. |
| Multi-Year Supply Contract Lock-In | Brazilian beverage manufacturers in Minas Gerais anchor volume commitments ahead of ANVISA compliance deadlines. |
| Fermentation-Derived Sweetener Scale-Up | Brazilian sugarcane ethanol infrastructure enables novel production economics for precision fermentation platforms. |
| Direct B2B Platform Channel Development | Mid-sized Argentine and Colombian processors bypass traditional distributor markups through digital procurement interfaces. |
Research Methodology
ANVISA regulatory filings, Mercosur harmonization documentation, and Brazilian customs trade records formed the secondary backbone for supply-side volume estimation. Primary interviews with stevia extraction plant managers, beverage formulation chemists at São Paulo and Minas Gerais manufacturing facilities, ANVISA regulatory affairs consultants, and Argentine food processor procurement leads validated secondary data patterns. Bottom-up triangulation across individual facility capacity disclosures and top-down reconciliation with regional consumption estimates anchored value projections.
Historical trendline analysis of stevia leaf harvest volumes, sucralose import trajectories, and enzymatic modification patent filings established baseline growth patterns across the projection horizon. Segmentation modeling incorporated sweetener type, application temperature sensitivity, end-user procurement scale, and distribution channel structure dimensions. CAGRs were derived from slope analysis of normalized adoption curves adjusted for regulatory inflection timing. Industry-specific forecast inputs included ANVISA enforcement intensity scenarios and Paraguayan climate yield variance bands.
Inputs from ANVISA pre-market approval databases and Paraguayan agricultural ministry harvest reports were available through the study window; gaps in real-time fermentation-derived sweetener production capacity introduce uncertainty bands around novel technology penetration assumptions. Practitioners should monitor ANVISA front-of-package warning label enforcement timelines and Mercosur mutual recognition implementation progress for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Xylitol Injection Market
Sweeteners
Saccharin Market
Sweeteners
Rice Syrup Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Sugar Syrups Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Agave Nectar Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Xylitol Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Sucralose Market