
 Stevia Mints Market | 2026-2036
Stevia Mints Market Size, Share, and Industry Trends Forecast 2026-2036
Stevia Mints Market Analytics
Health-conscious consumers is unwinding traditional sugar-dependent purchasing patterns among mainstream mint buyers. Mars leverages its confectionery R&D infrastructure to reformulate heritage brands with stevia extracts. The Hershey Company anchors North American shelf presence through health-positioned sub-brands. GLG Life Tech Corporation specializes in high-purity stevia leaf supply, controlling upstream botanical extraction for downstream mint manufacturers.
Stevia mints are compressed or molded confectionery products incorporating steviol glycosides as the primary sweetening agent, typically containing less than 0.5 grams of sugar per serving and manufactured through direct compression or candy panning processes. These products serve consumers seeking oral refreshment without glycemic impact or dental caries risk. Breath fresheners and lozenges command premium positioning due to functional health claims and pharmacy channel placement, while hard candies compete on price in mass retail. Health food shops and online retailers represent the fastest-growing distribution vectors as subscription models and direct-to-consumer wellness platforms expand.
FDA GRAS notifications for specific steviol glycosides and EFSA purity specifications shape formulation standards and cross-border product eligibility in the United States and European markets. India's FSSAI stevia approval framework and China's NMPA novel food ingredient pathways determine market access timelines for imported mint brands in Asia. Stakeholders must monitor evolving maximum permissible steviol glycoside concentrations and front-of-pack labeling mandates as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing stevia mint manufacturers to reformulate entire product portfolios, compressing development cycles and raising purity standards across the supply chain.
Growth Catalysts
- Sugar-reduction campaigns:Germany's federal nutrition strategy and retail-led reformulation pledges drive shelf-space reallocation toward stevia-sweetened confectionery in mainstream supermarkets.
- FDA GRAS pathway expansion:Broader steviol glycoside approvals enable U.S. manufacturers to launch novel flavor variants without novel food ingredient delays.
- Fitness and wellness program integration:Corporate workplace wellness initiatives in North America and Western Europe specify zero-glycemic refreshment options, creating institutional procurement pull.
Market Restraints
- Stevia leaf supply concentration:High-purity Reb A and Reb M extracts depend on cultivation clusters in China's Yunnan and Guizhou provinces, exposing formulations to climate and trade policy volatility.
- Bitter aftertaste technical ceiling:Reb A formulations above 250 ppm retain licorice-like off-notes that limit consumer acceptance in premium positioning.
- EFSA purity specification friction:Batch-to-batch steviol glycoside concentration variance creates border rejection risk for imported mint brands entering EU distribution.
Strategic Opportunities
- Pharmacy channel underpenetration:Lozenge formats with dental health claims remain underrepresented in German and French apotheek chains relative to sugar-free gum.
- Direct-to-consumer subscription platforms:Wellness-focused e-commerce aggregators enable mint brands to bypass slotting fee barriers and capture recurring revenue.
- Bioconversion stevia expansion:Fermentation-derived Reb M from microbial platforms bypasses agricultural supply constraints and enables cost parity with synthetic sweeteners.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging botanical extraction and confectionery masking systems concentrates among a handful of specialized consultancies.
- Dual certification burden:Separate organic and non-GMO verification timelines for stevia leaf and finished mint products extend new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stevia Mints Market |
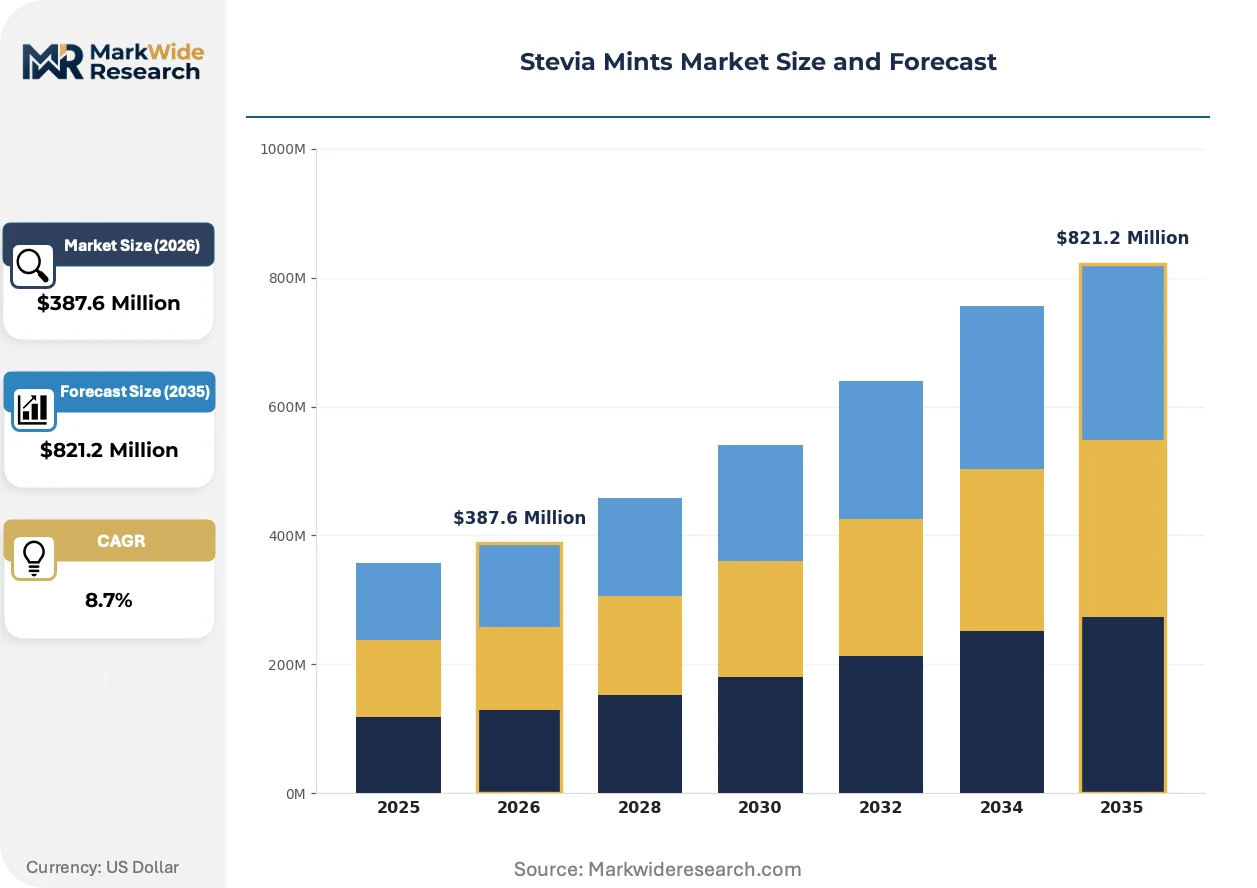
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candies, Chewing Gum, Breath Fresheners, Lozenges Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Shops End User: Health-Conscious Consumers, Diabetics, Athletes, Families Flavor Profile: Mint, Spearmint, Peppermint, Mixed Berry |
| Companies Covered | Mars, Nestlé, Johnson & Johnson, The Hershey Company, Cargill Incorporated, Tate & Lyle PLC, Ingredion Incorporated, GLG Life Tech Corporation, Wrigley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stevia Mints Market Evolving Landscape
Reformulation science and regulatory clarity are converging to reshape how stevia mints achieve sensory parity with sugar-based alternatives. Three developments dominate competitive positioning.
Enzymatically modified steviol glycosides are decomposing the traditional trade-off between sweetness intensity and clean taste profiles. Premium mint brands in Japan and South Korea adopt these next-generation extracts to eliminate bitter receptor activation. The technology is decomposing cost barriers that previously confined high-purity stevia to niche positioning.
EFSA's 2023 updated specifications for steviol glycoside purity and maximum use levels in confectionery categories are tightening batch documentation requirements. Manufacturers must now demonstrate sub-ppm impurity thresholds for every production lot. Hard candy segments face the steepest compliance recalibration as existing formulations approach concentration ceilings.
Subscription wellness platforms are capturing mint consumers who previously purchased through impulse retail. Direct-to-consumer brands in the United States bundle breath fresheners with oral care regimens, displacing single-unit convenience store transactions. This channel rotation is most pronounced among urban millennials in coastal metropolitan markets.
Stevia Mints Market Segmentation
Channel economics dictate which stevia mint formulations capture shelf space and margin. Manufacturers align product architecture with distribution physics: pharmacy chains demand clinical positioning, while mass retail rewards price-engineered formats.
Product Type:
Supermarkets and health food shops favor formats with visible clean-label credentials and extended shelf stability. Pharmacy channels extract premium placement for products with functional health claims and documented glycemic properties.
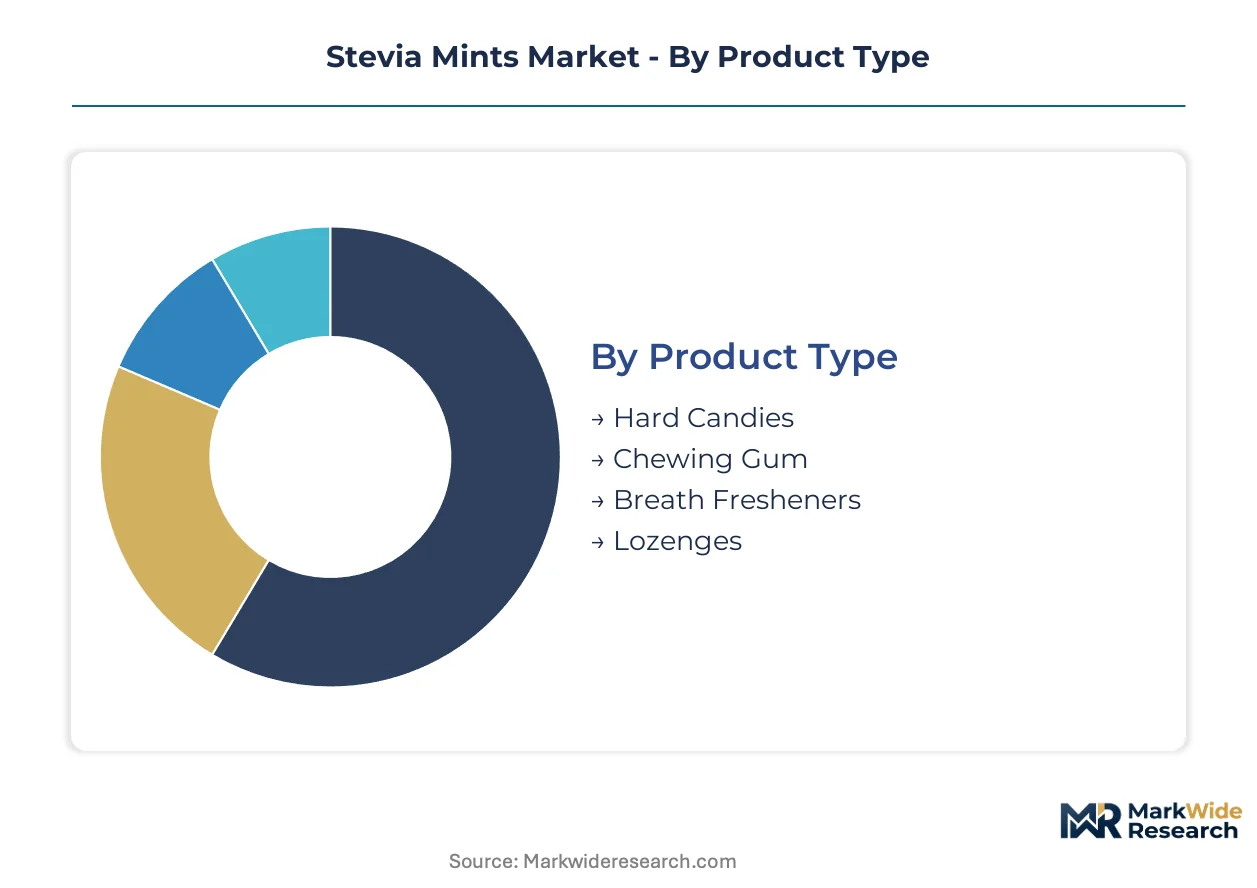
- Breath Fresheners:Compressed tablet formats containing high-purity Reb A or Reb M extracts deliver sub-0.5g sugar per serving. Demand clusters in German and French pharmacy chains where dental health claims justify 40-60% price premiums over conventional sugar-free alternatives. EFSA purity documentation requirements create compliance barriers that filter out smaller competitors.
- Lozenges:Slow-dissolve matrices with steviol glycoside concentrations up to 300 ppm serve throat comfort and oral hygiene positioning. German sugar-reduction campaigns have reallocated apotheek shelf space toward these formats, displacing legacy medicated cough drops. Batch-to-batch glycoside variance remains the primary technical constraint for cross-border EU distribution.
- Hard Candies:Pan-processed confectionery competing on unit economics in mass retail. China's Yunnan province stevia leaf supply volatility compresses margin predictability for price-sensitive positioning.
- Chewing Gum:Elastomer-based delivery systems requiring specialized masking systems to suppress stevia's licorice-like off-notes. Base polymer costs and flavor chemist scarcity limit new entrant participation.
Breath fresheners dominate installed base. Lozenges are where expansion concentrates.
Distribution Channel:
Cost-to-serve economics stratify across channel tiers, with slotting fees and certification requirements determining which product formats achieve viable economics.
- Health Food Shops:Curated assortments emphasizing organic certification and non-GMO verification. These outlets command 25-35% gross margins and reward brands with subscription-enabled replenishment models. Urban millennial consumers in coastal US metropolitan markets drive volume through wellness-platform bundling with oral care regimens.
- Online Retailers:Direct-to-consumer platforms bypass traditional slotting fee structures and enable recurring revenue capture through subscription mechanics. The channel rewards brands with vertically integrated supply chains that can maintain price parity while absorbing last-mile logistics costs.
- Supermarkets:High-velocity environments where stevia mints compete for impulse placement against established sugar-free gum brands. Germany's retail-led reformulation pledges have expanded dedicated shelf sections for plant-based confectionery.
- Convenience Stores:Single-unit transaction economics favor compact, high-margin formats. Limited cooler space and rapid inventory turns disadvantage products with shorter shelf-life profiles.
Supermarkets anchor volume throughput. Online retailers are climbing the fastest.
End User:
Application intensity varies by user physiology and consumption context, with institutional procurement creating distinct demand profiles from individual purchasing.
- Health-Conscious Consumers:Fitness and wellness program participants seeking zero-glycemic refreshment options. Corporate workplace wellness initiatives in North America specify these products for campus vending and meeting catering.
- Diabetics:Medically motivated users requiring documented glycemic index certification. Pharmacy channel placement and HCP recommendation influence brand selection.
- Athletes:Performance-oriented consumers integrating mint products into training protocols. Sports nutrition retail and team procurement channels drive bulk purchasing.
- Families:Household-level purchasing balancing adult preference for sugar reduction with children's taste acceptance. Reb A formulations above 250 ppm face acceptance ceilings in this segment due to residual bitterness.
Health-conscious consumers represent the broadest installed base. Diabetics concentrate margin expansion.
Flavor Profile:
Botanical oil sourcing and stevia glycoside masking chemistry determine which flavor directions achieve sensory parity with sugar-based benchmarks.
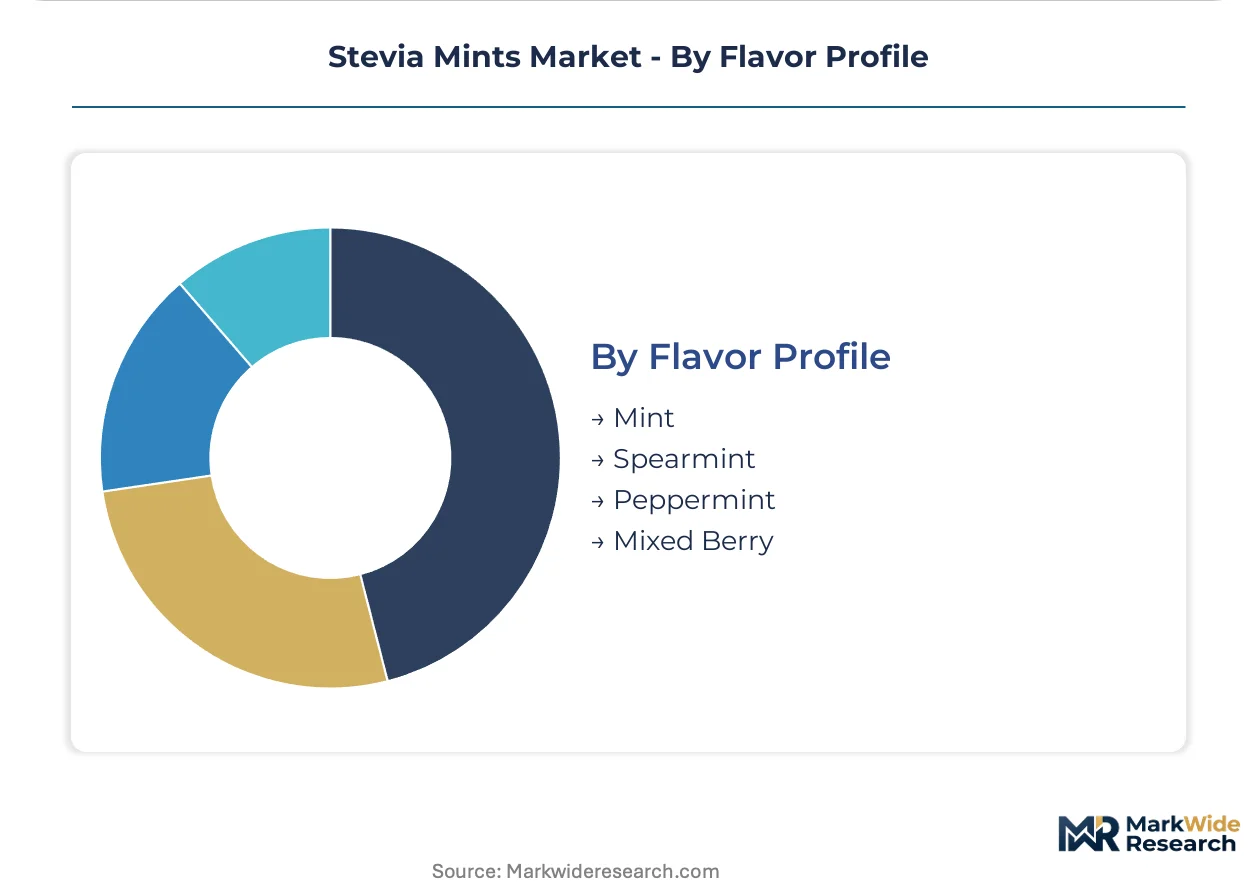
- Peppermint:High-menthol formulations that naturally suppress stevia's bitter receptor activation. Premium positioning in Japanese and South Korean markets leverages enzymatically modified steviol glycosides for clean taste profiles.
- Spearmint:Lower menthol intensity requires more sophisticated masking systems. The format competes on price in mass retail channels.
- Mint:Generic positioning with flexible formulation standards. Commodity stevia extracts suffice for basic sensory targets.
- Mixed Berry:Fruit-acid interactions with steviol glycosides create formulation complexity. EFSA's updated purity specifications impose sub-ppm impurity thresholds that complicate natural flavor integration.
Peppermint holds the deepest installed base. Mixed berry is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban professionals and corporate wellness managers concentrate demand in Germany, the United States, and Japan, with pharmacy channel placement and sugar-reduction policy frameworks determining regional penetration depth.
Germany
Federal sugar-reduction campaigns and apotheek chain procurement standards drive premium positioning for stevia-sweetened lozenges and breath fresheners. EFSA purity specifications enforce sub-ppm impurity documentation for every production batch entering distribution. Bavaria and North Rhine-Westphalia host the densest pharmacy network penetration, with Munich-based retailers allocating expanded shelf sections to plant-based confectionery.
United States
FDA GRAS pathway expansion for novel steviol glycosides accelerates flavor variant launches without novel food ingredient delays. Corporate workplace wellness initiatives in coastal metropolitan markets specify zero-glycemic refreshment for campus vending contracts. California and New York Metro wellness-platform subscriptions bundle stevia mints with oral care regimens, displacing single-unit convenience store transactions.
China
NMPA novel food ingredient approval timelines determine market access for imported mint brands seeking entry through cross-border e-commerce channels. Yunnan and Guizhou provinces concentrate high-purity Reb A and Reb M cultivation, exposing formulations to climate volatility and trade policy shifts. Shanghai and Beijing urban consumers drive demand through direct-to-consumer wellness aggregators.
Japan
Enzymatically modified steviol glycoside adoption eliminates bitter receptor activation in premium peppermint formulations. METI standards for functional food claims support pharmacy placement of dental health-positioned products. Tokyo and Osaka metropolitan markets anchor demand for next-generation extract technologies that achieve sensory parity with sugar benchmarks.
India
FSSAI stevia approval frameworks for confectionery applications create compliance pathways for domestic and imported brands. Health-conscious consumers in fitness and wellness programs drive adoption among urban professional segments. Maharashtra and Karnataka concentrate modern retail expansion, with Mumbai and Bengaluru health food shops curating organic-certified assortments.
Stevia Mints Market Competitive Landscape
Player mix skews toward multinational confectionery conglomerates with heritage brand portfolios and specialized stevia extract suppliers controlling upstream botanical supply. The vendor base stratifies across three tiers: integrated confectionery manufacturers with in-house reformulation capabilities, pure-play stevia extract specialists supplying downstream mint producers, and direct-to-consumer wellness brands bypassing traditional retail slotting structures. Dominant competitive moves include portfolio diversification into sugar-reduced sub-brands and strategic partnerships bridging extraction expertise with finished goods distribution.
Within the integrated confectionery tier, Mars and The Hershey Company occupy positions as North American market anchors with established R&D infrastructure for heritage brand reformulation. GLG Life Tech Corporation exemplifies the upstream specialization archetype, with corporate structure indicating concentrated focus on high-purity stevia leaf supply. Among diversified ingredient suppliers, Cargill Incorporated and Tate & Lyle PLC represent the scale-driven segment with broad sweetener portfolios extending into confectionery applications.
| Leading Market Players |
|---|
| Mars |
| Nestlé |
| Johnson & Johnson |
| The Hershey Company |
| Cargill Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| GLG Life Tech Corporation |
| Wrigley |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for high-purity Reb A and Reb M extracts concentrate pricing power among Yunnan and Guizhou cultivators, while downstream mint manufacturers absorb volatility through long-term offtake contracts or spot-market exposure. This lead-time band tightens when EFSA purity documentation requirements trigger batch rejection cascades, forcing reformulation cost pass-through or margin compression.
Pricing Analysis
Next-generation enzymatically modified steviol glycosides command substantial premiums over conventional Reb A extracts, while fermentation-derived Reb M from microbial platforms is compressing cost differentials toward synthetic sweetener parity. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-channel lozenges with dental health claims from mass-market hard candies and private-label breath fresheners. Pricing pressure stems from China's stevia leaf supply volatility and EFSA batch-to-batch variance documentation. Health-conscious consumers in corporate wellness programs show lowest price sensitivity; families purchasing for children's taste acceptance face highest substitution elasticity.
Supply Chain Analysis
Strait of Malacca transit routes for Indonesian and Malaysian botanical oil inputs intersect with Yunnan province stevia leaf concentration to create dual-hemisphere chokepoint exposure. High-purity Reb A and Reb M cultivation clusters in China's Yunnan and Guizhou provinces, Paraguayan stevia expansion zones, and Indian FSSAI-compliant processing facilities anchor upstream supply. Raw material dependencies include stevia leaf biomass, peppermint and spearmint essential oils, and panning-grade confectionery bases. Single-source vulnerability in Chinese extraction capacity generates tariff and trade policy risk. Distribution runs through pharmacy chain procurement systems, wellness-platform direct-to-consumer fulfillment, and mass retail slotting-fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in EFSA purity documentation and FDA GRAS notification pathways creates switching costs that lock in incumbent formulation expertise.
For Market Incumbents: Fortify upstream supply security through captive cultivation partnerships in Paraguay or backward integration into extraction capacity, while deepening pharmacy channel control through dental health claim certifications that emerging players cannot replicate. Bioconversion stevia specialists and direct-to-consumer wellness platforms represent the most credible substitute threats. Certification investment in dual organic and non-GMO verification timelines serves as the critical lever for shelf-space retention. For New Entrants and Emerging Players: Lead with pharmacy channel underpenetration in German and French apotheek chains, where lozenge formats with documented glycemic properties remain underrepresented relative to sugar-free gum. Mixed berry flavor profiles with enzymatically modified steviol glycosides offer the most penetrable sensory positioning. A subscription-enabled replenishment model bundled with oral care regimens provides the clearest go-to-market angle for bypassing slotting fee barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EFSA and FDA purity specifications are concentrating compliance burden among extract specialists with documented batch-control systems. Acquisition targets should display vertically integrated supply chains bridging Yunnan cultivation with finished goods distribution. The signal to watch is NMPA approval timeline acceleration for fermentation-derived Reb M, which would restructure cost curves and incumbent positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Bioconversion Stevia Scale-Up | Fermentation-derived Reb M from microbial platforms bypasses Yunnan climate volatility and enables cost parity. |
| Pharmacy Channel Expansion | German apotheek chain placement with dental health claims captures 40-60% price premiums over conventional alternatives. |
| Direct-to-Consumer Launch | Wellness-platform subscriptions in California and New York Metro displace convenience store transactions through bundling. |
| EFSA Compliance Investment | Sub-ppm impurity documentation systems filter out smaller competitors and secure cross-border EU distribution access. |
| Flavor Chemist Acquisition | Specialized formulation expertise bridging botanical extraction and confectionery masking systems concentrates among scarce consultancies. |
Research Methodology
Desk research of FDA GRAS notification filings, EFSA purity specification updates, and FSSAI stevia approval frameworks preceded structured interviews with confectionery R&D directors, pharmacy chain procurement managers, stevia extract supply planners, and wellness-platform category buyers. Secondary validation drew from customs records for stevia leaf and extract trade flows, Nielsen retail audit data for mint confectionery velocity, and SEC filings from publicly traded sweetener suppliers. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across product type, distribution channel, flavor profile, and regional regulatory cluster informed the analytical framework. CAGRs derived from segment-level growth rate reconciliation, with enzymatically modified steviol glycoside adoption curves and bioconversion stevia cost-down trajectories serving as key technology-input variables. Modeled outputs reflect volume-price interactions across the projection horizon without year-specific anchoring.
Forecasts assume regulatory continuity in FDA GRAS pathways and EFSA purity specifications; material policy shifts in maximum permissible steviol glycoside concentrations or front-of-pack labeling mandates would require re-modeling. Practitioners should keep alternative scenarios live as NMPA novel food ingredient timelines and climate volatility in Yunnan cultivation zones evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
China Saccharin Market
Sweeteners
India Food Sweetener Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Galactose Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Invert Sugar Market
Sweeteners
Icing Sugar Market
Sweeteners
Corn Sweeteners Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Trehalose Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Stevia Market
Sweeteners
Liquid Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Maltol and Ethyl Maltol Market