
 Australia Food Sweetener Market | 2026-2036
Australia Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Sweetener Market Outlook
FSANZ sugar content disclosure requirements is restructuring procurement priorities across Australian food manufacturing. Cargill Australia Limited leverages its broad ingredient portfolio to supply reformulated sweetener blends to national brands. Naturally Sweet Products anchors its position through specialization in stevia and monk fruit extracts for health-conscious segments. Tate & Lyle PLC competes on technology leadership in clean-label solutions tailored to local bakery and dairy applications.
Food sweeteners encompass caloric and non-caloric substances that impart sweetness to food and beverage matrices, typically measured by sucrose equivalence and stability under thermal processing conditions. Sucrose retains dominance in confectionery applications where crystallization control and bulk functionality prove essential, while stevia extracts represent the fastest-expanding category as beverage manufacturers pursue clean-label positioning. Liquid formulations lead in industrial scale-up for beverages, whereas granular and powder forms command premium placement in retail channels targeting household baking segments.
FSANZ governs sweetener approval and labelling standards, while the Australia New Zealand Food Standards Code dictates maximum permitted levels and mandatory added sugar declarations. TGA oversight intersects where sweeteners carry therapeutic or nutritional claims, tightening substantiation requirements. Stakeholders must monitor pending revisions to the Health Star Rating system and anticipate how front-of-pack sugar warnings will redirect procurement toward low-glycaemic and natural alternatives.
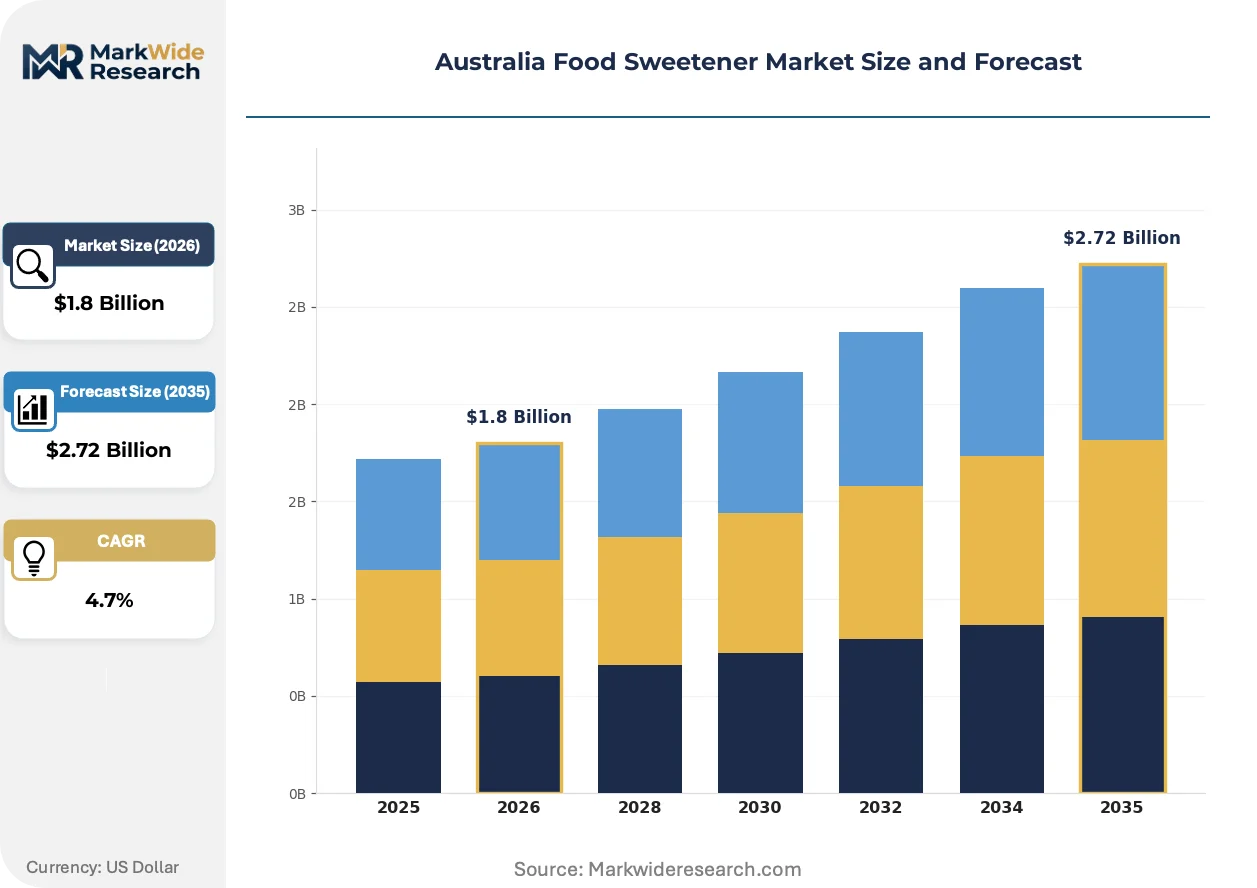
Market Dynamics
FSANZ sugar disclosure mandates are compressing formulation timelines across Australian food manufacturing, forcing procurement teams to validate natural sweetener alternatives within compressed product development cycles or risk shelf-space penalties under the Health Star Rating system.
Growth Catalysts
- Health Star Rating recalibration:FSANZ revisions to front-of-pack scoring algorithms penalize added sugar density, compelling beverage brands to reformulate with stevia and monk fruit extracts to maintain retail placement.
- Queensland beverage manufacturing expansion:New production facilities in Brisbane and Gold Coast are scaling clean-label output, generating concentrated demand for non-caloric sweetener supply contracts.
- Enzymatic bioconversion:Advanced fermentation platforms for rare sugar production are reducing cost premiums on allulose and tagatose, accelerating adoption in premium dairy applications.
Market Restraints
- Stevia leaf supply concentration:Raw material sourcing clusters in China's Yunnan and Guangxi provinces, exposing Australian formulators to currency volatility and harvest variability.
- TGA claim substantiation costs:Therapeutic Goods Administration evidentiary requirements for glycaemic index or prebiotic claims impose six-figure validation burdens on mid-tier manufacturers.
- Sucrose bulk functionality:Crystallization control and mouthfeel properties in confectionery remain unmatched by high-intensity alternatives, locking traditional sugar into hard candy and fondant segments.
Strategic Opportunities
- South Australia wine sector adjacency:Natural sweetener suppliers can leverage existing grape-derived extract infrastructure in Barossa Valley to develop wine-sugar hybrid formulations for reduced-alcohol beverages.
- Clean-label confectionery white space:Premium chocolate segments in Melbourne and Sydney show underpenetration for monk fruit-sweetened artisanal products targeting diabetic and keto consumer cohorts.
- Direct-to-manufacturer platform distribution:B2B ingredient marketplaces are bypassing traditional distributor markups, enabling smaller New South Wales food startups to access bulk stevia volumes previously reserved for national brands.
Industry Challenges
- Formulation chemist scarcity:Technical expertise in high-intensity sweetener synergy modeling—balancing temporal sweetness profiles with bulking agents—commands premium salaries that strain mid-cap R&D budgets.
- Legacy equipment retrofit costs:Powder handling systems designed for sucrose crystalline flow require capital-intensive modification to prevent caking and moisture absorption in hygroscopic natural extracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Sweetener Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Glucose Syrup, Stevia, Aspartame Form: Liquid, Granular, Powder, Tablet Application: Beverages, Bakery, Dairy Products, Confectionery Customer Type: Retailers, Food Manufacturers, Food Service, Households |
| Companies Covered | Archer Daniels Midland Company, Ajinomoto Co., Inc., Cargill Australia Limited, Naturally Sweet Products, Sweetlife Australia Pty Ltd., Ingredion ANZ Pty Ltd., GLG Life Tech Corp, Nirvana Health Products, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Sweetener Market Strategic Shifts
Biotechnology platforms and regulatory disclosure requirements are converging to compress the innovation cycle for Australian sweetener suppliers, while procurement behaviors shift toward direct supplier relationships that bypass traditional ingredient distribution channels.
Precision fermentation for rare sugars is integrating into Australian contract manufacturing infrastructure. Local biotech facilities in Melbourne's northern suburbs are scaling allulose and tagatose production using engineered yeast strains. Beverage formulators in Sydney are adopting these outputs at pilot scale, enabling clean-label claims that satisfy FSANZ added-sugar thresholds without sacrificing sweetness intensity.
FSANZ front-of-pack labelling amendments are mandating added sugar quantification in grams per serve. Food manufacturers face reformulation deadlines that compress supplier qualification timelines to under twelve months. Dairy processors in Victoria are responding fastest, restructuring procurement specifications to prioritize low-glycaemic sweetener blends that preserve mouthfeel in yogurt and flavored milk applications.
Ingredient sourcing patterns are fragmenting as mid-tier manufacturers bypass traditional distributors. Direct contracts with stevia and monk fruit extractors in Queensland and imported supply partners are replacing volume-based distributor relationships. This behavioral shift is most visible among Sydney-based functional food startups, which are negotiating spot pricing for small-batch natural sweetener volumes that legacy procurement systems failed to serve economically.
Australia Food Sweetener Market Segmentation
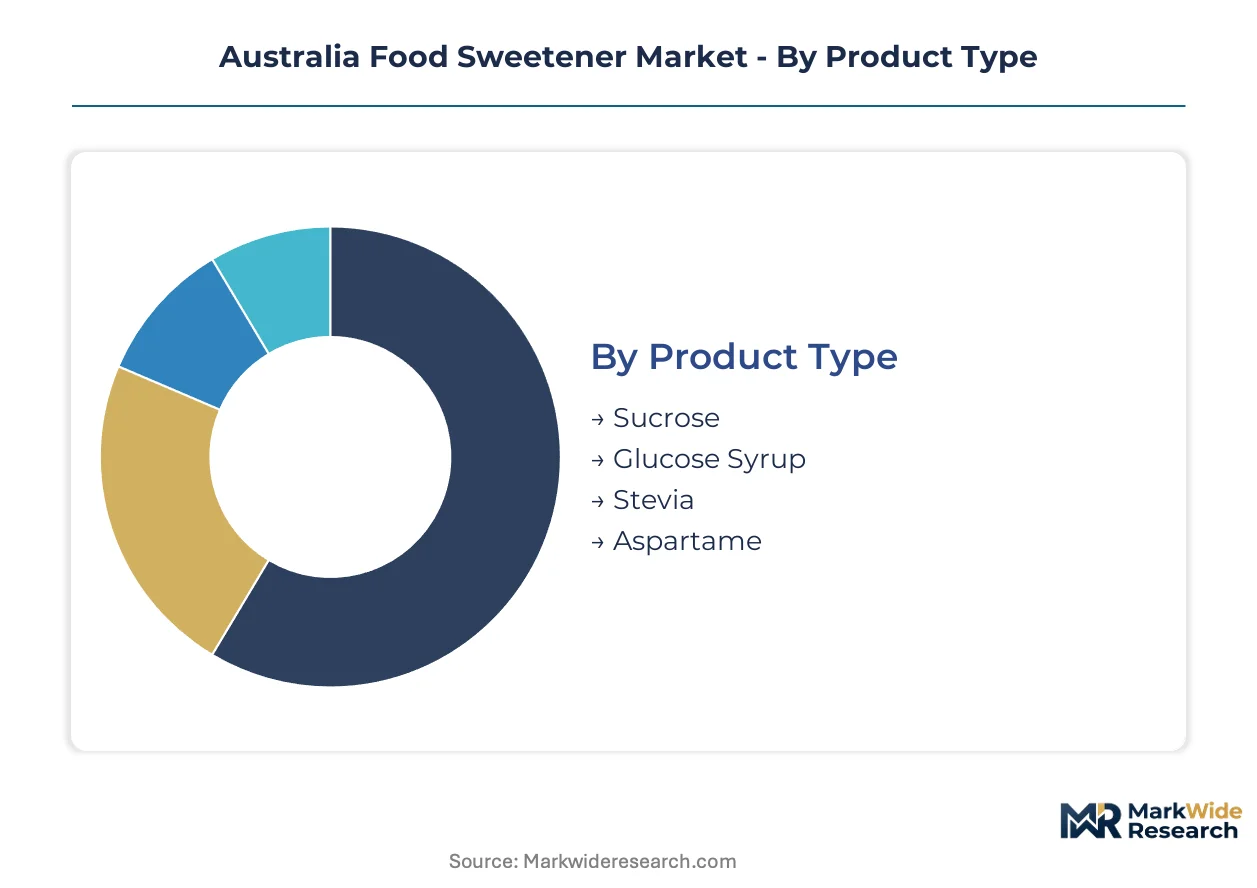
Reformulation pressures from FSANZ disclosure mandates are fragmenting procurement specifications across Australian food manufacturing. Sweetener selection now hinges on functional equivalence thresholds, clean-label positioning, and equipment compatibility rather than commodity pricing alone.
Product Type:
Replacement cycles in beverage and dairy applications are accelerating as manufacturers retire legacy sucrose formulations ahead of Health Star Rating recalibration deadlines.
- Sucrose:Crystalline sucrose retains dominance in confectionery and bakery matrices where bulk functionality, crystallization control, and Maillard browning prove irreplaceable. Victorian chocolate manufacturers and Sydney fondant producers anchor demand despite FSANZ disclosure penalties.
- Stevia:Purified steviol glycosides from Yunnan-sourced leaf extracts command premium placement in reduced-sugar beverages. Queensland bottling facilities in Brisbane and Gold Coast are scaling clean-label output, generating concentrated procurement contracts for Reb-A and Reb-M concentrated grades.
- Glucose Syrup:Enzymatically hydrolyzed starch syrups provide viscosity and humectancy in industrial bakery applications. New South Wales bread and biscuit manufacturers specify high-maltose variants for moisture retention in extended shelf-life products.
- Aspartame:The methyl ester dipeptide sweetener persists in tabletop and carbonated beverage applications where cost minimization outweighs clean-label positioning. Procurement concentrates among national soft drink brands with established formulation pipelines.
Sucrose sits at the top of the volume ranking, with stevia climbing the fastest.
Form:
Manufacturing scale and distribution channel determine form selection, with industrial users prioritizing handling efficiency and retail channels demanding consumer convenience.
- Liquid:Pumpable concentrates dominate beverage manufacturing in Queensland and Victoria, enabling precise dosing in high-speed bottling lines. Enzymatic bioconversion facilities in Melbourne's northern suburbs are scaling allulose and tagatose liquid outputs for direct tanker delivery.
- Powder:Spray-dried and agglomerated formats serve industrial bakery and dry mix applications where dispersion uniformity proves critical. Sydney-based functional food startups negotiate spot pricing for small-batch natural sweetener powders previously reserved for national brands.
- Granular:Crystalline formats with controlled particle size distribution target retail baking segments and tabletop use. Victorian and New South Wales supermarket chains specify free-flowing granules for private-label placement.
- Tablet:Compressed single-serve units command premium placement in café and food service channels across Melbourne and Sydney central business districts.
Liquid formulations lead industrial procurement, though powder is gaining share fastest among mid-tier manufacturers bypassing traditional distributors.
Application:
End-use specifications diverge sharply on thermal stability, pH tolerance, and mouthfeel requirements, forcing suppliers to maintain application-specific technical service capabilities.
- Beverages:pH-stable high-intensity sweeteners dominate reformulation efforts as FSANZ added-sugar disclosure mandates compress product development timelines. Stevia and monk fruit extracts are displacing sucrose in flavored waters and reduced-sugar carbonated lines.
- Dairy Products:Yogurt and flavored milk processors in Victoria prioritize low-glycaemic blends that preserve mouthfeel under refrigerated storage. Procurement specifications now require glycaemic index substantiation for front-of-pack claims.
- Bakery:Maillard-active sweeteners remain essential for crust color and flavor development in bread and biscuit applications. New South Wales industrial bakeries specify glucose syrups and sucrose blends for controlled browning kinetics.
- Confectionery:Crystallization control requirements lock traditional sugars into hard candy and fondant segments. Melbourne and Sydney artisanal chocolate makers show underpenetration for monk fruit-sweetened premium products targeting diabetic and keto cohorts.
Beverages command the largest procurement volumes, with dairy applications expanding most quickly under Health Star Rating pressure.
Customer Type:
Procurement sophistication varies dramatically across customer tiers, from commodity spot purchasing among households to multi-year supply agreements with technical service attachments for national manufacturers.
- Food Manufacturers:National beverage and dairy brands in Queensland and Victoria negotiate direct contracts with stevia and monk fruit extractors, bypassing traditional distributor markups. Technical collaboration on formulation stability and shelf-life testing accompanies volume commitments.
- Retailers:Supermarket chains in New South Wales and Victoria specify private-label sweetener blends with clean-label positioning. FSANZ disclosure mandates are redirecting procurement toward natural alternatives for house-brand beverages and baking mixes.
- Food Service:Café and restaurant operators in Sydney and Melbourne central business districts demand tabletop and batch-preparation formats with minimal training requirements for kitchen staff.
- Households:Consumer baking segments in suburban and regional Australia drive granular and powder retail sales, with stevia-based baking blends gaining placement in health-food channels.
Food manufacturers represent the dominant procurement tier, with retailers restructuring specifications fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's food sweetener industry traces its modern foundations to post-war sugar refining expansion in Queensland and the subsequent diversification into high-intensity alternatives during the 1990s health-conscious consumer shift. Today the market distributes procurement gravity across five states with distinct industrial specializations and regulatory exposures.
New South Wales
Sydney anchors national beverage reformulation demand as FSANZ sugar disclosure mandates compress product development timelines for flavored water and reduced-sugar carbonated lines. The state's food manufacturing corridor generates concentrated procurement contracts for stevia and monk fruit extracts. Parramatta-based functional food startups negotiate direct supplier relationships bypassing traditional distributor markups.
Victoria
Melbourne's dairy processing cluster drives specification for low-glycaemic sweetener blends preserving mouthfeel in yogurt and flavored milk applications. TGA substantiation requirements for glycaemic index claims tighten procurement documentation standards. Northern suburbs biotech facilities scale precision fermentation outputs for rare sugars including allulose and tagatose.
Queensland
Brisbane and Gold Coast beverage manufacturing expansion generates concentrated demand for non-caloric sweetener supply contracts. The state's historical sugar refining infrastructure provides enzymatic bioconversion capabilities transitioning toward clean-label outputs. Procurement teams here prioritize pH-stable high-intensity formulations for high-speed bottling lines.
South Australia
Barossa Valley grape-derived extract infrastructure offers adjacency opportunities for wine-sugar hybrid formulations in reduced-alcohol beverages. Adelaide food manufacturers face compressed supplier qualification timelines under Health Star Rating pressure. The state's smaller manufacturing base relies on B2B ingredient marketplaces for bulk natural sweetener access.
Western Australia
Perth's isolated procurement geography drives premium freight absorption for stevia leaf imports from Chinese Yunnan and Guangxi provinces. Local food service operators demand tabletop formats with minimal training requirements. The state's mining-affluent consumer base shows above-average penetration for premium monk fruit-sweetened retail baking products.
Australia Food Sweetener Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and technical service attachment. The Australian sweetener market structures around three tiers: multinational ingredient conglomerates with broad portfolios, regional specialists in natural extracts, and imported commodity traders. Archetypes include clean-label technology leaders, stevia supply chain integrators, and distributor-dependent volume suppliers. Dominant competitive moves center on direct-to-manufacturer platform distribution bypassing traditional markups, and enzymatic bioconversion capacity expansion for rare sugar production.
Among multinational conglomerates, Cargill Australia Limited and Tate & Lyle PLC exemplify the technology-forward tier with formulation collaboration capabilities. Naturally Sweet Products occupies a specialist position within the natural extracts segment. These three entities represent divergent strategic postures: broad portfolio leverage, clean-label technical leadership, and stevia-monk fruit specialization respectively.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ajinomoto Co., Inc. |
| Cargill Australia Limited |
| Naturally Sweet Products |
| Sweetlife Australia Pty Ltd. |
| Ingredion ANZ Pty Ltd. |
| GLG Life Tech Corp |
| Nirvana Health Products |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Captive sourcing from Chinese stevia leaf processors anchors both supply security and pricing power for Australian formulators, with Yunnan and Guangxi province concentration forcing volume commitments that lock in cost structures across multi-year contracts.
Pricing Analysis
Contract-based long-term offtake dominates procurement between national beverage brands and stevia extractors, with price differentiation hinging on Reb-A versus Reb-M glycoside purity grades and FSANZ-compliant documentation bundles. Cost compression in standard-grade stevia intensifies as Queensland bottling facilities scale clean-label output and negotiate collective purchasing arrangements. Mid-tier manufacturers show highest price sensitivity, while premium artisanal chocolate makers absorb premiums for monk fruit extracts with minimal glycaemic index substantiation.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne operate hub-and-spoke patterns feeding Queensland beverage corridors and Victorian dairy clusters. Raw material sourcing draws from China's Yunnan and Guangxi provinces for stevia leaf, Indian enzymatic processing facilities for glucose syrup precursors, and local Victorian biotech infrastructure for precision-fermented rare sugars. Single-source vulnerability concentrates in Chinese leaf supply, with harvest variability and currency exposure threatening formulation continuity. Distribution runs through B2B ingredient marketplaces that bypass traditional distributor markups for mid-tier New South Wales food startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSANZ sugar disclosure mandates function as a regulatory compounder, with Health Star Rating recalibration deadlines forcing reformulation procurement cycles that expand addressable market for natural sweetener suppliers.
For Market Incumbents: Anticipate enzymatic bioconversion technology displacement by securing exclusive supply partnerships with Melbourne-based precision fermentation facilities before capacity constraints emerge. Consolidate position through backward integration into Queensland stevia extraction infrastructure, capturing margin currently absorbed by Chinese leaf processors. Lock national beverage brands into technical service attachments that embed formulation chemists directly within client R&D teams. For New Entrants and Emerging Players: Direct-to-manufacturer platform distribution routes offer lowest-friction entry, bypassing distributor markups that legacy procurement systems impose on small-batch natural sweetener volumes. Target South Australia's Barossa Valley wine-sugar hybrid formulation white space, where existing grape-derived extract infrastructure enables reduced-alcohol beverage applications with minimal capital investment. Lead with glycaemic index substantiation services bundled with monk fruit supply, addressing TGA documentation burdens that strain mid-tier manufacturer budgets. For Investors and Strategic Acquirers: Roll-up economics work for stevia supply chain integrators because fragmented Queensland extraction capacity and distributor-dependent Victorian distributors create multiple bite-sized acquisition targets with immediate procurement consolidation benefits. Long-term viability favors platforms combining leaf sourcing with in-house Reb-M purification, as beverage manufacturers prioritize clean-label positioning over cost minimization. Watch for enzymatic bioconversion cost parity signals as inflection indicators, when allulose and tagatose production costs approach sucrose equivalence and trigger mass reformulation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Processing | Cargill Australia and Tate & Lyle capture margin currently absorbed by Chinese Yunnan processors. |
| Precision Fermentation Scale-Up | Melbourne biotech facilities expand allulose and tagatose output for direct tanker delivery to dairy processors. |
| Direct-to-Manufacturer Platform Launch | B2B marketplaces bypass traditional distributor markups for New South Wales functional food startups. |
| Glycaemic Index Substantiation Services | TGA-compliant documentation bundles address six-figure validation burdens for mid-tier manufacturers. |
| Queensland Extraction Capacity Acquisition | Consolidated stevia processing secures supply continuity against Chinese harvest variability exposure. |
Study Parameters
Direct dialogue with formulation chemists at national beverage brands, procurement leads at Victorian dairy processors, FSANZ regulatory affairs specialists, and Queensland extraction facility operators grounded qualitative findings in operational reality. Secondary validation drew from FSANZ food standards code amendments, TGA therapeutic claims guidance, Australian Bureau of Agricultural and Resource Economics trade data, and Health Star Rating system technical documentation. Bottom-up volume estimates from state-level manufacturing facility outputs triangulated against top-down sweetener category consumption trends.
Segmented projections across product type, form, application, and customer type dimensions generated value and volume trajectories across the analysis window. CAGRs derived from regression analysis of historical procurement patterns, elasticity-adjusted for Health Star Rating compliance deadlines and enzymatic bioconversion cost curves. Industry-specific inputs included stevia leaf harvest yield variability from Chinese provincial agriculture bureaus and precision fermentation facility commissioning timelines from Victorian biotechnology investment disclosures.
The model assumes a particular technology adoption path for enzymatic rare sugar production; alternative pathways involving cell-free bioconversion or novel yeast strain engineering would alter cost parity timelines and reformulation velocity. Forecasts reflect documented assumptions regarding FSANZ enforcement consistency and Chinese export tariff stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
China Food Sweetener Market
Sweeteners
South America Stevia Market
Sweeteners
Stevia Mints Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Sucralose Market
Sweeteners
Saccharin Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Erythritol Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Date Sugar Market
Sweeteners
Tagatose Market
Sweeteners
Australia Allulose Market