
 Tabletop Pizza Oven Market | 2026-2036
Tabletop Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Tabletop Pizza Oven Market Analytics
Asset-light leasing and pay-per-use financing for commercial kitchen equipment is tilting competitive dynamics toward mid-scale operators who previously lacked capital for premium heat sources. Ooni Pizza Ovens leverages direct-to-consumer channel control to sustain margin capture across compact electric and gas formats. Gozney anchors its position through product specialization in high-output stone-baked systems for restaurants. BakerStone differentiates by occupying the crossover zone between residential outdoor cooking and light commercial deployment.
A tabletop pizza oven denotes a portable, counter-top thermal appliance engineered to reach temperatures between 700°F and 900°F using refractory stone or steel decks, designed for rapid-cook Neapolitan-style and New York-style pizza production in spaces without built-in ventilation infrastructure. Electric units now lead volume shipments among households seeking plug-and-play operation without fuel storage, while wood-fired configurations command the strongest margin pools in the catering services segment where flame visibility drives customer experience value. Compact size tiers dominate unit sales for residential outdoor cooking applications, though medium formats generate disproportionate value in food truck installations where throughput per square foot determines equipment selection.
The US EPA regulates particulate emissions from wood-fired combustion appliances, pushing manufacturers toward cleaner pellet-burning architectures or electric alternatives to maintain market access. EU Ecodesign requirements and CE marking obligations for electrical safety constrain import pathways for Asian-origin equipment, favoring regional producers with certified testing infrastructure. Stakeholders must monitor how municipal fire codes in dense urban districts restrict propane and wood fuel use on commercial terraces, as these local ordinances increasingly override product-level compliance and reshape deployment feasibility across restaurant and catering channels.
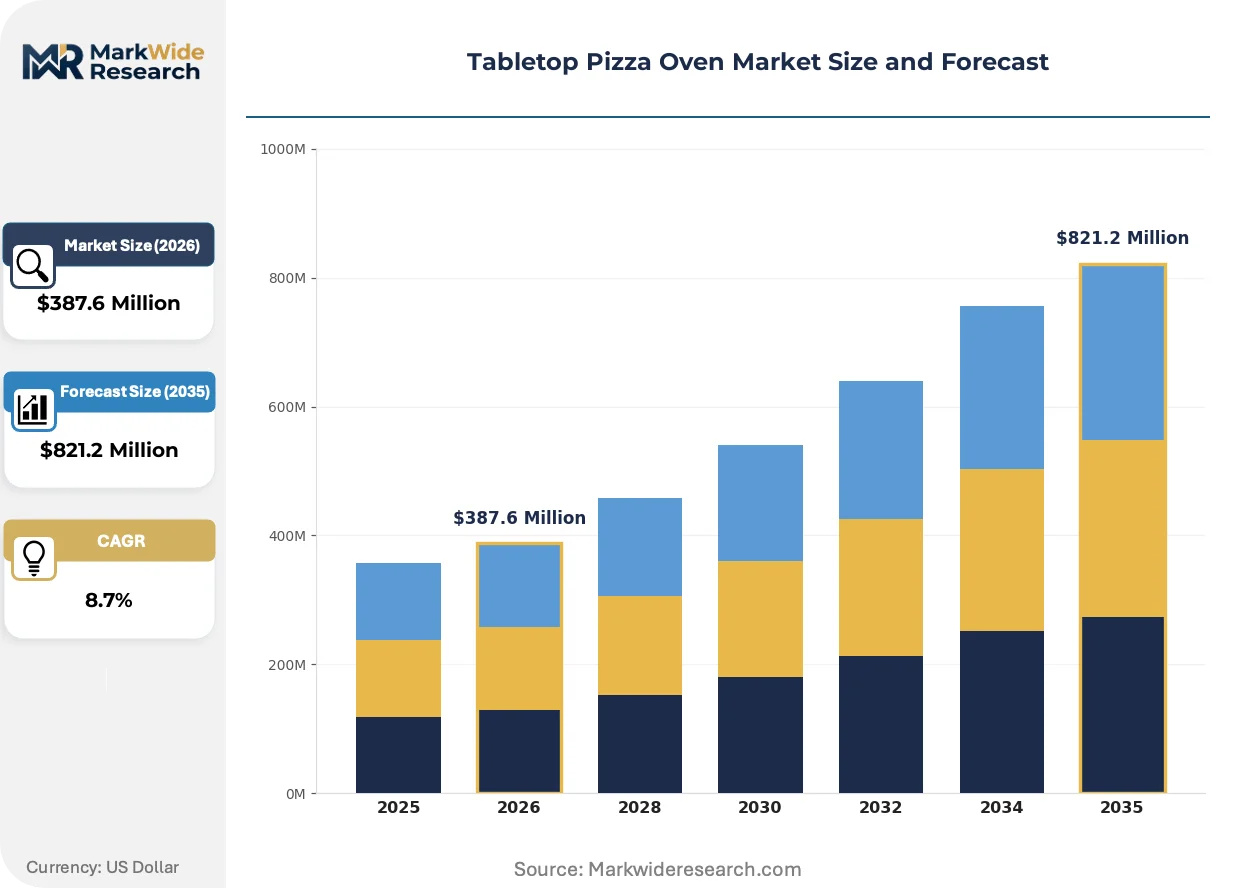
Market Dynamics
Asset-light leasing models for commercial kitchen equipment are compressing capital barriers for mid-scale operators, tilting competitive dynamics toward operators who previously lacked access to premium heat sources. This financing shift intersects with tightening emissions standards from the US EPA and EU Ecodesign, forcing manufacturers to redesign combustion architectures or pivot toward electric alternatives.
Growth Catalysts
- EU Ecodesign compliance pathways:Regional producers with certified testing infrastructure gain preferential import access as CE marking obligations constrain Asian-origin equipment, consolidating procurement toward compliant supply bases.
- Food truck throughput requirements:Medium-format stone-baked systems generate disproportionate value in mobile foodservice where square-foot efficiency determines equipment selection, accelerating compact gas unit deployment.
- Outdoor dining permanence:Terrace and patio infrastructure investments in Italy and Spain sustain premium wood-fired purchases where flame visibility drives customer experience differentiation.
Market Restraints
- Refractory stone supply concentration:High-alumina cordierite sourcing clusters in specific mining districts, exposing manufacturers to input cost volatility and geopolitical disruption in ceramic supply chains.
- Propane storage restrictions:Municipal fire codes in dense urban districts limit fuel deployment on commercial terraces, constraining addressable market for gas configurations regardless of product-level compliance.
- Electric grid capacity:240V outlet requirements and amperage demands restrict residential installation feasibility in older building stock, capping electric unit penetration in retrofit markets.
Strategic Opportunities
- Pay-per-use financing expansion:Equipment-as-a-service models for restaurants reduce upfront capital exposure while capturing recurring revenue streams through usage-based contracts.
- Pellet-burning architectures:Cleaner biomass combustion systems bridge EPA particulate thresholds while preserving flame aesthetics, opening urban deployment previously closed to wood fuel.
- Crossover residential-commercial positioning:Light commercial-grade units sized for outdoor kitchens capture hobbyist upgraders seeking professional performance without ventilation infrastructure.
Industry Challenges
- Certification timeline compression:UL and ETL testing backlogs for electrical safety create launch delays, forcing manufacturers to sequence market entry around laboratory availability.
- Stone deck thermal calibration:Consistent heat distribution engineering requires specialized thermodynamic expertise scarce in contract manufacturing bases, constraining quality scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tabletop Pizza Oven Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Wood-fired, Pellet End User: Households, Restaurants, Food Trucks, Catering Services Size: Compact, Medium, Large, Extra Large Application: Outdoor Cooking, Commercial Use, Residential Use, Events |
| Companies Covered | Ooni Pizza Ovens, Gozney, BakerStone, Forno Bravo, Alfa Forni, Breville, EarthStone Wood-Fire Ovens, Wood Stone Corporation, Fontana Forni USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tabletop Pizza Oven Market Evolving Landscape
Thermal engineering and fuel architecture are converging to reshape product development priorities. Manufacturers now balance emissions compliance against performance authenticity while distribution models fragment between direct-to-consumer control and foodservice equipment dealer networks.
Refractory deck materials are migrating from traditional cordierite toward engineered ceramics with superior thermal shock resistance. Food truck operators and catering services are adopting these advanced substrates fastest, driven by durability demands in high-cycle mobile environments. This material transition is compressing warranty cost structures while enabling thinner deck profiles that reduce preheat energy consumption.
US EPA particulate emissions regulations for wood-fired combustion appliances are tightening enforcement thresholds. Manufacturers must now certify cleaner pellet-burning systems or abandon urban restaurant channels entirely. Italian producers with established testing relationships are responding fastest, while Asian imports face extended approval timelines.
Buying patterns among restaurants are fragmenting between ownership and operational leasing. Food trucks and pop-up operators increasingly source through equipment-as-a-service providers rather than capital purchase, disrupting traditional dealer finance relationships. This behavioral shift is most visible in US coastal metros where real estate costs prioritize balance-sheet flexibility over asset ownership.
Tabletop Pizza Oven Market Segmentation
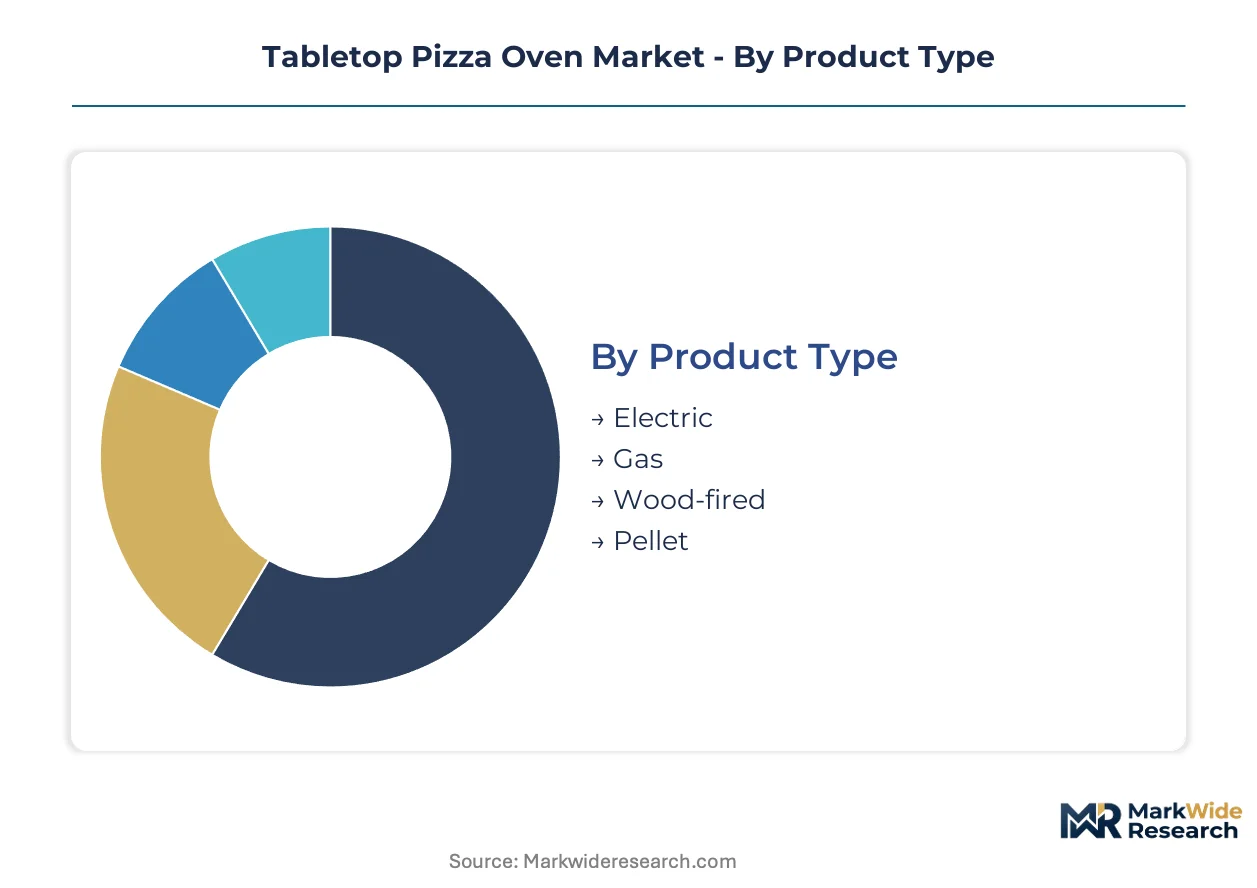
Segmentation in tabletop pizza ovens reveals how fuel architecture, deployment setting, and throughput requirements reshape procurement decisions. Manufacturers must align thermal specifications and compliance profiles against distinct operational constraints across residential and commercial channels.
Product Type:
Cost tier determines margin structure and regulatory exposure for each fuel architecture in this market.
- Electric:Plug-and-play thermal systems using resistive or infrared elements eliminate fuel storage and ventilation infrastructure. Demand concentrates in US and German households where municipal fire codes restrict combustion appliances on balconies and terraces, though 240V installation requirements limit retrofit penetration in older residential stock.
- Gas:Propane or natural gas configurations deliver rapid preheat and precise temperature modulation through burner control. Food trucks across California, Texas, and Florida deploy compact gas units most aggressively where throughput per square foot determines equipment selection and propane logistics remain operationally manageable.
- Wood-fired:Traditional cordierite or refractory brick systems reaching 900°F+ through hardwood combustion. Italian restaurants and Spanish terrace operators sustain premium purchases where flame visibility drives customer experience differentiation and artisanal authenticity commands pricing power.
- Pellet:Biomass pellet combustion architectures bridge EPA particulate thresholds while preserving flame aesthetics. Emerging deployment in urban US districts previously closed to wood fuel due to emissions restrictions.
Electric configurations command the established base. The steepest expansion runs through pellet-burning systems as municipal emissions ordinances tighten.
End User:
Application context reshapes specifications around mobility, duty cycle, and capital deployment flexibility.
- Households:Residential outdoor cooking installations prioritize compact footprints and minimal setup complexity. Weekend-use patterns in US suburbs and Australian metro peripheries favor electric and gas units with sub-30-minute preheat cycles.
- Restaurants:Permanent foodservice operations require certified commercial-grade construction with UL or ETL electrical safety validation. Italian trattorias and Neapolitan-focused pizzerias anchor wood-fired demand where stone-deck authenticity supports menu pricing.
- Food Trucks:Mobile foodservice operators prioritize medium-format systems balancing throughput against vehicle weight and spatial constraints. California and Texas regulatory environments favor gas configurations with onboard propane storage meeting DOT transport requirements.
- Catering Services:Event-based operators demand rapid deployment and visual spectacle. Wood-fired and pellet units dominate wedding and festival circuits where flame presence enhances guest experience and social media capture value.
Households represent the volume anchor. Food trucks are climbing the fastest as mobile foodservice licensing expands across US metropolitan zones.
Size:
Physical dimensions directly correlate with thermal mass, preheat energy, and pizza throughput capacity.
- Compact:Countertop units under 24 inches wide targeting residential balconies and small commercial terraces. German and Japanese urban households favor this tier where outdoor space constraints dominate selection criteria.
- Medium:Systems accommodating 12-16 inch pizzas with sufficient deck area for sequential baking. Food trucks and catering operators in the US and Italy select this format for throughput efficiency without excessive vehicle payload or transport bulk.
- Large:Equipment supporting simultaneous multi-pizza production for high-volume restaurants. Established pizzerias in Naples and New York deploy these configurations where peak-hour demand requires sustained thermal recovery.
- Extra Large:Professional installations exceeding standard tabletop classification with extended deck surfaces. Limited deployment in festival catering and large-format event production where batch capacity outweighs portability requirements.
Compact units hold the broadest installed base. Medium formats are gaining share fastest as food truck and outdoor dining infrastructure investments accelerate.
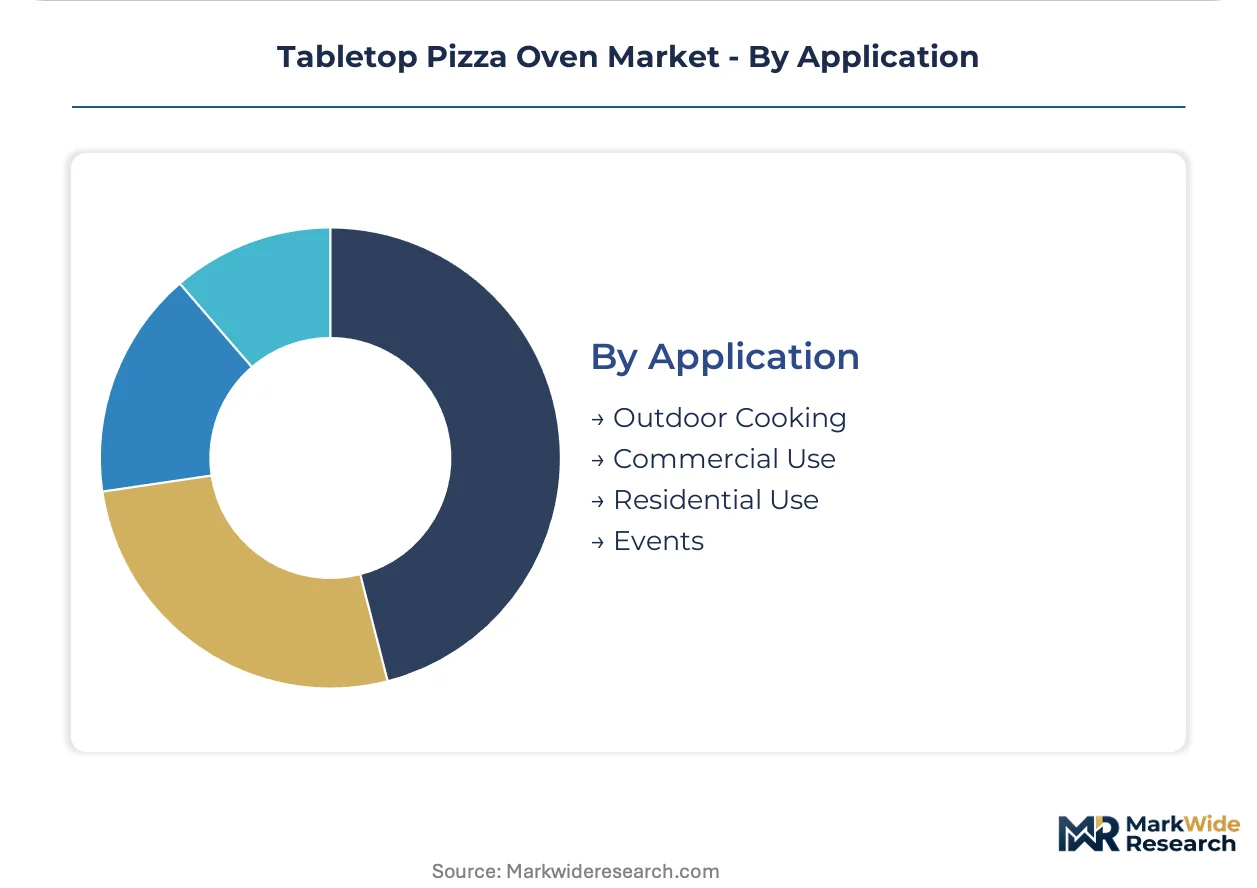
Application:
Deployment setting dictates fuel permissibility, ventilation requirements, and durability specifications against environmental exposure.
- Outdoor Cooking:Residential patio and terrace installations exposed to weather cycling. Australian and Mediterranean markets sustain this segment where year-round outdoor dining culture supports premium equipment purchases.
- Commercial Use:Revenue-generating foodservice operations requiring certified safety compliance and warranty coverage for high-duty cycles. US restaurants and Italian hospitality operators drive specifications toward stone-deck authenticity and rapid thermal recovery.
- Residential Use:Indoor or enclosed space deployment where electric configurations dominate due to emissions and fire safety constraints. German and Swiss markets favor this application tier with strict building code enforcement.
- Events:Temporary installations for festivals, weddings, and corporate gatherings requiring transportability and rapid setup. UK and US catering markets favor pellet and gas units for regulatory flexibility across municipal jurisdictions.
Commercial use anchors value concentration. Events are expanding most quickly as experiential dining and festival culture proliferates across European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian operators capture pricing premiums through artisanal authenticity, while German households face installation constraints that compress unit economics. This asymmetry reshapes manufacturer portfolio priorities across the Atlantic basin.
United States
Food truck licensing expansion in California and Texas accelerates medium-format gas unit procurement. The EPA regulates particulate emissions from wood-fired combustion, pushing manufacturers toward pellet-burning architectures. Los Angeles and Austin clusters concentrate mobile foodservice equipment deployment where throughput per square foot determines selection.
Germany
Balcony fire codes in Berlin and Munich restrict combustion appliances, channeling demand toward electric configurations. CE marking obligations and Ecodesign requirements constrain import pathways for non-compliant Asian-origin equipment. The Ruhr industrial corridor hosts certified testing infrastructure that accelerates regional producer market access.
Italy
Neapolitan pizzerias and terrace operators sustain premium wood-fired purchases where flame visibility drives customer experience value. EU Ecodesign standards and local emissions ordinances tighten compliance thresholds for combustion appliances. Naples and Rome anchor artisanal equipment demand, with Emilia-Romagna emerging as a fabrication cluster for stone-deck systems.
Australia
Year-round outdoor dining culture in Sydney and Melbourne supports premium residential purchases across compact and medium formats. The country's building code enforcement varies by state, with Victoria adopting stricter balcony fuel restrictions than Queensland. Perth's mining-derived affluence concentrates high-end outdoor kitchen installations.
United Kingdom
Catering services and festival operators in London and Manchester favor pellet and gas units for regulatory flexibility across municipal jurisdictions. The UK's departure from EU harmonization creates parallel certification requirements for electrical safety. The Cotswolds and Lake District clusters drive rural residential demand for wood-fired aesthetics.
Tabletop Pizza Oven Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying refractory decks and burner assemblies. The vendor base concentrates around three strategic archetypes: direct-to-consumer brands controlling channel margin, foodservice equipment specialists anchoring restaurant supply relationships, and crossover players bridging residential outdoor cooking with light commercial deployment. Competitive moves center on certification timeline acceleration and material substitution in thermal substrates.
Within the direct-to-consumer archetype, Ooni Pizza Ovens exemplifies channel control strategies, while Gozney occupies a position in high-output stone-baked specialization. BakerStone represents the crossover tier, bridging residential and light commercial positioning. These three anchors illustrate how fuel architecture specialization and distribution model selection reshape competitive boundaries without requiring vertical integration into refractory supply.
| Leading Market Players |
|---|
| Ooni Pizza Ovens |
| Gozney |
| BakerStone |
| Forno Bravo |
| Alfa Forni |
| Breville |
| EarthStone Wood-Fire Ovens |
| Wood Stone Corporation |
| Fontana Forni USA |
| Others |
Value Network & Pricing Analysis
Italian refractory stone mining districts concentrate high-alumina cordierite supply, anchoring margin capture among manufacturers with captive deck fabrication or long-term offtake agreements. This upstream clustering shapes downstream pricing power, as stone-deck authenticity commands premium positioning in restaurant and catering channels.
Pricing Analysis
Configured-to-order wood-fired systems command spreads of 40-60% above standard electric SKUs, reflecting stone-deck craftsmanship and UL/ETL certification tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal recovery speed and warranty coverage. Cost compression in compact electric tiers is intensifying because Asian-origin manufacturers compete on plug-and-play simplicity. Households exhibit highest price sensitivity, while Italian trattorias absorb premium positioning for flame-visibility differentiation.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are emerging as competitive weapons among Italian and German equipment fabricators seeking distributor loyalty. Supply concentrates in Italy, China, and Germany for refractory decks, burner assemblies, and steel enclosures. Ceramic supply chains draw from specific mining districts, exposing manufacturers to input cost volatility. Tariff exposure on Chinese-origin electrical components creates vulnerability for price-competitive electric entrants. Distribution runs through foodservice equipment dealers and direct-to-consumer platforms in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
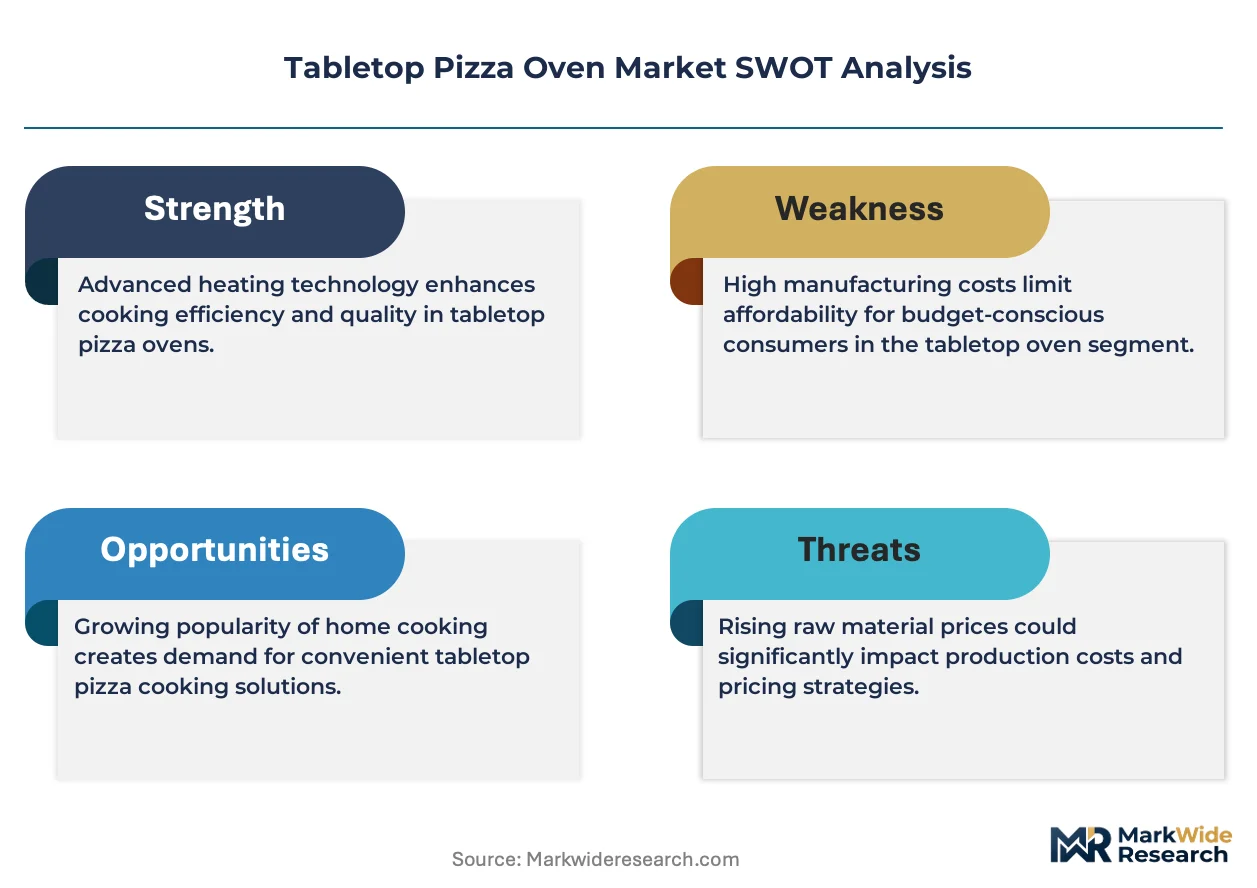
Regulatory entrenchment around EPA particulate thresholds and EU Ecodesign compliance creates durable moats for certified producers, as testing backlog delays rival market entry.
For Market Incumbents: Insulate certification-derived positioning by accelerating UL/ETL laboratory partnerships to compress approval timelines for pellet-burning architectures. Secure backward integration into cordierite supply through offtake agreements with Italian mining districts. Emerging Asian electric entrants threaten compact-tier margins through price aggression. For New Entrants and Emerging Players: Pursue equipment-as-a-service white space in US coastal metros where food truck operators prioritize balance-sheet flexibility over ownership. Pellet-burning configurations for urban restaurant terraces represent the most penetrable segment, as municipal emissions ordinances displace traditional wood-fired systems. Go-to-market traction requires EPA pre-certification investment before channel engagement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor cooking brands seeking platform consolidation into commercial foodservice. Five-to-ten year viability hinges on fuel architecture flexibility across electric, gas, and pellet systems. Acquisition targets should demonstrate certified testing relationships and regional production footprints. Watch for EPA enforcement acceleration as inflection indicator for pellet-system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Pellet-Burning Certification Investment | EPA pre-approval unlocks urban restaurant channels previously closed to wood fuel. |
| Refractory Deck Backward Integration | Captive cordierite supply insulates margin from Italian mining district volatility. |
| Equipment-as-a-Service Launch | Usage-based contracts capture recurring revenue from California and Texas food truck clusters. |
| Direct-to-Consumer Channel Expansion | Ooni's margin model demonstrates pricing power through platform-controlled distribution. |
| Crossover Residential-Commercial Positioning | BakerStone's tier captures hobbyist upgraders seeking professional performance without ventilation. |
Research Methodology
A standing panel of restaurant equipment procurement managers, food truck operators, refractory material suppliers, and commercial kitchen leasing executives provided ongoing calibration against shipment data and pricing intelligence. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed appliance manufacturers, EPA certification databases, EU Ecodesign registry entries, and customs trade records. Bottom-up unit economics triangulated against top-down market sizing across fuel architecture and end-use segments.
Scenario-bracketing anchored projections across base, upside, and downside demand trajectories over the analysis window. Segmentation modeling incorporated fuel type, size tier, end-user category, and regional regulatory cluster dimensions. CAGRs derived from installed base growth rates, replacement cycle analysis, and penetration assumptions by application. Forecast inputs included municipal fire code adoption timelines, food truck licensing expansion rates, and pellet-fuel infrastructure development.
Sensitivities concentrate around EPA enforcement intensity, cordierite supply disruptions, and electric grid capacity constraints in older residential stock. Forecasts reflect documented assumptions on regulatory trajectory and substitution elasticity between fuel architectures. Macroeconomic contraction, accelerated emissions standard tightening, or breakthrough infrared heating technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Brazil Foodservice Market
Food Service
Inflight Catering Market
Food Service
Virtual Kitchen Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Stirrers Market
Food Service
Food Delivery Services Market
Food Service
Onboard Rail Catering Market
Food Service
Smoker Grill Market
Food Service
Africa Foodservice Market
Food Service
United States Online Food Delivery Market
Food Service
Spain Food Service Market
Food Service
Food Away from Home Market
Food Service
Australia Foodservice Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
India Foodservice Market
Food Service
China Inflight Catering Market