
 Asia-Pacific Low-Calorie Sweeteners Market | 2026-2036
Asia-Pacific Low-Calorie Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Low-Calorie Sweeteners Market Outlook
Premium-grade stevia extract specifications with higher rebaudioside-A purity is unwinding commodity pricing structures across the Asia-Pacific supply base. PureCircle Limited leverages its Malaysian agronomy and extraction footprint to sustain leaf-to-powder vertical control. Tate & Lyle PLC anchors reformulation service capabilities that help beverage clients navigate sensory matching challenges. Ajinomoto Co., Inc. competes through amino-acid-based sweetener specialization in Japan and Southeast Asian processed food channels.
Asia-Pacific low-calorie sweeteners are non-nutritive sugar substitutes engineered to deliver sweetness intensity multiples above sucrose while contributing negligible caloric value, typically manufactured through fermentation, enzymatic conversion, or solvent extraction processes with specified purity thresholds measured by HPLC analysis. Stevia leaf extracts and sucralose dominate volume flows into beverage applications, where reformulation mandates from brand owners and retail chains concentrate procurement scale. Powder and granulated forms capture the bulk of industrial demand due to dosing precision and shelf stability requirements in high-throughput bakery and dairy operations.
China's NMPA and SAMR enforce food additive registration and GB standard compliance for novel sweetener introductions, while India's FSSAI operationalizes front-of-pack sugar warning labels that accelerate manufacturer switching behavior. The EU Green Deal's deforestation due diligence requirements, as mirrored by Asia-Pacific import jurisdictions, are reshaping stevia leaf sourcing verification protocols. Stakeholders must monitor regulatory divergence between national pharmacopeia standards and CODEX-aligned frameworks to anticipate reformulation cost impacts and qualification timelines.
Market Dynamics
Reformulation mandates from beverage brand owners and retail chains are compressing procurement cycles for stevia extracts and sucralose across the Asia-Pacific supply base, forcing manufacturers to qualify alternative sweeteners under accelerated timelines.
Growth Catalysts
- FSSAI Front-of-Pack Labeling:India's mandatory sugar warning labels are compelling domestic beverage and confectionery manufacturers to switch to rebaudioside-A stevia extracts.
- China's Processed Food Scale:Expansion in the country's bakery and dairy sectors concentrates bulk procurement demand for granulated sucralose and erythritol blends.
- Enzymatic Bioconversion:Novel fermentation-derived sweeteners produced via engineered yeast strains are broadening the functional ingredient palette for clean-label product developers.
Market Restraints
- Stevia Leaf Input Volatility:Weather-dependent agronomic yields in Guangxi and Yunnan provinces create raw material price swings that compress extractor margins.
- Sucralose Supply Concentration:Bulk chemical synthesis capacity clusters among a limited set of Chinese manufacturers, exposing buyers to single-source risk during environmental compliance shutdowns.
- Sensory Matching Limitations:Bitter aftertaste profiles in high-purity stevia formulations require expensive taste-modifier adjuncts that erode cost advantages versus sugar.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Nascent processed food sectors in these markets present first-mover positioning for amino-acid-based sweetener specialists.
- EU Green Deal Deforestation Due Diligence:Verification protocols for stevia leaf traceability are creating service-layer revenue streams for agronomy audit providers.
- Direct-to-Manufacturer Digital Platforms:B2B ingredient marketplaces are disintermediating traditional distributor networks for mid-scale bakery and beverage compounders.
Industry Challenges
- Novel Food Approval Timelines:NMPA and SAMR registration pathways for fermentation-derived sweeteners extend qualification cycles beyond typical product development windows.
- Cross-Functional Formulation Expertise Scarcity:Beverage manufacturers lack in-house capability to reconcile sweetness intensity curves with mouthfeel and stability requirements.
- GB Standard Harmonization Delays:Divergence between China's food additive purity specifications and CODEX-aligned frameworks complicates multi-jurisdiction product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Low-Calorie Sweeteners Market |
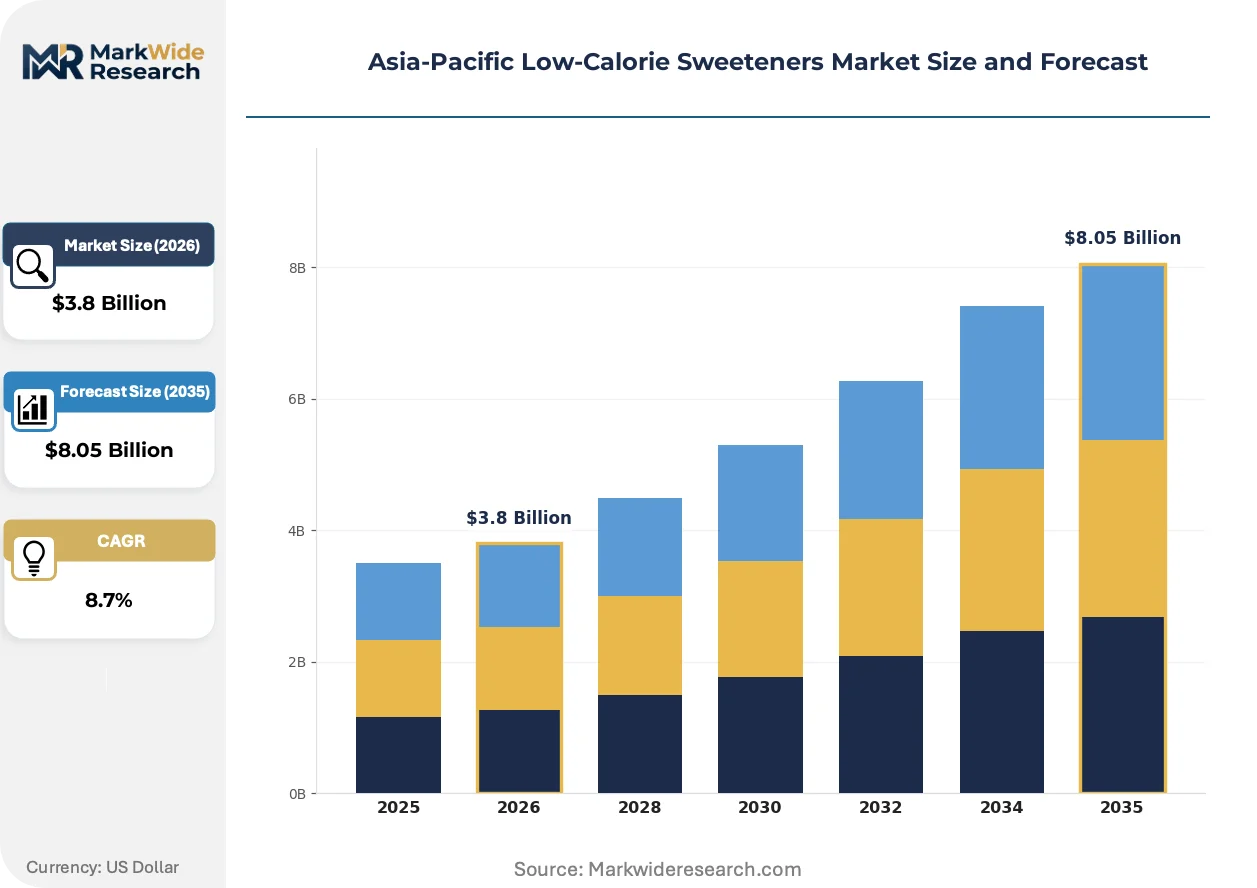
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aspartame, Sucralose, Stevia, Acesulfame Potassium Application: Beverages, Bakery, Dairy, Confectionery Form: Liquid, Powder, Granulated, Tablet End User: Food Industry, Beverage Manufacturers, Pharmaceutical Companies, Household Consumers |
| Companies Covered | Ingredion Incorporated, PureCircle Limited, Tate & Lyle PLC, Sunwin Stevia International Inc, Ajinomoto Co., Inc., Cargill Incorporated, Roquette Frères, Biolotus Technology Lasa Inc, The Archer Daniels Midland Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Low-Calorie Sweeteners Market Strategic Shifts
Biotechnology-derived sweetening molecules and tightening supply-chain verification requirements are restructuring how Asia-Pacific manufacturers source, qualify, and deploy low-calorie alternatives across beverage and food matrices.
Enzymatically enhanced stevia glycosides with optimized rebaudioside-M ratios are supplanting conventional rebaudioside-A extracts in premium beverage applications. Japanese and South Korean functional drink manufacturers have accelerated adoption timelines from 18-month qualification cycles to 6-month pilots. The structural consequence is compression in commodity-grade leaf extract pricing as high-purity bioconversion output captures formulation budgets.
China's SAMR has tightened GB 2760 food additive maximum usage levels for synthetic sweeteners in dairy and fermented milk categories. Industrial consequence includes forced reformulation of existing product lines and accelerated natural sweetener substitution programs. Domestic dairy processors in Shandong and Heilongjiang provinces are responding by locking multi-year supply contracts with Malaysian stevia extractors.
Retail chain private-label programs are consolidating sweetener specification power previously dispersed across national brand portfolios. Supermarket and convenience store chains in Australia and Thailand now mandate single-sweetener platforms across their beverage and bakery supplier bases to simplify quality auditing. This concentration is most visible in Bangkok and Sydney metropolitan procurement regions where chain store density drives supplier compliance investments.
Asia-Pacific Low-Calorie Sweeteners Market Segmentation
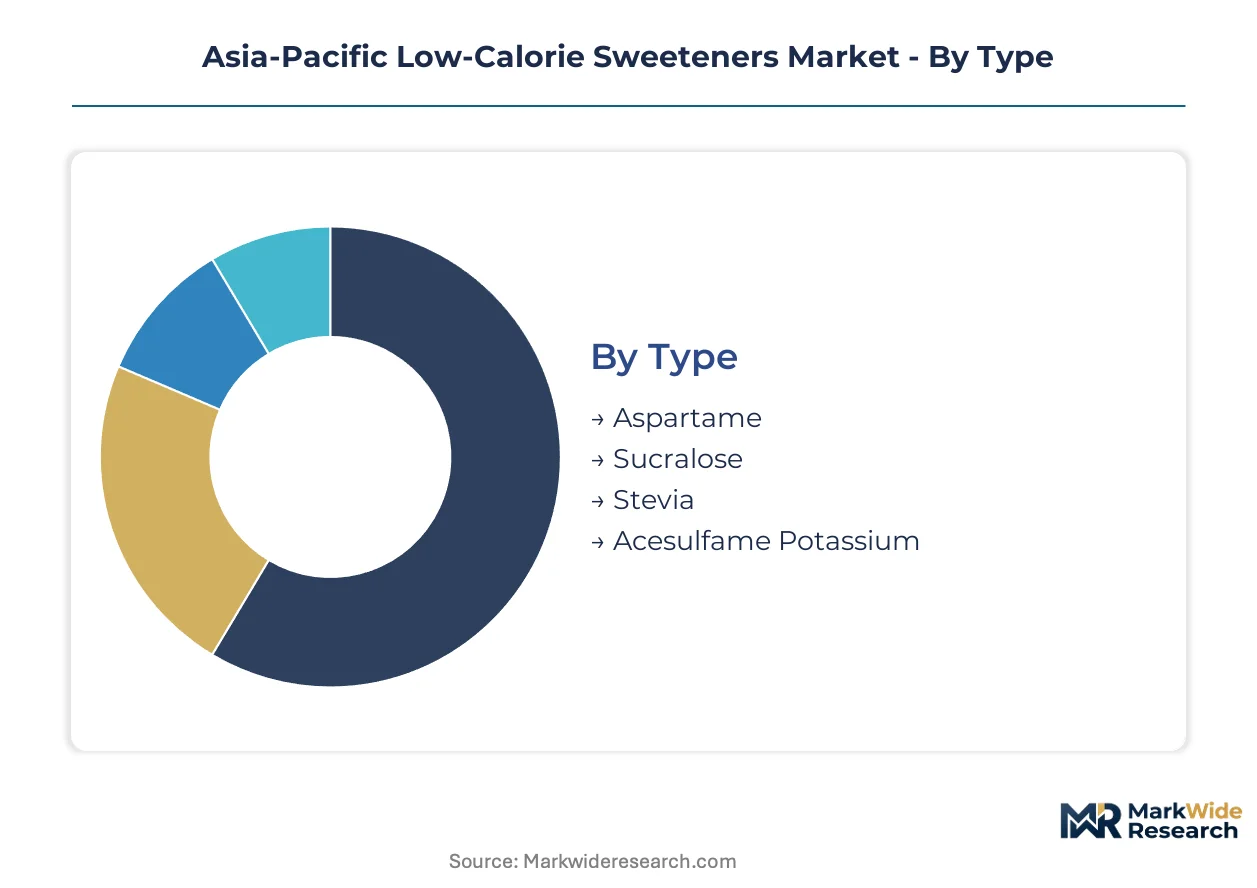
Sweetener specification choices in Asia-Pacific carry direct regulatory compliance consequences across NMPA, FSSAI, and SAMR jurisdictions. Procurement segmentation determines which purity thresholds and usage limits apply, shaping supplier qualification timelines and reformulation costs.
Type:
GB 2760 maximum usage levels and FSSAI additive schedules create divergent compliance burdens across synthetic and natural sweetener categories, forcing manufacturers to segment procurement by regulatory pathway rather than sweetness intensity alone.
- Stevia:Leaf-derived glycosides with specified rebaudioside-A or rebaudioside-M purity measured by HPLC analysis. Chinese beverage manufacturers in Guangdong and Zhejiang provinces are locking supply contracts with Malaysian extractors to secure front-of-pack labeling compliance for reduced-sugar claims.
- Sucralose:Chlorinated disaccharide synthesized through selective substitution of hydroxyl groups on sucrose. Bulk chemical production concentrates in Jiangsu and Shandong provinces, where environmental compliance shutdowns periodically constrain availability for Indian dairy processors.
- Aspartame:Methyl ester dipeptide requiring phenylketonuria labeling across all Asia-Pacific jurisdictions. Pharmaceutical tablet applications in Japan sustain niche demand despite beverage sector displacement.
- Acesulfame Potassium:Synthetic oxathiazinone dioxide with high heat stability for bakery applications. Thai and Indonesian biscuit manufacturers favor this for cost-controlled reformulation of mass-market product lines.
Established volume favors sucralose; emerging adoption favors stevia.
Application:
Reformulation mandates from retail chains and brand owners concentrate procurement scale differently across liquid versus solid food matrices, with sensory matching requirements varying by water activity and thermal processing conditions.
- Beverages:Carbonated and still drinks requiring sweetness stability across pH ranges and pasteurization cycles. China's Nongfu Spring and Japan's Kirin Beverage are accelerating stevia-sucralose blend adoption to meet SAMR and METI labeling pressures.
- Bakery:Heat-processed applications demanding thermal stability above 180°C. Australian and New Zealand manufacturers prioritize granulated sucralose and acesulfame potassium for Maillard reaction compatibility in crust formation.
- Dairy:Fermented milk and yogurt categories facing tightened GB 2760 maximum usage levels for synthetic sweeteners. Shandong and Heilongjiang processors are switching to erythritol-stevia blends to maintain sweetness without regulatory exceedance.
- Confectionery:Hard candy and chewing gum applications requiring sustained sweetness release profiles. Indian FSSAI sugar warning labels are pushing domestic manufacturers toward high-purity stevia extracts in premium chocolate segments.
Volume concentration sits with beverages; margin expansion sits with dairy.
Form:
Dosing precision requirements and shelf stability needs segment procurement between industrial compounders and finished goods manufacturers, with powder and granulated formats capturing bulk throughput.
- Powder:Spray-dried or crystallized material with specified particle size distribution for uniform blending. High-throughput bakery and dairy operations in China and Vietnam require this for automated dosing system compatibility.
- Granulated:Agglomerated particles with improved flow properties for direct compression tableting. Pharmaceutical manufacturers in Japan and South Korea specify this for excipient blending in oral dosage forms.
- Liquid:Aqueous or propylene glycol solutions with defined concentration for pump-metered addition. Beverage bottling lines in Thailand and Indonesia favor this for continuous process integration and reduced dust exposure.
- Tablet:Direct-compression or granulated compacts for single-serve household dispensing. Australian retail chains are expanding private-label tablet ranges for consumer-controlled sweetening of coffee and tea.
Industrial procurement favors powder and granulated; consumer channel growth favors tablet and liquid.
End User:
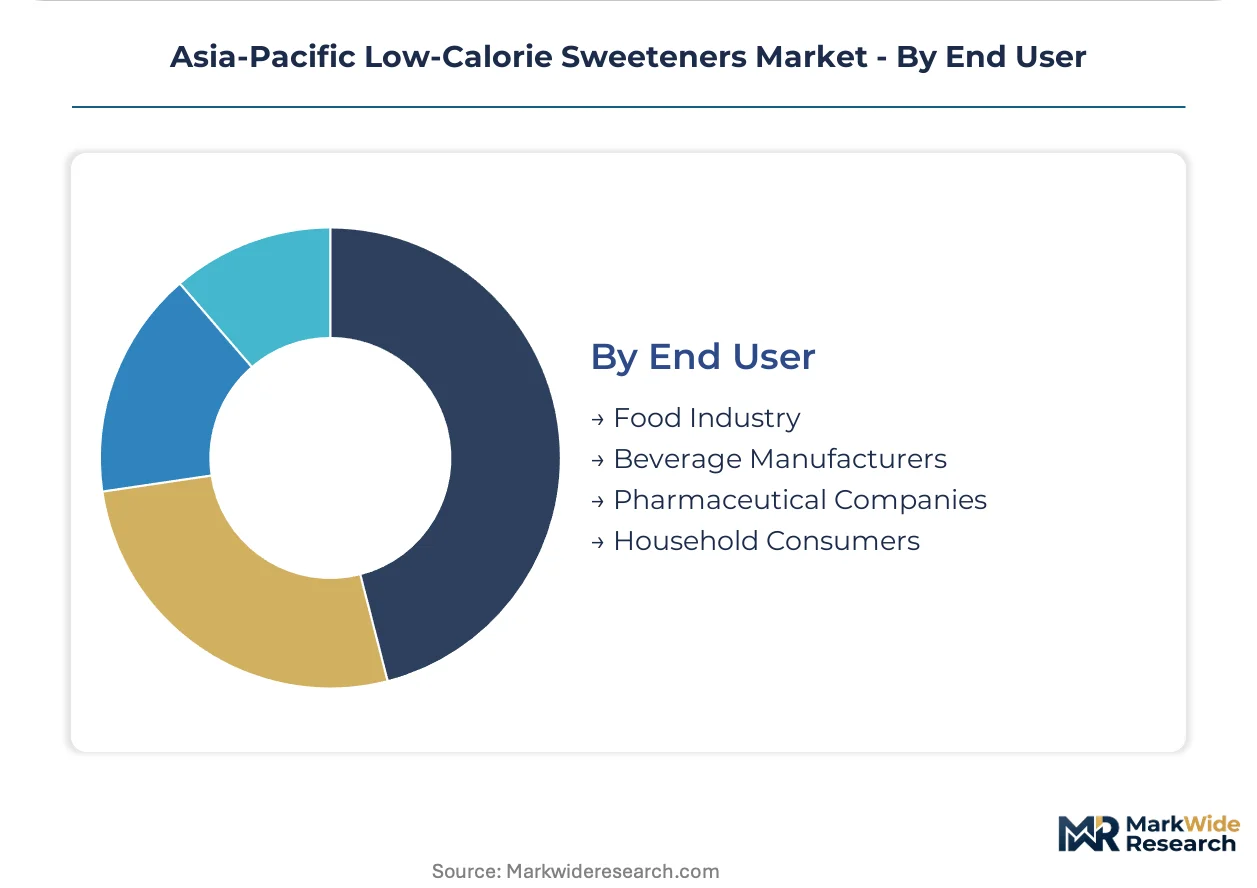
Formulation expertise availability and regulatory compliance burden split demand between sophisticated compounders with in-house sensory capabilities and specification-takers dependent on supplier technical support.
- Beverage Manufacturers:Brand owners and contract packers with dedicated reformulation teams navigating sensory matching challenges. Suntory in Japan and Tingyi in China are investing in stevia glycoside bioconversion partnerships to accelerate qualification cycles.
- Food Industry:Processed food manufacturers across bakery, dairy, and confectionery segments with varying technical capabilities. Mid-scale compounders in Vietnam and Indonesia rely heavily on supplier-provided application guidance.
- Pharmaceutical Companies:Dosage form developers requiring excipient-grade sweeteners with pharmacopeia-compliant documentation. India's CDSCO and China's NMPA impose distinct purity verification protocols that segment supplier eligibility.
- Household Consumers:Retail purchasers of table-top sweeteners through supermarket and e-commerce channels. Australian and Thai retail chain private-label consolidation is reducing brand diversity in this segment.
Procurement scale concentrates with beverage manufacturers and food industry compounders; specification complexity concentrates with pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian stevia extractors ship bulk rebaudioside-A concentrates to Guangdong beverage compounders, while Chinese sucralose manufacturers supply Indian dairy processors facing FSSAI compliance deadlines. This trade-flow structure concentrates procurement leverage in extraction hubs and creates dependency risks for reformulation-heavy markets.
China
Nongfu Spring and Tingyi drive stevia-sucralose blend procurement for reduced-sugar claims. SAMR tightened GB 2760 maximum usage levels for synthetic sweeteners in dairy. Shandong and Heilongjiang processors now lock multi-year contracts with Malaysian extractors to secure supply continuity.
India
Domestic beverage manufacturers accelerate switching to high-purity stevia extracts. FSSAI front-of-pack sugar warning labels compress reformulation timelines to under 12 months. Maharashtra and Gujarat confectionery clusters face raw material qualification bottlenecks as demand outpaces certified supplier capacity.
Japan
Kirin Beverage and Suntory invest in stevia glycoside bioconversion partnerships for functional drink lines. METI labeling pressures align with consumer preference for clean-label sweetness. Kanto and Kansai manufacturing belts concentrate pilot-scale adoption of enzymatically enhanced extracts.
Australia
Retail chain private-label programs consolidate sweetener specifications across beverage and bakery supplier bases. TGA-aligned purity documentation requirements segment supplier eligibility. Sydney and Melbourne metropolitan procurement regions drive compliance investments through chain store density.
Thailand
Bangkok-based beverage bottling lines favor liquid sweetener formats for continuous process integration. Domestic biscuit manufacturers prioritize acesulfame potassium for cost-controlled mass-market reformulation. Central Plains dairy processors navigate sensory matching challenges in yogurt applications.
Asia-Pacific Low-Calorie Sweeteners Market Competitive Environment
Listed leaders compete with private specialists across extraction scale and reformulation service depth. The supplier base organizes around three tiers: agronomy-integrated extractors controlling leaf-to-powder supply chains, chemical synthesis houses dominating bulk sucralose output, and application specialists providing sensory matching support. Strategic moves concentrate on backward integration into stevia leaf sourcing and partnerships with beverage brands for accelerated qualification cycles.
Within the agronomy-integrated tier, PureCircle Limited represents vertical control archetypes through Malaysian extraction footprint, while Tate & Lyle PLC anchors reformulation service capabilities. Ajinomoto Co., Inc. exemplifies amino-acid-based specialization for processed food channels in Japan and Southeast Asia. These three occupy distinct competitive positions: extraction control, technical services, and regional product chemistry expertise respectively.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| PureCircle Limited |
| Tate & Lyle PLC |
| Sunwin Stevia International Inc |
| Ajinomoto Co., Inc. |
| Cargill Incorporated |
| Roquette Frères |
| Biolotus Technology Lasa Inc |
| The Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory buffers among Guangdong beverage compounders signal procurement leverage concentration in Malaysian extraction hubs, compressing margin capture for mid-tier distributors while amplifying price-setting power for agronomy-integrated suppliers with captive leaf supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Asia-Pacific supply base. Price differentiation rests on rebaudioside-A purity grades certified through HPLC analysis and volume scale commitments exceeding 500-kilogram annual offtakes. Cost compression in commodity-grade stevia extracts is intensifying because Chinese domestic processors are expanding enzymatic bioconversion capacity. Mid-scale bakery compounders in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese functional drink manufacturers demonstrate lowest sensitivity due to reformulation timeline premiums.
Supply Chain Analysis
China and Malaysia anchor stevia glycoside extraction, while India and Thailand concentrate downstream formulation and blending operations. Raw material dependencies center on Yunnan and Guangxi leaf supply, fermentation-derived enzyme inputs, and chromatographic purification resins. Single-source vulnerability runs through Jiangsu province sucralose synthesis clusters, where environmental compliance shutdowns periodically constrain Indian dairy processor access. Distribution runs through regional distributor networks serving mid-scale compounders, with direct-to-manufacturer digital platforms emerging for qualified bulk buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward retail chain private-label consolidators and multinational beverage brand owners, fragmenting specification authority previously held by national distributors.
For Market Incumbents: Consolidate backward integration into Yunnan and Guangxi leaf sourcing to defend against PureCircle's Malaysian agronomy control. Lock multi-year supply contracts with Shandong dairy processors before SAMR tightens GB 2760 synthetic sweetener limits further. Certification investment in EU Green Deal deforestation due diligence protocols represents the critical lever for retaining European export eligibility. For New Entrants and Emerging Players: Sensory matching service gaps in Vietnamese and Indonesian processed food channels offer first-mover positioning for amino-acid-based sweetener specialists. Target Central Plains dairy processors in Thailand with application-technical support bundles that incumbent chemical synthesis houses under-provide. Direct-to-manufacturer digital platforms serving mid-scale bakery compounders represent the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because divergence between NMPA, FSSAI, and CODEX-aligned frameworks creates sustained qualification service demand. Acquisition target archetypes include agronomy-audit providers with EU Green Deal verification capabilities and enzymatic bioconversion specialists with rebaudioside-M production scale. The signal to watch is acceleration in Japanese and South Korean pilot-cycle compression from 18-month to sub-6-month qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Sourcing | Captive Yunnan supply secures margin control against Malaysian extractor pricing power. |
| Enzymatic Bioconversion Scale-Up | Engineered yeast strain capacity captures premium formulation budgets from rebaudioside-A commodity erosion. |
| EU Green Deal Verification Program | Deforestation due diligence compliance unlocks European export channels for Chinese extractors. |
| Direct-to-Manufacturer Digital Platform | B2B marketplace disintermediation reduces distributor margin capture in Vietnam and Indonesia. |
| Sensory Matching Service Expansion | Technical application support secures switching manufacturers facing FSSAI reformulation deadlines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with stevia extraction plant managers, beverage procurement leads at Nongfu Spring and Kirin, FSSAI regulatory affairs specialists, and Malaysian agronomy auditors; combined with secondary validation through SAMR GB standard filings, Indian customs import records, and CODEX food additive specifications. Bottom-up volume triangulation across extraction capacity disclosures and top-down value estimation through downstream formulation cost structures anchored the quantitative framework.
Across the projection horizon, the analytical framework modeled segmentation dimensions including sweetener type, application matrix, form specification, and end-user technical capability tier. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions calibrated to purity-grade spreads. Forecast inputs incorporated SAMR regulatory tightening schedules and FSSAI front-of-pack labeling implementation velocity.
Material uncertainties — NMPA novel food approval timeline extensions, weather-driven Yunnan leaf yield volatility, and EU Green Deal verification protocol finalization — sit outside the modeled envelope. Recalibration cycles align with material shifts in regulatory enforcement intensity and bioconversion technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Italy Food Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Maltodextrin Market
Sweeteners
Sorbitol Market
Sweeteners
D-Mannose Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Mannitol Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Stevia Mints Market
Sweeteners
China Saccharin Market