
 Xylitol Market | 2026-2036
Xylitol Market Size, Share, and Industry Trends Forecast 2026-2036
Xylitol Market Analysis
A wide capital-intensity divergence between players is reorganizing competitive tiers in xylitol production. Cargill, Incorporated leverages its integrated corn wet-milling infrastructure to secure feedstock cost advantages across North American operations. Roquette Frères anchors European supply through pea and wheat starch diversification, while Zhejiang Huakang Pharmaceutical Co., Ltd. competes on crystallization scale out of Zhejiang province.
Xylitol is a five-carbon sugar alcohol (C5H12O5) with a melting point of 92-96°C, produced through catalytic hydrogenation of xylose derived from hardwood hemicellulose or agricultural residues; it delivers approximately 2.4 kcal/g with negligible glycemic impact, making it indispensable for diabetic-friendly formulations and dental-protective products. Granulated and powdered grades dominate volume in food manufacturing where texture and dissolution rate determine specification, while liquid xylitol concentrates margin pools in pharmaceutical oral solutions and personal care humectants where solubility control commands premium positioning. The oral care end-user segment leads absolute consumption through toothpaste and mouthwash formulations, whereas pharmaceutical applications represent the fastest structural expansion as formulators replace sorbitol in pediatric and geriatric dosage forms.
FDA food additive regulations, EFSA novel food assessments, and China's SAMR GB standards collectively shape purity thresholds, labeling requirements, and import clearance protocols for xylitol suppliers seeking multi-jurisdiction market access. REACH compliance in Europe and evolving F-Gas Regulation linkages to biobased chemical processes further condition production investment decisions for fermentation and hydrogenation assets. Stakeholders must monitor regulatory divergence on sugar alcohol labeling between jurisdictions while calibrating capacity plans against feedstock volatility in corn, wheat, and hardwood markets.
Market Dynamics
Capital-intensity divergence between integrated corn processors and regional hardwood refiners is reorganizing competitive tiers, with feedstock access determining margin sustainability across hydrogenation and fermentation routes.
Growth Catalysts
- Pediatric Formulation Demand:Pharmaceutical manufacturers are expanding xylitol use in chewable tablets and liquid syrups as a low-glycemic excipient for diabetic and pediatric populations, with EFSA novel food assessments streamlining approval pathways across European markets.
- Dental Association Endorsements:Germany's BZÄK, Japan's JDA, and the American Dental Association actively promote xylitol's cariostatic properties, driving prescription-grade demand in therapeutic oral care products.
- Cellulosic Feedstock Expansion:Agricultural residue processing from wheat straw and corn stover is diversifying xylose supply beyond hardwood hemicellulose, reducing seasonal dependency on birch and beech harvest cycles.
Market Restraints
- Corn Price Volatility:Wet-milling economics tie North American production to corn futures, with drought conditions in Iowa and Illinois directly compressing hydrogenation margins.
- Purity Benchmark Escalation:China's SAMR GB standards and NMPA import protocols impose tightening heavy metal and microbial thresholds, disqualifying smaller crystallization operators from cross-border supply.
- Erythritol Substitution Pressure:Zero-calorie sweetener formulators in beverage applications increasingly specify erythritol for its lower laxation threshold and comparable cooling effect.
Strategic Opportunities
- Geriatric Dosage Form Expansion:Japan's METI aging-population initiatives and PMDA fast-track designations create regulatory tailwinds for xylitol-based orodispersible films and sublingual tablets.
- Fermentation Route Scale-Up:Yeast-based xylose-to-xylitol bioconversion is converging with carbon capture utilization, enabling producers to position output under EU Green Deal biobased chemical classifications.
- Direct-to-Pharmacy Distribution:API suppliers are bypassing traditional distributor networks to contract directly with hospital formularies and compounding pharmacies, capturing margin previously allocated to wholesale intermediaries.
Industry Challenges
- Crystallization Engineering Talent Scarcity:The specialized skill set for controlling polymorphism and particle size distribution in sugar alcohol production concentrates among aging process engineers in European and Japanese technical institutes.
- Multi-Jurisdiction Certification Timelines:REACH compliance dossiers, FDA food additive petitions, and China's GB standard conformity assessments require parallel regulatory affairs teams, extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylitol Market |
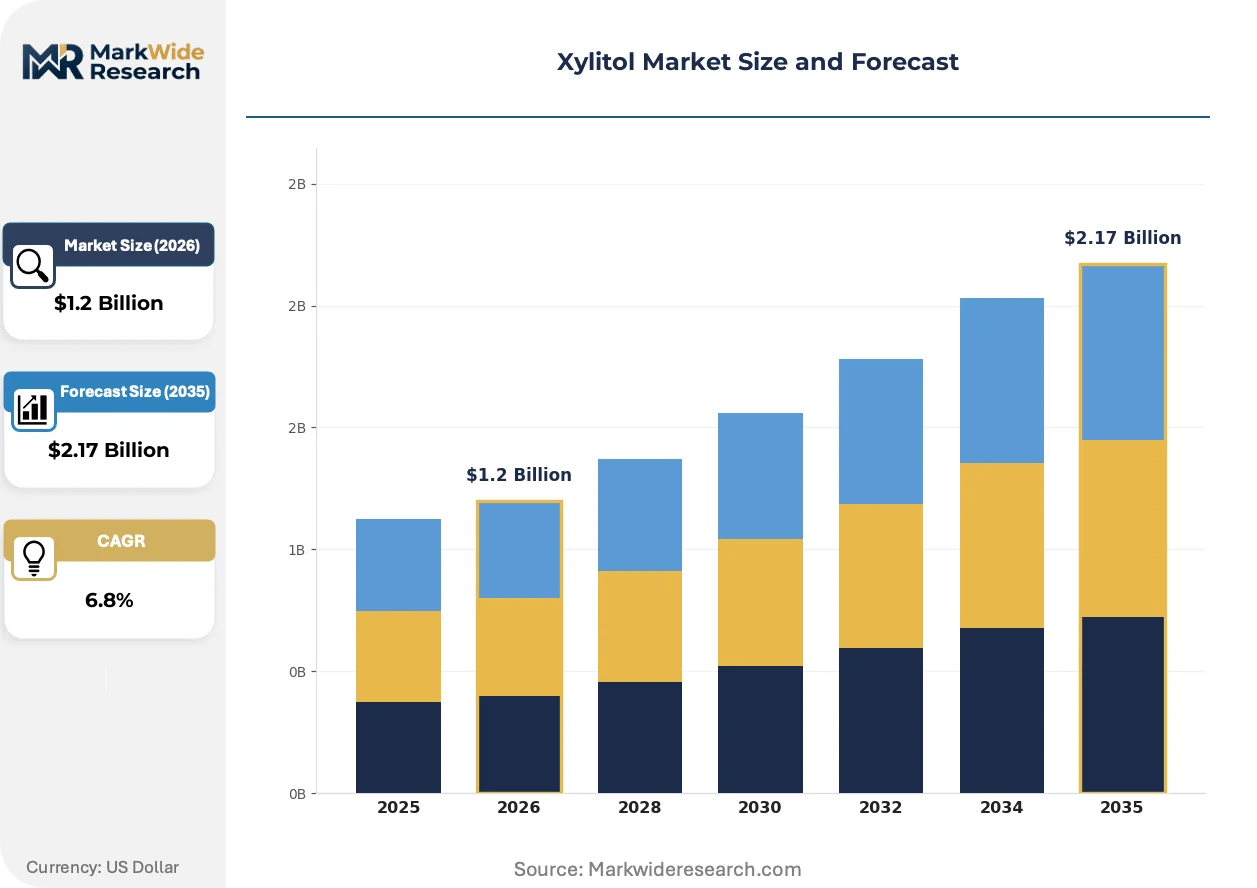
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Liquid, Chewing Gum End User: Food & Beverage, Pharmaceuticals, Cosmetics, Oral Care Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Application: Sweetener, Sugar Substitute, Humectant, Flavoring Agent |
| Companies Covered | Cargill, Incorporated, Roquette Frères, DuPont de Nemours, Inc., Ingredion Incorporated, Zhejiang Huakang Pharmaceutical Co., Ltd., Shandong Futaste Co., Ltd., Archer Daniels Midland Company, Shandong Longlive Bio-Technology Co., Ltd., ZuChem, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylitol Market Emerging Trajectories
Process intensification and regulatory harmonization pressures are compressing traditional production economics while opening differentiated positioning around carbon intensity and purity grades.
Continuous catalytic hydrogenation reactor designs are supplanting batch autoclave configurations in new capacity installations. European engineering firms and Chinese state-owned chemical groups are adopting these systems for their 40% reduction in steam consumption and tighter residence-time control. The technology is supplanting legacy vessel-based production in plants exceeding 10,000-tonne annual capacity, creating a two-tier equipment market split between retrofit-limited incumbents and greenfield optimized entrants.
REACH F-Gas Regulation linkages to biobased process certification are conditioning investment decisions for fermentation assets in the European Economic Area. The regulation's evolving scope creates compliance obligations for hydrogenation catalyst recovery and solvent recycling, pushing producers toward integrated environmental management systems. German and Dutch chemical parks are consolidating xylitol production with shared wastewater and energy infrastructure to distribute compliance costs across tenant firms.
Hospital procurement consortia are consolidating sweetener and excipient purchasing into centralized tender frameworks, displacing decentralized pharmacy-level ordering. This concentration shifts bargaining power toward GPOs and national health service formularies in France, Italy, and Spain. The restructuring is most visible in pediatric and geriatric therapeutic nutrition contracts, where multi-year supply agreements now specify carbon footprint disclosure alongside purity certificates.
Xylitol Market Segmentation
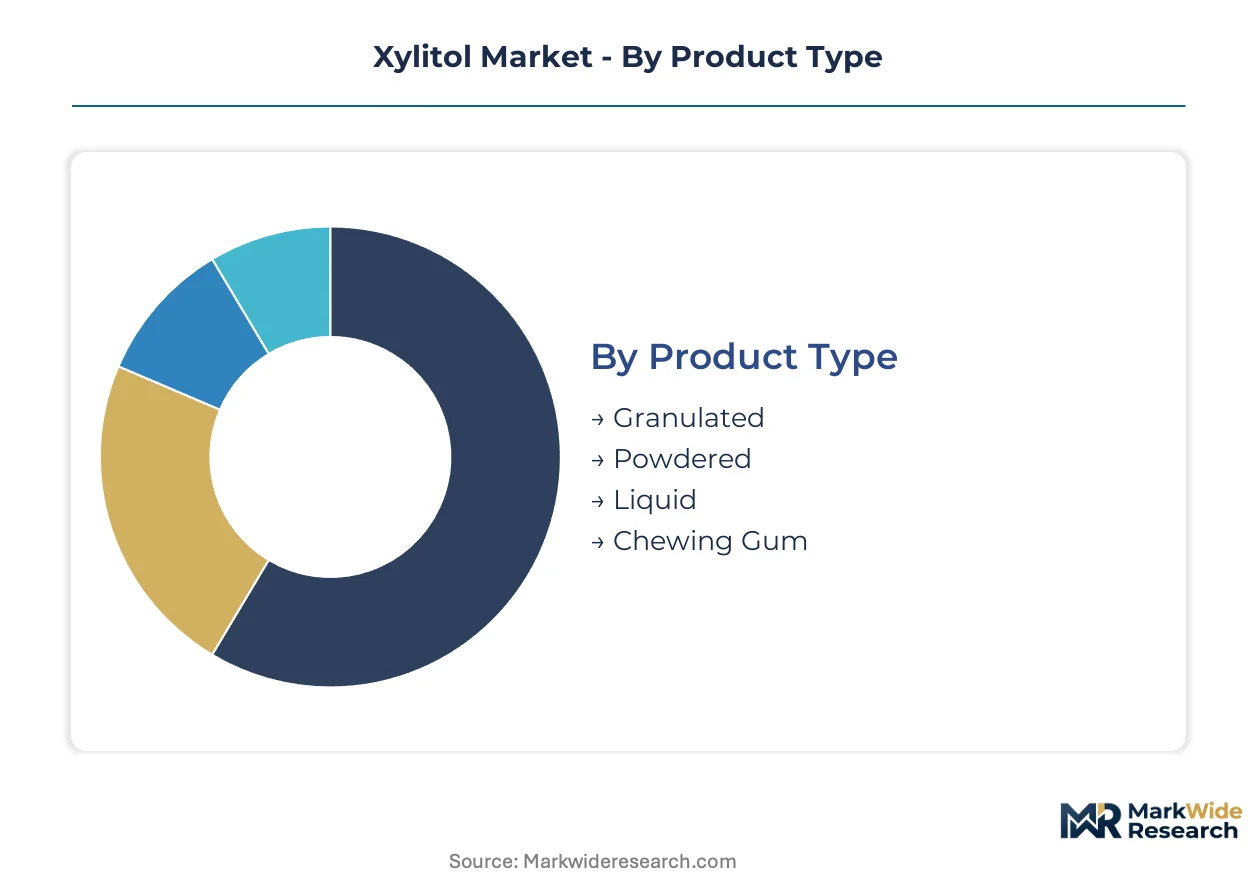
Xylitol's specification diversity creates distinct margin pools across pharmaceutical, food, and oral care value chains. Regulatory purity tiers separate prescription-grade excipients from commodity sweetener grades, conditioning investment returns and certification timelines for producers.
Product Type:
FDA food additive regulations, EFSA novel food assessments, and China's SAMR GB standards impose divergent purity thresholds that segment crystallization output into distinct certification tracks.
- Granulated:Coarse crystalline structure with controlled particle size distribution dominates food manufacturing applications. Bakery and confectionery formulators in Germany, Japan, and the United States specify this grade for texture-critical applications where dissolution kinetics must match sucrose replacement ratios. Established volume favors Granulated; emerging adoption favors Liquid.
- Powdered:Micronized particle engineering enables rapid hydration in instant beverage mixes and pharmaceutical powder blends. The fine grade commands premium positioning in orodispersible tablet formulations where Japan's PMDA fast-track designations accelerate geriatric dosage form approvals. Powdered xylitol expands most quickly in direct compression tableting.
- Liquid:Aqueous concentrates serve pharmaceutical oral solutions and personal care humectants where solubility control eliminates crystallization handling. Pediatric syrup manufacturers leverage liquid xylitol for its low-glycemic excipient properties in diabetic-friendly formulations.
- Chewing Gum:Pre-formulated resin-compatible grades integrate directly with gum base manufacturing, incorporating dental association-endorsed cariostatic claims into finished consumer products.
Granular specifications anchor industrial procurement; liquid and powder grades capture formulation flexibility premiums.
End User:
Application-specific purity requirements create margin stratification, with pharmaceutical and oral care segments commanding certification premiums over commodity food channels.
- Food & Beverage:Diabetic-friendly confectionery, bakery, and beverage applications drive volume consumption. EFSA novel food assessments streamline European market entry for reformulated products replacing sucrose and sorbitol.
- Pharmaceuticals:Low-glycemic excipient demand concentrates in pediatric syrups, chewable tablets, and geriatric orodispersible films. Japan's METI aging-population initiatives and PMDA regulatory tailwinds accelerate xylitol's displacement of sorbitol in dosage forms for diabetic and pediatric populations.
- Cosmetics:Humectant applications in skincare and personal care formulations leverage xylitol's hygroscopic stability and skin-conditioning properties.
- Oral Care:Therapeutic toothpaste and mouthwash formulations lead absolute consumption, with Germany's BZÄK, Japan's JDA, and the American Dental Association actively promoting cariostatic properties. Prescription-grade demand in therapeutic oral care products sustains premium positioning.
Oral care maintains volume leadership; pharmaceutical applications climb the fastest on regulatory tailwinds for geriatric and pediatric formulations.
Distribution Channel:
Hospital procurement consolidation and direct-to-pharmacy contracting are restructuring traditional wholesale intermediation.
- Online Retail:Direct-to-consumer channels expand for dental-protective chewing gums and diabetic-friendly confectionery, bypassing traditional retail markups.
- Supermarkets:Mass-market sweetener and oral care product placement reaches household consumers through conventional grocery retail infrastructure.
- Health Stores:Specialty retailers target diabetic nutrition and natural products consumers with premium-positioned xylitol formulations.
- Specialty Shops:Compounding pharmacies and dental professional channels supply prescription-grade therapeutic oral care products with purity certifications.
Supermarkets anchor consumer volume; specialty and online channels gain share fastest on procurement decentralization.
Application:
Functional performance requirements differentiate specification grades across sweetening, moisture management, and sensory enhancement roles.
- Sweetener:Primary caloric reduction applications in beverages and confectionery compete with erythritol substitution pressure in zero-calorie formulations.
- Sugar Substitute:Direct sucrose replacement in diabetic-friendly and dental-protective products leverages negligible glycemic impact and cooling sensory profile.
- Humectant:Moisture retention in pharmaceuticals and cosmetics requires liquid concentrates and powdered grades with controlled hygroscopic behavior.
- Flavoring Agent:Cooling effect enhancement in mint-flavored oral care and confectionery applications differentiates sensory performance from alternative polyols.
Sweetener applications dominate tonnage; humectant and sugar substitute roles capture margin expansion on pharmaceutical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xylitol trade flows reflect divergent feedstock endowments and regulatory stringency, with surplus production in corn-processing zones offsetting deficits in hardwood-dependent markets. Import dependence concentrates in jurisdictions where dental-association endorsements outpace domestic crystallization capacity.
United States
Pediatric syrup formulators and therapeutic oral care manufacturers drive prescription-grade consumption. FDA food additive regulations maintain purity thresholds that favor established hydrogenation operators. Iowa and Illinois corn wet-milling clusters anchor North American supply, with drought conditions periodically compressing export availability.
Germany
The BZÄK dental association actively promotes cariostatic properties in professional channels. REACH compliance and F-Gas Regulation linkages condition biobased process certifications for fermentation assets. Chemical parks in North Rhine-Westphalia consolidate production with shared energy infrastructure to distribute environmental compliance costs.
China
Pharmaceutical excipient demand accelerates as NMPA and SAMR GB standards tighten heavy metal thresholds for sugar alcohol imports. Zhejiang province crystallization operators compete on scale, though smaller facilities face disqualification from cross-border supply. Agricultural residue processing from wheat straw diversifies xylose supply beyond hardwood dependency.
Japan
METI aging-population initiatives and PMDA fast-track designations accelerate geriatric dosage form approvals for xylitol-based orodispersible films. The JDA endorses cariostatic properties in therapeutic oral care prescriptions. Kanto and Kansai industrial corridors concentrate formulation expertise among aging process engineering cohorts.
India
Diabetic-friendly confectionery and pharmaceutical excipient applications expand as domestic formulators seek low-glycemic alternatives. CDSCO and FSSAI frameworks govern import clearance for sugar alcohols, with BIS standards emerging for local production. Maharashtra and Gujarat pharmaceutical clusters drive compounding pharmacy demand.
Xylitol Market Vendor Landscape
Concentration sits with integrated agribusiness conglomerates and regional crystallization specialists, creating a tiered structure where feedstock access determines margin sustainability. Wet-milling operators leverage captive corn supply chains, while hardwood and agricultural residue processors compete on purity-grade specialization. Strategic moves center on fermentation route scale-up and direct-to-pharmacy distribution bypasses of wholesale intermediaries.
Among integrated agribusiness operators, Cargill, Incorporated and Roquette Frères exemplify the feedstock-anchored archetype, with geographic positioning in North American corn belts and European pea-wheat starch diversification respectively. Zhejiang Huakang Pharmaceutical Co., Ltd. occupies a position within the crystallization-scale tier, representing Chinese provincial production concentration. These three entities anchor the competitive map without exhausting its diversity.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Roquette Frères |
| DuPont de Nemours, Inc. |
| Ingredion Incorporated |
| Zhejiang Huakang Pharmaceutical Co., Ltd. |
| Shandong Futaste Co., Ltd. |
| Archer Daniels Midland Company |
| Shandong Longlive Bio-Technology Co., Ltd. |
| ZuChem, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day crystallization lead times for pharmaceutical-grade xylitol concentrate bargaining power among Zhejiang province operators, while corn wet-milling economies in Iowa and Illinois anchor standard-grade spot pricing through captive feedstock integration.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical excipients and standard food-grade crystalline product runs wide. Three-tier pricing structure across prescription-grade, food-additive, and industrial feedstock levels segments buyers by certification burden, with FDA and EFSA purity tiers commanding substantial premia over SAMR GB baseline compliance. Cost compression in standard granulated grades is intensifying because erythritol substitution in beverage applications erodes volume commitments. Hospital procurement consortia exhibit lowest price sensitivity through multi-year formulary contracts, while commodity confectionery manufacturers negotiate aggressively on spot volumes.
Supply Chain Analysis
Corn belt harvest volatility constitutes the dominant chokepoint, with drought conditions in Iowa and Illinois propagating feedstock scarcity through North American hydrogenation networks. Supply concentrates in the United States, China, and Germany, with xylose extraction drawing from hardwood hemicellulose, corn stover, and wheat straw in shifting proportions. Single-source vulnerability concentrates in Zhejiang crystallization corridors where NMPA purity escalations disqualify sub-scale operators. Distribution runs through hospital GPOs and pharmaceutical wholesaler networks for premium grades, while food-grade volumes flow via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xylitol's excipient standardization around pharmacopeial monographs is creating platform-economics dynamics, with interoperability across USP-NF, EP, and ChP compendia enabling formulation portability that rewards scale and certification depth.
For Market Incumbents: Shield margin pools in pediatric and geriatric dosage forms by deepening backward integration into cellulosic feedstock preprocessing. Secure fermentation route capacity with carbon capture utilization positioning ahead of EU Green Deal biobased chemical classifications. Erythritol substitution in zero-calorie beverages demands defensive certification investment in dental-association endorsed therapeutic oral care channels where switching costs are highest. For New Entrants and Emerging Players: Differentiate on agricultural residue xylose extraction from wheat straw and corn stover, bypassing hardwood harvest cycle dependencies that constrain incumbent seasonal planning. India's Maharashtra and Gujarat pharmaceutical clusters present the most penetrable geography, with CDSCO and FSSAI frameworks still stabilizing for sugar alcohol API classification. Direct-to-pharmacy distribution bypassing traditional wholesale markups offers the clearest go-to-market angle for compounding pharmacy and hospital formulary access. For Investors and Strategic Acquirers: Long-term, this sits as a biobased platform chemistry play because fermentation route convergence with carbon capture utilization creates durable green premium positioning under evolving EU regulatory frameworks. Acquisition targets should concentrate on crystallization-scale specialists with demonstrated polymorphism control and existing multi-jurisdiction certification dossiers. The signal to watch is PMDA fast-track designation velocity for geriatric orodispersible films, which would confirm structural expansion beyond oral care into high-margin pharmaceutical excipient substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulosic Feedstock | Corn stover and wheat straw preprocessing secures xylose supply independent of hardwood harvest cycles. |
| Fermentation Route Scale-Up with CCU | Yeast-based bioconversion with carbon capture utilization qualifies output under EU Green Deal classifications. |
| Direct-to-Pharmacy Distribution | Bypassing wholesale intermediaries captures margin previously allocated to distributor networks in hospital formulary channels. |
| Multi-Jurisdiction Certification Investment | Parallel FDA, EFSA, and NMPA dossiers extend product launch cycles but lock out sub-scale competitors. |
| Geriatric Dosage Form Partnership | PMDA fast-track collaborations for orodispersible films accelerate displacement of sorbitol in aging-population formulations. |
Methodological Framework
Cross-validation between primary interviews with pharmaceutical formulators, crystallization process engineers, and hospital procurement managers and secondary validation through FDA food additive petitions, EFSA novel food assessments, and NMPA excipient filings anchors the qualitative findings. Customs and trade data from corn belt and Zhejiang export corridors, SEC 10-K disclosures from integrated agribusiness operators, and SAMR GB standard evolution records provide volume and pricing triangulation. Bottom-up crystallization capacity modeling and top-down end-use consumption estimates converge through iterative reconciliation.
Sensitivity analysis across feedstock price bands, purity threshold escalations, and substitution elasticity parameters tests forecast robustness throughout the projection horizon. Segmentation dimensions span product grade tier, end-use application, distribution channel structure, and regional regulatory cluster, with CAGRs derived from fitted growth curves against historical excipient adoption patterns. Xylose supply diversification rates and dental association endorsement velocity constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained pharmacopeial harmonization and stable corn wet-milling economics would require recalibration. Forecasts reflect documented assumptions regarding erythritol substitution limits and fermentation route yield improvements. Practitioners should keep alternative scenarios live as China's SAMR GB heavy metal thresholds and EU F-Gas Regulation scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Glucose Syrup Market
Sweeteners
Stevia Market
Sweeteners
Methyl Glucose Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Maltodextrin Market
Sweeteners
Icing Sugar Market
Sweeteners
Turbinado Sugar Market
Sweeteners
France Food Sweetener Market
Sweeteners
United States Xylitol Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Natural Sweeteners Market
Sweeteners
Sugar Syrups Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Liquid Sugar Market
Sweeteners
Specialty Sweeteners Market
Sweeteners
Natural Sweetener Blends Market