
 Turbinado Sugar Market | 2026-2036
Turbinado Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Turbinado Sugar Market Outlook
The gap between premium organic turbinado and commodity-grade raw sugar is realigning procurement patterns across North American food manufacturing. ASR Group leverages its integrated cane supply from Florida and Louisiana to sustain volume leadership in conventional channels. Florida Crystals differentiates through certified organic cultivation and renewable energy-powered milling, while Wholesome Sweeteners occupies the fair-trade and non-GMO premium tier with strong specialty store distribution.
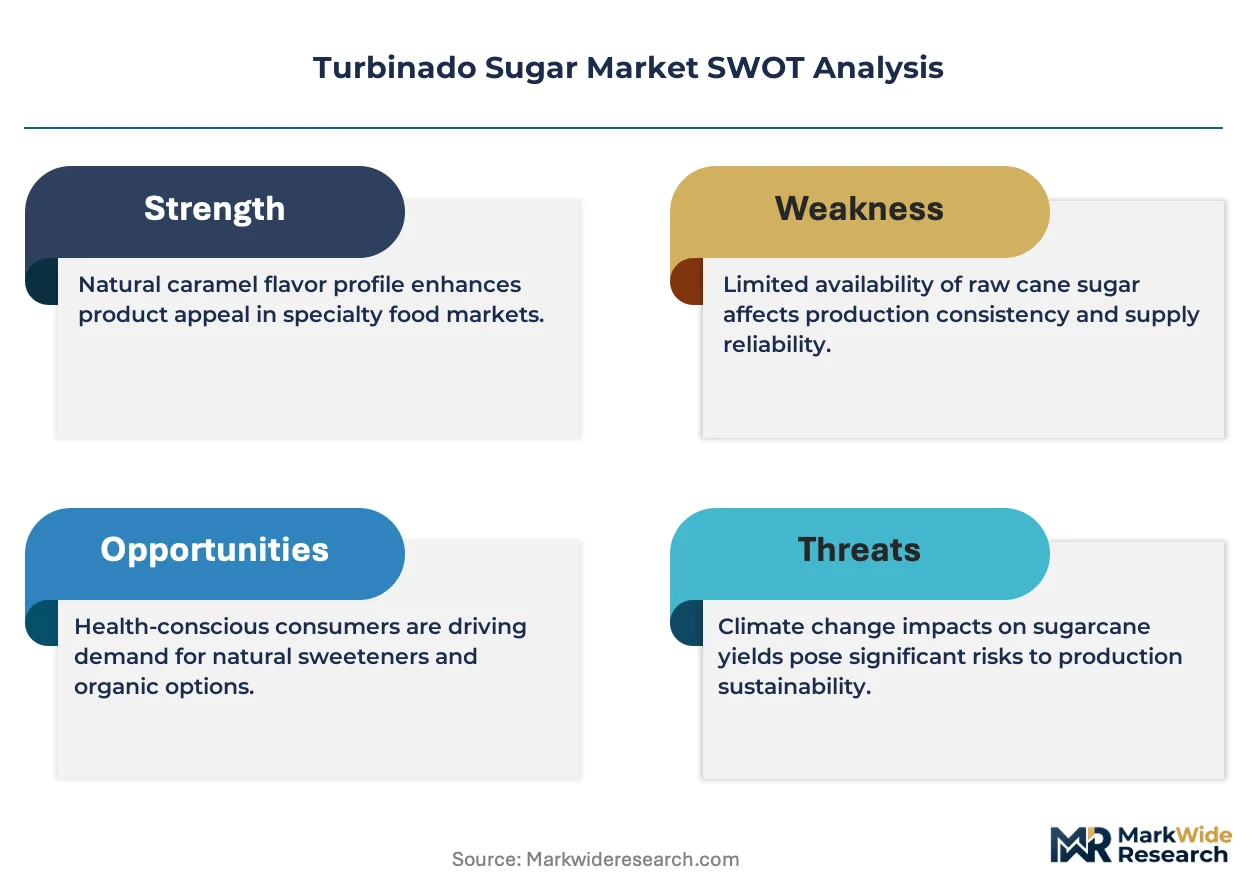
Turbinado sugar retains natural molasses content through a single-crystallization process, yielding golden crystals with moisture levels around 3.5 percent and a light caramel flavor profile prized by artisan bakers and beverage formulators. Organic Turbinado commands the fastest expansion within product type classifications as clean-label mandates from food manufacturers intensify ingredient scrutiny. The Beverages application segment leads volume contribution, though Confections anchors higher margin pools due to smaller batch requirements and premium positioning.
The FDA's added sugars labeling requirements and USDA organic certification standards shape formulation transparency and market access across domestic supply chains. State-level sugar excise proposals in California and Washington add compliance complexity for distributors serving West Coast retail networks. Stakeholders must monitor evolving sweetener taxation frameworks and organic acreage expansion rates to calibrate sourcing strategies.
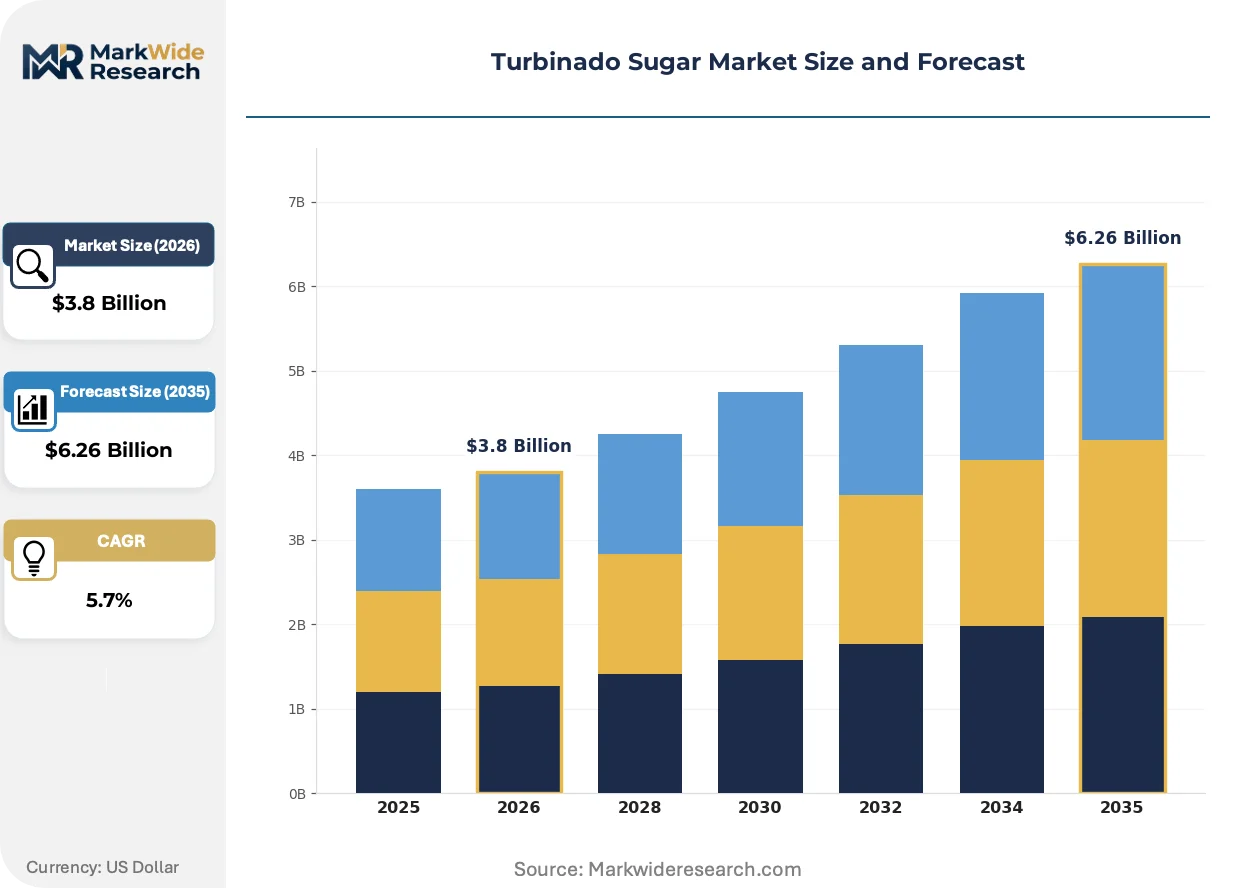
Market Dynamics
The FDA's added sugars disclosure mandate and USDA organic certification requirements are compressing formulation timelines while fragmenting supplier qualification criteria across North American food manufacturing networks.
Growth Catalysts
- Clean-Label Procurement Mandates:Beverage formulators in California's Bay Area and Pacific Northwest metropolitan corridors are specifying single-crystallization sweeteners to meet retailer transparency scorecards.
- USDA Organic Certification Standards:Food manufacturers seeking non-GMO verification are driving acreage conversion toward certified organic cane cultivation.
- Specialty Coffee Roaster Expansion:Artisanal roasting clusters in Portland and Seattle are building direct procurement relationships with minimally processed sugar suppliers.
Market Restraints
- Input Cost Volatility:Raw cane supply fluctuations from Florida and Louisiana growing regions create margin pressure for conventional-grade processors.
- Substitution Threat:Coconut sugar and date syrup are capturing shelf space in natural grocery channels targeting the same clean-label consumer segment.
- Regulatory Friction:California and Washington state sugar excise proposals add compliance layers for distributors serving West Coast retail networks.
Strategic Opportunities
- Underpenetrated Foodservice Channel:Independent restaurant groups and boutique hotel chains represent untapped volume for fair-trade certified turbinado.
- Regulatory Tailwind:The FDA's updated Nutrition Facts label requirements create formulation windows for suppliers offering transparent molasses-content specifications.
- Technology Convergence:Renewable energy-powered milling combined with blockchain traceability is enabling premium positioning for carbon-conscious buyers.
Industry Challenges
- Certification Timeline Compression:Organic and fair-trade accreditation cycles are extending lead times for new supplier onboarding.
- Capex Intensity for Traceability:Blockchain and IoT infrastructure investments are required to meet emerging retailer transparency mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbinado Sugar Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Turbinado, Raw Turbinado, Brown Sugar, White Sugar Application: Baking, Beverages, Sauces, Confections End User: Food Manufacturers, Restaurants, Retailers, Households Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | ASR Group, Wholesome Sweeteners, Florida Crystals, Tate & Lyle, Cumberland Packing, Domino Sugar, Bob’s Red Mill Natural Foods, Tereos, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbinado Sugar Market Strategic Shifts
Single-crystallization processing advances and renewable energy integration are redefining competitive differentiation in minimally processed sweetener supply chains.
Mechanical vapor recompression evaporation systems are rewriting energy economics for cane sugar mills. Specialty ingredient distributors in the Pacific Northwest are specifying these systems in supplier qualification audits. The technology is compressing operating cost structures for organic-certified processors while raising barriers for conventional competitors.
REACH chemical safety protocols and the EU Green Deal sustainability frameworks are reshaping import requirements for North American sweetener exporters. European confectionery manufacturers are demanding comprehensive carbon footprint documentation. The Beverages segment is responding by consolidating procurement around suppliers with verified renewable energy credentials.
Direct-to-manufacturer contracting is displacing traditional commodity broker networks in specialty sweetener sourcing. Artisanal bakeries and small-batch confectioners are building captive supply relationships with certified organic mills. This pattern is most visible in California's Central Valley where food manufacturing clusters are co-locating near cane processing facilities.
Turbinado Sugar Market Segmentation
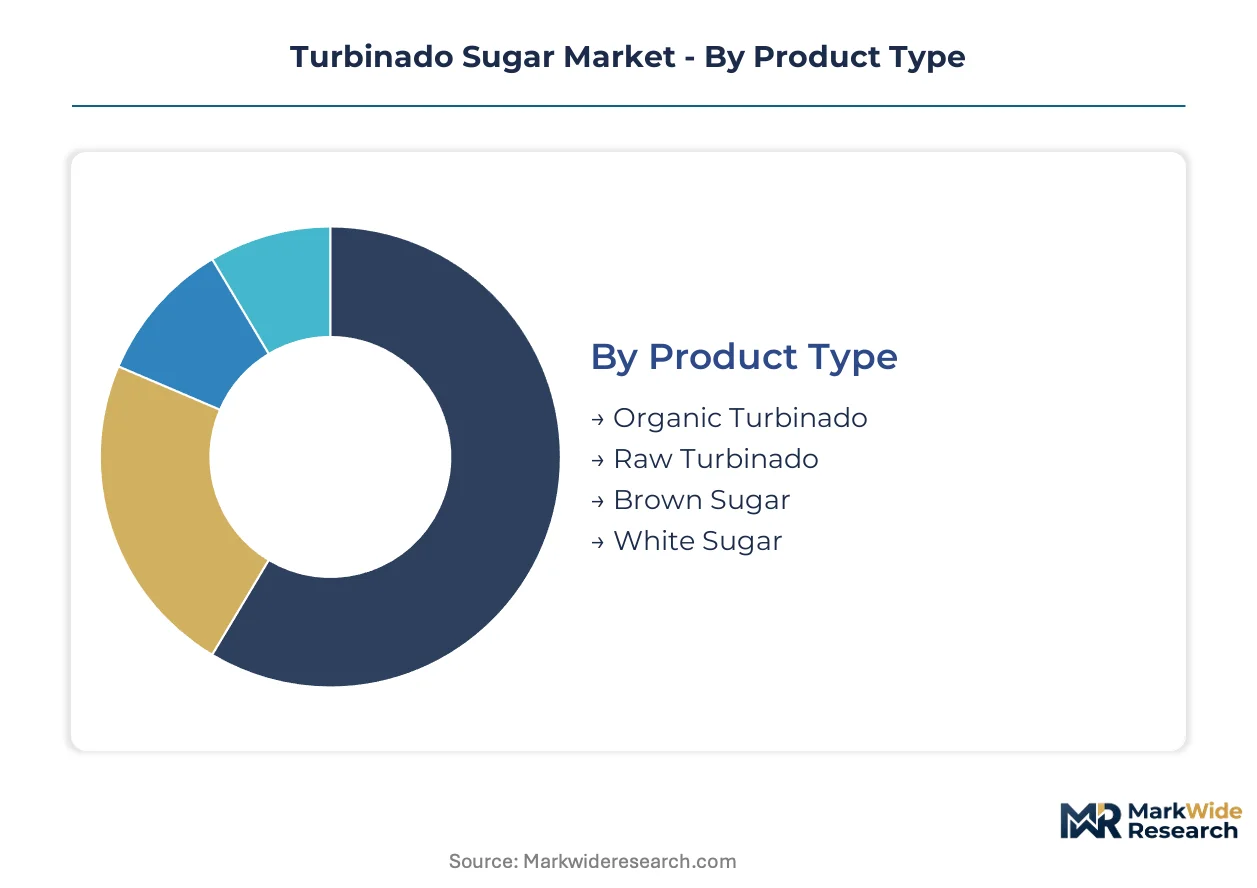
Turbinado sugar procurement patterns diverge sharply across certification grades and end-use specifications. Understanding these segment boundaries clarifies where margin pools concentrate and which qualification standards govern supplier selection.
Product Type:
Single-crystallization processing and molasses retention levels define the technical hierarchy across sweetener grades.
- Organic Turbinado:Certified cane cultivation meets USDA organic standards with non-GMO verification and restricted pesticide protocols. Bay Area beverage formulators and Pacific Northwest coffee roasters specify this grade for clean-label compliance, though acreage conversion timelines constrain supply expansion.
- Raw Turbinado:Minimally processed crystals retain natural molasses content through single-crystallization, yielding golden color and light caramel notes. Artisanal bakeries in California's Central Valley cluster procurement around this specification for texture and flavor control in small-batch production.
- Brown Sugar:Molasses reintroduction creates darker crystals with higher moisture content, serving cost-sensitive baking applications where color intensity outweighs processing transparency requirements.
- White Sugar:Full refining strips residual molasses, positioning this grade outside turbinado's core definition but competing for share in price-driven food manufacturing formulations.
Raw Turbinado leads on scale; Organic Turbinado leads on momentum.
Application:
End-use viscosity requirements and thermal stability demands shape formulation-grade specifications.
- Beverages:Dissolution kinetics and clarity standards govern selection for specialty coffee, craft cocktails, and premium soft drinks. Portland and Seattle roasting clusters drive specification tightening through direct mill relationships.
- Confections:Crystal size distribution and moisture control determine performance in chocolate tempering and caramel production. Smaller batch requirements sustain premium positioning despite lower absolute volumes.
- Baking:Creaming behavior and browning reactions guide procurement for artisanal bread and pastry applications where moisture content affects gluten development.
- Sauces:Viscosity contribution and shelf-stability requirements define performance in barbecue and specialty condiment manufacturing.
Beverages anchor volume contribution; Confections capture margin concentration.
End User:
Scale economies and certification stringency create distinct procurement operating models across buyer categories.
- Food Manufacturers:Volume contracting and multi-site qualification requirements favor suppliers with integrated cane supply and renewable energy-powered milling infrastructure.
- Restaurants:Independent restaurant groups and boutique hotel chains represent fragmented demand with emerging interest in fair-trade certification for menu storytelling.
- Retailers:Transparency scorecards and private-label development programs drive consolidation around suppliers with blockchain traceability capabilities.
- Households:Direct-to-consumer channels and specialty store placement respond to packaging size preferences and organic certification visibility.
Food Manufacturers dominate procurement scale; Restaurants show steepest expansion trajectory.
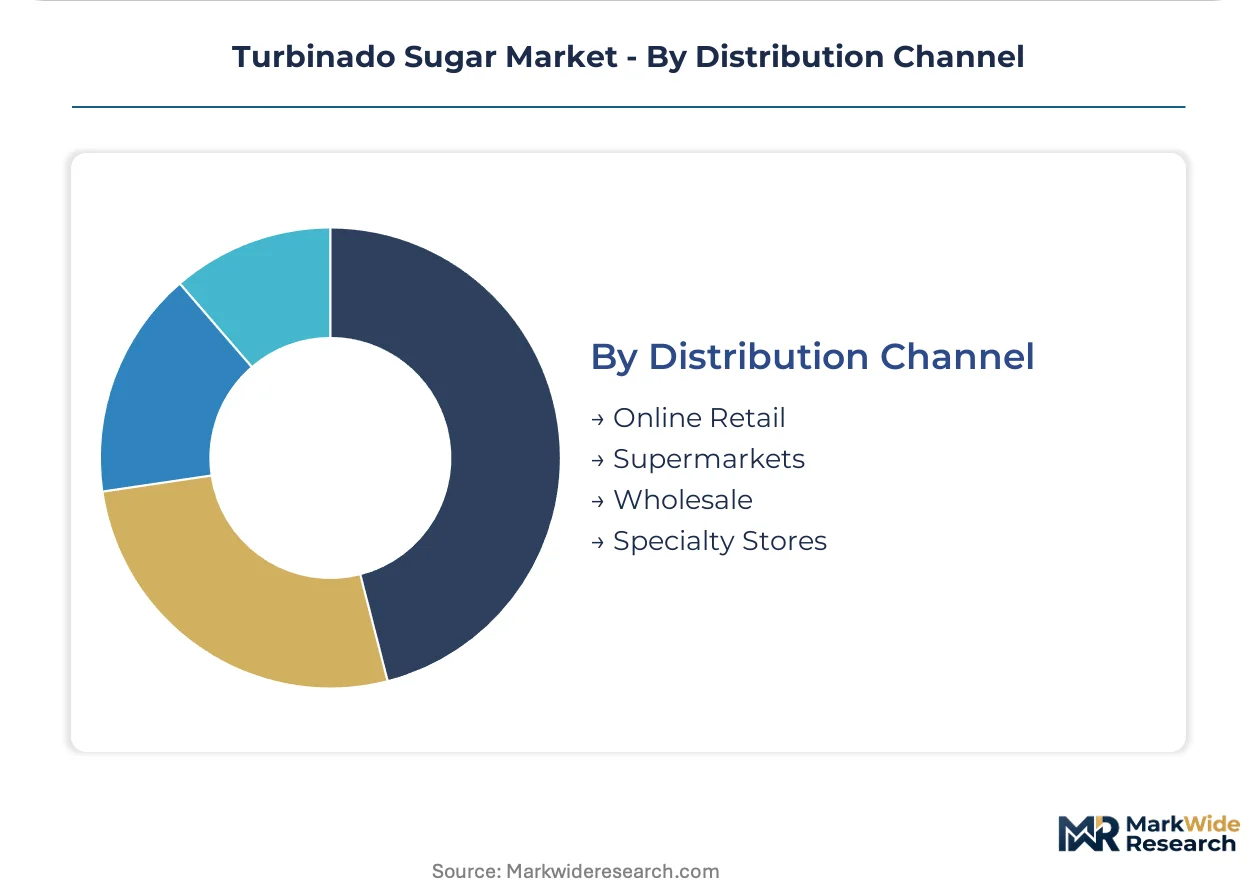
Distribution Channel:
Channel selection determines certification visibility and price realization for turbinado suppliers.
- Specialty Stores:Premium placement and educated consumer base support fair-trade and organic price premiums through focused merchandising.
- Supermarkets:Mainstream shelf access requires compliance with retailer transparency mandates and slotting fee structures that favor volume suppliers.
- Online Retail:Direct-to-manufacturer and direct-to-consumer platforms enable bypass of traditional broker networks, compressing margin extraction by intermediaries.
- Wholesale:Foodservice and industrial volumes move through distributor relationships where state-level sugar excise compliance adds operational complexity for West Coast networks.
Supermarkets maintain volume leadership; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty food manufacturing talent clusters in California's Bay Area and the Pacific Northwest anchor North American turbinado procurement, while cane cultivation expertise concentrates in Florida and Louisiana growing regions.
United States
Artisanal bakeries in California's Central Valley and specialty coffee roasters in Portland and Seattle drive organic turbinado specification. The FDA's added sugars disclosure mandate under updated Nutrition Facts label requirements compresses formulation timelines for beverage manufacturers. Clean-label food manufacturing corridors in the Bay Area are co-locating near cane processing facilities to secure transparent supply chains.
Brazil
Organic cane acreage expansion in São Paulo state supplies North American premium-tier demand with non-GMO verification. The country's national agricultural regulator enforces pesticide restriction protocols aligned with USDA organic equivalency agreements. São Paulo-based milling clusters are integrating mechanical vapor recompression systems to meet Pacific Northwest distributor sustainability audits.
India
Specialty sweetener exporters in Maharashtra and Gujarat are targeting fair-trade certification for European confectionery manufacturers. FSSAI food safety standards and organic certification protocols govern export-grade processing facility approvals. Mumbai-Pune industrial corridors are developing blockchain traceability infrastructure to satisfy retailer transparency scorecards in California markets.
Germany
REACH chemical safety protocols and EU Green Deal sustainability frameworks are reshaping import requirements for North American turbinado exporters. EFSA sweetener classification standards influence formulation decisions across European beverage and confectionery manufacturing. Hamburg and Bremen port logistics clusters are consolidating procurement around suppliers with verified renewable energy credentials and comprehensive carbon footprint documentation.
Canada
Health Canada food labeling regulations and organic equivalency arrangements with the USDA facilitate cross-border specialty sweetener trade. Ontario and Quebec food manufacturing clusters are specifying single-crystallization sweeteners for clean-label product development. Toronto-area natural grocery distributors are building direct relationships with certified organic mills to bypass traditional commodity broker networks.
Turbinado Sugar Market Competitive Environment
Top-tier vendors anchor integrated cane supply and renewable energy-powered milling infrastructure, while mid-tier specialists occupy fair-trade and non-GMO certification niches. The vendor base stratifies across three archetypes: volume-scale processors with captive agricultural operations, premium-tier organic specialists with direct-to-roaster distribution, and diversified ingredient conglomerates with multi-sweetener portfolios. Competitive moves concentrate on backward integration into cane cultivation and blockchain-enabled traceability investments that satisfy retailer transparency mandates.
Within the integrated supply archetype, ASR Group and Florida Crystals exemplify contrasting approaches to North American market positioning. ASR Group leverages its Florida and Louisiana cane supply base to sustain volume leadership in conventional distribution channels. Florida Crystals occupies the certified organic cultivation tier with renewable energy-powered milling differentiation. Wholesome Sweeteners represents the fair-trade and non-GMO premium specialist model, anchoring specialty store distribution networks that command price premiums through focused merchandising and clean-label storytelling.
| Leading Market Players |
|---|
| ASR Group |
| Wholesome Sweeteners |
| Florida Crystals |
| Tate & Lyle |
| Cumberland Packing |
| Domino Sugar |
| Bob's Red Mill Natural Foods |
| Tereos |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Clean-label procurement mandates from Bay Area beverage formulators are forcing supply chain reconfiguration toward certified organic mills, compressing price premiums for conventional-grade processors while elevating organic tier valuations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs turbinado procurement. Price differentiation rests on USDA organic certification and fair-trade accreditation as primary drivers. Cost compression in conventional channels is intensifying because raw cane supply fluctuations from Florida and Louisiana create margin pressure. Food manufacturers show highest price sensitivity, while specialty coffee roasters absorb premiums for traceability.
Supply Chain Analysis
Regional distribution centers in California's Central Valley and Pacific Northwest metropolitan corridors anchor hub-and-spoke patterns for specialty sweetener distribution. Supply concentrates in Florida, Louisiana, and São Paulo state for cane cultivation, with mechanical vapor recompression systems becoming a qualification threshold. Raw material dependencies include cane supply, molasses retention specifications, and renewable energy inputs. Single-source vulnerability from hurricane-exposed Florida growing regions threatens supply continuity. Distribution runs through specialty ingredient distributors and direct-to-manufacturer contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turbinado sugar market functions as a stable compounder, with clean-label regulatory mandates driving steady procurement growth across North American food manufacturing networks.
For Market Incumbents: Deploy blockchain traceability infrastructure to defend shelf position against coconut sugar and date syrup substitutes. Deepen upstream control over certified organic cane acreage in Florida and Louisiana to secure volume leadership. Invest in mechanical vapor recompression systems to meet Pacific Northwest distributor sustainability audits and sustain premium tier access. For New Entrants and Emerging Players: Renewable energy-powered milling with carbon footprint documentation offers a technology-first wedge into fair-trade certification gaps. Target independent restaurant groups and boutique hotel chains as underpenetrated foodservice volume. Build direct procurement relationships with Portland and Seattle roasting clusters to bypass established broker networks. For Investors and Strategic Acquirers: Asymmetric upside sits with organic-certified processors with integrated cane supply and renewable energy infrastructure. Long-term viability centers on suppliers positioned for FDA transparency mandates and state-level sugar excise compliance. Monitor organic acreage conversion rates in Florida and São Paulo as the critical inflection signal for supply-constrained premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cane Cultivation | Captures margin pool from acreage conversion timelines constraining premium supply expansion. |
| Blockchain Traceability Implementation | Satisfies retailer transparency scorecards from Bay Area clean-label manufacturing clusters. |
| Renewable Energy-Powered Milling | Qualifies suppliers for Pacific Northwest distributor sustainability audits and carbon-conscious buyers. |
| Direct-to-Manufacturer Contracting | Bypasses traditional commodity broker networks in specialty sweetener sourcing channels. |
| Fair-Trade Certification Investment | Unlocks price premiums through specialty store placement and menu storytelling for restaurants. |
Study Parameters
Coverage spans North America, Brazil, and India, with primary inputs from each region combining interviews with cane mill operations managers, specialty ingredient procurement leads at beverage formulators, organic certification auditors, and foodservice distribution channel partners. Secondary validation draws from USDA organic certification databases, FDA food labeling guidance documents, customs trade records, and SEC filings from publicly traded sweetener processors. Bottom-up volume modeling and top-down market sizing triangulate demand estimates.
Granularity-level modeling applies across product type, application, end user, and distribution channel dimensions, with renewable energy credential status as an additional industry-specific qualifier. CAGRs derive from segment-level growth rate reconciliation against macro sweetener consumption trends. Forecast inputs include organic acreage expansion projections, state-level sugar excise proposal tracking, and clean-label procurement mandate adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to organic certification timeline compression and substitution threat acceleration from alternative sweeteners. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Allulose Market
Sweeteners
Palm Sugar Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Sanding Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Japan Allulose Market
Sweeteners
South America Stevia Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
South Korea Allulose Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
France Food Sweetener Market
Sweeteners
Asia Pacific Food Sweetener Market