
 Oligofructose Market | 2026-2036
Oligofructose Market Size, Share, and Industry Trends Forecast 2026-2036
Oligofructose Market Intelligence
Demand from large-scale food and beverage producers versus specialized nutraceutical companies is bifurcating the oligofructose market. Beneo specializes in scientifically-backed prebiotic ingredients for the high-margin nutraceutical space. In contrast, Cargill leverages its extensive manufacturing and distribution network to supply bulk oligofructose to major food conglomerates. Tate & Lyle differentiates through its focus on sugar replacement applications within the beverage industry.
Oligofructose is a short-chain fructan produced through the partial enzymatic hydrolysis of inulin, typically extracted from chicory root. It functions as a low-calorie, soluble prebiotic fiber used for sugar reduction and improving gut microbiota. The powder form dominates due to its stability and ease of integration into dry mixes for functional foods and dietary supplements. Liquid syrups represent a fast-growing segment, particularly for applications in beverages and infant nutrition formulas where precise dosing is critical.
Regulatory frameworks from the U.S. FDA and the European Food Safety Authority (EFSA) govern the classification of oligofructose as a dietary fiber and approve associated health claims. In China, the NMPA's standards for infant formula ingredients also influence sourcing and quality requirements. Navigating these divergent international regulations for prebiotic health claims remains a central strategic challenge for manufacturers.
Market Dynamics
The oligofructose market is defined by the tension between its application as a bulk sugar-replacement commodity and its role as a high-value, scientifically-validated prebiotic. This duality creates divergent pricing, supply chain, and regulatory strategies for manufacturers targeting either the mass food industry or the specialized nutraceutical sector.
Growth Catalysts
- Regulatory Endorsements:The European Food Safety Authority's (EFSA) approval of health claims related to prebiotic fibers and gut health provides a significant catalyst, enabling manufacturers to market products with scientifically-backed benefits.
- Infant Nutrition Demand:The infant formula industry's focus on creating products that mimic the composition of human milk drives demand for oligofructose as a key prebiotic ingredient to support infant gut microbiome development.
- Consumer Health Focus in China:Strong consumer awareness and proactive spending on digestive health in China are accelerating the adoption of functional foods and supplements containing oligofructose, making it a primary growth geography.
Market Restraints
- Raw Material Volatility:The market is highly dependent on chicory root as the primary source for inulin hydrolysis, making oligofructose prices susceptible to agricultural yields, weather patterns, and crop diseases affecting chicory supply.
- Substitution from Other Fibers:Oligofructose faces direct competition from other functional fibers like inulin, fructooligosaccharides (FOS), and galactooligosaccharides (GOS), which offer similar prebiotic and sugar-reduction benefits in many applications.
- Dosage and Tolerance Limits:The potential for gastrointestinal side effects, such as bloating and gas at higher intake levels, restricts the maximum inclusion rate of oligofructose in certain food and beverage products, limiting its application scope.
Strategic Opportunities
- Personalized Nutrition Platforms:The integration of oligofructose into personalized nutrition services, where formulations are tailored to an individual's unique gut microbiome profile, presents a high-margin opportunity beyond mass-market products.
- Synbiotic Product Development:Combining specific strains of oligofructose with targeted probiotic bacteria to create synbiotic formulations offers enhanced functional benefits, creating a new category of value-added gut health solutions.
- Expansion in Southeast Asia:Markets in countries like Vietnam and Indonesia represent a significant growth frontier, where rising disposable incomes and growing health awareness are creating new demand for functional food ingredients.
Industry Challenges
- Health Claim Substantiation:Navigating the complex and divergent evidentiary requirements of regulatory bodies like the FDA, EFSA, and China's NMPA to validate and approve specific health claims for oligofructose-containing products remains a major hurdle.
- Supply Chain Integrity:Maintaining the stability and functional properties of both powder and liquid oligofructose requires careful management of temperature and humidity across the supply chain to prevent caking, degradation, or microbial contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oligofructose Market |
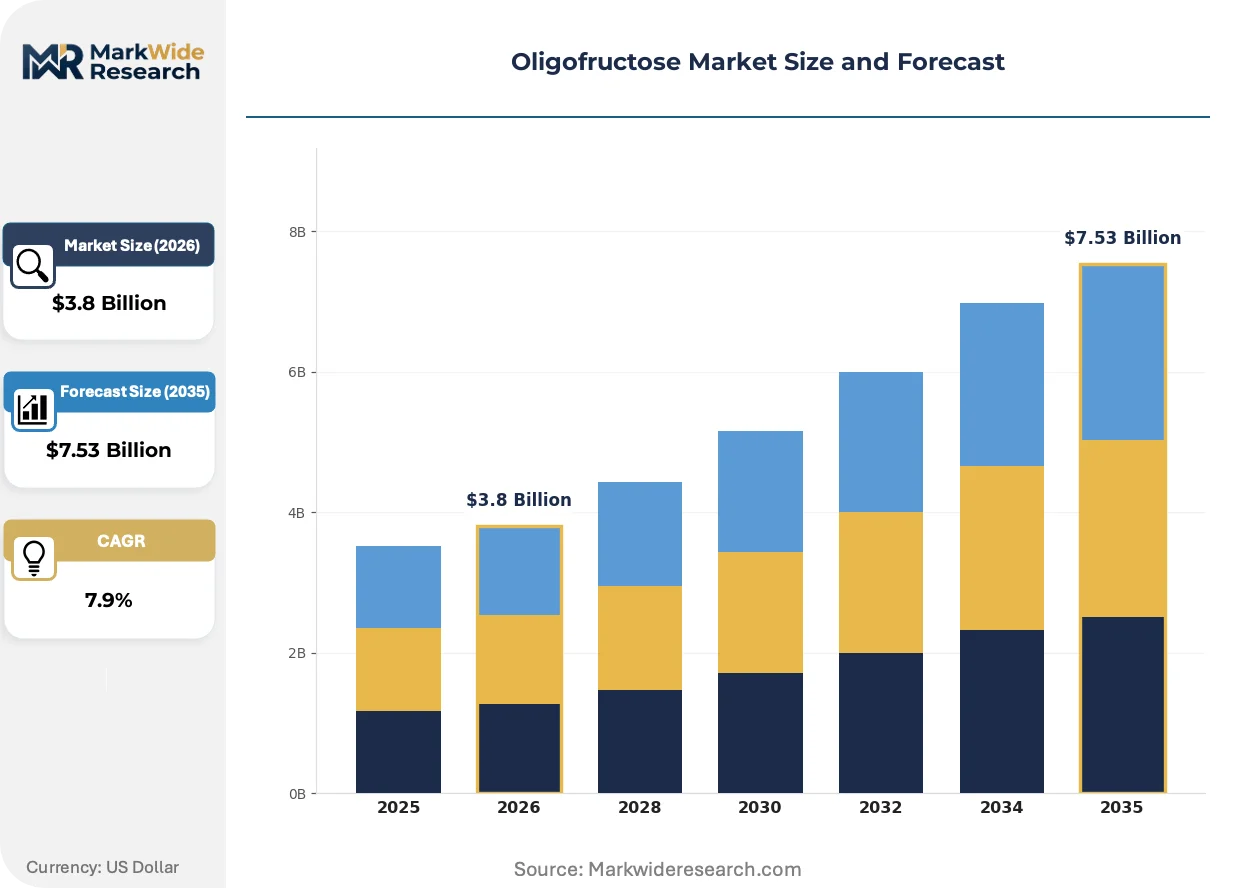
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Syrup, Concentrate Application: Functional Foods, Dietary Supplements, Bakery Products, Beverages, Infant Nutrition End User: Contract Manufacturers, Nutraceutical Companies, Food & Beverage Producers, Pharmaceutical Firms Packaging Type: Bags, Drums, Bottles, Bulk Containers, Sachets |
| Companies Covered | Tereos Group, Meiji Holdings Co., Ltd., Beneo, Tate & Lyle, Baolingbao Biology, Cargill, Incorporated, Galam, Roquette Frères, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oligofructose Market Strategic Shifts & Innovations
Innovation is shifting from optimizing bulk production to refining the molecular structure of oligofructose for targeted physiological outcomes. This evolution is driven by advanced enzymatic processing and a deeper understanding of microbiome science, transforming a commodity ingredient into a portfolio of functional tools.
Advanced enzymatic hydrolysis is the core technology used to produce oligofructose with specific chain lengths from inulin. Nutraceutical and specialized food producers are adopting these tailored grades to achieve precise prebiotic effects, such as stimulating specific beneficial bacteria. This precision processing is decomposing the monolithic view of oligofructose into a spectrum of specialized ingredients, each with distinct physiological properties and price points.
The U.S. FDA’s formal recognition of certain oligofructose types as dietary fiber has significant market implications. This classification allows brands to feature higher fiber content on Nutrition Facts panels, directly appealing to health-conscious consumers. The snack and bakery segments are most affected, rapidly reformulating products to leverage "added fiber" claims for a competitive edge in the crowded wellness space.
A notable behavioral shift is occurring in how food companies source functional ingredients. Procurement decisions are moving beyond cost-per-unit metrics to an evidence-based model that prioritizes clinical data on efficacy and bioavailability. This change empowers R&D and marketing teams over traditional purchasing departments, especially in the European dietary supplement sector where EFSA's stringent rules demand robust scientific backing for all product claims.
Oligofructose Market Segmentation
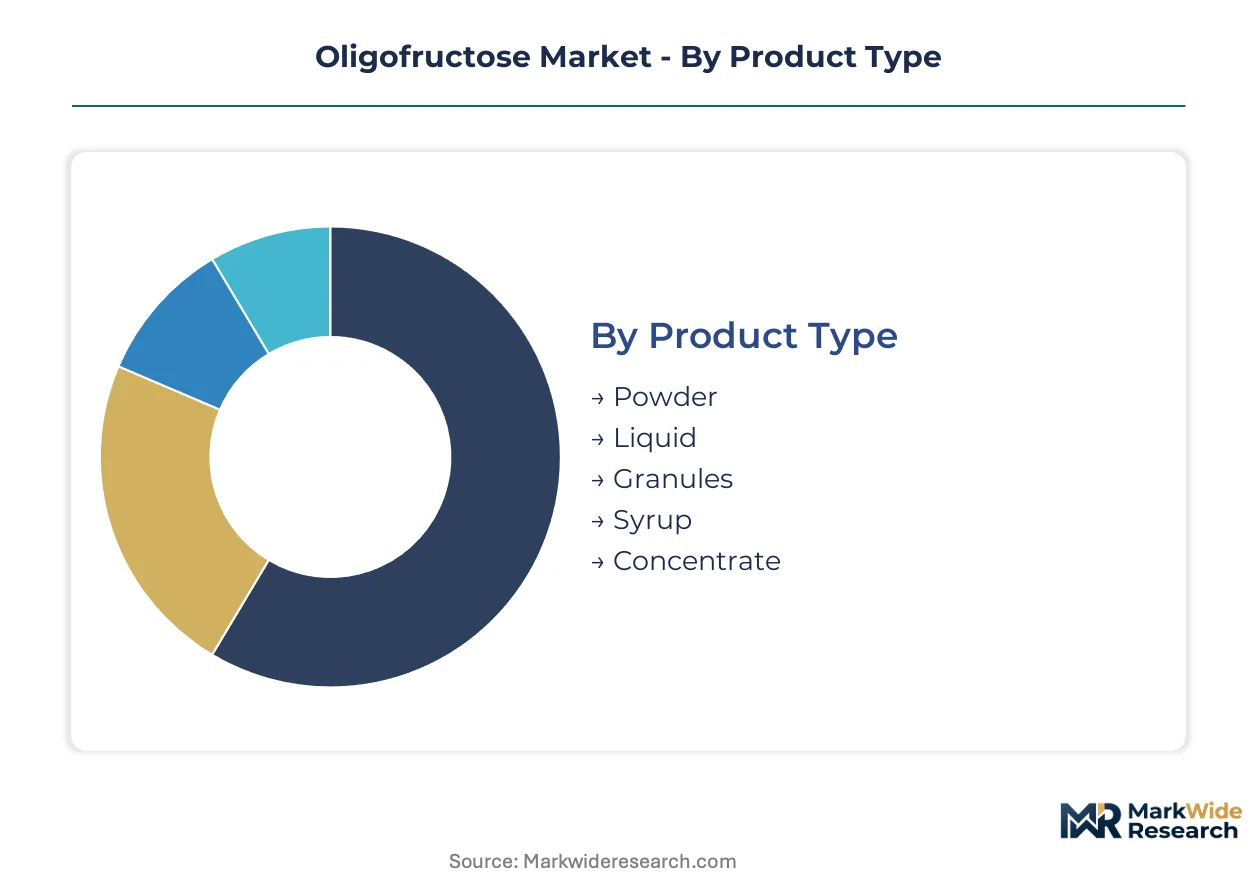
The oligofructose market segments across product forms, application areas, end-user types, and packaging solutions. This segmentation highlights the diverse commercial priorities and strategic considerations for manufacturers and suppliers within the industry.
Product Type:
The product type segmentation differentiates how oligofructose is delivered through various distribution channels to industrial and consumer clients.
- Powder:Dominant form due to stability and ease of integration into dry mixes for functional foods and dietary supplements. Its widespread use in mass-market products and specialized nutraceuticals drives demand across global supply chains.
- Liquid:Growing segment, especially for beverages and infant nutrition formulas, where precise dosing is critical for efficacy and safety. Demand is concentrated in Europe and China due to stringent regulatory standards.
- Granules:Offer improved flowability and reduced dust, beneficial for certain industrial applications and direct consumption supplements.
- Syrup:Used primarily as a functional ingredient in liquid food formulations, providing sweetness and prebiotic benefits.
- Concentrate:High-purity oligofructose form, often employed in specialized dietary supplements and health beverages for maximum efficacy.
By volume, the Powder segment leads. By growth pace, the Liquid segment is ahead.
Application:
The application segmentation highlights diverse end-use priorities for oligofructose across consumer product categories.
- Functional Foods:Represents a primary growth engine, integrating oligofructose into everyday food products for digestive health benefits. Consumer focus on gut health in China and Western markets drives significant demand.
- Infant Nutrition:Critical application where oligofructose mimics human milk oligosaccharides, supporting infant gut microbiome development. NMPA standards in China significantly influence ingredient sourcing for this high-value segment.
- Dietary Supplements:Oligofructose is a key ingredient in capsules, powders, and gummies targeting gut health and fiber intake.
- Bakery Products:Incorporated for sugar reduction and fiber enrichment in items like breads, biscuits, and cereals.
- Beverages:Used in functional drinks, juices, and dairy alternatives to enhance nutritional profiles and provide prebiotic effects.
Infant Nutrition shows the steepest expansion trajectory. Functional Foods represent the largest end-use category by volume.
End User:
End-user categories distinguish between industrial-scale purchasers and specialized formulators of oligofructose.
- Food & Beverage Producers:Represents the largest volume segment, leveraging oligofructose as a bulk ingredient for sugar reduction and fiber enrichment in mass-market products. Cargill's extensive network serves this sector globally.
- Nutraceutical Companies:Focus on high-margin, scientifically-backed formulations, utilizing specialized oligofructose grades for targeted health outcomes. Beneo is a prominent supplier in this segment, emphasizing clinical data.
- Contract Manufacturers:Provide specialized production services for various brands, incorporating oligofructose into client-specific formulations.
- Pharmaceutical Firms:Explore oligofructose for its potential therapeutic applications, particularly in gut-related health conditions and drug delivery systems.
Nutraceutical Companies typically command higher margins. Food & Beverage Producers drive the largest procurement volumes.
Packaging Type:
Packaging type reflects both the scale of procurement and the final consumer delivery method for oligofructose.
- Bulk Containers:Essential for large-scale industrial users, including major food and beverage producers, ensuring cost-effective transport and storage of high volumes. This segment dominates procurement for commodity-grade oligofructose.
- Sachets:Cater to the dietary supplement and personalized nutrition markets, offering precise, single-dose portions for direct consumer use. Demand for sachets is expanding in Southeast Asian health-conscious markets.
- Bags:Common for intermediate-scale industrial clients and smaller food manufacturers requiring manageable quantities.
- Drums:Used for transporting and storing liquid or semi-liquid oligofructose forms to various industrial clients.
- Bottles:Primarily serve the retail consumer market for liquid oligofructose supplements or specialized food additives.
Bulk Containers are critical for supply chain efficiency. Sachets offer enhanced convenience for direct consumer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's significant import demand for functional ingredients drives trade flows from European suppliers. This corridor supports specialized oligofructose grades for infant nutrition and dietary supplements. European manufacturers leverage scientific backing to meet stringent Chinese regulatory requirements.
China
Chinese consumer focus on digestive health and infant formula quality propels oligofructose demand. The NMPA's stringent standards for infant formula ingredients influence sourcing and quality requirements for prebiotics. Shanghai's advanced food processing clusters actively integrate oligofructose into innovative functional food and beverage formulations.
United States
United States demand for fiber enrichment and sugar reduction in snack and bakery products remains strong. The U.S. FDA’s formal recognition of specific oligofructose types as dietary fiber supports product claims. California's innovative food manufacturers reformulate products to leverage these fiber claims for competitive advantage.
Germany
Germany's nutraceutical sector drives demand for scientifically-backed prebiotic ingredients. The European Food Safety Authority's (EFSA) approval of health claims enables manufacturers to market products with validated benefits. The Rhine-Main region's specialized ingredient firms develop tailored oligofructose grades for precise physiological outcomes.
Vietnam
Rising disposable incomes and health awareness in Vietnam create new demand for functional food ingredients. Vietnam's national food safety regulations guide the incorporation of novel prebiotics into consumer products. Ho Chi Minh City's dynamic beverage industry integrates oligofructose into new health drinks and fortified dairy alternatives.
Oligofructose Market Key Industry Players
Player mix skews toward a dual structure, encompassing both large-scale commodity suppliers and specialized ingredient innovators. This bifurcation creates distinct competitive arenas within the oligofructose market, catering to different application needs and customer segments. Archetypes include global food ingredient giants, science-backed nutraceutical firms, and sugar-reduction specialists. Portfolio diversification into synbiotic formulations and strategic partnerships for infant nutrition applications represent key competitive moves for market participants.
Across the varied competitive landscape, Beneo exemplifies a specialized ingredient provider, focusing on scientifically-backed prebiotic solutions for the high-margin nutraceutical space. Tate & Lyle occupies a distinct position as a sugar-reduction specialist, differentiating its oligofructose offerings specifically within the beverage industry. Cargill, Incorporated, conversely, anchors the large-volume segment, leveraging its extensive manufacturing and distribution network to supply bulk oligofructose to major food conglomerates globally, emphasizing cost-efficiency and broad market reach.
| Leading Market Players |
|---|
| Tereos Group |
| Meiji Holdings Co., Ltd. |
| Beneo |
| Tate & Lyle |
| Baolingbao Biology |
| Cargill, Incorporated |
| Galam |
| Roquette Frères |
| Ingredion |
| Others |
Cost & Logistics Intelligence
Large-scale chicory processing capacity underpins oligofructose production, enabling significant scale economies. This production model concentrates supply among major ingredient manufacturers, setting competitive price floors for bulk commodity grades.
Pricing Analysis
The pricing gap between advanced enzymatic hydrolysis grades and standard oligofructose reflects differing functional performance. The market employs a hybrid pricing model, combining contract-based long-term offtake for bulk volumes with value-based pricing for specialized nutraceutical grades. Price differentiation stems from purity levels for infant nutrition applications and specific regulatory certifications like EFSA health claims. Cost compression affects bulk commodity grades due to competition from other functional fibers, making Food & Beverage Producers highly price-sensitive compared to Nutraceutical Companies.
Supply Chain Analysis
European countries, particularly Belgium and the Netherlands, anchor chicory root cultivation and inulin extraction, forming the base of oligofructose production. The supply chain draws heavily from chicory root as its primary raw material. This reliance creates a structural risk from agricultural yield volatility due to weather patterns and crop diseases. Distribution runs through direct sales channels for large Food & Beverage Producers and specialized ingredient distributors for nutraceutical companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oligofructose manufacturers face a critical substitution defense challenge. The market must navigate direct competition from other functional fibers like inulin and fructooligosaccharides (FOS) in a range of food and beverage applications.
For Market Incumbents:Shield existing market share by investing in advanced enzymatic processing to create tailored oligofructose grades with specific physiological outcomes. Secure long-term chicory root supply contracts to mitigate raw material volatility and ensure supply chain integrity. This defends against commodity price pressure from bulk suppliers and the threat of substitution from other fibers. Focus R&D on synbiotic product development, combining oligofructose with targeted probiotics for enhanced functional benefits.
For New Entrants and Emerging Players:Anchor in underserved, high-growth segments like personalized nutrition platforms, where formulations are tailored to individual gut microbiomes. Target expansion in Southeast Asian markets such as Vietnam and Indonesia, leveraging rising disposable incomes and health awareness. The most penetrable segment remains specialized dietary supplements, where consumers seek premium, evidence-based ingredients. Emphasize robust clinical data and unique microbiome-targeting properties as a key go-to-market angle.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized nutraceutical firms with proprietary processing technologies and strong regulatory compliance. The long-term viability of the market is anchored in sustained consumer focus on gut health, particularly in infant nutrition and functional foods. Investors should seek acquisition targets that possess robust clinical data for specific oligofructose grades. Watch for EFSA or FDA approval of new, specific health claims for oligofructose variants as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Enzymatic Processing | Refines oligofructose molecular structures for targeted physiological outcomes in nutraceutical applications. |
| Synbiotic Product Development | Combines oligofructose with probiotics to offer enhanced functional benefits for gut health. |
| Infant Nutrition Partnerships | Secures long-term supply agreements with formula manufacturers, meeting stringent NMPA standards. |
| Southeast Asia Market Entry | Captures new demand from rising health awareness and disposable incomes in emerging economies. |
| Health Claim Substantiation | Navigates complex regulatory requirements to validate product benefits for consumer trust. |
Research Approach
A spread of perspectives from R&D directors, procurement leads at Food & Beverage Producers, regulatory affairs specialists, and nutraceutical product managers converged on the working assumptions. Primary interviews were combined with secondary validation from EFSA scientific opinions, FDA dietary fiber classifications, and NMPA infant formula standards. This approach facilitated bottom-up and top-down triangulation of market data. Industry association reports also provided critical contextual information.
Product forms, application areas, end-user types, packaging solutions, and regional consumption patterns defined the segmentation dimensions modeled. Compound annual growth rates were derived from historical trends, demand drivers, and competitive landscape analysis across the analysis window. Forecast inputs included chicory root agricultural yields and anticipated regulatory changes for prebiotic health claims. This framework projected market evolution through the forecast period.
Material uncertainties—unforeseen agricultural crises affecting chicory or sudden shifts in regulatory stances on prebiotics—sit outside the modeled envelope. Forecasts reflect assumptions documented regarding market dynamics and technological advancements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Mannitol Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
South Korea Allulose Market
Sweeteners
Sour Sugar Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Compressible Sugar Market
Sweeteners
Xylose Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Russia Food Sweetener Market