
 Drone Identification System Market | 2026-2036
Drone Identification System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Identification System Market Analysis
Project finance and operational leasing for counter-UAS infrastructure is tilting competition toward vendors with asset-light deployment models. Anduril Industries leverages its Lattice AI backbone to sustain recurring software revenue alongside hardware sales. Northrop Grumman anchors its position through captive integration of radar and command-and-control systems for layered airspace defense. Robin Radar Systems competes on specialized bird-and-drone discrimination algorithms that reduce false-alarm rates in dense electromagnetic environments.
A drone identification system comprises sensor arrays, signal processors, and data fusion engines that detect, classify, and track unmanned aerial vehicles through radio frequency emission analysis, optical triangulation, or radar cross-section measurement, typically resolving targets below two meters in wingspan at ranges exceeding five kilometers for airspace security applications. Automatic Identification Systems and Tracking Devices represent the established revenue base where procurement cycles run long and margins compress under federal budget scrutiny, while Surveillance Solutions integrating machine learning inference at the edge capture the fastest expansion as real-time threat classification replaces post-event forensic analysis. Computer Vision and Machine Learning segments concentrate software value creation, with RFID and GPS modules increasingly treated as commodity inputs rather than differentiation points.
The FAA Remote ID rule and EASA drone regulation framework jointly define product certification pathways, with FCC equipment authorization and CE marking governing radio frequency emissions compliance for cross-border equipment sales. NHTSA and Department of Homeland Security grant programs shape domestic demand concentration by funding municipal and critical infrastructure deployments. Stakeholders must monitor evolving standards for detect-and-avoid interoperability that will determine which technology architectures achieve regulatory lock-in versus obsolescence.
Market Dynamics
The FAA Remote ID mandate compresses deployment timelines for broadcast module manufacturers while NATO defense agencies accelerate layered counter-UAS procurement following airport disruption incidents.
Growth Catalysts
- FAA Remote ID Rule:Federal mandate for standard-compliant broadcast modules creates immediate replacement demand across recreational and commercial drone fleets.
- Critical Infrastructure Protection Directives:Designated facilities in the United States now require layered detection architectures, mandating redundant sensor coverage.
- Machine Learning Inference:Edge-deployed threat classification algorithms displace post-event forensic analysis, shortening response cycles for security operators.
Market Restraints
- RF Spectrum Congestion:Dense electromagnetic environments in urban corridors degrade signal discrimination accuracy, elevating false-positive rates.
- Component Supply Concentration:Specialized gallium nitride amplifiers for high-frequency radar modules concentrate among Asian foundry suppliers.
- EASA Certification Complexity:European drone regulation framework imposes divergent testing protocols that fragment product development roadmaps.
Strategic Opportunities
- Municipal Airspace Management:City-scale drone traffic management systems in the United States present untapped demand for integrated identification networks.
- Bird-Drone Discrimination:Specialized algorithms that distinguish avian radar signatures from unmanned vehicles open premium pricing in airport environments.
- Software-Defined Radio Convergence:Flexible RF front-ends combined with cloud-native fusion engines enable subscription-based detection-as-a-service models.
Industry Challenges
- Multidisciplinary Engineering Talent:Scarce expertise spanning RF engineering, computer vision, and airspace operations constrains product development velocity.
- Legacy C4I Integration:Command-and-control interoperability with existing military and civilian air defense networks demands costly custom engineering.
- Standards Fragmentation:Competing detect-and-avoid protocols across jurisdictions threaten technology obsolescence for non-adaptive architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Identification System Market |
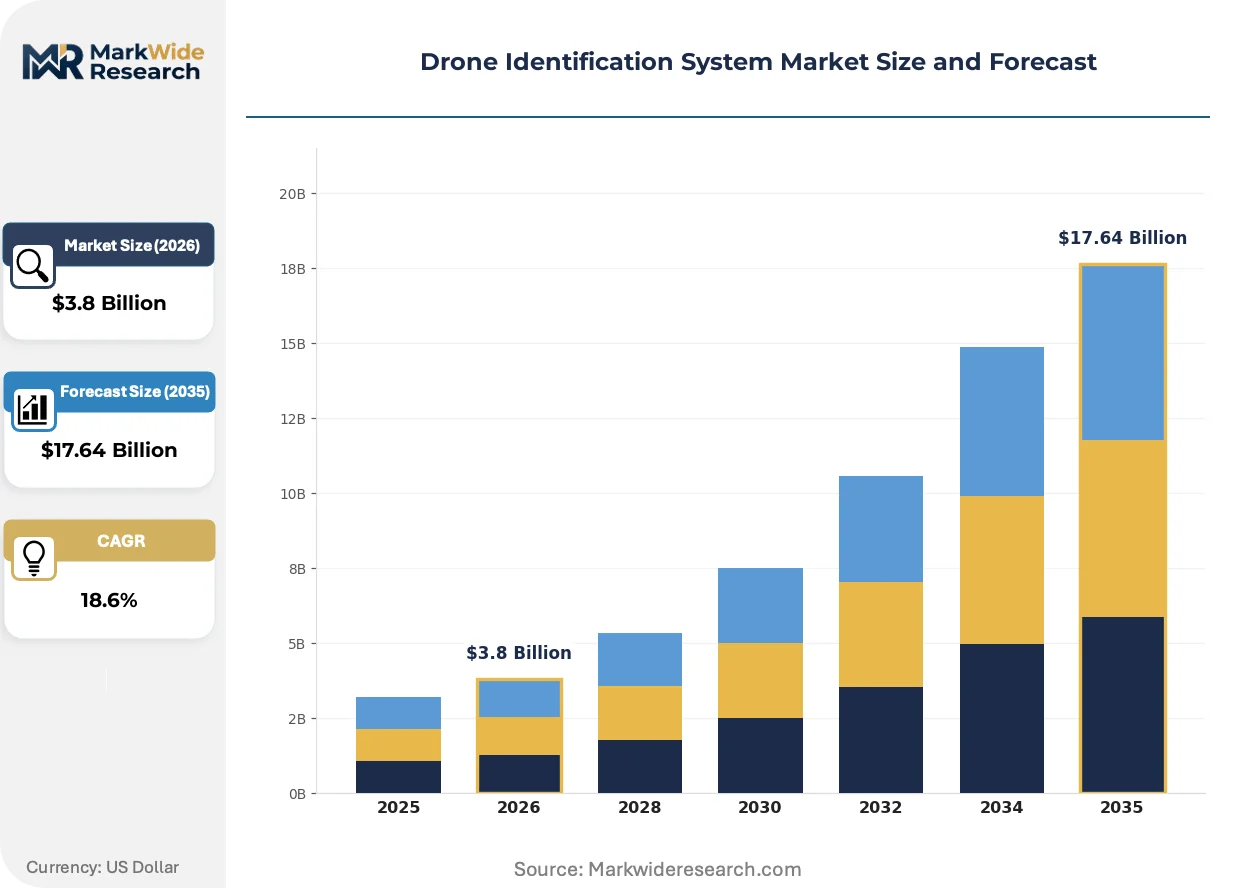
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Identification Systems, Remote Sensing Systems, Tracking Devices, Surveillance Solutions End User: Aerospace, Defense, Government, Commercial Enterprises Technology: RFID, GPS, Computer Vision, Machine Learning Application: Aerial Monitoring, Security Enforcement, Traffic Management, Search & Rescue |
| Companies Covered | Northrop Grumman, Azur Drones, Anduril Industries, Red Cat Holdings, Vantage Robotics, Skydio, Insitu, Robin Radar Systems, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Identification System Market Emerging Trajectories
Passive RF sensing architectures and edge AI inference engines are compressing the cost-performance frontier for drone detection, while regulatory mandates force standardization around broadcast identification protocols.
Software-defined passive RF sensors that capture and fingerprint drone control-link emissions without active radar illumination are rendering obsolete hardware-heavy active radar installations for urban perimeter security. Municipal police departments and critical infrastructure operators in the United States adopt these lower-signature systems to minimize spectrum interference and reduce power consumption. The shift collapses deployment costs and enables denser sensor grids across extended facility perimeters.
The FAA Remote ID rule and EASA drone regulation framework jointly establish certification pathways that harmonize equipment authorization requirements across transatlantic markets. Manufacturers must now design single hardware platforms satisfying both FCC equipment authorization and CE marking for radio frequency emissions compliance. This regulatory convergence pressures regional specialists to consolidate or exit, favoring vendors with established cross-border certification expertise.
Security buyers increasingly unbundle hardware procurement from ongoing software maintenance, favoring detection networks with open API architectures that permit third-party algorithm integration. Defense agencies and commercial airport operators in the United States lead this shift, treating sensor hardware as commodity infrastructure while competing on threat classification accuracy and update frequency. Vendors responding with modular software stacks capture recurring revenue streams that offset hardware margin compression.
Drone Identification System Market Segmentation
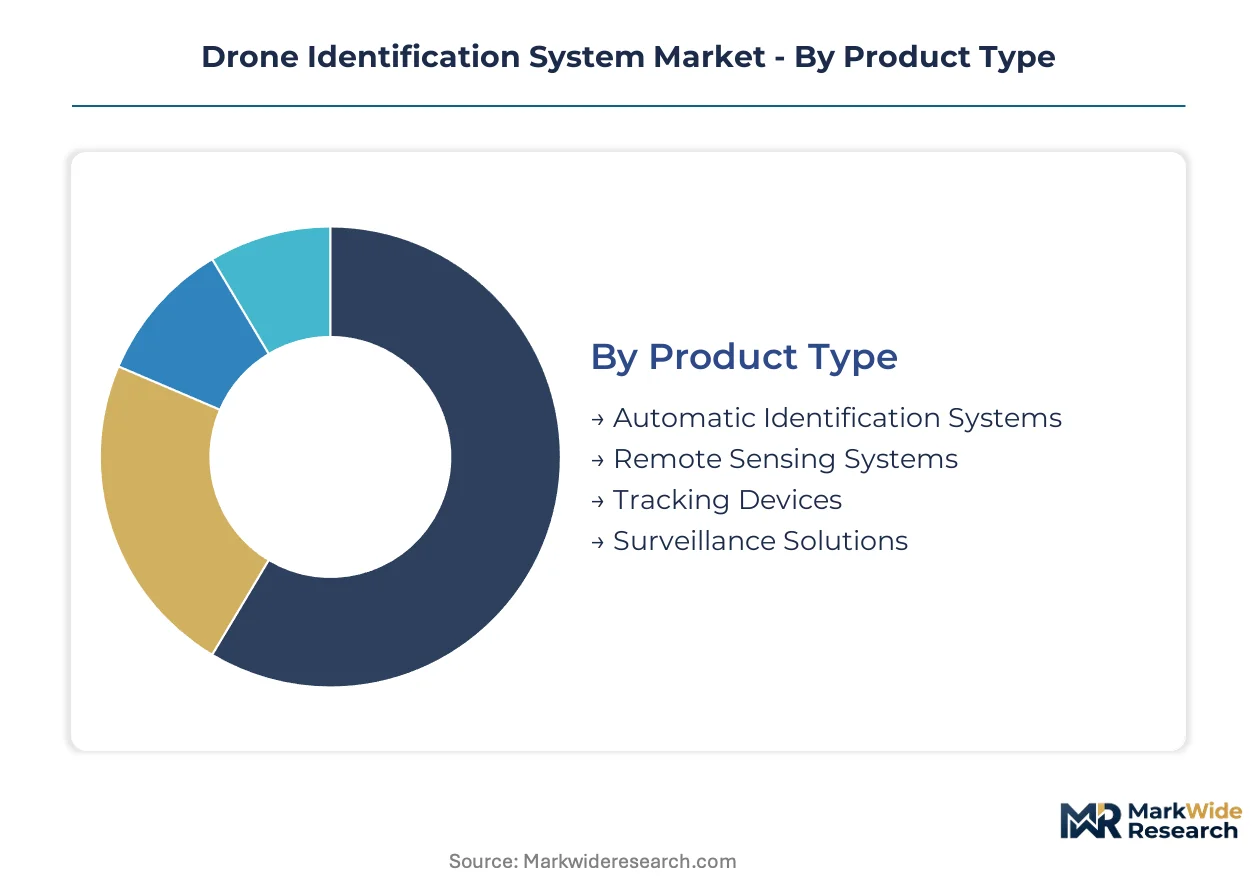
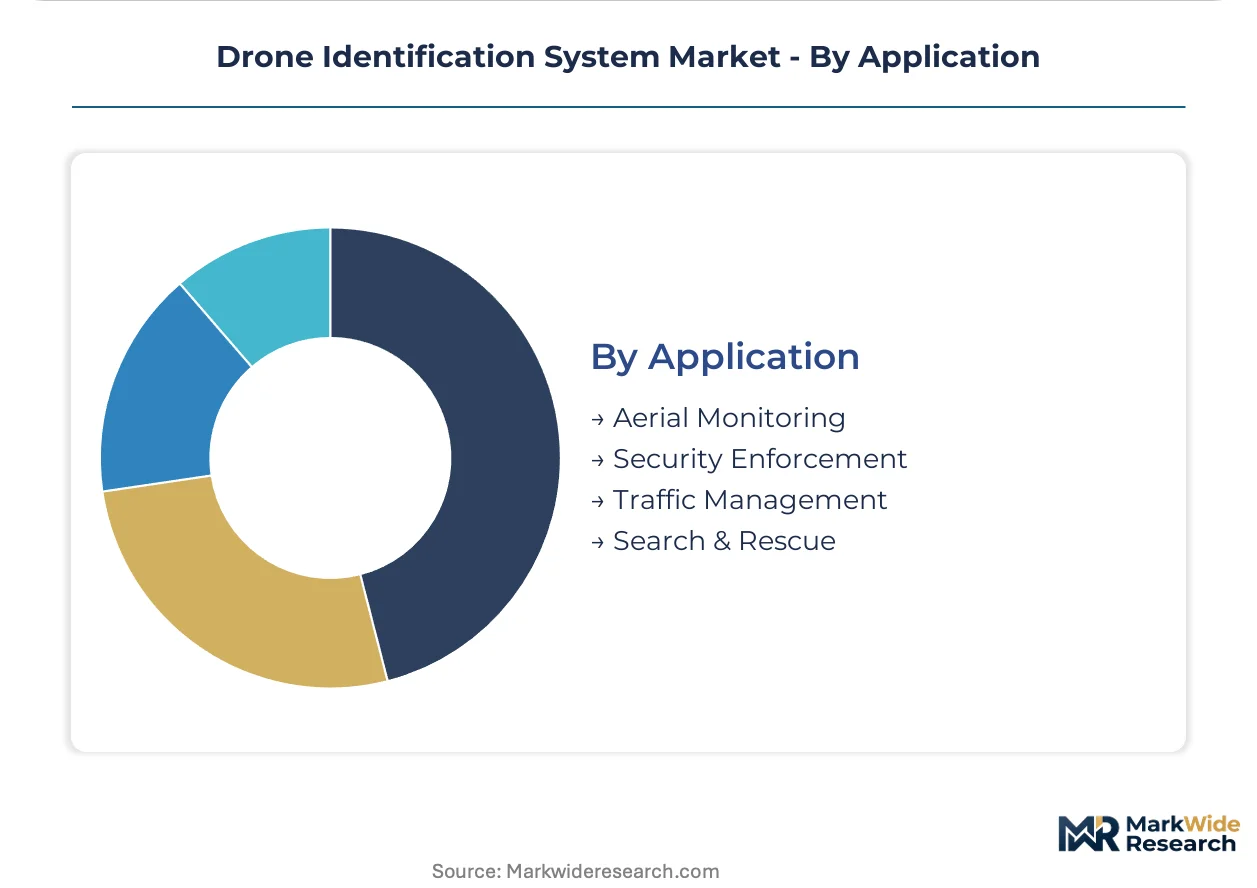
Drone identification system architectures diverge sharply across procurement contexts, with defense buyers prioritizing layered sensor fusion while commercial operators optimize for cost-per-detection. Segmentation reveals where software value concentrates against hardware commoditization pressures.
Product Type:
Mature broadcast modules and emerging AI-integrated surveillance platforms occupy opposite ends of the technology maturity spectrum.
- Automatic Identification Systems:Standard-compliant broadcast modules transmit drone position, velocity, and identification via RF or Wi-Fi protocols. FAA Remote ID rule enforcement drives replacement cycles across recreational and commercial fleets in the United States.
- Surveillance Solutions:Edge-deployed sensor networks fuse radar, optical, and passive RF inputs with machine learning inference for real-time threat classification. Critical infrastructure operators adopt these for layered perimeter defense mandated by federal protection directives.
- Remote Sensing Systems:Satellite and aerial platforms detect drone signatures across wide-area coverage zones for border monitoring applications.
- Tracking Devices:Embedded transponders and recovery beacons support forensic investigation and asset recovery for law enforcement agencies.
Automatic Identification Systems retain volume leadership; Surveillance Solutions hold the steepest expansion curve.
End User:
Defense procurement concentrates spending on multi-sensor fusion platforms while commercial demand fragments across price-sensitive use cases.
- Defense:Military buyers mandate command-and-control interoperability with existing air defense networks, driving premium pricing for customized integration services. NATO member states accelerate layered counter-UAS procurement following airport disruption incidents.
- Government:Federal and municipal agencies deploy identification networks for critical infrastructure protection, prison perimeter security, and public event monitoring under grant-funded programs.
- Aerospace:Airport operators prioritize bird-drone discrimination algorithms to minimize false-alarm rates in dense electromagnetic environments.
- Commercial Enterprises:Energy facilities, data centers, and logistics hubs adopt lower-cost passive RF systems for facility perimeter monitoring.
Defense commands the highest per-unit spending; Commercial Enterprises are gaining share fastest as sensor costs decline.
Technology:
Value creation shifts from hardware modules toward software-defined classification engines.
- Computer Vision:Optical sensors with edge-deployed neural networks resolve drone silhouettes against cluttered backgrounds for short-range precision tracking. Airport security operators demand these for terminal proximity monitoring.
- Machine Learning:Signal processing algorithms discriminate drone control-link emissions from background RF noise, enabling passive detection without active radar illumination. Municipal police departments adopt these for urban deployment.
- RFID:Short-range identification tags support inventory management and access control for commercial drone fleets.
- GPS:Position reporting modules face commoditization as regulatory mandates standardize minimum performance specifications.
Machine Learning captures software margin expansion; Computer Vision anchors high-reliability deployments.
Application:
Security-centric deployments outpace operational efficiency use cases in funding priority.
- Security Enforcement:Counter-UAS platforms detect, track, and interdict unauthorized drone incursions at prisons, stadiums, and government facilities. Layered detection architectures are now mandatory at designated critical infrastructure sites.
- Aerial Monitoring:Wide-area surveillance networks track drone traffic patterns for airspace management and regulatory compliance verification.
- Traffic Management:Urban air mobility corridors require real-time identification for deconfliction as drone delivery volumes expand.
- Search & Rescue:First responders deploy identification systems to locate missing aircraft and coordinate disaster response drone fleets.
Security Enforcement dominates procurement budgets; Traffic Management shows the strongest forward momentum as urban air mobility infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal security buyers concentrate procurement in the United States while European defense agencies accelerate layered counter-UAS spending. Airport operators and critical infrastructure managers drive commercial adoption across NATO member states.
United States
Defense agencies and homeland security departments dominate procurement volumes for layered detection architectures. The FAA Remote ID mandate compresses deployment timelines for broadcast module manufacturers serving recreational and commercial fleets. Critical infrastructure operators in Texas and California deploy redundant sensor coverage at energy facilities and data centers under federal protection directives.
Germany
Bundeswehr procurement offices prioritize command-and-control interoperability with existing air defense networks for military installations. EASA drone regulation frameworks impose certification requirements that fragment product development roadmaps for equipment suppliers. Industrial clusters around Munich and Stuttgart host system integrators specializing in radar and passive RF fusion for airport security applications.
United Kingdom
Royal Air Force and civilian airport operators drive demand for bird-drone discrimination algorithms to minimize false-alarm rates. The Civil Aviation Authority enforces registration and remote identification standards for commercial drone operations above 250 grams. Security technology firms in the Southeast England corridor develop edge-deployed threat classification systems for prison perimeter monitoring.
France
Direction Générale de l'Armement funds multi-sensor fusion platforms for military base protection and expeditionary deployments. ANSM and aviation regulators coordinate with EASA on harmonized certification pathways for cross-border equipment sales. Aerospace and defense suppliers in the Toulouse-Paris axis integrate optical and radar signatures for real-time threat classification in dense electromagnetic environments.
Israel
Ministry of Defense procurement prioritizes portable counter-UAS systems for border monitoring and urban perimeter security. National regulators enforce strict export controls on dual-use detection technologies with signal intelligence applications. Defense technology clusters around Tel Aviv specialize in passive RF sensing and machine learning inference for drone control-link fingerprinting.
Drone Identification System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement contexts. Defense prime contractors anchor the premium tier through captive integration of radar and command-and-control systems. Software-defined radio specialists and edge AI vendors occupy the innovation frontier with subscription-based detection models. Dominant competitive moves include strategic partnerships for C4I interoperability and technology licensing for regulatory certification acceleration.
Within the defense prime tier, Northrop Grumman and Anduril Industries exemplify contrasting approaches to recurring revenue capture. Northrop Grumman represents traditional systems integration with captive hardware-software stacks for military buyers. Anduril Industries occupies a position emphasizing software-centric delivery models with modular open architectures. Among specialized detection vendors, Robin Radar Systems exemplifies the algorithm-differentiation archetype for airport and critical infrastructure applications.
| Leading Market Players |
|---|
| Northrop Grumman |
| Azur Drones |
| Anduril Industries |
| Red Cat Holdings |
| Vantage Robotics |
| Skydio |
| Insitu |
| Robin Radar Systems |
| AeroVironment |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese gallium nitride foundries for high-frequency radar amplifiers compresses pricing power across tiered hardware offerings while forcing buyers toward longer-term contracting with embedded price escalators. This chokepoint widens spreads between premium military-grade systems and commoditized commercial modules as vendors pass through input volatility or absorb margins to defend market position.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate defense procurement, locking in predictable margins for integrators while exposing commercial buyers to spot-market component swings. Price differentiation rests on FCC certification tier and software update frequency, with subscription-anchored SaaS models capturing recurring revenue from security operators. Cost compression in passive RF sensor tiers intensifies as Asian module suppliers scale output. Municipal police departments exhibit highest price sensitivity; NATO defense agencies least.
Supply Chain Analysis
Upstream feedstock for specialized RF components concentrates in Taiwan, South Korea, and Japan, where gallium nitride wafer fabrication and precision radar subassemblies anchor tier-one supplier networks. Critical inputs include GaN-on-SiC wafers, software-defined radio chipsets, and edge AI inference processors. Single-source vulnerability in Taiwanese foundry capacity exposes lead times to geopolitical disruption. Distribution runs through defense prime contractor channels and direct municipal procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone identification markets approach a platform-economics inflection where open API architectures and detect-and-avoid interoperability standards will determine vendor survival, rewarding ecosystems that lock in municipal and defense buyers through modular software stacks.
For Market Incumbents: Pre-empt margin erosion in broadcast module hardware by accelerating vertical integration into edge AI software layers, while defending against SaaS-native entrants through captive certification pipelines that accelerate FAA and EASA compliance timelines for integrated offerings. For New Entrants and Emerging Players: Municipal airspace management in mid-tier US metropolitan areas offers the most penetrable white space, where legacy radar incumbents lack cost-optimized passive RF solutions; pursue detection-as-a-service models with subscription pricing to bypass capital-constrained procurement cycles. For Investors and Strategic Acquirers: The market sits at a standards-consolidation phase that favors software-defined specialists with regulatory certification momentum over hardware-heavy primes; prioritize targets with embedded EASA and FCC authorization pathways. Watch for detect-and-avoid protocol harmonization across NATO members as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Convergence | Enables subscription-based detection-as-a-service models for municipal police departments. |
| Regulatory Certification Acceleration | Captures FAA Remote ID and EASA harmonization timing for cross-border equipment sales. |
| Edge AI Platform Integration | Shortens threat classification cycles for critical infrastructure security operators. |
| Bird-Drone Discrimination Licensing | Opens premium pricing at airports through specialized algorithm differentiation. |
| C4I Interoperability Partnership | Secures military procurement slots via command-and-control network integration. |
Methodological Framework
Initial hypotheses were tested against primary input from defense procurement officers, critical infrastructure security directors, RF engineering leads, and municipal aviation planners and refined through secondary validation against FAA regulatory filings, EASA certification databases, NATO counter-UAS procurement disclosures, and customs trade data for gallium nitride component flows. Bottom-up sensor deployment counts and top-down defense budget appropriations were triangulated to anchor market sizing.
Demand-supply-balance modeling across the projection horizon segmented by product architecture, end-user procurement authority, technology modality, and application security tier, with CAGRs derived from regression against historical defense electronics spending and drone fleet growth curves. Forecast inputs included FAA Remote ID compliance deadlines and EASA drone regulation adoption trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation by software-centric entrants or sudden tariff disruption in Taiwanese semiconductor supply chains would shift outcomes. Cross-checking against Department of Homeland Security grant allocation disclosures and NATO defense electronics procurement bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Target Drone Market
UAV
Drone Leasing Market
UAV
Rotary Blade UAV Drones Market
UAV
Middle-East and Africa Drones Market
UAV
UAV Battery Market
UAV
Bubble Drone Market
UAV
GCC Drones Market
UAV
Counter Drone System Market
UAV
Latin America Small UAV Market
UAV
Global Drone Light Shows Market
UAV
Ultra-Long Endurance Drone Market
UAV
Anti-Drone Technology Market
UAV
US Commercial Drone Market
UAV
UAV GNSS Antenna Market
UAV
Short-Range Delivery Drone Market
UAV
Drone Telematics Market