
 Night Vision Devices Market | 2026-2036
Night Vision Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Devices Market Intelligence
Israeli and French defense electronics manufacturing capacity is fragmenting the supply base for critical sensor components. L3Harris Technologies Inc. leverages its scale in military contracts to drive innovation in integrated systems. Teledyne FLIR LLC specializes in thermal imaging technology across both defense and commercial markets. Thales Group competes through its extensive systems portfolio and strong presence in European defense programs, securing key national contracts.
Night vision devices are optoelectronic instruments that render visible images in low-light or total darkness. They function by amplifying ambient light through image intensifier tubes or by detecting thermal radiation via microbolometer arrays. Their primary purpose is to enable surveillance, navigation, and targeting when natural illumination is insufficient. Fusion technology, which overlays thermal and intensified images, is emerging as a high-growth area, while defense forces constitute the dominant end-user segment.
The market operates under strict regulatory controls, including U.S. International Traffic in Arms Regulations (ITAR) which governs the export of military-grade systems. Devices sold for commercial use in Europe must comply with CE marking standards for safety and performance. These frameworks dictate market access and product specifications. Manufacturers must continually balance the pursuit of military-spec performance with the development of cost-effective solutions for expanding civilian applications.
Market Dynamics
The market's central dynamic is the tension between military-driven performance specifications and the push for lower-cost commercial solutions. This is reshaping product development, as demand for fusion technology in border security and law enforcement is concentrating investment in dual-use systems.
Growth Catalysts
- Border Security Modernization:National initiatives in countries like the United States, India, and Turkey to upgrade surveillance capabilities at borders are a primary demand driver for advanced night vision systems.
- Fusion Technology Adoption:The integration of thermal imaging with image intensification enhances situational awareness, prompting defense agencies to procure these more capable devices for tactical superiority.
- Law Enforcement Mandates:Urban policing modernization programs increasingly specify night vision for surveillance and officer safety, particularly for special tactical units operating in low-light environments.
Market Restraints
- Export Controls:Strict regulations, notably the U.S. International Traffic in Arms Regulations (ITAR), limit the export of high-performance military-grade devices, constraining access to certain international markets.
- Component Cost:The high manufacturing cost of core components like gallium arsenide image intensifier tubes and microbolometer arrays keeps device prices elevated, slowing adoption in commercial sectors.
- Supply Base Fragmentation:Critical sensor components are sourced from a fragmented base of specialized suppliers in geographies like Israel and France, creating potential supply chain vulnerabilities and pricing power.
Strategic Opportunities
- Autonomous Systems Integration:The automotive sector presents a significant opportunity, with potential for integrating night vision sensors into advanced driver-assistance systems (ADAS) and autonomous vehicle perception stacks.
- Emerging Commercial Verticals:Untapped demand exists in wildlife conservation, search and rescue, and private security in markets across Africa and Southeast Asia where low-light monitoring is critical.
- Digital Night Vision:Development of lower-cost, solid-state digital night vision technologies opens avenues for networked devices that are easier to integrate and maintain for civilian and paramilitary users.
Industry Challenges
- Legacy System Integration:Manufacturers face difficulties ensuring new night vision systems are interoperable with existing military and police command, control, and communications (C3) platforms, delaying fielding.
- Divergent Compliance Pathways:Balancing the design requirements to meet U.S. military specifications against commercial standards like Europe's CE marking adds significant engineering and testing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Devices Market |
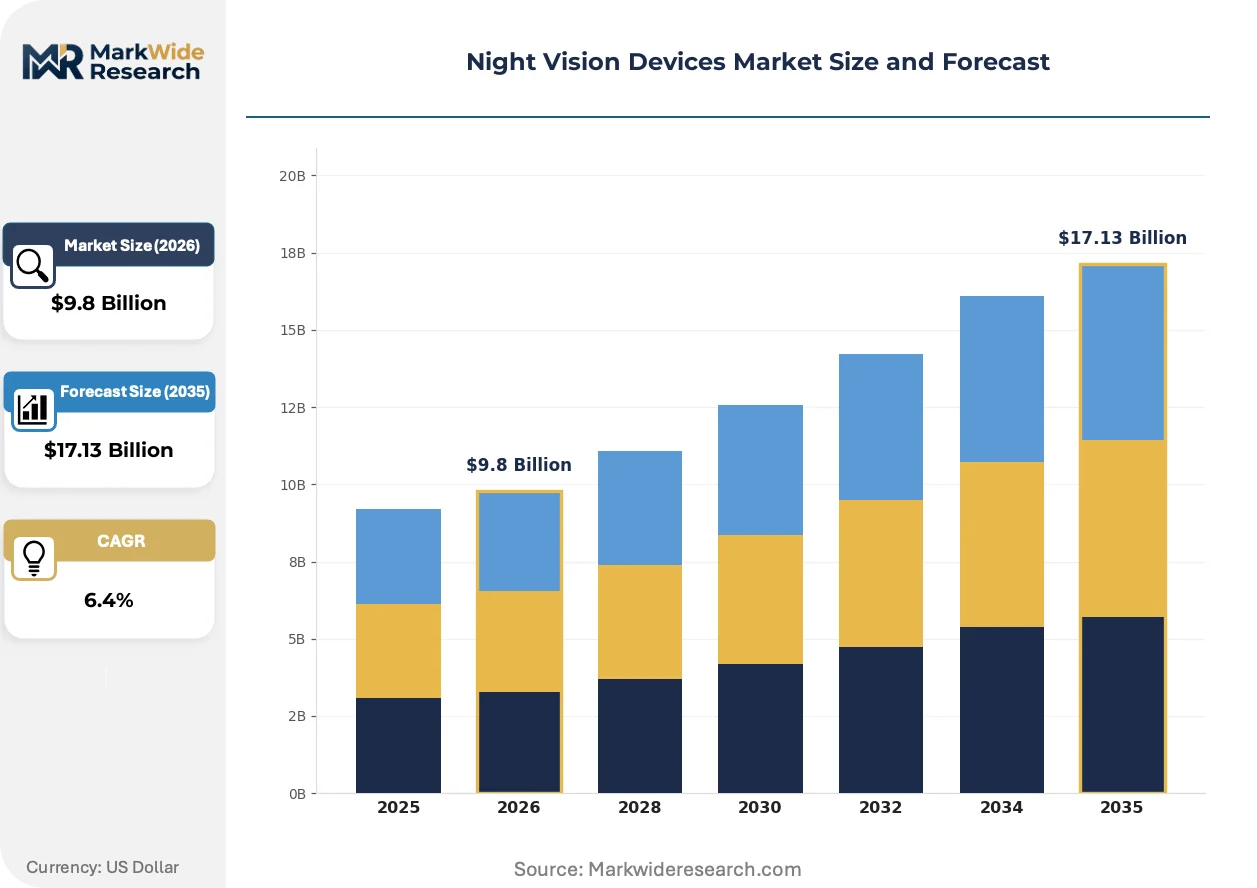
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoculars, Binoculars, Goggles, Scopes, Cameras Technology: Image Intensification, Thermal Imaging, Digital Night Vision, Near-Infrared, Fusion Technology Application: Surveillance, Wildlife Monitoring, Security, Search & Rescue, Maritime Navigation End User: Defense Forces, Law Enforcement, Wildlife Researchers, Maritime Operators, Private Security |
| Companies Covered | Teledyne FLIR LLC, L3Harris Technologies Inc., BAE Systems plc, Thales Group, Elbit Systems Ltd., Raytheon Technologies Corporation, Leonardo S.p.A., Collins Aerospace, ATN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of digital processing with advanced sensor hardware. This shift turns standalone optical instruments into networked, data-centric assets essential for enhanced situational awareness across defense and public safety operations.
Connected-Augmented Reality (C-AR) overlays integrate real-time data streams from command centers directly into the user’s field of view. Special operations forces and advanced law enforcement units are the primary adopters of this nascent capability. This technology is virtualizing the operational environment, transforming an optical feed into an interactive, data-rich battlespace.
European Union CE marking requirements for electromagnetic compatibility and user safety mandate specific design protocols for commercial-grade devices. This forces manufacturers to engineer separate product lines for military and civilian sales, limiting economies of scale. The commercial segment, particularly for maritime security in Europe, is most affected as compliance is a prerequisite for market access.
A notable behavioral shift involves public agencies moving from one-time hardware purchases toward acquiring "vision-as-a-service" packages. This subscription model, bundling hardware with software updates and maintenance, displaces traditional capital expenditures. The change is most visible among North American municipal police forces seeking predictable operational spending.
Night Vision Devices Market Segmentation
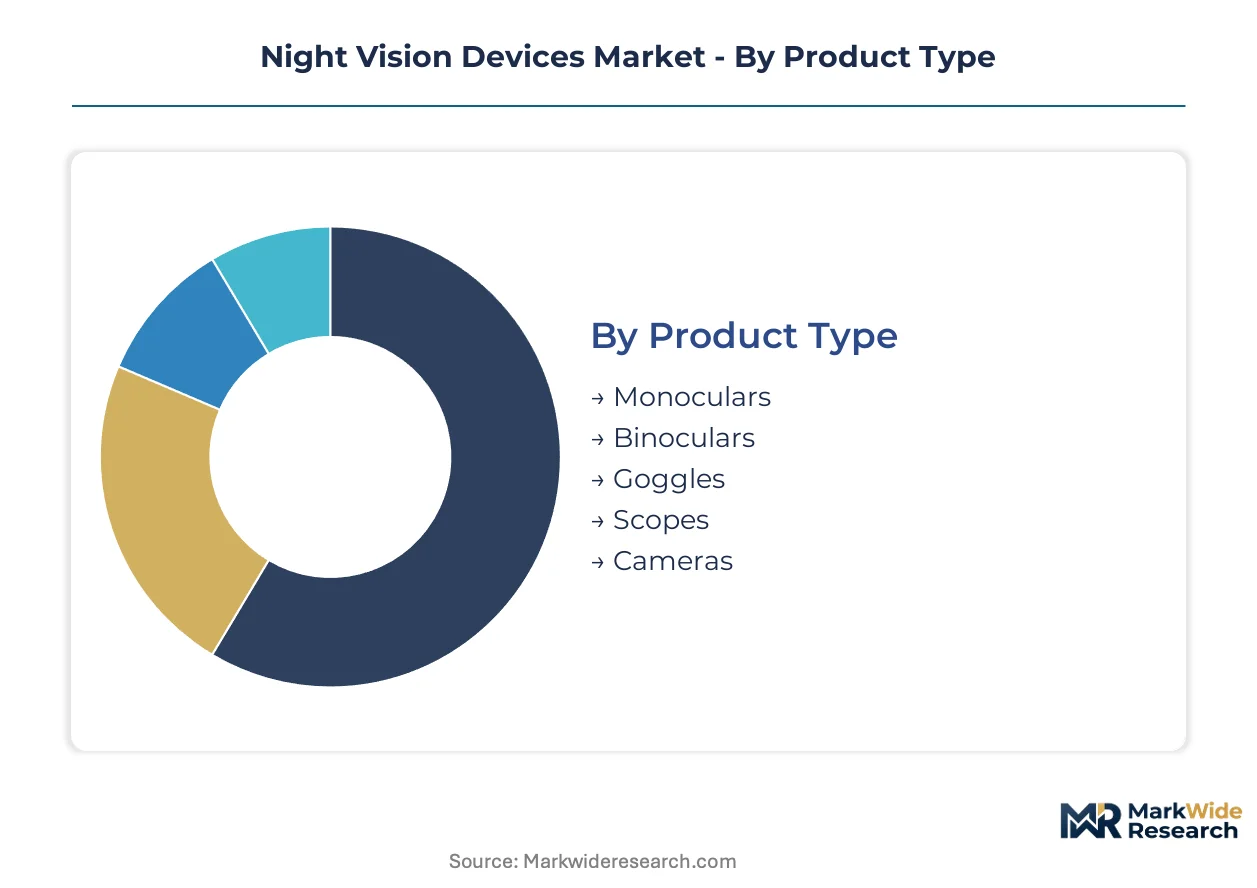
The segmentation of the night vision devices market reveals distinct patterns in demand and technological evolution. Understanding these categories allows for precise targeting of product development and market entry strategies. This granular analysis highlights where investment and innovation are most impactful across diverse user groups.
Product Type:
The use-case spectrum for night vision devices dictates the form factor and optical configuration. Each type serves specific operational needs, from individual portability to integrated surveillance.
- Monoculars:These compact, single-eye devices offer portability and reduced weight for individual users in reconnaissance. Demand concentrates in special operations forces in Europe seeking agile, hands-free observational tools.
- Binoculars:Providing stereoscopic vision, these devices enhance depth perception for navigation and extended observation.
- Goggles:Head-mounted for hands-free operation, goggles are essential for tactical mobility and close-quarters engagements. Law enforcement units in the United States prioritize these for urban surveillance and officer safety.
- Scopes:Designed for weapon mounting, scopes provide target acquisition capabilities for military and hunting applications.
- Cameras:Integrated into surveillance systems, these devices capture night-time imagery for recording and remote monitoring.
The dominant share belongs to Goggles, while Monoculars is closing the gap fastest.
Technology:
The maturity and performance characteristics of night vision technologies define their suitability for various operational environments. Advancements continually push the boundaries of low-light visibility.
- Image Intensification:This traditional technology amplifies ambient light through a photocathode and microchannel plate for a green-hued image.
- Thermal Imaging:Detecting infrared radiation emitted by objects, thermal imagers provide clear visibility through smoke, fog, and complete darkness. Defense agencies globally prioritize thermal systems for all-weather threat detection.
- Digital Night Vision:Utilizing CMOS or CCD sensors, digital devices offer full-color night vision and easy integration with digital systems.
- Near-Infrared:These systems rely on active illumination, projecting infrared light to enhance visibility for close-range observation.
- Fusion Technology:Combining thermal and image-intensified views, fusion devices offer superior situational awareness and target identification. Border security forces in India are increasingly adopting fusion systems for enhanced threat assessment.
Thermal Imaging holds a significant market position, with Fusion Technology exhibiting the steepest expansion trajectory.
Application:
The primary operational requirements of users shape the specific features and configurations of night vision devices. Each application demands tailored performance attributes.
- Surveillance:This application involves continuous monitoring of areas or individuals, often requiring high-resolution, long-range capabilities. Demand for surveillance systems is strong in national border security initiatives across Turkey.
- Wildlife Monitoring:Used by researchers and conservationists, this application focuses on non-invasive observation of nocturnal animals.
- Security:Encompassing perimeter defense and asset protection, security applications demand reliable detection and identification in low-light conditions. Private security firms in the Middle East increasingly deploy night vision for critical infrastructure protection.
- Search & Rescue:These operations utilize night vision for locating individuals in dark or obscured environments.
- Maritime Navigation:Enabling safe passage for vessels in low visibility, maritime navigation systems assist pilots and crew.
Surveillance applications command the largest segment, with Security gaining share fastest.
End User:
The institutional structure and funding mechanisms of end-users dictate procurement cycles and performance specifications for night vision devices. Each segment has distinct purchasing priorities.
- Defense Forces:Military organizations procure high-performance, ruggedized night vision systems for combat, reconnaissance, and training. Global defense spending significantly influences this segment.
- Law Enforcement:Police and special tactical units utilize night vision for surveillance, tactical entries, and officer safety during nighttime operations. Urban policing modernization programs in the United States drive demand for advanced systems.
- Wildlife Researchers:These professionals employ night vision for ecological studies and non-intrusive animal observation.
- Maritime Operators:Commercial and recreational mariners use night vision for navigation and collision avoidance in low-light conditions.
- Private Security:Companies providing security services deploy night vision for guarding premises and personnel.
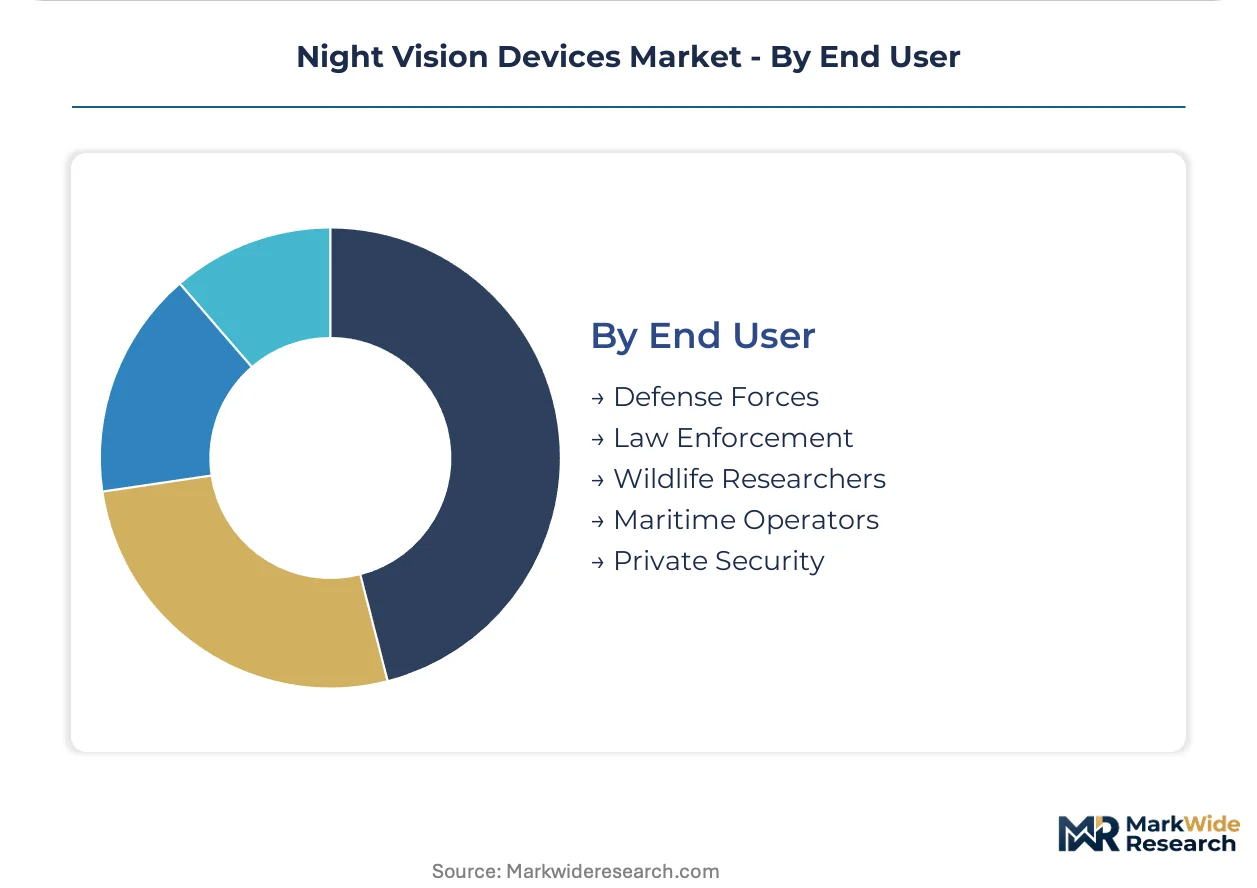
Defense Forces represent the dominant end-user segment, while Law Enforcement shows robust procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for night vision devices varies significantly across global geographies, reflecting diverse security priorities and regulatory landscapes. Military procurement drives high-performance system adoption in some areas, while others concentrate on law enforcement and commercial applications. This consumption mix shapes regional market dynamics.
United States
The United States market sees strong demand from border security modernization and urban policing programs. Strict U.S. International Traffic in Arms Regulations (ITAR) govern military-grade device exports. Major defense contractors in the Washington D.C. area drive innovation in integrated night vision systems for federal agencies.
India
India's night vision market is propelled by national border security initiatives and increasing adoption of fusion technology. The country's defense procurement policies encourage domestic manufacturing and technology transfer. Bengaluru serves as a critical hub for defense electronics research, fostering indigenous night vision capabilities.
Turkey
Turkey's demand for night vision devices primarily stems from national border security initiatives and extensive surveillance applications. The government's focus on defense self-sufficiency influences procurement strategies. Ankara, as the center of the Turkish defense industry, hosts companies developing advanced night vision solutions for security forces.
France
French defense electronics manufacturing contributes significantly to critical sensor components, supporting European defense programs. Devices for commercial use in Europe must comply with CE marking standards. The Paris region hosts major defense contractors like Thales Group, securing national contracts for advanced night vision systems.
Germany
German defense forces and law enforcement agencies increasingly procure advanced night vision systems for tactical operations. Compliance with CE marking standards is essential for commercial devices, particularly in maritime security. Companies in Bavaria specialize in precision optics and sensor integration, supplying national and international defense clients.
Night Vision Devices Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The night vision devices market exhibits fragmentation in critical sensor components but consolidation among integrated system providers. Key archetypes include specialized component manufacturers, large defense contractors, and dual-use technology developers. Strategic partnerships and portfolio diversification are dominant competitive moves among these players.
Specialists in thermal imaging technology, such as Teledyne FLIR LLC, occupy a significant market position across both defense and commercial segments. This company exemplifies a dual-market approach, leveraging core expertise for varied applications. L3Harris Technologies Inc. represents a large defense contractor archetype, leveraging its scale in military contracts to drive innovation in integrated systems. Thales Group, a prominent European defense electronics company, anchors the market through its extensive systems portfolio and strong presence in European defense programs, securing key national contracts.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| L3Harris Technologies Inc. |
| BAE Systems plc |
| Thales Group |
| Elbit Systems Ltd. |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| Collins Aerospace |
| ATN Corporation |
| Others |
Cost & Logistics Intelligence
Fragmented manufacturing capacity for critical sensor components in specialized geographies drives supplier pricing power, impacting overall device costs. This dynamic influences product development strategies across the night vision devices market.
Pricing Analysis
Long-term contract-based pricing dominates military procurement for night vision systems. Price differentiation stems from military-grade performance specifications and the integration of advanced fusion technology. Pricing softness affects commercial segments due to high component costs and competition from digital alternatives. Law enforcement and defense entities exhibit lower price sensitivity compared to commercial and civilian end-users.
Supply Chain Analysis
U.S. International Traffic in Arms Regulations (ITAR) restrict the export of military-grade night vision devices, limiting supply flows to certain international markets. The supply chain for critical sensor components concentrates in Israel and France, with integrated systems often assembled in the United States. Key dependencies include gallium arsenide image intensifier tubes and microbolometer arrays. Supply base fragmentation presents a structural risk, while distribution runs primarily through direct government contracts and specialized commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands a strong substitution defense as lower-cost digital night vision technologies pose a viable alternative. Incumbents must navigate this evolving landscape to maintain market share.
For Market Incumbents: Insulate core military contracts by investing heavily in fusion technology R&D, ensuring continued performance superiority. Deepen vertical integration for critical sensor components to mitigate supply chain fragmentation risks from specialized suppliers. Develop cost-effective digital night vision solutions to counter the threat from emerging commercial alternatives. Secure long-term service contracts with defense and law enforcement agencies to build recurring revenue streams.
For New Entrants and Emerging Players: Underpenetration in African and Southeast Asian commercial verticals offers substantial entry points for night vision solutions. Target wildlife conservation and private security applications with cost-effective digital night vision systems. Focus on providing "vision-as-a-service" packages for municipal police forces, leveraging predictable operational spending. Partnerships with local distributors can accelerate market access in these nascent regions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers offering "vision-as-a-service" bundles, indicating stable long-term cash flows. Long-term viability hinges on companies mastering the integration of night vision with autonomous systems and networked digital platforms. Acquisition targets should include specialists in microbolometer arrays or advanced image intensifier tube manufacturing. The signal to watch is the increasing adoption of digital night vision solutions across paramilitary user groups.
| Strategic Initiative | Industry Significance |
|---|---|
| Fusion Technology R&D | Enhances device capabilities for defense agencies, providing a competitive edge in tactical superiority. |
| Digital Night Vision Development | Opens new market segments for networked, cost-effective solutions in civilian and paramilitary applications. |
| "Vision-as-a-Service" Model Adoption | Transforms revenue streams from capital expenditure to predictable operational spending for public agencies. |
| Supply Chain Vertical Integration | Mitigates risks from fragmented component suppliers, ensuring stable production of critical sensor components. |
| ADAS Integration Partnerships | Expands night vision sensor applications into the automotive sector, targeting advanced driver-assistance systems. |
Research Approach
The analysis maps night vision devices across defense, law enforcement, and commercial sub-sectors, each validated through extensive primary interviews. Conversations with defense procurement officers, tactical unit leads, and component manufacturers informed market dynamics. Secondary validation involved government defense budgets, regulatory filings like U.S. ITAR and CE marking standards. This approach ensures robust bottom-up and top-down triangulation.
Assumptions held fixed include stable geopolitical landscapes, while variables like defense spending and technology adoption rates were modeled across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected market penetration. Key inputs included border security modernization budgets.
Practitioners should monitor geopolitical shifts and new regulatory controls for early signals of market recalibration. Forecasts reflect a specific set of assumptions, and component supply disruptions could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Passive Radar Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Military Radar Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Global Radar Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market