
 Land Based Military Electro Optical & IR Systems Market | 2026-2036
Land Based Military Electro Optical & IR Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Land Based Military Electro Optical & IR Systems Market Insights
The divergence between premium cooled infrared sensor tiers and commodity uncooled alternatives is realigning procurement patterns across land forces. BAE Systems plc leverages its sovereign UK manufacturing base to sustain long-term service contracts for armored vehicle sighting systems. Elbit Systems Ltd. differentiates through vertical integration into thermal core production, while Thales Group competes on NATO interoperability certification across multiple European land forces.
Land based military electro optical and IR systems integrate thermal detectors, laser designators, and digital image processing hardware into stabilized gimbal platforms operating across near-infrared to long-wave infrared bands, primarily enabling target detection and engagement in degraded visual environments. Thermal imaging cameras and targeting systems command the deepest margin pools due to cooled sensor complexity and precision stabilization requirements. Multispectral technology is displacing single-band infrared in next-generation programs, though passive infrared dominates current installed bases across mechanized units.
US Army night vision programs operate under FAA-equivalent airworthiness coordination for aerial platform integration, while EU Green Deal procurement directives increasingly mandate conflict minerals traceability in optical component supply chains. NATO standardization agreements shape sensor interchangeability requirements, limiting vendor lock-in but raising compliance costs for non-aligned suppliers. Stakeholders must monitor how export control recalibrations affect thermal core technology transfer timelines.
Market Dynamics
Multispectral sensor fusion is compressing procurement cycles for mechanized land forces, as single-band infrared systems face accelerated replacement timelines under NATO standardization pressure.
Growth Catalysts
- EU Green Deal procurement directives:Conflict minerals traceability mandates in optical component supply chains are filtering out non-compliant suppliers, creating procurement advantages for certified European manufacturers serving Baltic defense ministries.
- Forward defense posture realignment:Poland's armored vehicle modernization programs are driving concentrated demand for stabilized gimbal platforms with laser designation capability.
- Night vision compatibility standards:US Department of Defense refresh cycles for legacy equipment are accelerating sensor replacement across Army Stryker and Abrams fleet upgrades.
Market Restraints
- Germanium substrate supply concentration:Optical component fabrication depends on limited-source germanium refining capacity concentrated in China and Russia, exposing Western manufacturers to input cost volatility and export restriction risk.
- Cooled sensor thermal core scarcity:Precision indium antimonide and mercury cadmium telluride detector production remains concentrated among three qualified suppliers, constraining volume scaling for next-generation programs.
- REACH substance restrictions:European Chemicals Agency classification of certain optical coating precursors as substances of very high concern is forcing reformulation of anti-reflective treatments, extending qualification timelines.
Strategic Opportunities
- Uncooled sensor convergence with AI-enabled target recognition:Machine learning inference at the edge is closing the performance gap between thermal core tiers, opening mechanized infantry vehicle segments to lower-cost alternatives.
- Polish-Baltic corridor demand concentration:Estonia, Latvia, and Lithuania are consolidating border surveillance procurement under NATO cooperative frameworks, creating volume aggregation opportunities for compliant system integrators.
- US Army next-generation targeting pod unbundling:Modular procurement specifications are separating sensor payloads from vehicle integration contracts, enabling specialist subsystem vendors to bypass prime contractor capture.
Industry Challenges
- Stabilized platform mechanical engineering talent scarcity:Precision gimbal design expertise resides within aging workforce cohorts at legacy defense contractors, constraining new entrant scaling.
- NATO STANAG 4695 certification timelines:Interoperability testing for sensor interchangeability extends 18-24 months, compressing contract award-to-delivery windows and straining working capital.
- Retrofit integration with analog legacy optics:Digital image processing hardware must interface with 1980s-era vehicle sighting systems, requiring custom signal conditioning that erodes margin on upgrade contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Based Military Electro Optical & IR Systems Market |
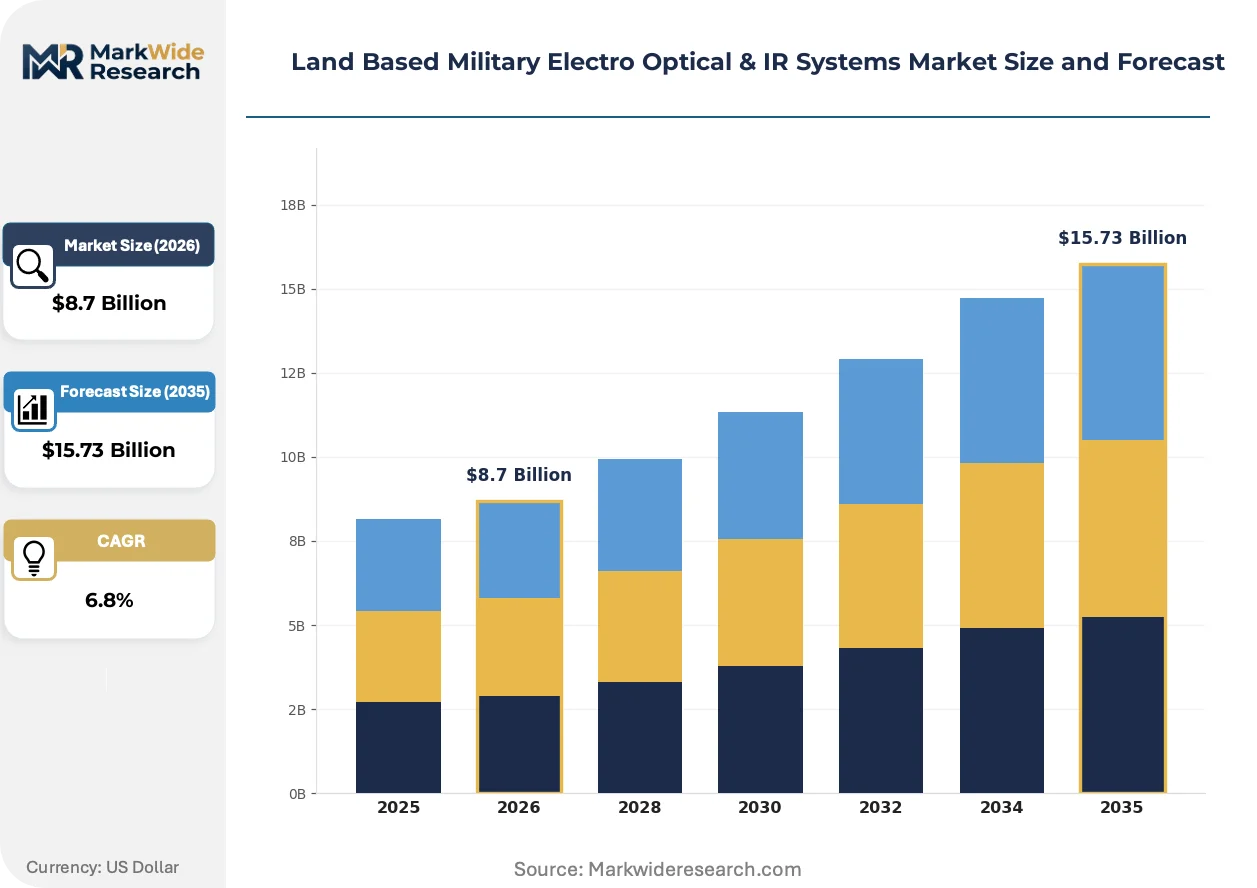
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Imaging Cameras, Night Vision Goggles, Laser Rangefinders, Targeting Systems Technology: Active Electro-Optical, Passive Infrared, Multispectral, Hyperspectral End User: Army, Navy, Air Force, Special Operations Application: Surveillance, Target Acquisition, Reconnaissance, Situational Awareness |
| Companies Covered | BAE Systems plc, Leonardo S.p.A, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, L3Harris Technologies, Inc., Raytheon Technologies Corporation, Elbit Systems Ltd., Israel Aerospace Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Based Military Electro Optical & IR Systems Market Trends and Innovations
Sensor payload architectures are fragmenting from monolithic integrated designs toward modular subsystem assemblies, enabling mixed-vendor configurations and compressing technology refresh timelines.
Short-wave infrared focal plane arrays are modularizing battlefield situational awareness capabilities, allowing armored vehicle commanders to detect laser spot illumination and covert beacon markers through obscurants. Polish Land Forces are fielding these capabilities at platoon scale ahead of NATO standardization. The technology is modularizing procurement decisions, separating detector selection from gimbal and processing hardware commitments.
EU AI Act risk classification for autonomous targeting assistance is reshaping software development roadmaps for European suppliers, mandating human-in-the-loop validation for systems above defined capability thresholds. Thales and Safran are restructuring algorithm training pipelines to maintain CE marking eligibility. German and French land vehicle programs are most affected, with compliance costs being absorbed through cooperative development frameworks.
Buyer aggregation through NATO support and procurement agencies is consolidating national tender volumes, reducing supplier count per member state while expanding contract scope. The NATO Support and Procurement Agency is displacing bilateral national negotiations for multispectral targeting systems. This concentration is most visible in Baltic and Nordic member states, where defense budgets are pooling under collective security frameworks.
Land Based Military Electro Optical & IR Systems Market Segmentation
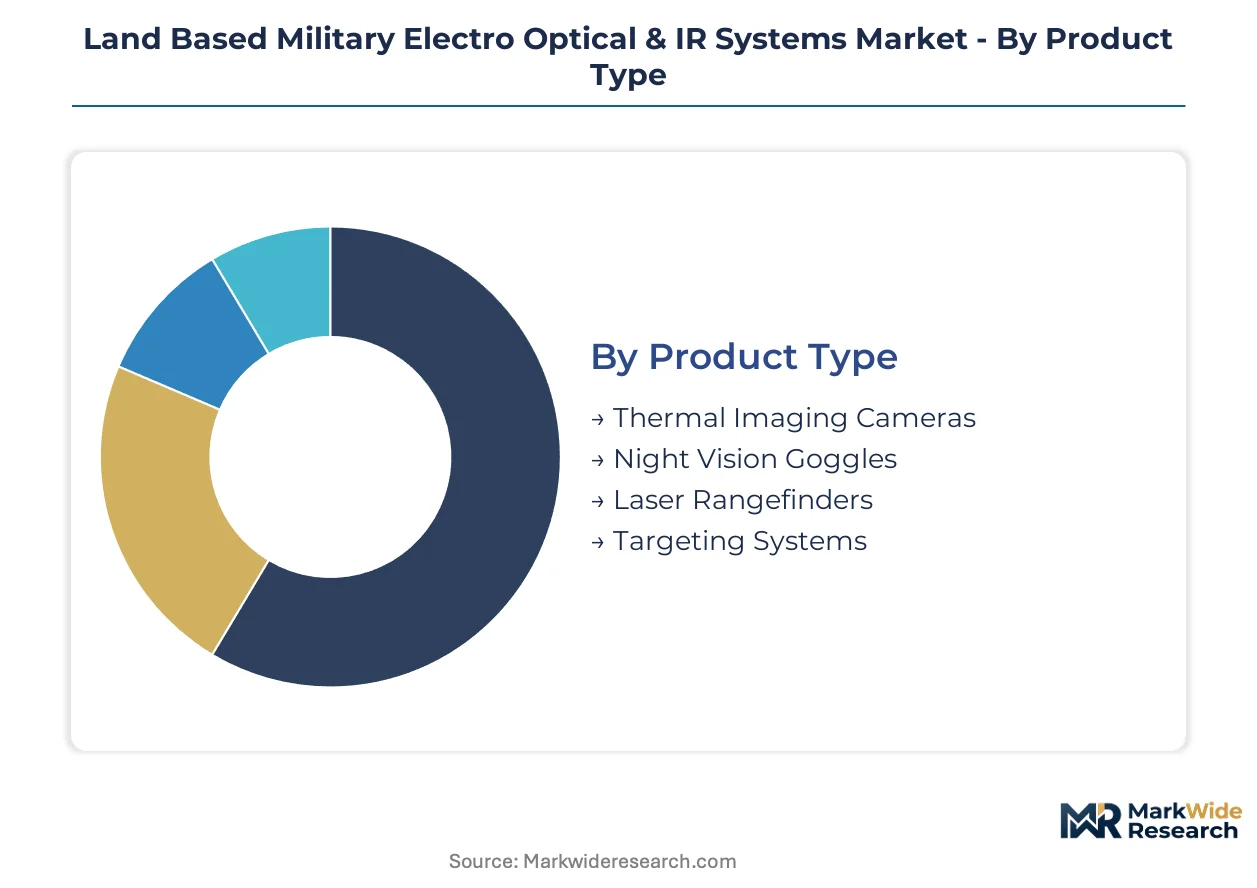
Segmentation in military electro-optical and infrared systems reveals how procurement budgets fragment across technology readiness levels and operational requirements. Understanding these divisions exposes where margin concentrates and where commodification threatens incumbent positions.
Product Type:
Supply concentration in cooled infrared detector manufacturing disproportionately shapes which product categories command premium pricing and which face cost compression from uncooled alternatives.
- Thermal Imaging Cameras:Cooled indium antimonide and mercury cadmium telluride focal plane arrays deliver long-wave infrared detection with superior range performance. Polish armored vehicle modernization programs and US Army Stryker fleet upgrades are concentrating demand for vehicle-mounted variants with integrated laser designation capability.
- Targeting Systems:Stabilized gimbal platforms combining multispectral sensors with digital image processing enable precision engagement in degraded visual environments. NATO standardization pressure on mechanized forces is accelerating replacement cycles for legacy single-band infrared systems.
- Night Vision Goggles:Image intensification tubes and fusion devices for dismounted soldier programs.
- Laser Rangefinders:Eye-safe diode-pumped solid-state emitters for target designation and fire control.
Today's leader: Targeting Systems. Tomorrow's challenger: Thermal Imaging Cameras.
Technology:
Cost tier differentiation separates mature passive infrared from emerging multispectral architectures, with qualification timelines and thermal core scarcity determining competitive access.
- Passive Infrared:Single-band thermal detection dominates current installed bases across mechanized units, leveraging established supply chains for uncooled microbolometer arrays. Legacy refresh cycles under US Department of Defense night vision compatibility standards sustain volume, though margin pressure intensifies from uncooled sensor convergence.
- Multispectral:Sensor fusion across near-infrared through long-wave infrared bands compresses procurement cycles as NATO standardization agreements mandate interoperability. Polish Land Forces field short-wave infrared capabilities at platoon scale ahead of formal alliance adoption.
- Active Electro-Optical:Laser illumination and gated imaging for target identification through atmospheric obscurants.
- Hyperspectral:Contiguous spectral sampling for material discrimination and anomaly detection in reconnaissance roles.
Passive Infrared holds current volume dominance. Multispectral claims the steepest expansion trajectory as mechanized forces modernize.
End User:
Application specificity drives volume allocation, with ground force mechanization programs outpacing aerial and maritime integration timelines for land-based electro-optical payloads.
- Army:Mechanized infantry and armored vehicle programs constitute the primary demand center, with Abrams and Stryker upgrades driving stabilized sighting system procurement. Forward defense posture realignment in Poland and Baltic states is concentrating border surveillance investment.
- Special Operations:Discreet portable systems for unconventional warfare missions with stringent size and signature constraints.
- Navy:Coastal defense and amphibious platform integration for littoral operations.
- Air Force:Ground-based air defense and forward air controller targeting support.
Army programs anchor current procurement volume. Special Operations represents the fastest-climbing segment as asymmetric mission requirements proliferate.
Application:
Customer type segmentation separates sustained operational deployment from developmental platform integration, with fielded systems commanding recurring service revenue versus one-time development fees.
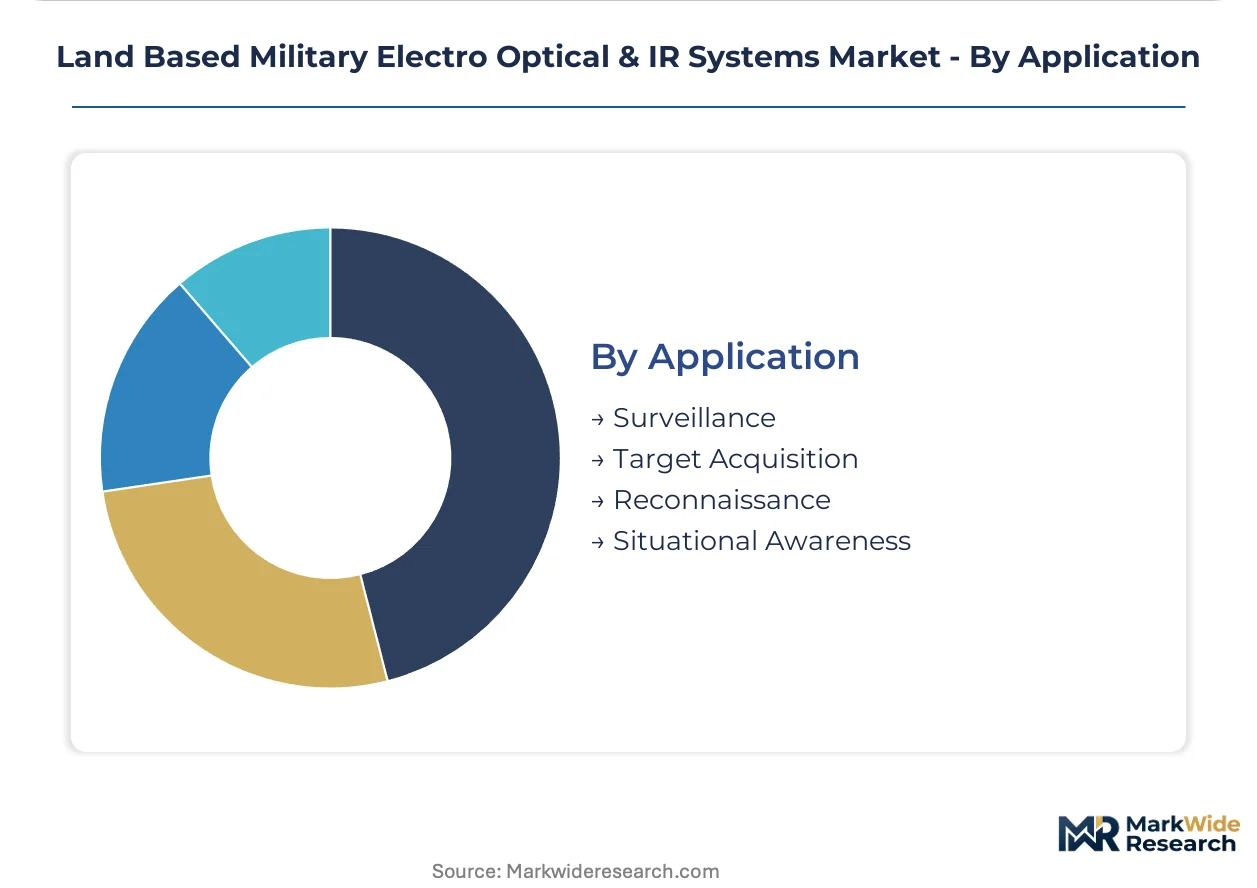
- Surveillance:Persistent wide-area monitoring for border security and critical infrastructure protection. Estonian, Latvian, and Lithuanian defense ministries are consolidating procurement under NATO cooperative frameworks, creating volume aggregation for compliant system integrators.
- Situational Awareness:Crew and dismounted force visibility enhancement through helmet-mounted and vehicle-integrated displays.
- Target Acquisition:Precision detection and engagement handoff for direct and indirect fire systems.
- Reconnaissance:Standoff collection and intelligence preparation of the battlefield.
Surveillance commands the deepest recurring revenue streams. Situational Awareness is gaining share fastest as digitization extends to squad-level formations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision gimbal engineering talent clusters in the United States, the United Kingdom, and Israel anchor the industry's geographic footprint. These concentrations sustain sovereign manufacturing capabilities for stabilized sighting platforms. Forward defense posture realignment in Eastern Europe is redrawing procurement maps.
United States
The US Army's Stryker and Abrams modernization programs drive sustained demand for vehicle-integrated targeting systems. FAA-equivalent airworthiness coordination governs aerial platform integration requirements. Huntsville, Alabama and Orlando, Florida host concentrated defense electronics engineering clusters where night vision compatibility standards are accelerating sensor replacement cycles.
Poland
Armored vehicle procurement at platoon scale concentrates demand for short-wave infrared capabilities ahead of NATO standardization. EU Green Deal conflict minerals traceability mandates filter supplier eligibility for Baltic corridor programs. Warsaw and Poznań defense industrial zones are absorbing technology transfer agreements for domestic gimbal assembly capacity.
United Kingdom
Sovereign manufacturing for armored vehicle sighting systems sustains long-term service contract volumes. BAE Systems plc anchors a supplier ecosystem around Glascoed and Rochester facilities. UK Export Finance support mechanisms are conditioning Polish and Baltic procurement decisions toward British-sourced thermal imaging subsystems.
Israel
In-house production of thermal cores distinguishes vertically integrated suppliers serving special operations and mechanized segments. Israeli Ministry of Defense qualification protocols exceed NATO STANAG baselines. Elbit Systems Ltd. and Israel Aerospace Industries Ltd. anchor industrial capacity in Haifa and Beersheba with captive detector fabrication lines.
Germany
Rheinmetall and Krauss-Maffei Wegmann vehicle programs integrate electro-optical payloads under EU AI Act human-in-the-loop compliance frameworks. ECHA REACH substance restrictions on optical coating precursors are forcing anti-reflective treatment reformulation. Bavarian and Baden-Württemberg precision optics clusters face extended qualification timelines for next-generation sighting systems.
Land Based Military Electro Optical & IR Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across cooled sensor fabrication and gimbal integration. The vendor base separates between sovereign-system integrators holding long-term service contracts and specialist subsystem suppliers capturing modular procurement opportunities. Two strategic archetypes dominate: vertically integrated thermal core manufacturers and platform-agnostic payload vendors. Competitive positioning hardens through NATO STANAG certification capture and backward integration into detector production.
Among UK-based sovereign integrators, BAE Systems plc exemplifies the long-term service contract archetype through armored vehicle sighting system sustainment. Elbit Systems Ltd. occupies a position representing captive thermal core production, while Thales Group anchors the NATO interoperability certification tier across multiple European land forces. These three patterns illustrate how geographic manufacturing bases, vertical integration depth, and alliance compliance capabilities segment competitive access to mechanized vehicle programs and border surveillance procurement.
| Leading Market Players |
|---|
| BAE Systems plc |
| Leonardo S.p.A |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| L3Harris Technologies, Inc. |
| Raytheon Technologies Corporation |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
NATO cooperative procurement frameworks pooling Baltic and Polish defense budgets are compressing supplier margins and forcing volume commitments that reshape how electro-optical manufacturers structure their cost bases. This buyer consolidation is intensifying competition for qualified suppliers while elevating the strategic value of captive thermal core production and NATO STANAG certification assets.
Pricing Analysis
Bundled long-term service contracts for armored vehicle sighting systems coexist with unbundled modular procurement separating sensor payloads from vehicle integration, creating divergent margin structures. Pricing stratifies across premium cooled sensor tiers, standard uncooled alternatives, and economy retrofit configurations, with differentiation driven by NATO STANAG 4695 certification status and backward integration into indium antimonide detector fabrication. Cost compression in uncooled thermal imaging is intensifying because AI-enabled target recognition is closing performance gaps between sensor tiers. Mechanized infantry vehicle programs exhibit highest price sensitivity, while special operations forces demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Direct-to-OEM channels handle prime contractor demand for stabilized gimbal platforms, while specialist subsystem vendors access mechanized vehicle programs through modular procurement specifications. Manufacturing concentration centers on the United States, the United Kingdom, and Israel for precision gimbal engineering and thermal core fabrication. Optical component supply draws from limited-source germanium refining capacity concentrated in China and Russia, with mercury cadmium telluride and indium antimonide detector production anchored among three qualified Western suppliers. Single-source vulnerability in germanium substrate supply exposes Western manufacturers to input cost volatility and export restriction risk. Distribution runs through NATO Support and Procurement Agency consolidation for Baltic corridor programs, displacing bilateral national negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal conflict minerals traceability mandates and REACH substance restrictions on optical coating precursors impose compliance costs that certified European manufacturers can leverage against non-aligned competitors facing extended qualification timelines.
For Market Incumbents: Hedge against uncooled sensor convergence by accelerating captive thermal core production investments and securing NATO STANAG 4695 certification lock-in ahead of Polish-Baltic corridor procurement waves. Stabilized platform mechanical engineering talent scarcity constrains new entrant scaling, creating defensive moats for legacy contractors with aging workforce expertise. Capacity addition in Polish domestic gimbal assembly zones through technology transfer agreements secures forward defense posture realignment demand.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in vehicle-mounted thermal imaging offers entry points through AI-enabled target recognition modules that bypass cooled sensor thermal core scarcity. Mechanized infantry vehicle segments represent the most penetrable white space as modular procurement specifications separate sensor payloads from prime contractor capture. Border surveillance procurement consolidation under NATO cooperative frameworks enables volume aggregation plays for compliant system integrators lacking legacy platform integration burdens.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated thermal core manufacturers possessing captive indium antimonide and mercury cadmium telluride detector fabrication lines. Long-term viability over the projection horizon favors suppliers with NATO interoperability certification depth and sovereign manufacturing bases insulated from germanium supply disruption. Acquisition target archetypes include specialist subsystem vendors with STANAG 4695 pre-qualification and established Polish-Baltic corridor relationships. The signal to monitor is US Army next-generation targeting pod unbundling velocity, which determines modular procurement expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Thermal Core Production | Backward integration into indium antimonide fabrication insulates margin from detector supply scarcity. |
| NATO STANAG 4695 Certification Investment | Interoperability testing completion opens Polish and Baltic mechanized vehicle program access. |
| Polish-Baltic Corridor Market Entry | EU Green Deal compliance enables participation in NATO cooperative procurement frameworks. |
| Modular Payload Architecture Development | Unbundled sensor designs capture US Army next-generation targeting pod disaggregation opportunities. |
| Short-Wave Infrared Capability Fielding | Platoon-scale deployment ahead of NATO standardization secures first-mover positioning in situational awareness. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers at NATO member ministries, program managers at land vehicle OEMs, thermal imaging subsystem engineers, and electro-optical component sourcing leads with secondary validation. Defense contract award databases, NATO standardization agreement registries, EU procurement directive filings, and customs trade records for germanium and optical coating precursor flows anchored supply-side assessment. Bottom-up program-level demand aggregation and top-down defense budget allocation analysis provided cross-checking triangulation.
Segment-weighting approaches distributed volume across product type, technology tier, end-user service branch, and application mission profile dimensions, with additional weighting for NATO alignment status and domestic content requirements across the analysis window. CAGRs derived from installed base refresh cycle modeling, platform modernization schedule alignment, and cooperative procurement framework adoption curves. Forecast inputs incorporated EU AI Act human-in-the-loop compliance cost absorption rates and REACH substance restriction reformulation timeline impacts on anti-reflective treatment qualification.
The model assumes a particular technology adoption path; alternative pathways for uncooled sensor convergence with AI-enabled target recognition would alter the outlook if performance gaps close faster than projected. Forecasts reflect documented assumptions regarding NATO standardization agreement ratification schedules and germanium supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Military Jammer Market
Military Surveillance
Global Radar Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market