
 Military Manportable Surveillance Radar Market | 2026-2036
Military Manportable Surveillance Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Military Manportable Surveillance Radar Market Insights
Software-defined radar architecture is fragmenting traditional hardware-centric supply chains into modular component ecosystems. Thales Group leverages its European defense electronics integration depth to sustain long-term service contracts with French and Belgian forces. L3Harris Technologies Inc. anchors North American production capacity for compact gallium nitride transmit-receive modules. Saab AB competes through Nordic interoperability certifications that dominate Baltic procurement frameworks.
Military manportable surveillance radar denotes a transportable, soldier-carried sensor system typically weighing under 35 kilograms, operating in X-band or Ku-band frequencies, and generating real-time ground-moving target indication data for tactical commanders. These systems serve primarily to detect, classify, and track personnel, vehicles, and low-altitude aerial threats in contested electromagnetic environments. Ground Surveillance commands the largest procurement volumes as mechanized infantry brigades replace aging tripod-mounted radars with dismountable alternatives. Synthetic Aperture Radar represents the fastest-expanding technology segment, driven by special operations requirements for all-weather, high-resolution imagery in denied-access zones. Threat Detection applications concentrate margin pools where artificial intelligence-enabled classification algorithms command premium pricing from intelligence agencies.
The US Department of Defense imposes MOSA compliance through the Office of the Secretary of Defense, while EU member states align procurement with the European Defence Agency's Capability Development Plan and NATO's STANAG 4694 interoperability standards. These frameworks shape supplier qualification pathways, software export licensing timelines, and cross-border maintenance network access. Stakeholders must monitor evolving electromagnetic spectrum allocation battles between commercial 5G operators and military radar bands, as spectrum encroachment threatens operational availability in dense urban deployments.
Market Dynamics
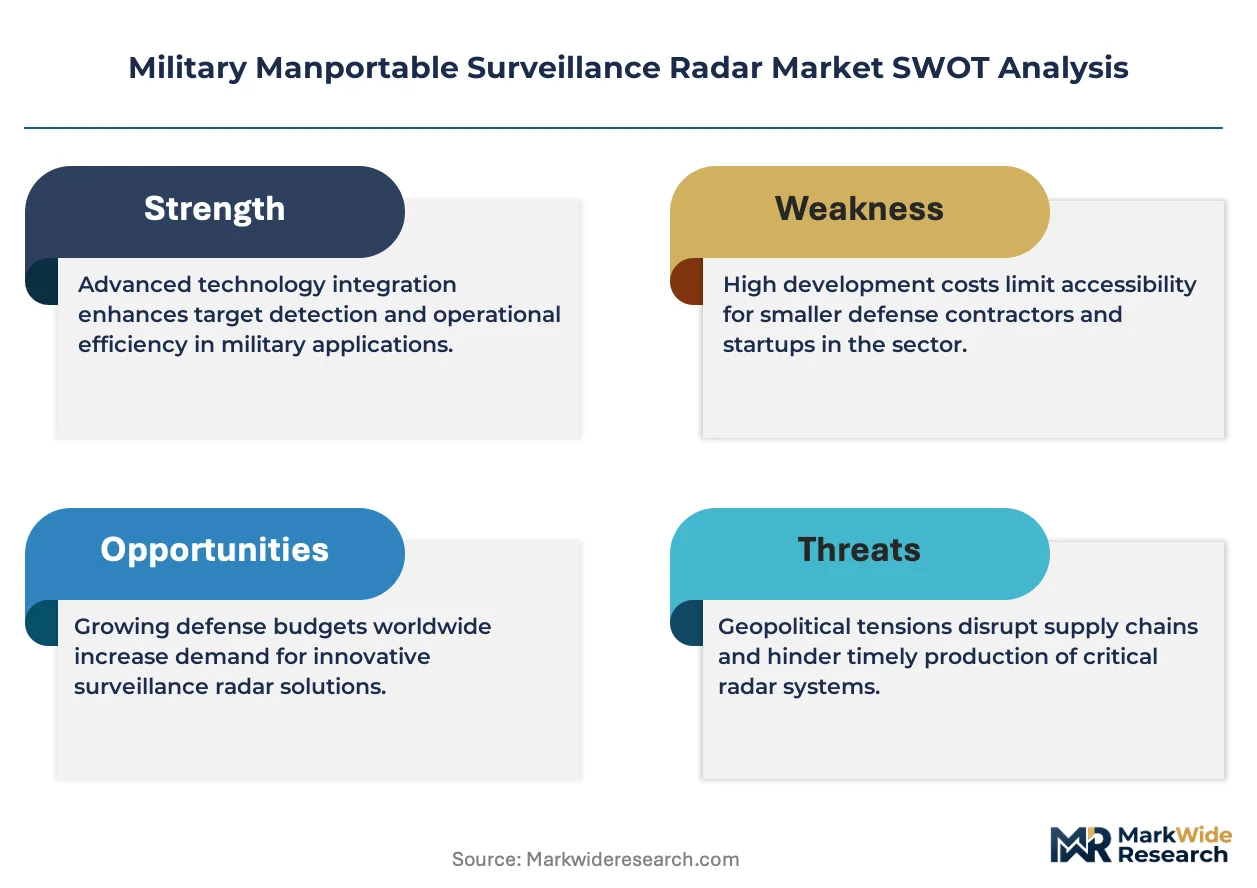
The US Army's Modular Open Systems Approach mandate is fragmenting traditional hardware-centric supply chains into modular component ecosystems, forcing suppliers to rearchitect products for interoperability rather than proprietary lock-in.
Growth Catalysts
- NATO STANAG 4694:Allied standardization for soldier-borne sensor interoperability is accelerating cross-border procurement among frontline member states.
- Special Operations Command:Disaggregated warfare doctrines are driving backpackable radar demand for platoon-level situational awareness in denied terrain.
- Gallium Nitride semiconductors:Wider bandgap materials are enabling higher power density in compact transmit-receive modules, reducing system weight below 35 kilograms.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency on Chinese processing facilities creates input cost volatility and export restriction exposure.
- Spectrum allocation battles:Commercial 5G operators are encroaching on X-band and Ku-band military allocations, compressing operational availability in urban deployments.
- ITAR licensing timelines:US State Department export controls extend software release cycles by 12-18 months, freezing supplier responsiveness to allied urgent operational needs.
Strategic Opportunities
- Poland's territorial defense expansion:Frontline NATO posture investments are creating dedicated procurement streams for dismounted surveillance in eastern border regions.
- AI-enabled target classification:Machine learning inference at the edge is opening premium pricing tiers for intelligence agency threat detection applications.
- European Defence Industrial Strategy:EU joint procurement incentives are consolidating national fragmentations into pooled acquisition frameworks for mid-tier suppliers.
Industry Challenges
- RF engineer scarcity:Specialized microwave circuit design expertise concentrates in defense primes, constraining mid-tier vendor scaling.
- MOSA compliance requalification:Legacy system architectures require complete software stack rewrites to meet open interface mandates, absorbing 18-24 month development cycles.
- Cross-domain integration complexity:Ground surveillance radars must now interface with soldier-worn networks, aerial layers, and command cloud architectures simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Manportable Surveillance Radar Market |
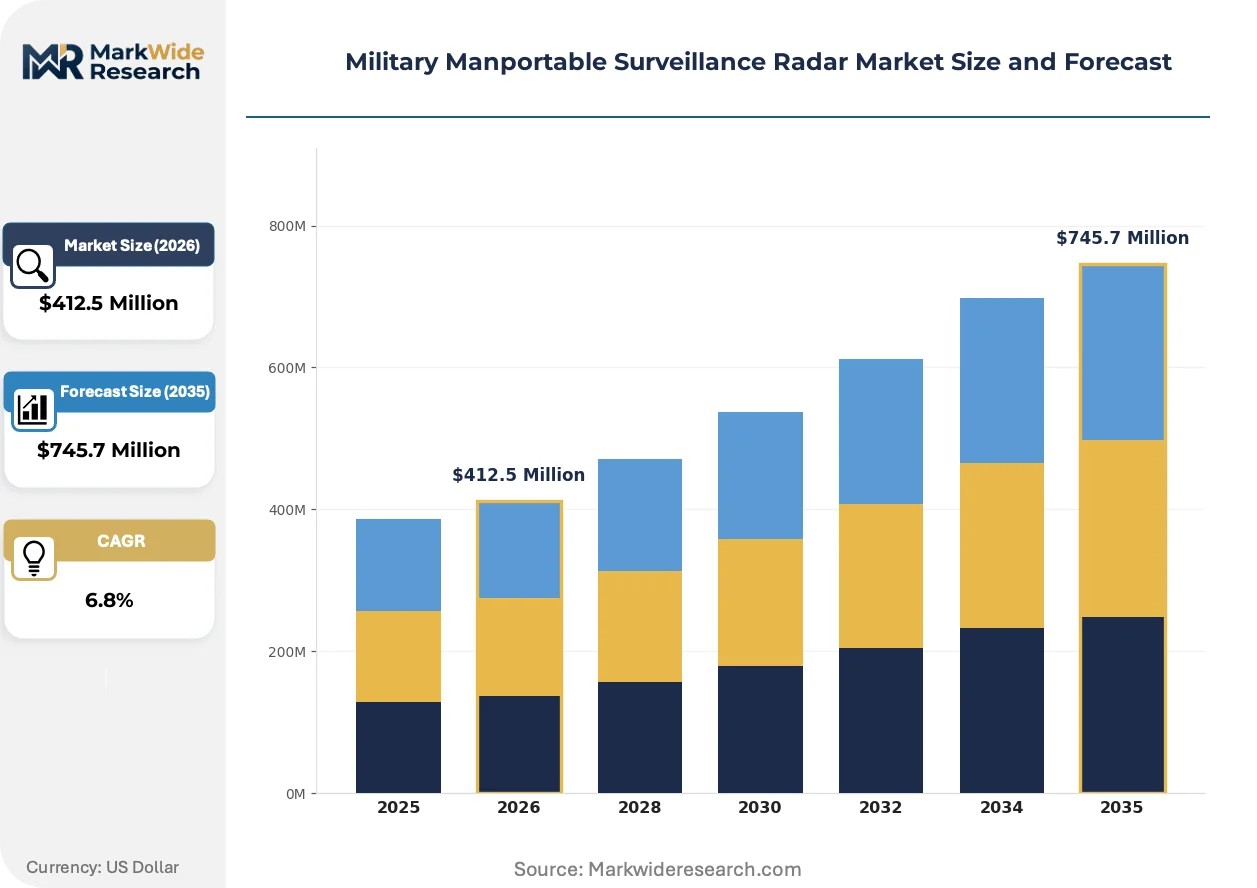
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Surveillance, Airborne Surveillance, Coastal Surveillance, Border Surveillance, Perimeter Security Technology: Doppler Radar, Synthetic Aperture Radar, Phased Array Radar, Pulse-Doppler Radar, Continuous Wave Radar Application: Reconnaissance, Target Acquisition, Threat Detection, Force Protection, Tactical Surveillance End User: Army Units, Special Forces, Border Patrol, Maritime Security, Intelligence Agencies |
| Companies Covered | Thales Group, L3Harris Technologies Inc., Lockheed Martin Corporation, Saab AB, Leonardo S.p.A., Raytheon Technologies Corporation, BAE Systems Plc, Israel Aerospace Industries Ltd., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Manportable Surveillance Radar Market Trends and Innovations
Software-defined architectures are decoupling hardware from signal processing, enabling field-upgradeable capabilities that extend platform service life without physical retrofit. This shift is compressing supplier margins on replacement hardware while expanding recurring software revenue pools.
Synthetic Aperture Radar processing is migrating from dedicated FPGA arrays to general-purpose GPU clusters with firmware abstraction layers. Special operations units in denied-access zones are adopting these reconfigurable systems for all-weather high-resolution imagery. The technology is migrating from classified special mission platforms to standard infantry brigade equipment, collapsing the historical performance tiering between elite and conventional forces.
The European Defence Agency's Capability Development Plan is mandating European-sourced critical components for PESCO-funded programs. This industrial consequence is redirecting supply chain qualification pathways toward continental semiconductor foundries and away from non-EU sources. Baltic procurement frameworks are responding fastest, with Nordic interoperability certifications becoming de facto prerequisites for vendor shortlisting.
Buyer organizations are unbundling hardware acquisition from sustainment services, compressing initial contract values while elongating vendor revenue recognition timelines. Defense ministries in Germany and the United Kingdom are leading this disaggregation, separating platform purchase from 10-year logistics support. Poland's territorial defense forces represent the sharpest geographic manifestation, where conscript-heavy units demand simplified operator interfaces and remote technical support models.
Military Manportable Surveillance Radar Market Segmentation
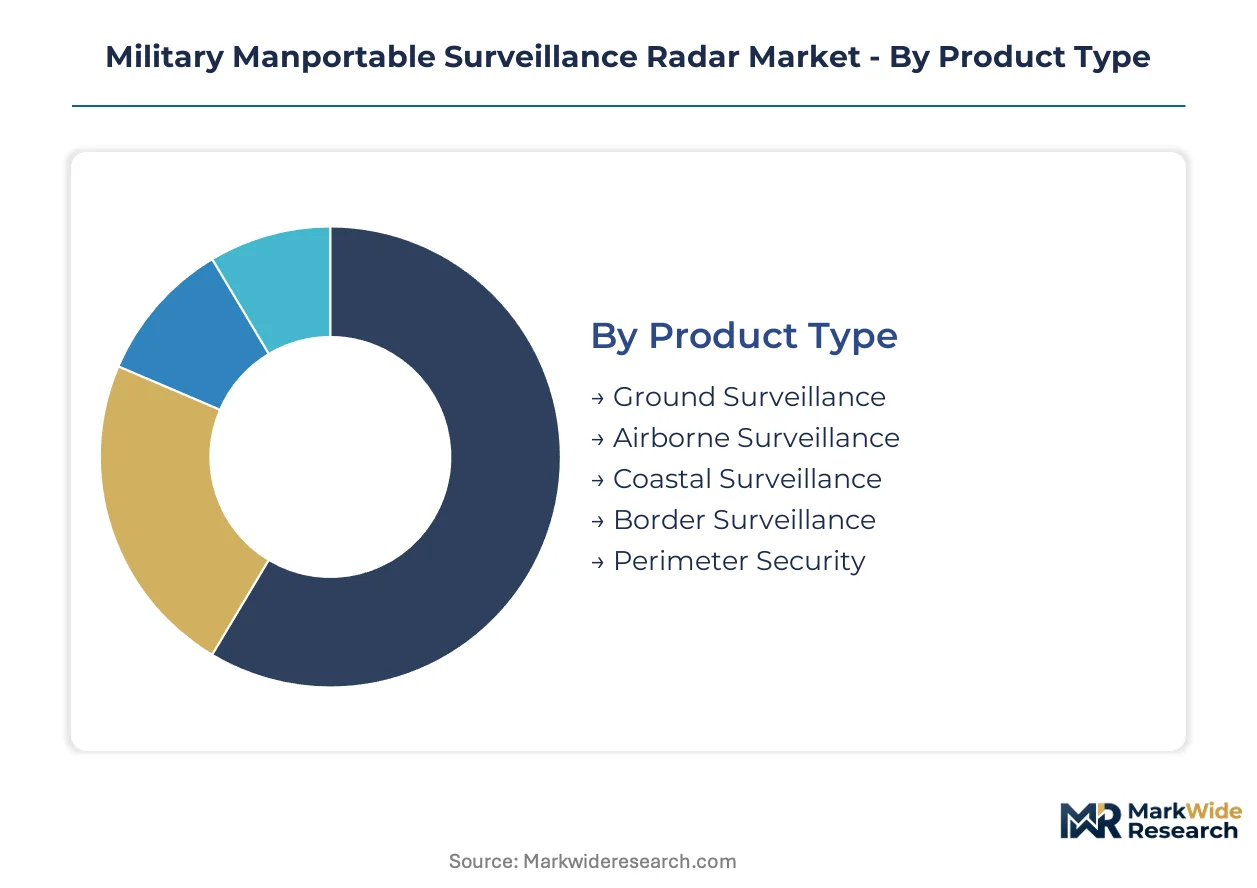
Segmentation in military manportable surveillance radar reveals distinct procurement patterns across operational domains. Force structure requirements and threat environment specificity drive technology selection more than unit cost considerations.
Product Type:
Use-case spectrum spans dismounted infantry patrols to fixed-site perimeter defense, with weight and power constraints dictating platform suitability.
- Ground Surveillance:These systems detect personnel and vehicle movement across open terrain using X-band or Ku-band frequencies. Mechanized infantry brigades in Germany and Poland are replacing aging tripod-mounted units with backpackable alternatives for dismounted operations.
- Airborne Surveillance:Compact radars designed for small unmanned aerial platforms or aerostat tethering. Special operations units across NATO frontline states are accelerating procurement for low-altitude threat monitoring in contested electromagnetic environments.
- Coastal Surveillance:Marine-hardened variants with salt-corrosion resistance and stabilized antenna mounts. Maritime security forces deploy these for small-craft detection in littoral zones.
- Border Surveillance:Extended-range systems optimized for linear barrier monitoring. Polish territorial defense forces represent concentrated demand for eastern border coverage.
- Perimeter Security:Fixed-site or rapidly emplaceable units for forward operating base protection. Intelligence agencies prioritize these for classified facility coverage.
Established volume favors Ground Surveillance; emerging adoption favors Airborne Surveillance.
Technology:
Signal processing architecture determines performance ceilings and upgrade pathways more than antenna hardware specifications.
- Doppler Radar:Measures frequency shift to calculate target velocity and direction. Legacy systems dominate maintenance contract portfolios across European land forces.
- Synthetic Aperture Radar:Generates high-resolution imagery through platform motion compensation. Special operations requirements for all-weather reconnaissance in denied-access zones are expanding procurement fastest.
- Phased Array Radar:Electronic beam steering eliminates mechanical antenna movement. Gallium nitride transmit-receive modules are reducing weight below 35-kilogram thresholds.
- Pulse-Doppler Radar:Combines range measurement with velocity discrimination for clutter rejection. Ground surveillance applications in wooded terrain favor this modality.
- Continuous Wave Radar:Uninterrupted transmission enables low-probability-of-intercept operation. Intelligence agency technical collection units specify these for covert deployment.
Hardware-centric procurement favors Doppler and Pulse-Doppler; software-defined migration favors Synthetic Aperture and Phased Array.
Application:
Mission profile determines sensor configuration, with artificial intelligence integration creating pricing stratification across intelligence versus conventional military users.
- Reconnaissance:Wide-area search and route survey capabilities for advance force operations. Special Forces platoons prioritize lightweight systems for extended dismounted patrols.
- Target Acquisition:Precision location for indirect fire or air support coordination. Artillery observer teams in mechanized brigades drive standardization requirements.
- Threat Detection:Automated classification algorithms for personnel, vehicles, and low-altitude aerial systems. AI-enabled variants command premium pricing from intelligence agencies.
- Force Protection:Perimeter and convoy security with rapid emplacement protocols. Base defense units favor simplified operator interfaces.
- Tactical Surveillance:Real-time situational awareness for company-level commanders. NATO STANAG 4694 interoperability mandates are shaping procurement specifications.
Volume procurement concentrates in Tactical Surveillance and Force Protection; margin expansion concentrates in Threat Detection.
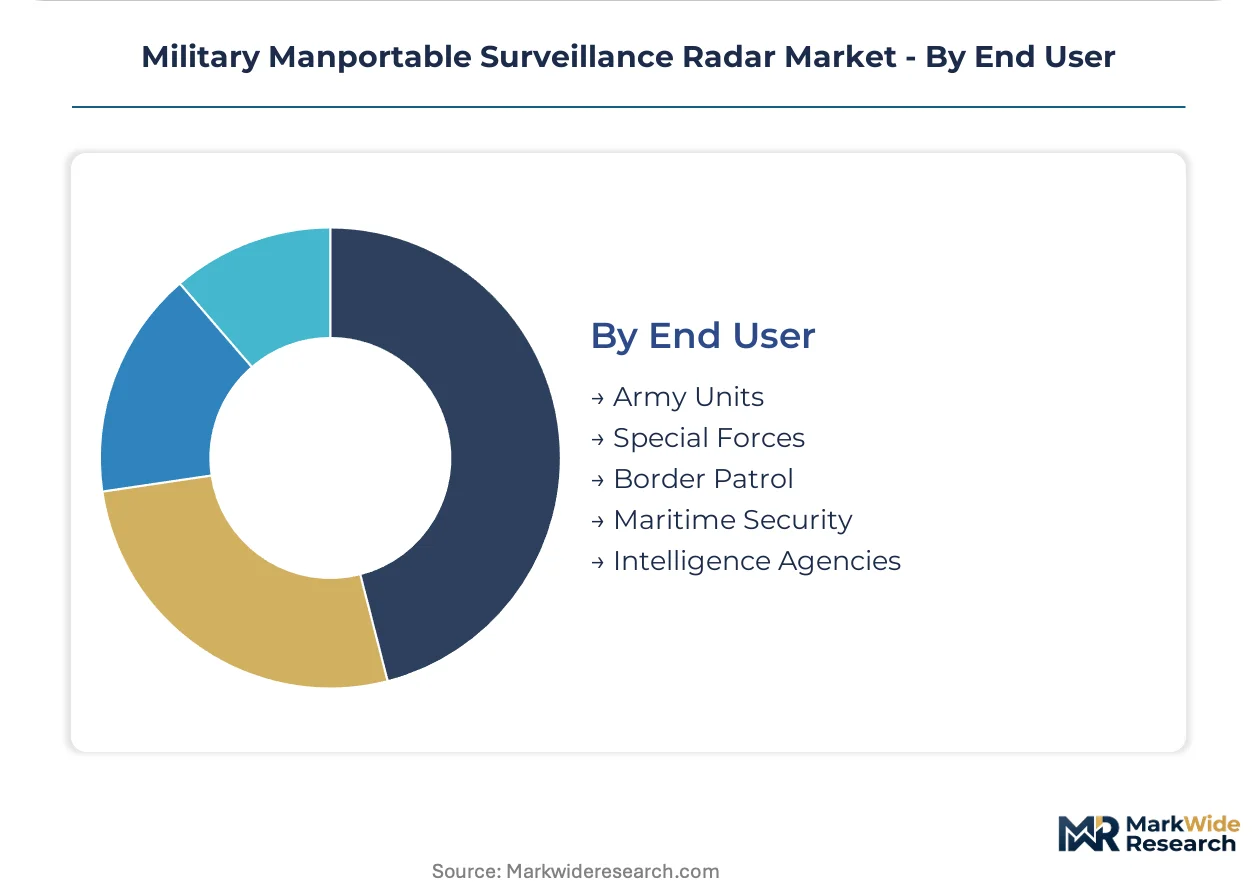
End User:
Organizational culture and funding authority create distinct requirement sets across conventional and specialized formations.
- Army Units:Mechanized and light infantry brigades with standardized equipment tables. The US Army's MOSA mandate is forcing interoperability upgrades across supplier networks.
- Special Forces:Disaggregated warfare doctrine drives backpackable system demand for platoon-level situational awareness. Nordic interoperability certifications dominate Baltic procurement frameworks.
- Border Patrol:Extended deployment cycles and conscript operator pools demand ruggedized simplicity. Polish territorial defense expansion is creating dedicated procurement streams.
- Maritime Security:Coastal and port protection units with marine environmental hardening requirements.
- Intelligence Agencies:Technical collection units with classified performance specifications and minimal logistics footprints.
Procurement volume aggregates with Army Units; technology premium concentrates with Intelligence Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German radar component exports supply Polish and Baltic territorial defense units confronting eastern border surveillance requirements. Cross-border procurement flows concentrate along NATO's eastern flank, where frontline member states source modular systems from established European defense electronics clusters.
United States
The US Army's MOSA mandate drives interoperability upgrades across supplier networks for mechanized infantry brigades. The Office of the Secretary of Defense enforces open systems compliance through acquisition regulations, compressing proprietary lock-in timelines. Gallium nitride foundries in North Carolina and Texas anchor compact transmit-receive module production for sub-35-kilogram systems.
Germany
Mechanized brigades in Lower Saxony and Bavaria replace aging tripod-mounted radars with dismountable alternatives for dismounted operations. The Federal Office of Bundeswehr Equipment aligns procurement with NATO STANAG 4694 standards and European Defence Agency capability roadmaps. Defense electronics integration clusters around Munich and Ulm sustain long-term service contracts with French and Belgian forces.
Poland
Territorial defense expansion along eastern border regions creates dedicated procurement streams for conscript-operable surveillance systems. The Ministry of National Defence channels EU joint procurement incentives into pooled acquisition frameworks for mid-tier suppliers. Industrial partnerships in Warsaw and Krakow concentrate on simplified operator interfaces and remote technical support models.
United Kingdom
Special Forces units accelerate backpackable system adoption for platoon-level situational awareness in denied terrain. The Ministry of Defence unbundles hardware acquisition from sustainment services, separating platform purchase from decade-long logistics support. Defense technology corridors in Greater London and the South West anchor system integration for intelligence agency threat detection applications.
Military Manportable Surveillance Radar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across modular component ecosystems forced by interoperability mandates. The vendor base organizes into three tiers: integrated defense primes with sustainment networks, component specialists with gallium nitride foundry access, and software-defined architecture firms with AI-enabled classification capabilities. Consolidation pressures concentrate around MOSA compliance requalification costs and cross-domain integration complexity. Dominant competitive moves include backward integration into semiconductor supply chains and geographic expansion into Baltic procurement frameworks.
Within the integrated prime tier, Thales Group and Saab AB exemplify European defense electronics positioning through Nordic interoperability certifications and continental service networks. L3Harris Technologies Inc. anchors North American production capacity for compact transmit-receive modules. These three entities represent divergent geographic anchoring strategies—French-Belgian, Nordic-Baltic, and US-domestic—each occupying positions within fragmented but consolidating national procurement frameworks.
| Leading Market Players |
|---|
| Thales Group |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Saab AB |
| Leonardo S.p.A. |
| Raytheon Technologies Corporation |
| BAE Systems Plc |
| Israel Aerospace Industries Ltd. |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Raleigh-Durham's gallium nitride foundry cluster anchors North American transmit-receive module capacity, translating semiconductor fabrication bottlenecks directly into pricing power for compact radar systems. Defense primes with captive foundry access command premium positioning against component-dependent competitors.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate procurement frameworks for military manportable surveillance radar systems. Three-tier pricing structure across premium, standard, and economy levels separates MOSA-compliant open-architecture systems from legacy proprietary platforms and conscript-operable simplified units. Pricing pressure stems from EU joint procurement incentives consolidating national fragmentations into pooled acquisition frameworks. Intelligence agencies exhibit lowest price sensitivity for AI-enabled threat detection variants, while Polish territorial defense forces drive economy-tier volume procurement.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for rare earth magnet inputs. Neodymium processing concentrates in Chinese facilities, while gallium nitride wafer production clusters in the United States, Taiwan, and Germany. RF semiconductor fabrication draws from specialized defense-qualified foundries with limited commercial crossover. Distribution runs through prime contractor sustainment networks rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through EU joint procurement frameworks and NATO pooled acquisition mechanisms, fragmenting national vendor relationships into consolidated multi-country tenders.
For Market Incumbents: Pre-empt MOSA compliance requalification costs by accelerating software stack rewrites before mandate deadlines compress competitive timelines. Backward integration into gallium nitride foundry capacity anchors supply security against rare earth magnet volatility. Channel control through long-term service contracts with French and Belgian forces defends position against Nordic interoperability certification challengers. For New Entrants and Emerging Players: Build out AI-enabled target classification capabilities for intelligence agency threat detection applications, the most penetrable premium segment. Polish territorial defense expansion offers geographic white space for conscript-operable simplified interfaces. Go-to-market through remote technical support models bypasses prime contractor sustainment network lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined architecture firms with firmware abstraction layer capabilities over hardware-centric legacy suppliers. Long-term viability across the projection horizon hinges on cross-domain integration complexity management. Watch NATO STANAG 4694 certification velocity as inflection indicator for vendor shortlisting access.| Strategic Initiative | Industry Significance |
|---|---|
| MOSA Compliance Acceleration | Open-architecture requalification unlocks NATO procurement frameworks and extends platform service life. |
| Gallium Nitride Foundry Investment | Captive transmit-receive module production reduces weight thresholds and insulates against rare earth volatility. |
| AI Classification Algorithm Development | Machine learning inference at the edge commands premium pricing from intelligence agency buyers. |
| Nordic Interoperability Certification | Baltic procurement frameworks treat Swedish and Finnish standards as de facto prerequisites for vendor shortlisting. |
| Remote Technical Support Model | Conscript-heavy territorial defense units in Poland demand simplified operator interfaces with centralized expertise access. |
Research Methodology
A spread of perspectives from radar systems program managers, RF semiconductor procurement leads, defense electronics integration engineers, and territorial defense equipment officers converged on the working assumptions. Primary fieldwork combined with secondary validation against NATO STANAG documentation, European Defence Agency capability roadmaps, and Office of the Secretary of Defense acquisition regulations. Customs data on gallium nitride wafer trade flows, SEC filings from defense primes, and EU joint procurement award notices anchored quantitative triangulation. Bottom-up unit economics and top-down defense budget allocation analysis were cross-referenced for convergence.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, signal processing architecture, mission application, and end-user organizational culture. CAGRs were derived from defense procurement pipeline visibility and technology substitution elasticity estimates. Gallium nitride semiconductor cost curves and MOSA compliance adoption timelines served as industry-specific forecast inputs.
Stress conditions across rare earth export restriction scenarios, spectrum allocation encroachment severity, and ITAR licensing timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on defense budget trajectory and alliance procurement coordination. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Tactical Optics Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
UXO Detection Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Jammer Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Military Radar Market