
 Maritime Surveillance Market | 2026-2036
Maritime Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Surveillance Market Analysis
Defense procurement channels is tilting toward multi-domain maritime awareness contracts that bundle satellite feeds, autonomous surface vessels, and shore-based command centers. Lockheed Martin leverages its Aegis combat system integration heritage to anchor naval force modernization programs across multiple allied fleets. Kongsberg Gruppen specializes in underwater acoustics and naval strike missile systems, sustaining its stronghold in Nordic and NATO submarine surveillance architectures.
Maritime surveillance encompasses the systematic detection, tracking, identification, and classification of surface and subsurface vessels through integrated sensor networks operating across radar, acoustic, electro-optical, and satellite spectra, typically processed at refresh rates under ten seconds for real-time threat assessment. Its primary purpose centers on securing territorial waters, protecting commercial shipping lanes, and enabling rapid response to environmental or security incidents. Radar Systems and Satellite Imagery command the largest share of technology budgets due to their all-weather coverage and wide-area persistence, while Sonar Systems retains premium margins in anti-submarine warfare where technical barriers remain steep. Aerial and Hybrid deployment modes attract accelerated investment as unmanned platforms extend dwell times beyond manned patrol limits.
The US Coast Guard's SAR modernization mandates and NATO STANAG interoperability standards shape sensor procurement specifications, while the EU Maritime Security Strategy and national coast guard authorities across member states enforce cross-border data-sharing protocols. These frameworks compel vendors to certify platforms for multi-national task force integration, raising compliance costs but locking out non-compliant suppliers. Stakeholders must weigh the trade-off between proprietary sensor architectures and the strategic advantage of alliance-certified open systems.
Market Dynamics
Defense procurement channels are tilting toward multi-domain maritime awareness contracts that bundle satellite feeds, autonomous surface vessels, and shore-based command centers into unified operational architectures.
Growth Catalysts
- NATO STANAG Interoperability Mandates:Allied naval forces require certified sensor platforms capable of seamless data exchange during joint operations, compelling fleet-wide upgrades across member states.
- US Coast Guard SAR Modernization:Search and rescue fleet recapitalization programs mandate integrated radar and electro-optical suites for extended offshore coverage.
- Indo-Pacific Littoral Tensions:Coastal states from Vietnam to Indonesia prioritize persistent domain awareness through layered shore-based and aerial sensor networks.
Market Restraints
- Gallium Nitride Supply Concentration:Advanced radar transmitter modules depend on Chinese-processed rare earth substrates, creating single-source vulnerability for AESA system manufacturers.
- ITAR Classification Barriers:US State Department export controls restrict acoustic processing algorithms and synthetic aperture radar modes to cleared allied operators, fragmenting addressable demand.
- Submarine Signature Database Asymmetry:Proprietary acoustic intelligence repositories held by US and UK navies prevent third-party sonar vendors from achieving classification accuracy parity.
Strategic Opportunities
- Philippine Archipelagic Security Gap:The Philippine Navy's limited offshore patrol vessel fleet creates demand for shore-based over-the-horizon radar and unmanned aerial system leasing arrangements.
- Synthetic Aperture Lidar Fusion:Converging electro-optical and photonic technologies enable through-foliage coastal vessel detection previously requiring multi-sensor correlation.
- EU Maritime Security Strategy Data-Sharing Protocols:Cross-border surveillance information exchange mandates open architecture certification pathways for non-traditional sensor vendors.
Industry Challenges
- Acoustic Intelligence Analyst Shortage:Naval sonar operator training pipelines produce insufficient personnel to crew expanding passive surveillance arrays across Nordic and Baltic fleets.
- Multi-Sensor Correlation Latency:Fusing radar, AIS, and electro-optical tracks into single coherent pictures requires sub-ten-second processing that stresses legacy command-and-control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Surveillance Market |
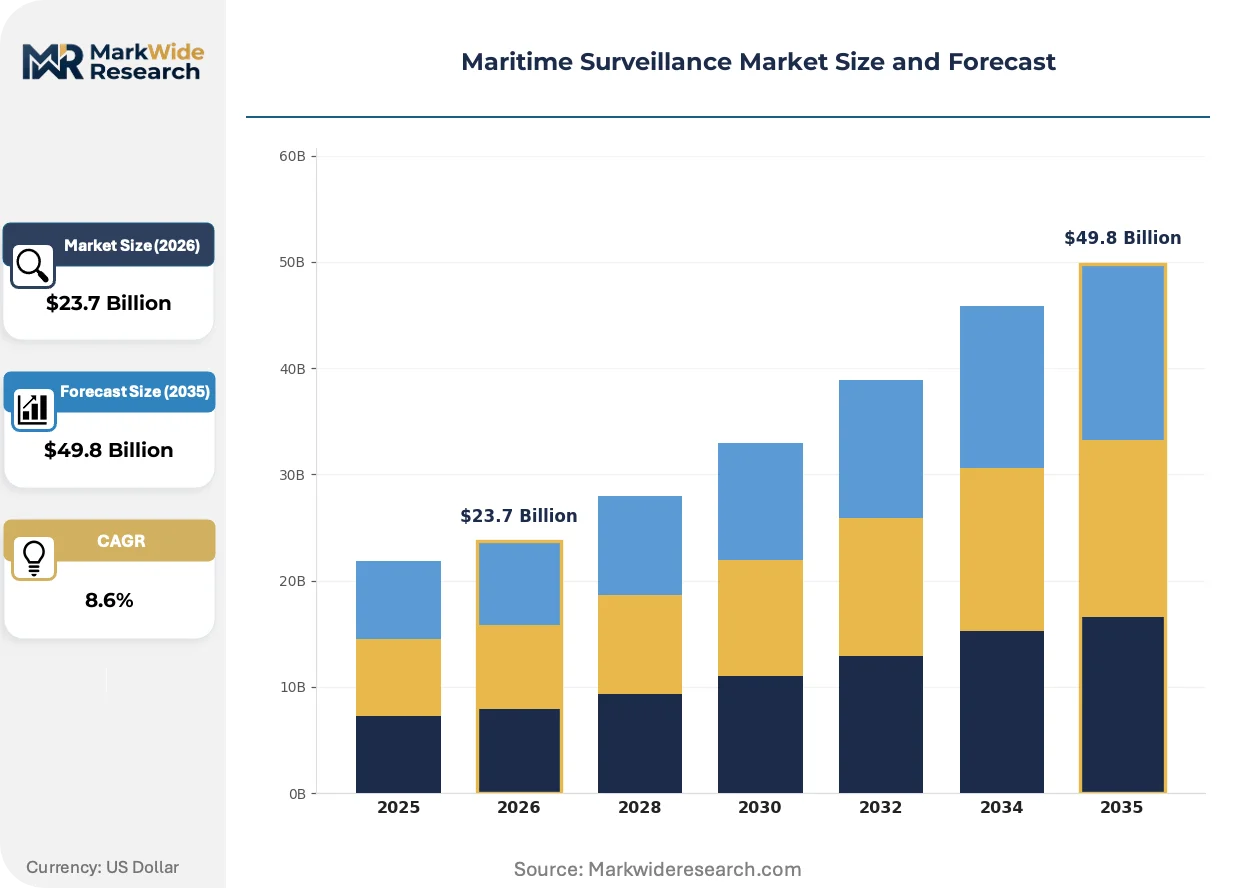
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, Sonar Systems, AIS, Satellite Imagery Deployment: Onshore, Offshore, Aerial, Hybrid Application: Coastal Monitoring, Search & Rescue, Fisheries Management, Harbor Security End User: Naval Forces, Coast Guard, Commercial Shipping, Research Institutions |
| Companies Covered | Lockheed Martin Corporation, Kongsberg Gruppen ASA, Northrop Grumman Corporation, L3Harris Technologies Inc., Elbit Systems Ltd., Raytheon Technologies Corporation, Saab AB, Indra Sistemas S.A., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Surveillance Market Emerging Trajectories
Maritime surveillance architectures are converging toward autonomous platform swarms and edge-processed sensor feeds that compress detection-to-intervention timelines from hours to minutes.
Artificial intelligence-based target classification algorithms are digitizing acoustic and radar signal processing workflows that previously demanded trained operator interpretation. Nordic submarine forces are deploying these tools for real-time threat prioritization during under-ice operations. The technology is digitizing sonar maintenance schedules by predicting transducer degradation before performance thresholds breach.
The EU AI Act's high-risk system classification requirements are imposing conformity assessment obligations on autonomous maritime patrol platforms operating in European Economic Area waters. Vendors must now document algorithmic decision trails for target identification outputs used in law enforcement contexts. Coastal surveillance procurements in France, Germany, and the Netherlands now specify explainable AI certification as a technical compliance gate.
Buyers are consolidating sensor procurement under multi-year availability contracts that bundle hardware, software updates, and operator training into fixed annual fees. Traditional equipment purchase models with separate maintenance agreements are losing share to integrated service offerings in UK and Australian naval programs. The Royal Australian Navy's offshore patrol vessel fleet exemplifies this shift, embedding contractor logistics support within platform acquisition structures.
Maritime Surveillance Market Segmentation
Maritime surveillance procurement cycles vary dramatically across technology layers, with sensor hardware refresh intervals stretching to fifteen years while software-defined processing suites upgrade annually. Understanding these differential replacement rhythms enables vendors to structure service revenue streams and predict contract renewal windows with precision.
Technology:
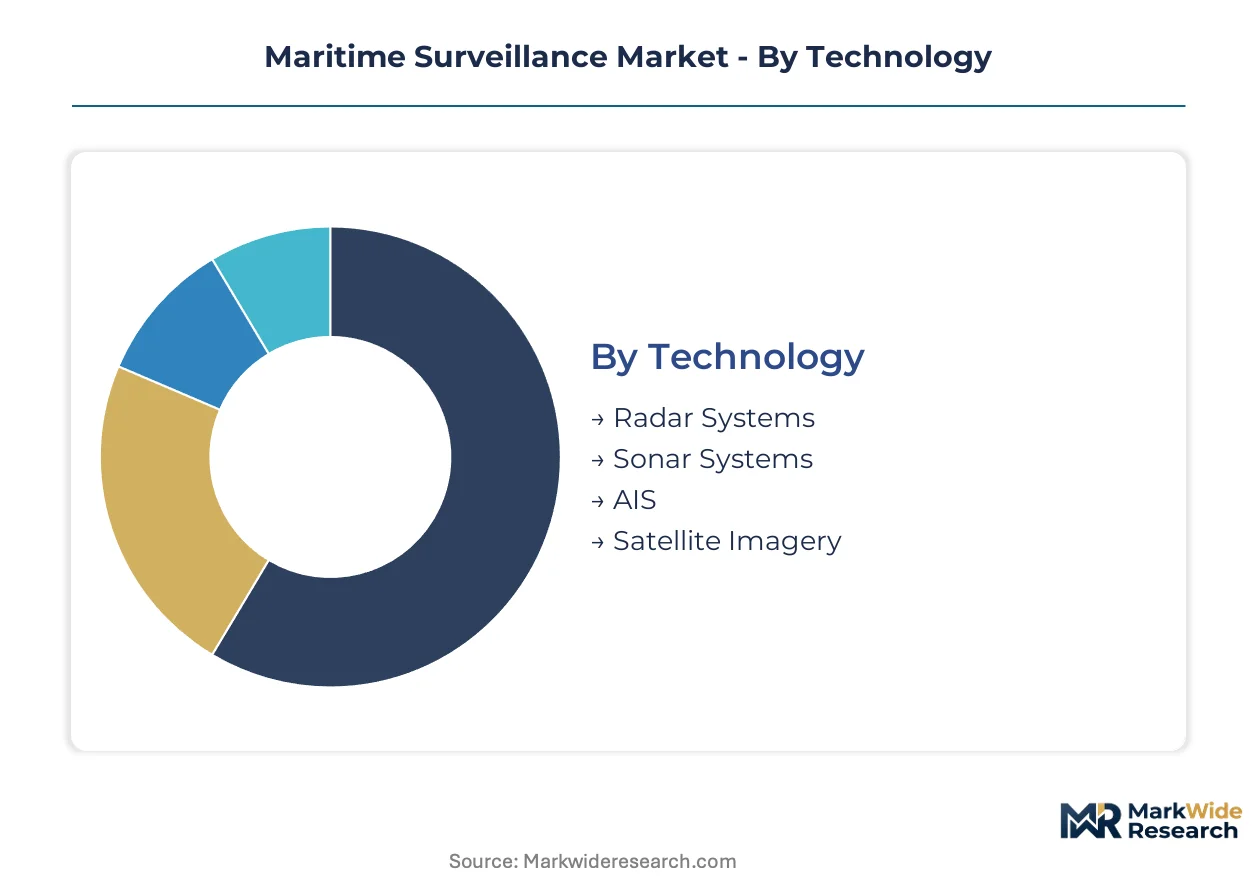
Radar Systems and Satellite Imagery platforms operate on the longest procurement cycles given capital intensity and platform integration complexity, while AIS transponders and software-based acoustic processing turn over fastest through modular upgrade paths.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit-receive modules deliver all-weather surface detection out to 200 nautical miles. NATO naval forces and coast guards across Norway, Poland, and Romania drive replacement demand as Soviet-era magnetron systems reach obsolescence.
- Satellite Imagery:Synthetic aperture radar and electro-optical constellations provide persistent wide-area coverage independent of atmospheric conditions. Commercial shipping operators and fisheries enforcement agencies in the Mediterranean and South China Sea corridor subscribe to multi-sensor fusion services for route optimization and illegal fishing detection.
- Sonar Systems:Hull-mounted and towed array configurations dominate anti-submarine warfare architectures.
- AIS:Automatic Identification System transponders and receivers form the maritime traffic data backbone.
Radar Systems anchors the volume base while Satellite Imagery gains share at the steepest rate.
Deployment:
Cost tier differentiation separates capital-intensive offshore patrol vessels from rapidly deployable unmanned aerial platforms, with hybrid architectures commanding premium pricing through multi-domain integration complexity.
- Onshore:Coastal radar towers, command centers, and shore-based electro-optical sites provide persistent territorial water coverage. Vietnam, Indonesia, and the Philippines prioritize these fixed installations where archipelagic geography multiplies monitoring requirements across dispersed coastlines.
- Offshore:Patrol vessels, autonomous surface vehicles, and seabed sensor networks extend surveillance into exclusive economic zones. Nordic submarine forces and allied ASW task groups invest here for under-ice and deep-water acoustic tracking capabilities.
- Aerial:Manned maritime patrol aircraft and long-endurance unmanned aerial systems deliver rapid response and over-the-horizon detection.
- Hybrid:Integrated architectures combining shore, sea, and air layers into unified operational pictures.
Onshore deployments dominate current installed base while Hybrid configurations expand most quickly through NATO interoperability mandates.
Application:
Customer maturity varies sharply across mission types, with harbor security representing established compliance-driven demand and fisheries management emerging as policy-forced growth territory.
- Coastal Monitoring:Persistent domain awareness for territorial water integrity and smuggling interdiction. Baltic and Black Sea littoral states under EU Maritime Security Strategy obligations drive sensor density increases.
- Search & Rescue:US Coast Guard modernization mandates and allied SAR fleet recapitalizations prioritize integrated radar and thermal imaging for extended offshore coverage.
- Fisheries Management:Illegal, unreported, and unregulated fishing detection through AIS correlation and satellite monitoring.
- Harbor Security:Port facility defense against intrusion, sabotage, and trafficking threats.
Harbor Security anchors the volume base while Fisheries Management climbs the fastest as regulatory enforcement tightens.
End User:
Procurement authority fragmentation creates distinct sales cycles, with naval forces operating on multi-year defense budget horizons and commercial shipping responding to insurance and charter market pressures.
- Naval Forces:Integrated combat system procurement for fleet-wide situational awareness and anti-submarine warfare. Allied NATO members and Indo-Pacific partners fund these programs through collective security frameworks.
- Coast Guard:Civil maritime security and law enforcement platform acquisition. US Coast Guard, Japan Coast Guard, and EU member state agencies balance SAR, environmental protection, and border control missions.
- Commercial Shipping:Vessel-mounted AIS, radar, and voyage data recorders driven by SOLAS compliance and insurance requirements.
- Research Institutions:Oceanographic and climate monitoring sensor networks.
Naval Forces anchors the volume base while Coast Guard segments show the steepest expansion trajectory through fleet recapitalization waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification requirements for unmanned aerial surveillance platforms intersect with US Coast Guard procurement mandates, establishing regulatory precedent that shapes allied fleet modernization timelines across NATO member states and Indo-Pacific partner nations.
United States
The US Coast Guard's SAR fleet recapitalization and Navy integrated sensor network programs drive procurement volume. FAA Part 107 waivers for beyond-visual-line-of-sight drone operations enable contractor logistics support models. Norfolk Naval Shipyard and Pascagoula Marine clusters concentrate platform integration work for littoral combat ship surveillance suites.
United Kingdom
Royal Navy submarine surveillance architecture upgrades and fisheries enforcement satellite monitoring contracts expand addressable demand. The UK Maritime and Coastguard Agency mandates AIS integration for coastal patrol vessels. Clyde naval base and Plymouth Sound facilities anchor sonar system maintenance and acoustic intelligence analyst training pipelines.
Germany
Nordic-Baltic ASW task force commitments and North Sea offshore wind farm security requirements elevate sensor density needs. KBA maritime safety regulations enforce voyage data recorder standards for commercial fleet interoperability. Kiel and Wilhelmshaven naval clusters concentrate towed array manufacturing and hull-mounted sonar integration.
Japan
Japan Coast Guard offshore patrol vessel expansion and Senkaku Islands domain awareness priorities accelerate aerial and hybrid deployment procurement. METI subsidies for autonomous maritime platform development reduce domestic manufacturer R&D risk. Yokosuka naval base and Kure shipyard clusters sustain integrated combat system upgrade cycles.
Australia
Royal Australian Navy offshore patrol vessel availability contracting and AUKUS submarine surveillance information sharing obligations reshape procurement structures. TGA-equivalent defense export certification requirements filter vendor participation in sovereign shipbuilding programs. Henderson shipyard and Osborne naval shipbuilding precinct concentrate platform delivery and through-life support integration.
Maritime Surveillance Market Vendor Landscape
Systems integrators and subsystem specialists split the market along platform ownership boundaries. Tiered supplier structures concentrate at the prime contractor level where multi-year availability contracts lock in decade-long revenue streams. Three archetypes dominate: combat system integrators with naval force heritage, acoustic and sensor specialists with undersea warfare focus, and emerging autonomy vendors with unmanned platform portfolios. Competitive moves center on alliance certification capture and sovereign shipyard joint ventures that embed contractors within national procurement frameworks.
Within the combat system integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify archetypes leveraging Aegis heritage and airborne surveillance platforms respectively to anchor allied fleet modernization. Kongsberg Gruppen ASA occupies a specialized position representing Nordic acoustic and naval strike system expertise that sustains stronghold positioning in submarine surveillance architectures. These three entities illustrate how geographic origin and historical program participation shape competitive access to NATO STANAG-certified procurement channels.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Kongsberg Gruppen ASA |
| Northrop Grumman Corporation |
| L3Harris Technologies Inc. |
| Elbit Systems Ltd. |
| Raytheon Technologies Corporation |
| Saab AB |
| Indra Sistemas S.A. |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Gallium nitride supply concentration in Chinese rare earth processing facilities determines both AESA radar module pricing spreads and defense contractor sourcing strategies. ITAR classification barriers fragment procurement channels into cleared-allied and restricted tiers, compressing margins for non-compliant vendors while inflating customization premiums for certified platforms.
Pricing Analysis
Configured-to-order AESA radar suites command three-to-five-fold premiums over standard magnetron replacements due to NATO STANAG certification requirements and gallium nitride transmitter integration. Three-tier pricing structure across sovereign-certified, allied-compliant, and commercial-off-the-shelf levels reflects divergent compliance investment recovery timelines. Cost compression in the commercial tier intensifies because fisheries enforcement agencies and port authorities prioritize lowest-compliant-bid procurement. Naval forces demonstrate least price sensitivity due to availability contracting structures that bundle hardware, software updates, and operator training into fixed annual fees.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor substrate suppliers dominates supply chain risk planning for AESA radar manufacturers. Gallium nitride wafers, rare earth magnet assemblies, and acoustic transducer ceramics draw from Chinese, Japanese, and US production clusters. Single-source vulnerability in Chinese-processed rare earth substrates threatens transmitter module output consistency. Distribution runs through prime contractor logistics support networks embedded within national shipyard maintenance schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat structure where NATO STANAG certification creates switching costs that lock allied navies into decade-long availability contracts. Network effects compound through acoustic intelligence database accumulation that prevents third-party sonar vendors from achieving classification parity.
For Market Incumbents: Entrench position by deepening sovereign shipyard joint ventures in Australia, Norway, and Japan that embed contractors within AUKUS and NATO procurement frameworks. Acquire specialized autonomy vendors with unmanned surface vessel portfolios before emerging players achieve EU AI Act explainable certification. Lockheed Martin and Kongsberg Gruppen demonstrate this path through platform integration heritage and Nordic acoustic expertise respectively. For New Entrants and Emerging Players: Philippine archipelagic security gaps offer the most penetrable white-space target, where limited offshore patrol vessel fleets create demand for shore-based over-the-horizon radar leasing and unmanned aerial system service contracts. Synthetic aperture lidar fusion technologies enable through-foliage coastal detection previously requiring multi-sensor correlation, opening non-traditional vendor pathways. Pursue EU Maritime Security Strategy data-sharing protocol certification to bypass prime contractor lock-in. For Investors and Strategic Acquirers: The market sits at a fleet recapitalization phase that favors acoustic intelligence specialists and autonomous platform developers over traditional hardware manufacturers. Five-to-ten year viability hinges on AI-enabled target classification algorithm portfolios that satisfy EU AI Act high-risk system conformity requirements. Watch for FAA Part 107 waiver expansion signals that would accelerate beyond-visual-line-of-sight drone logistics support adoption.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Investment | Opens NATO allied fleet procurement channels previously restricted to heritage combat system integrators. |
| Autonomous Platform Swarm Development | Compresses detection-to-intervention timelines from hours to minutes for Indo-Pacific littoral monitoring. |
| Sovereign Shipyard Joint Venture | Embeds contractors within national procurement frameworks like Australia's Henderson and Osborne precincts. |
| Acoustic Intelligence Database Accumulation | Builds proprietary signature repositories that prevent third-party sonar vendors from achieving classification parity. |
| EU AI Act Explainable AI Certification | Enables autonomous maritime patrol platform sales to France, Germany, and Netherlands coast guard agencies. |
Methodological Framework
A standing panel of naval program executives, coast guard procurement officers, sonar system engineers, and autonomous platform developers provided ongoing calibration across the study period. Primary interviews with sensor subsystem specialists and shore-based command center operators combined with secondary validation from NATO STANAG documentation, EU Maritime Security Strategy implementation reports, FAA certification filings, and national defense budget appropriations. Bottom-up segment sizing triangulated against top-down fleet modernization expenditure tracking.
Scenario-bracketing around gallium nitride supply disruption and ITAR classification expansion anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology layer, deployment mode, application mission type, and end-user procurement authority. CAGRs derived from correlated fleet recapitalization schedules and interoperability mandate compliance deadlines. Anti-submarine warfare platform density and satellite constellation refresh cycles served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by rare earth processors or autonomous platform pure-plays would shift outcomes. Macroeconomic defense budget contraction, regulatory chokepoint expansion, or breakthrough acoustic detection technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Military Man-Portable Radar System Market