
 Military Imaging System Market | 2026-2036
Military Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Military Imaging System Market Foresight
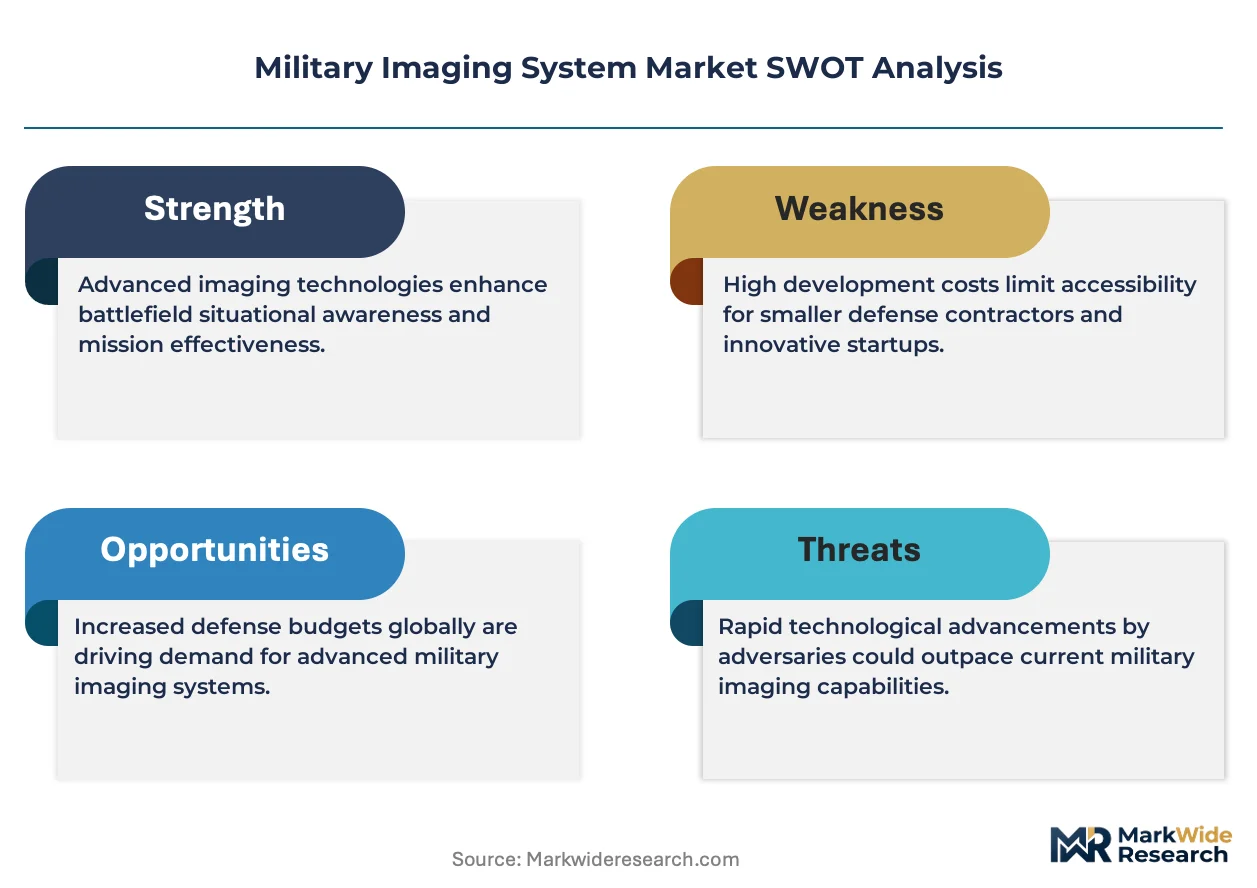
The EU AI Act is decoupling legacy analog imaging architectures from next-generation battlefield qualification pathways. BAE Systems anchors its European market position through captive supply of gallium arsenide focal plane arrays. Elbit Systems leverages its vertical integration into thermal core manufacturing to sustain margin pools in the Middle East. L3Harris competes primarily on digital imaging pipeline density for helmet-mounted displays.
Military imaging systems integrate photon-collecting sensors, signal processing electronics, and hardened display interfaces to generate actionable visual intelligence under zero-illumination or obscured atmospheric conditions. These systems typically operate across infrared wavebands from near-infrared through long-wave infrared, with resolution thresholds measured in line pairs per millimeter and cooling requirements ranging from thermoelectric stabilization to cryogenic dewar architectures. Thermal cameras occupy the largest revenue share due to matured uncooled microbolometer supply chains, while multi-spectral sensors represent the fastest-expanding category as forces demand simultaneous visible-SWIR-MWIR fusion for contested environments. Electro-optical systems concentrate margin pools in airborne targeting applications where stabilization and laser designation complexity create qualification barriers.
US procurement flows through the Defense Federal Acquisition Regulation Supplement, with NHTSA export control classifications shaping foreign military sale eligibility for focal plane array technologies. European adoption hinges on CE marking under the EU Green Deal's conflict mineral traceability requirements and REACH substance restrictions on sensor coatings. The US FAA coordinates airworthiness certification for imaging payloads aboard unmanned platforms. Stakeholders must monitor how dual-use technology reclassifications reshape component sourcing strategies before committing to fixed-price development contracts.
Market Dynamics
Multi-spectral sensor fusion requirements are compressing development cycles as defense programs demand simultaneous visible-through-LWIR coverage in single payload architectures, forcing suppliers to requalify analog signal chains under digital-native battlefield standards.
Growth Catalysts
- US DoD Night Vision Standards Refresh:Digital sensor fusion mandates are accelerating procurement of helmet-mounted display systems with unified thermal-visible pipelines.
- Border Surveillance Mission Expansion:Electro-optical targeting pods for persistent wide-area monitoring are driving uncooled microbolometer volume across frontline defense agencies.
- Gallium Arsenide Focal Plane Arrays:Maturity in III-V semiconductor epitaxy is lowering cryogenic cooling requirements for long-wave infrared detection at tactical ranges.
Market Restraints
- Indium Antimonide Substrate Concentration:MWIR focal plane array production depends on limited US and European foundry capacity, creating single-source vulnerability for precision targeting systems.
- REACH Substance Restrictions:ECHA limitations on sensor coating chemistries are extending qualification timelines for European defense contractors by 18-24 months.
- Synthetic Aperture Radar Substitution:All-weather radar imaging is displacing electro-optical payloads in maritime patrol applications where atmospheric obscuration dominates.
Strategic Opportunities
- Urban Canyon Operations:Short-wave infrared augmentation of existing thermal systems addresses reflected-light targeting gaps in dense built environments.
- CE Marking Pathway Expansion:EU Green Deal conflict mineral traceability requirements are creating first-mover advantage for suppliers with audited supply chains.
- Unmanned Platform Certification:FAA airworthiness standards for imaging payloads aboard Group 3-5 UAS are opening new contract vehicles beyond manned aircraft retrofit.
Industry Challenges
- Cryogenic Dewar Engineering Talent:Specialized vacuum packaging expertise for cooled infrared detectors has contracted to a handful of aging specialists in US and Israeli defense clusters.
- Dual-Use Technology Reclassification:NHTSA export control shifts are forcing prime contractors to revalidate foreign military sale eligibility for focal plane array subcomponents mid-program.
- Legacy Analog-Digital Interface Integration:Fielded thermal weapon sights with RS-170 video output require costly bridge electronics to feed modern network-centric battle management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Imaging System Market |
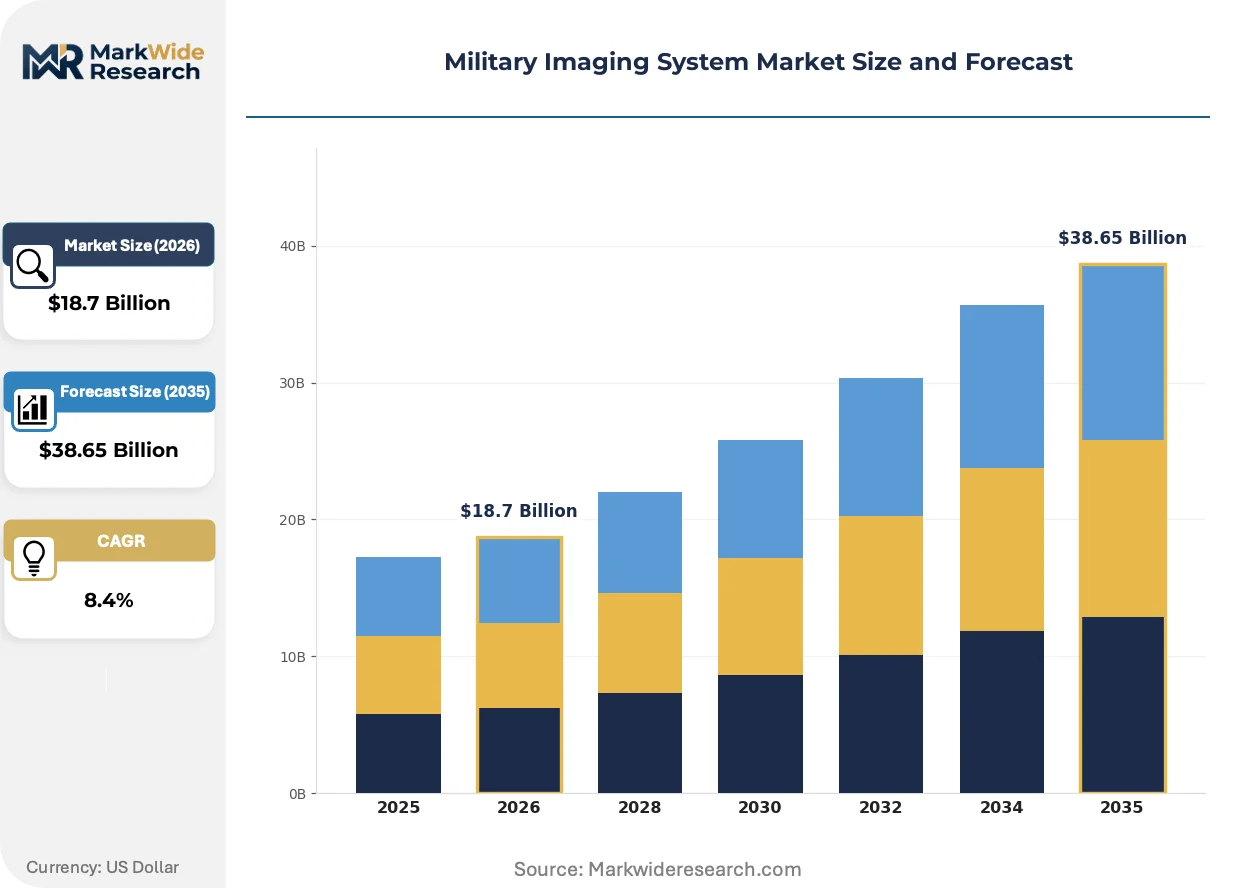
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cameras, Night Vision Devices, Electro-Optical Systems, Multi-Spectral Sensors Application: Surveillance, Target Acquisition, Reconnaissance, Search and Rescue End User: Armed Forces, Coast Guard, Law Enforcement, Defense Contractors Technology: Digital Imaging, Analog Imaging, Photonic Sensors, Compact Active Systems |
| Companies Covered | FLIR Systems (Teledyne Technologies), BAE Systems, L3Harris Technologies, Lockheed Martin Corporation, Raytheon Technologies Corporation, Thales Group, Elbit Systems, Leonardo S.p.A., Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Imaging System Market Shifts & Advancements
Computational imaging architectures are displacing hardware-centric optical designs, compressing the traditional trade-off between resolution, field of view, and payload weight through algorithmic reconstruction of sparse sensor data.
Event-based vision sensors are rewriting engagement timelines for close-combat applications. These bio-inspired detectors respond to per-pixel luminance changes rather than absolute intensity, enabling microsecond-latency target tracking. Special operations forces in Germany and Australia are field-testing helmet-integrated event cameras for urban breaching scenarios. The technology is compressing the sensor-processor-display latency chain from tens of milliseconds to sub-millisecond thresholds.
The EU AI Act is bifurcating qualification pathways for autonomous targeting systems. Legacy analog imaging architectures face exclusion from next-generation battlefield certification, while digital-native sensor fusion stacks gain expedited conformity assessment. European primes are responding by accelerating software-defined payload roadmaps and freezing analog product lines ahead of 2027 implementation deadlines.
Defense agencies are consolidating sensor procurement under platform-agnostic performance specifications rather than form-factor mandates. The US Army's IVAS program and Bundeswehr's IdZ-ES initiative both specify functional outcomes—detection range, identification probability, environmental envelope—permitting contractor innovation in physical implementation. This behavioral shift is visible across NATO member states, where fixed-price development contracts now dominate previously cost-plus arrangements for imaging subsystem upgrades.
Military Imaging System Market Segmentation
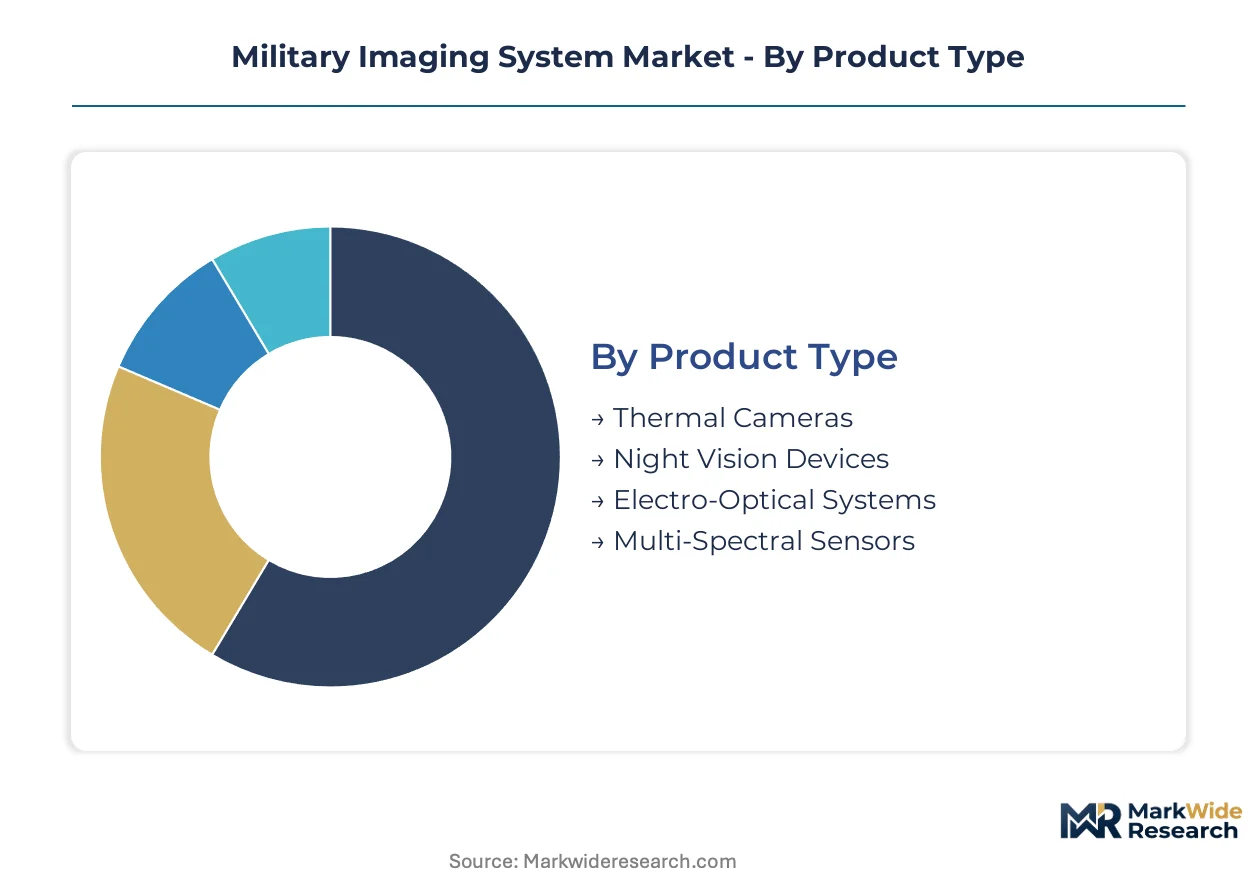
Military imaging procurement splits across mission-critical hardware tiers and software-defined processing stacks. Understanding these fault lines exposes where defense budgets concentrate and where qualification barriers protect margin pools.
Product Type:
Standardization dominates thermal camera supply chains while multi-spectral architectures demand custom sensor fusion engineering for each platform integration.
- Thermal Cameras:Uncooled microbolometer arrays operating in long-wave infrared bands deliver passive heat signature detection without cryogenic cooling. US border surveillance programs and German Bundeswehr vehicle upgrades drive volume procurement of fixed-mount and gimbal-stabilized variants. Mature foundry supply chains in the US and Israel compress unit economics for tactical deployments.
- Multi-Spectral Sensors:Simultaneous visible-SWIR-MWIR-LWIR fusion demands digital-native signal processing and requalified analog front-ends under EU AI Act battlefield certification pathways. German fighter aircraft electro-optical targeting pods and US helmet-mounted display programs represent concentrated demand for these complex payloads.
- Night Vision Devices:Image intensification tubes and thermal overlay systems for individual soldier systems.
- Electro-Optical Systems:Laser-designating targeting pods with stabilized line-of-sight for precision strike missions.
Leading the category by volume: Thermal Cameras. Growing fastest: Multi-Spectral Sensors.
Application:
Volume concentrates in persistent wide-area monitoring while close-combat targeting commands premium pricing through latency-sensitive processing requirements.
- Surveillance:Persistent electro-optical and infrared monitoring of borders, forward operating bases, and critical infrastructure. US Customs and Border Protection and European coast guard agencies drive demand for mast-mounted and aerostat-borne sensor suites with automated motion detection algorithms.
- Target Acquisition:Laser rangefinding and designation systems for precision-guided munitions engagement. US Army IVAS and Bundeswehr IdZ-ES programs specify sub-meter accuracy with network-centric fire support coordination, compressing sensor-processor-display latency chains.
- Reconnaissance:Long-range standoff imaging for deep-strike mission planning and battle damage assessment.
- Search and Rescue:Thermal and low-light sensors for personnel recovery in denied or degraded visual environments.
Surveillance commands the largest budget allocation. Target Acquisition exhibits the steepest expansion trajectory as NATO forces prioritize sensor-to-shooter linkages.
End User:
Armed forces procurement follows platform-centric specifications while defense contractors absorb integration risk through fixed-price development contracts.
- Armed Forces:National military services specifying helmet-mounted displays, vehicle sights, and airborne targeting pods. US Department of Defense refresh of night vision standards accelerates digital sensor fusion mandates across Army, Marine Corps, and Special Operations Command programs.
- Defense Contractors:Prime integrators sourcing focal plane arrays and processing electronics for platform embedding. BAE Systems and Elbit Systems maintain captive supply of gallium arsenide arrays and thermal cores to defend margin pools against component cost volatility.
- Coast Guard:Maritime patrol and interdiction missions requiring all-weather electro-optical payloads.
- Law Enforcement:Tactical teams procuring thermal weapon sights and observation systems for urban operations.
Armed Forces dominate procurement volume. Defense Contractors represent the fastest-climbing segment as primes internalize subsystem production.
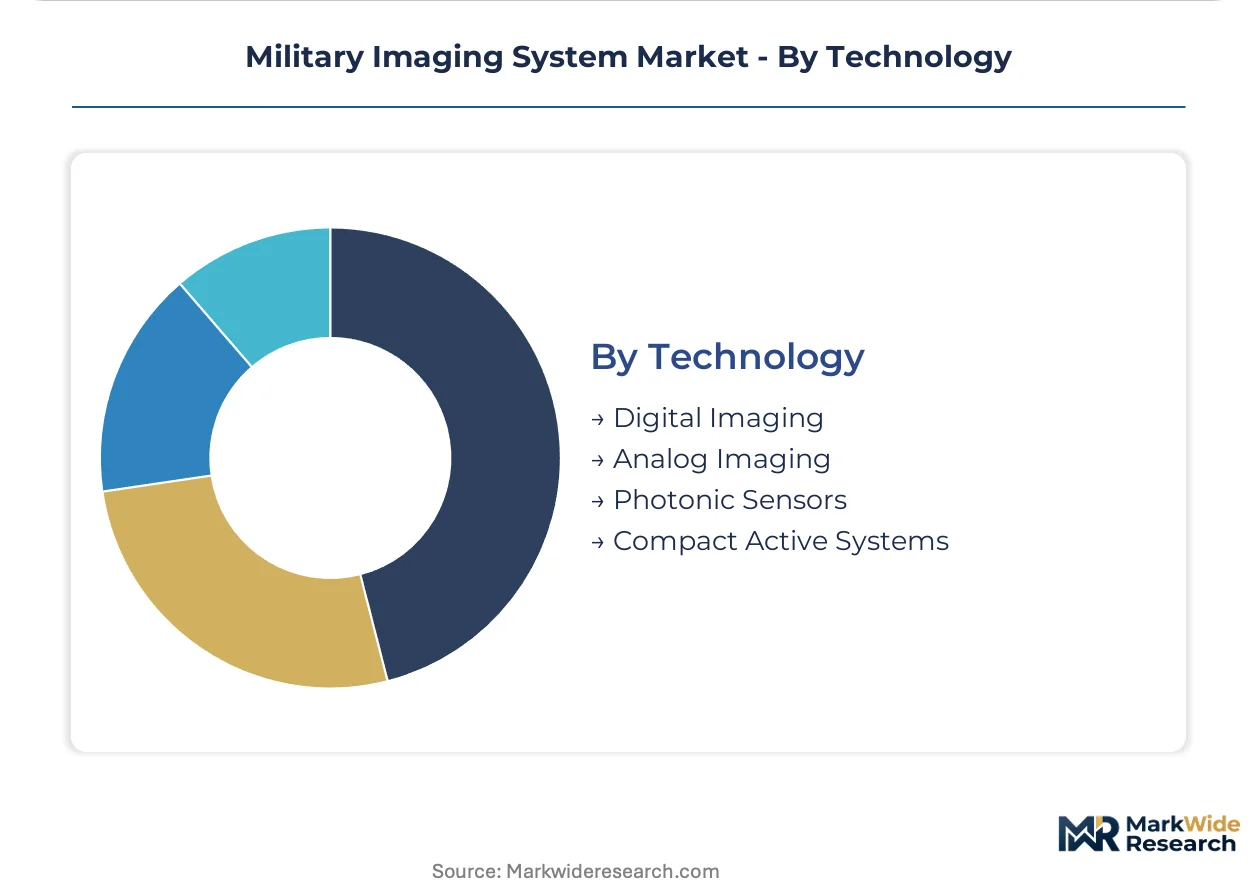
Technology:
Digital imaging pipelines displace legacy analog architectures as EU AI Act qualification pathways bifurcate battlefield certification eligibility.
- Digital Imaging:Software-defined sensor fusion with unified processing of visible, near-infrared, and thermal wavebands. L3Harris competes on pipeline density for helmet-mounted displays, compressing multiple spectral feeds into single digital streams compatible with network-centric battle management systems.
- Photonic Sensors:Event-based vision detectors responding to per-pixel luminance changes rather than absolute intensity. German and Australian special operations forces field-test these bio-inspired sensors for urban breaching scenarios, achieving microsecond-latency target tracking.
- Analog Imaging:Legacy RS-170 video output systems requiring bridge electronics for modern network integration.
- Compact Active Systems:Miniaturized laser illumination and gated imaging for covert close-range targeting.
Digital Imaging leads technology investment. Photonic Sensors are gaining share fastest as computational imaging architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense technology parks in Huntsville, Alabama and Tel Aviv anchor concentrated imaging system development, with special economic zones offering accelerated procurement pathways for classified sensor programs.
United States
The Department of Defense's night vision standards refresh drives procurement of helmet-mounted displays with unified thermal-visible pipelines. FAA airworthiness certification for Group 3-5 UAS imaging payloads opens contract vehicles beyond manned aircraft retrofit. Huntsville's Redstone Arsenal corridor hosts prime contractor integration facilities for electro-optical targeting pods.
Germany
Bundeswehr modernization programs prioritize electro-optical targeting pods for fighter aircraft and soldier systems under the IdZ-ES initiative. EU AI Act battlefield certification requirements are accelerating digital-native sensor fusion roadmaps ahead of 2027 deadlines. Bavaria's defense cluster around Munich anchors thermal core manufacturing for European combat vehicle upgrades.
Israel
Special operations forces field-testing of event-based vision sensors for urban breaching scenarios concentrates demand for microsecond-latency target tracking. NHTSA export control classifications shape foreign military sale eligibility for focal plane array technologies. Tel Aviv's defense technology corridor houses captive supply chains for gallium arsenide focal plane arrays.
United Kingdom
Ministry of Defence procurement through the Defence and Security Equipment International framework prioritizes multi-spectral sensors for maritime patrol and border surveillance. CE marking under EU Green Deal conflict mineral traceability requirements creates qualification barriers for uncertified suppliers. Glasgow's electro-optics cluster specializes in stabilized gimbal systems for persistent wide-area monitoring.
Australia
Australian Defence Force modernization under Project Land 400 drives demand for vehicle-mounted thermal sights with network-centric battle management integration. TGA-equivalent defense materiel certification aligns with NATO interoperability standards for coalition operations. Melbourne's defense precinct hosts integration facilities for helmet-mounted display systems drawing on US and Israeli component supply.
Military Imaging System Market Competitive Landscape
US producers anchor the prime contractor tier; Israeli and European specialists hold positions in thermal core manufacturing and sensor fusion subsystems. Market structure concentrates around five to seven vertically integrated defense primes with captive focal plane array supply, while mid-tier component suppliers face margin compression from fixed-price development contracts. Two strategic archetypes dominate: primes with backward integration into III-V semiconductor epitaxy, and software-defined payload specialists competing on digital pipeline density. Competitive moves center on M&A to secure cryogenic dewar engineering talent and strategic partnerships for unmanned platform certification.
Within the prime contractor tier, BAE Systems, L3Harris Technologies, and Elbit Systems occupy positions reflecting distinct geographic anchoring and supply chain configurations. BAE Systems exemplifies the European prime archetype with captive gallium arsenide focal plane array production. L3Harris represents the US digital imaging pipeline specialist competing on helmet-mounted display integration density. Elbit Systems sits within the Israeli vertically integrated tier with in-house thermal core manufacturing sustaining margin pools in Middle Eastern defense procurement.
| Leading Market Players |
|---|
| FLIR Systems (Teledyne Technologies) |
| BAE Systems |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| Elbit Systems |
| Leonardo S.p.A. |
| Northrop Grumman |
| Others |
Supply & Pricing Matrix
Gallium arsenide wafer pricing indices cascade through III-V semiconductor epitaxy tiers into three distinct procurement bands: cryogenically cooled MWIR arrays command premium positioning, uncooled microbolometer volumes settle at mid-tier contract rates, and legacy analog intensifier tubes face persistent cost compression from digital substitution mandates.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement cycles from planned program schedules, with cryogenic dewar assemblies carrying substantial premiums against spot-market uncooled alternatives. Three-tier pricing structure across expeditionary-grade, standard military-qualified, and commercial-off-the-shelf levels reflects certification depth and thermal sensitivity specifications. Cost compression in analog-to-digital bridge electronics is intensifying because EU AI Act qualification deadlines are freezing legacy product lines. Defense contractors exhibit lowest price sensitivity due to captive integration mandates, while coast guard agencies demonstrate highest elasticity to unit economics.
Supply Chain Analysis
Indium antimonide substrate supply rests on limited US and European foundry capacity, creating single-source vulnerability for precision targeting systems. Focal plane array manufacturing draws from Israeli gallium arsenide epitaxy clusters, US cryogenic packaging specialists, and German precision optics houses. Germanium lens supply faces tariff exposure from raw material concentration in China and Russia. Distribution runs through Defense Federal Acquisition Regulation Supplement channels for US procurement and NATO standardization agreements for allied nations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's battlefield certification bifurcation erects a compliance moat around digital-native sensor fusion suppliers, freezing analog-dependent competitors from next-generation program eligibility.
For Market Incumbents: Lock in cryogenic dewar engineering talent through targeted acquisition of Israeli and US defense cluster specialists before demographic contraction eliminates this capability pool. Secure backward integration into MWIR substrate supply through long-term offtake agreements with indium antimonide foundries to defend against synthetic aperture radar substitution in maritime patrol applications. For New Entrants and Emerging Players: Launch via unmanned platform certification pathways under FAA Group 3-5 airworthiness standards, where incumbent primes lack entrenched positions. Urban canyon SWIR augmentation represents the most penetrable white-space target, with Australian and German special operations forces already field-testing event-based vision prototypes. Pursue strategic partnerships with established thermal core manufacturers to bypass focal plane array qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined payload specialists with EU AI Act pre-certification in Germany and the United Kingdom, where defense modernization budgets remain resilient. Long-term viability across the analysis window hinges on digital pipeline density rather than hardware-centric optical legacy. Monitor NHTSA export control reclassification announcements as the critical inflection signal for focal plane array subcomponent valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Dewar Engineering Acquisition | Captures scarce vacuum packaging expertise concentrated in aging US and Israeli specialist pools. |
| EU AI Act Pre-Certification Investment | Secures expedited conformity assessment pathways for digital-native sensor fusion stacks ahead of competitors. |
| MWIR Substrate Supply Agreement | Mitigates indium antimonide foundry concentration risk through locked capacity at US or European sources. |
| Unmanned Platform Certification Partnership | Opens FAA airworthiness contract vehicles beyond saturated manned aircraft retrofit markets. |
| Event-Based Vision Sensor Development | Addresses microsecond-latency requirements for urban breaching scenarios field-tested by German and Australian forces. |
Research Methodology
Multi-period observation of Defense Federal Acquisition Regulation Supplement contract awards, EU Green Deal conflict mineral traceability filings, and NHTSA export control classification shifts anchored the trend analysis, supplemented by interviews with electro-optical subsystem program managers, focal plane array procurement leads at prime contractors, cryogenic packaging engineering directors, and defense agency technology qualification officers. Secondary validation drew from SEC 10-K defense segment disclosures, Bundeswehr IdZ-ES program documentation, and FAA UAS airworthiness certification databases. Bottom-up unit economics for thermal camera and multi-spectral sensor categories were triangulated against top-down defense budget allocation models.
Input-output matrices mapped focal plane array supply constraints against platform integration demand across the projection horizon, with segmentation dimensions spanning cooled versus uncooled thermal architectures, helmet-mounted versus vehicle-mounted versus airborne payload form factors, and digital-native versus legacy analog signal processing tiers. CAGRs were derived from contract velocity analysis and procurement pipeline visibility. Cryogenic cooling technology maturity curves and computational imaging algorithm advancement rates served as industry-specific forecast inputs.
Regulatory reclassification timelines, foundry capacity expansion decisions, and dual-use technology policy shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about certification pathway stability and allied defense budget continuity. A small set of named triggers—NHTSA focal plane array reclassification, ECHA coating chemistry restriction expansion, and FAA UAS payload standard finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Early Warning Radar Market