
 Sea-Based Military Electro-Optical and Infrared Systems Market | 2026-2036
Sea-Based Military Electro-Optical and Infrared Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sea-Based Military Electro-Optical and Infrared Systems Market Analytics
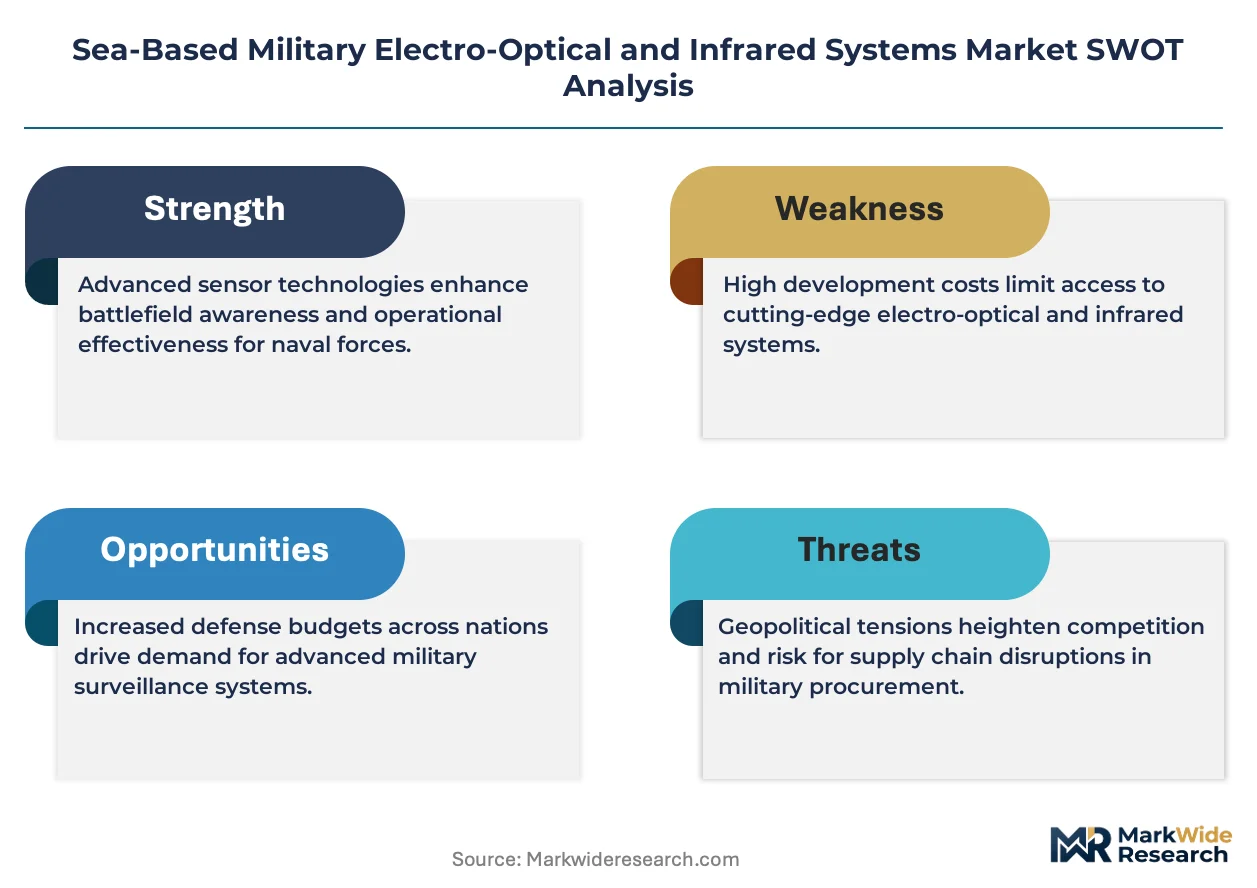
MIL-STD-810H qualification tier is redrawing supplier hierarchies in naval electro-optical procurement. Elbit Systems leverages captive gallium arsenide foundry capacity to sustain margin on cooled thermal cores. Rheinmetall anchors European frigate modernization programs with stabilized naval optronic suites. Thales differentiates through integrated mast architectures that compress sensor apertures into stealth-optimized envelopes.
Sea-based military electro-optical and infrared systems encompass stabilized sensor payloads that detect, track, and identify surface and aerial contacts across visible, near-infrared, short-wave infrared, and thermal bands, typically operating at frame rates exceeding 30 Hz with sub-pixel stabilization accuracy for maritime clutter rejection. Their primary purpose is to extend vessel standoff distance during threat engagement cycles while reducing radar emission signatures. Thermal imaging occupies the largest product category due to all-weather passive detection requirements, yet multispectral sensors represent the fastest-expanding segment as navies fuse hyperspectral signatures with automatic target recognition libraries. Detection systems within the technology dimension lead procurement volumes, though data fusion architectures now capture disproportionate R&D allocation as distributed sensor networks proliferate across fleet formations.
US Navy MIL-STD-461G electromagnetic compatibility requirements and NATO STANAG 4670 interface standards shape hardware interoperability and test certification burdens for non-aligned suppliers. The EU AI Act's risk classification framework for autonomous targeting systems is forcing early design-stage algorithm documentation across European defense supply chains. Japan's Acquisition, Technology and Logistics Agency has tightened indigenous content thresholds for maritime sensor platforms. Stakeholders must monitor convergence between software-defined sensor roadmaps and emerging sovereign AI certification regimes to preserve platform access across allied procurement programs.
Market Dynamics
Naval procurement officers are compressing sensor integration timelines as distributed maritime operations require interoperable electro-optical suites across allied fleet formations. The shift from platform-centric to network-centric warfare architectures is forcing hardware suppliers to certify against multiple national standards simultaneously.
Growth Catalysts
- US Navy MIL-STD-461G electromagnetic compatibility mandates:Surface combatant modernization programs require hardened electro-optical systems that suppress electromagnetic interference signatures during coordinated fleet operations.
- Hyperspectral signature libraries:Automatic target recognition databases trained on maritime clutter patterns are accelerating procurement of multispectral sensor payloads for threat identification at extended standoff distances.
- NATO STANAG 4670 interface standardization:Allied frigate and destroyer programs in the United Kingdom, Norway, and the Netherlands are converging on common optical sensor data formats.
Market Restraints
- Gallium arsenide substrate scarcity:Cooled thermal imaging cores depend on specialized semiconductor foundry capacity concentrated in Israel and the United States.
- EU AI Act risk classification burdens:Autonomous targeting algorithms for naval electro-optical systems face mandatory design-stage documentation requirements that extend development cycles.
- Indium antimonide detector cost volatility:Mid-wave infrared focal plane arrays require rare earth processing inputs subject to export control fluctuations.
Strategic Opportunities
- Japan's indigenous content thresholds:The Acquisition, Technology and Logistics Agency is mandating local electro-optical subsystem assembly for maritime patrol vessel programs.
- Software-defined sensor convergence:Programmable thermal cores that reconfigure detection bands via firmware updates are opening retrofit markets for legacy surface combatants.
- Integrated mast architectures:Stealth-optimized envelope designs are compressing sensor apertures into unified superstructures that reduce radar cross-section signatures.
Industry Challenges
- Sub-pixel stabilization engineering talent:Maritime clutter rejection algorithms require specialized expertise in gyroscopic compensation and real-time image processing.
- MIL-STD-810H environmental qualification timelines:Salt spray, shock, and vibration testing for naval electro-optical systems extends certification cycles beyond commercial aerospace equivalents.
- Legacy analog interface integration:Existing surface combatant combat management systems use proprietary data buses that complicate digital sensor retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea-Based Military Electro-Optical and Infrared Systems Market |
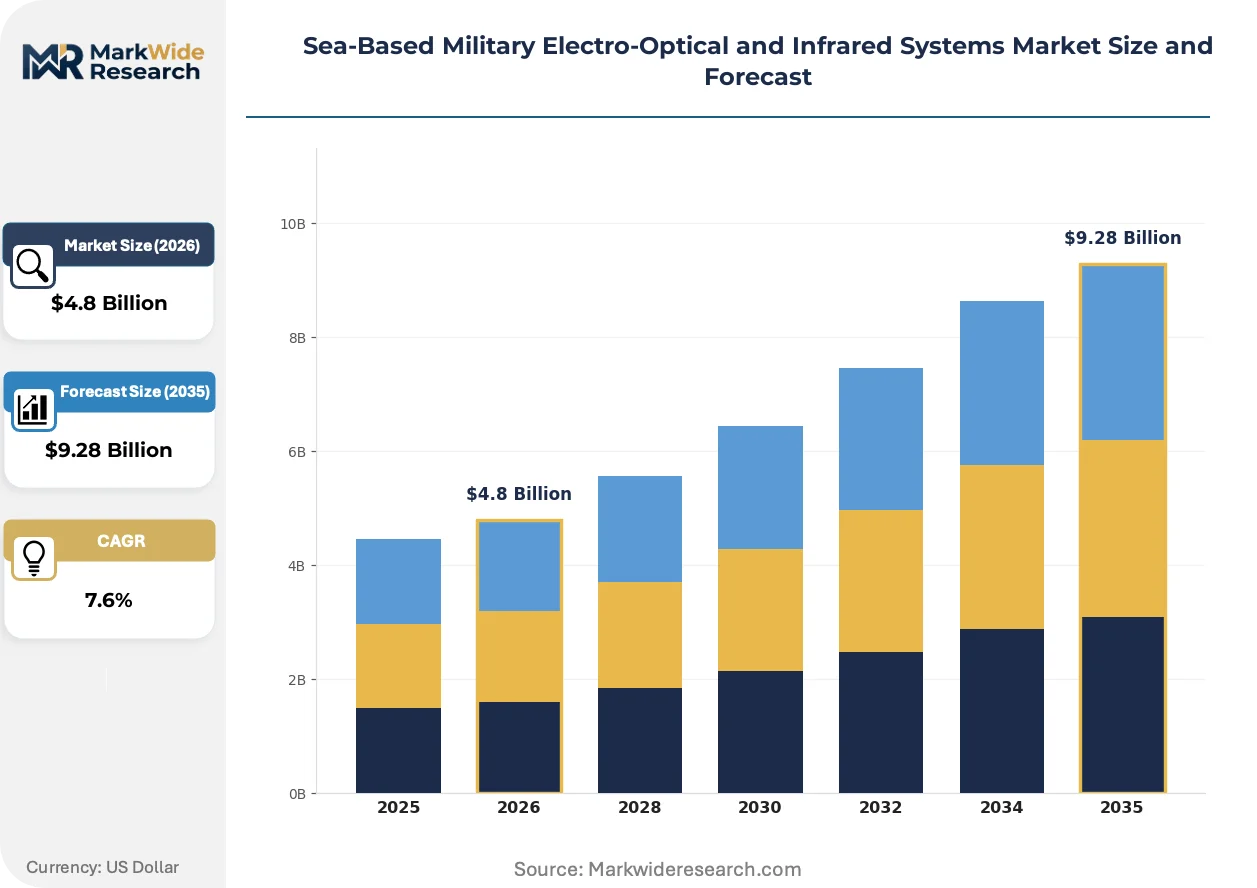
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Imaging, Multispectral Sensors, Laser Rangefinders, Night Vision Technology: Image Processing, Detection Systems, Tracking Solutions, Data Fusion End User: Naval Forces, Coast Guards, Defense Contractors, Security Agencies Application: Surveillance, Target Acquisition, Reconnaissance, Maritime Interdiction |
| Companies Covered | Elbit Systems Ltd, Rheinmetall AG, Teledyne FLIR LLC, Thales, Safran SA, BAE Systems, Northrop Grumman Corporation, L3Harris Technologies, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea-Based Military Electro-Optical and Infrared Systems Market Evolving Landscape
Electro-optical payload architectures are fragmenting into modular, software-reconfigurable designs that decouple hardware refresh cycles from capability upgrades. This shift is compressing supplier margins while expanding addressable retrofit markets.
Solid-state laser rangefinder integration is miniaturizing naval fire control systems previously dependent on discrete component assemblies. The US Navy's Next Generation Surface Search Radar mandate is accelerating adoption of combined electro-optical and active radar tracking on Arleigh Burke-class destroyers. This convergence is miniaturizing masthead sensor footprints and reducing electromagnetic signature emissions during passive surveillance operations.
The EU AI Act's risk classification framework for autonomous targeting systems is forcing algorithm documentation at the design stage across European defense supply chains. Naval primes in France, Germany, and Italy must now submit conformity assessments for machine learning models embedded in electro-optical tracking loops. This regulatory friction is favoring suppliers with established quality management systems certified against ISO 9001 and AQAP 2110 standards.
Allied naval procurement officers are consolidating electro-optical sensor awards into multi-year framework agreements that bundle hardware, software licenses, and through-life support. The United Kingdom's Type 26 frigate program and Australia's Hunter-class build are shifting from transactional purchases to performance-based availability contracts. This restructuring is displacing component specialists who lack integrated logistics capabilities or sovereign security clearances.
Sea-Based Military Electro-Optical and Infrared Systems Market Segmentation
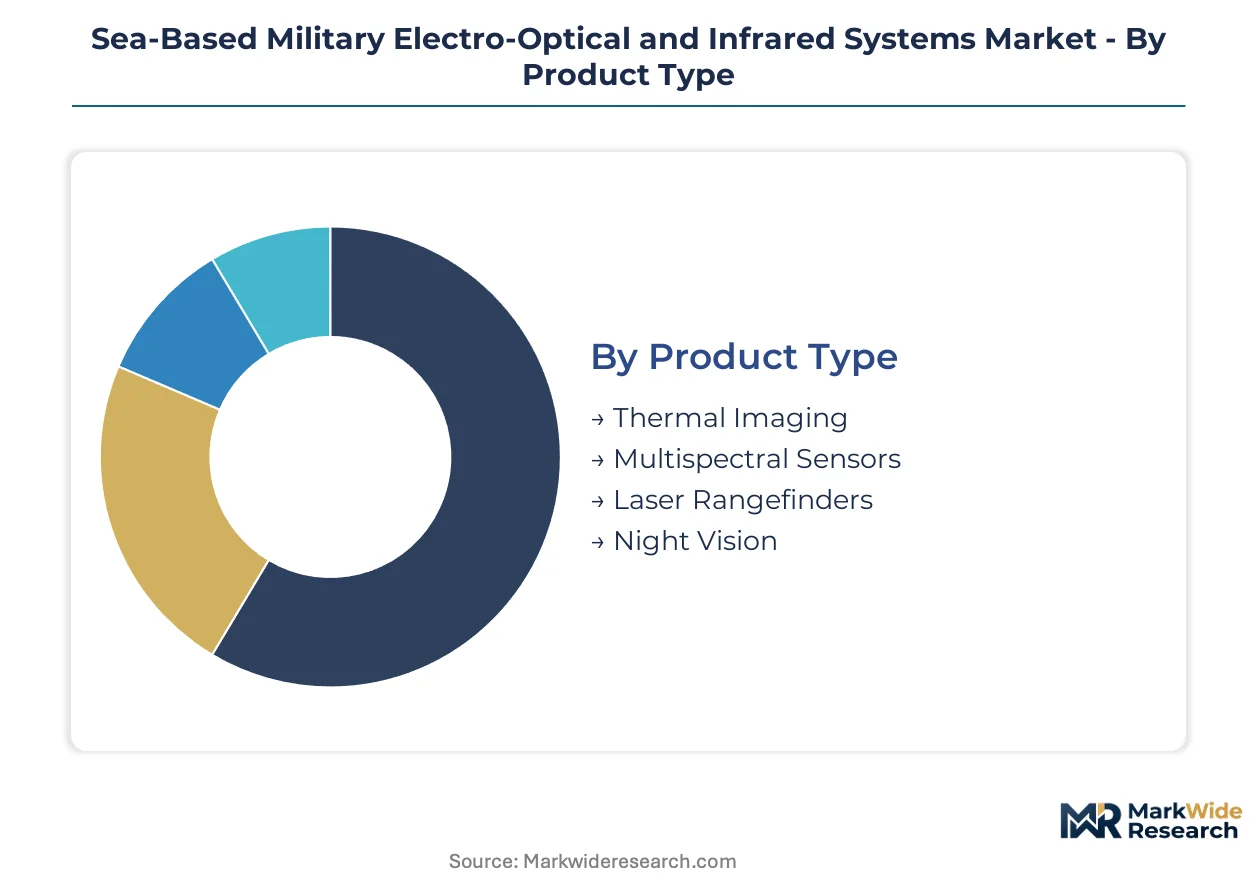
Segmentation in naval electro-optical systems reveals how procurement priorities diverge across mission profiles and platform classes. Procurement officers balance legacy fleet compatibility against next-generation network architectures when allocating sensor budgets across product categories and technology tiers.
Product Type:
US Navy MIL-STD-461G electromagnetic compatibility requirements and NATO STANAG 4670 interface standards differentiate procurement tiers by environmental hardening and data interoperability specifications.
- Thermal Imaging:Cooled and uncooled focal plane arrays detect thermal signatures across long-wave and mid-wave infrared bands for all-weather passive surveillance. Naval forces in the United States, the United Kingdom, and Japan concentrate procurement here for surface combatant modernization programs, driven by requirements for reduced radar cross-section operations.
- Multispectral Sensors:Hyperspectral and multispectral payloads fuse visible, near-infrared, and short-wave infrared channels with automatic target recognition algorithms. Demand is climbing fastest in European NATO frigate programs where EU AI Act documentation requirements favor suppliers with pre-certified algorithm libraries.
- Laser Rangefinders:Solid-state diode-pumped designs now miniaturize fire control systems previously requiring discrete optical benches.
- Night Vision:Image intensification tubes and digital low-light sensors support boarding party operations and coastal patrol missions.
Established volume favors Thermal Imaging; emerging adoption favors Multispectral Sensors.
Technology:
Cost tiers separate commercial-off-the-shelf image processing modules from hardened military-grade detection systems requiring extended environmental qualification cycles.
- Image Processing:Real-time stabilization algorithms and maritime clutter rejection software operate at frame rates exceeding 30 Hz with sub-pixel accuracy. Defense contractors in the United States prioritize this capability for retrofit programs on Arleigh Burke-class destroyers, constrained by legacy analog interface integration challenges.
- Detection Systems:Passive electro-optical sensors with integrated laser warning receivers dominate procurement volumes for surface combatant masthead installations. Naval forces in Japan are accelerating adoption here under indigenous content thresholds mandated by the Acquisition, Technology and Logistics Agency.
- Tracking Solutions:Kalman filter-based target state estimators and multi-hypothesis correlation algorithms support fire control loops.
- Data Fusion:Distributed sensor network architectures aggregate electro-optical tracks with radar and electronic support measures across fleet formations.
Hardware procurement concentrates in Detection Systems; software investment flows fastest into Data Fusion architectures.
End User:
Customer type determines security clearance requirements, sovereign content rules, and through-life support contract structures.
- Naval Forces:Surface combatant and submarine programs drive specifications for shock-hardened, salt-spray-resistant sensor enclosures meeting MIL-STD-810H qualification. The US Navy's Next Generation Surface Search Radar integration mandate shapes procurement patterns, with electromagnetic compatibility requirements forcing supplier consolidation.
- Coast Guards:Maritime patrol vessel programs prioritize cost-optimized thermal cores with reduced stabilization accuracy for littoral surveillance missions.
- Defense Contractors:System integrators bundle electro-optical subsystems into platform-level combat management solutions for export markets.
- Security Agencies:Port facility and critical infrastructure protection programs generate demand for portable and fixed-site surveillance payloads.
Platform-level procurement dominates through Naval Forces; modular subsystem sales expand fastest via Defense Contractors.
Application:
Mission profile differentiation separates continuous surveillance requirements from time-critical targeting engagements with distinct sensor refresh and latency specifications.
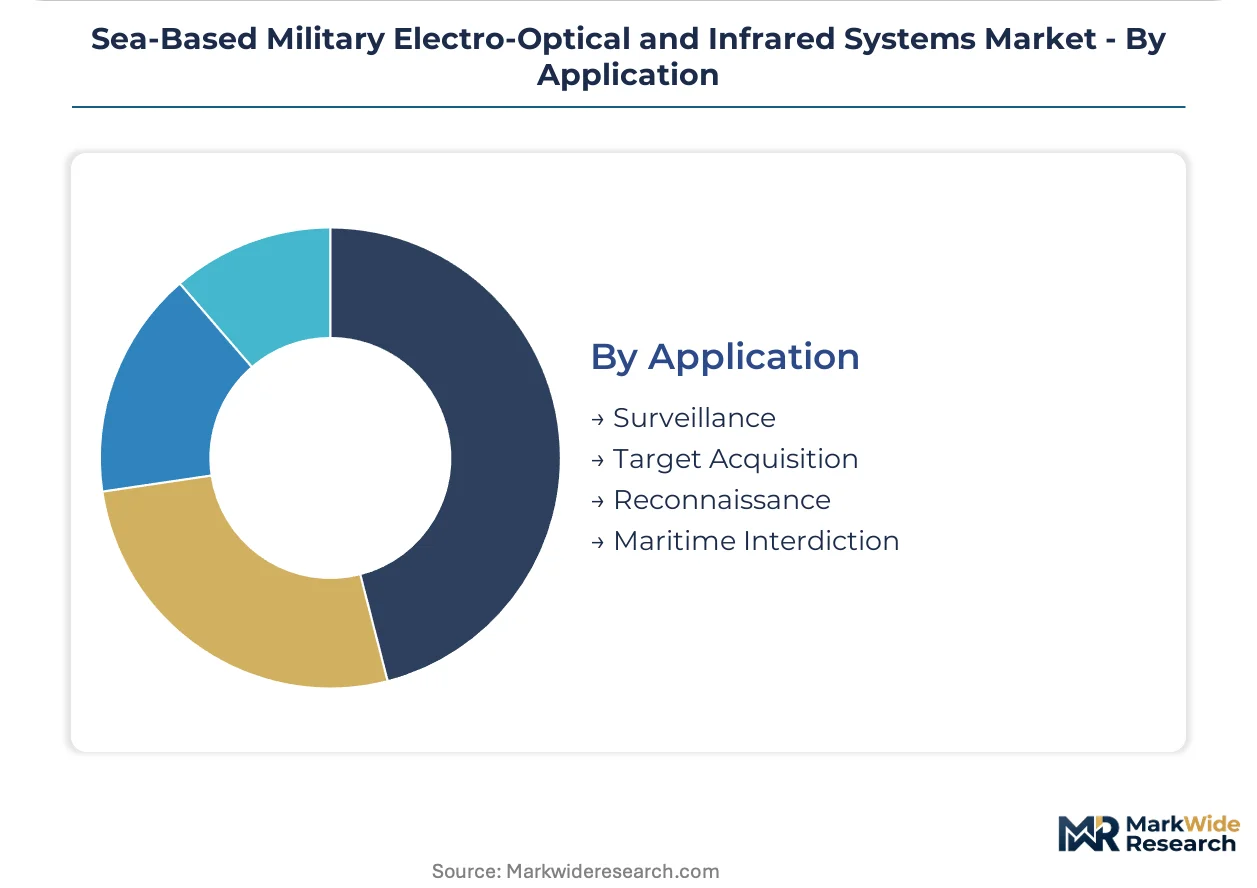
- Surveillance:Wide-area persistent stare and scanning search modes require cooled thermal cores with extended mean-time-between-failure ratings for unmanned maritime system deployments. Coast Guards in allied NATO nations are expanding procurement here for exclusive economic zone monitoring.
- Target Acquisition:High-resolution identification modes with laser designation capability support over-the-horizon missile engagements. Naval forces concentrate investment in this segment for distributed maritime operations, where extended standoff distances reduce platform vulnerability.
- Reconnaissance:Covert intelligence collection missions demand passive-only sensor configurations with suppressed thermal and acoustic signatures.
- Maritime Interdiction:Fast-moving small craft detection and tracking drives requirements for high-frame-rate visible and thermal sensors with rapid slew rates.
Baseline fleet capability centers on Surveillance; capability gap closure prioritizes Target Acquisition modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics foundries cluster in Israel and the United States, creating chokepoints for cooled thermal core substrates. Naval modernization programs across NATO member states and Pacific allies are redrawing procurement geography.
United States
Arleigh Burke-class destroyer retrofits and Next Generation Surface Search Radar integration concentrate demand in Virginia and California shipyards. MIL-STD-461G electromagnetic compatibility mandates filter supplier participation. The Pacific Northwest hosts prime contractor engineering centers for distributed maritime operations sensor fusion.
United Kingdom
Type 26 frigate construction at Scottish yards drives stabilized optronic suite procurement. NATO STANAG 4670 interface standardization shapes subsystem selection criteria. Southwest England clusters defense electronics specialists supporting integrated mast architectures.
Japan
Maritime patrol vessel programs under indigenous content thresholds accelerate local electro-optical subsystem assembly. The Acquisition, Technology and Logistics Agency enforces technology transfer requirements. Yokohama and Kobe house prime contractor facilities for naval sensor integration.
Germany
F125 and F126 frigate programs anchor European demand for multispectral naval sensors. EU AI Act documentation requirements for autonomous targeting algorithms extend development cycles. Northern shipyards coordinate with Bavarian electro-optics specialists on combat management integration.
Israel
Captive gallium arsenide foundry capacity sustains cooled thermal core production for export markets. Defense procurement ties to NATO interoperability standards shape product roadmaps. Haifa and Tel Aviv districts concentrate sensor payload engineering talent for maritime applications.
Sea-Based Military Electro-Optical and Infrared Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the naval electro-optical sector. The supplier base stratifies into three tiers: vertically integrated defense primes with sovereign security clearances, mid-scale specialists with captive semiconductor capacity, and component subsystem vendors dependent on prime contractor channels. Consolidation pressure intensifies as procurement officers bundle hardware, software licenses, and through-life support into multi-year framework agreements. Strategic moves center on algorithm library certification against emerging AI governance regimes and foundry capacity expansion for thermal imaging substrates.
Among Israeli and European defense electronics groups, Elbit Systems Ltd, Rheinmetall AG, and Thales occupy positions spanning the technology-cost spectrum. Elbit Systems exemplifies the captive foundry archetype with in-house gallium arsenide production. Rheinmetall represents European prime contractor integration capabilities for naval platform modernization. Thales anchors the integrated sensor mast segment with stealth-optimized envelope designs. These three entities illustrate how geographic industrial bases and regulatory compliance postures segment competitive positioning across NATO and allied procurement programs.
| Leading Market Players |
|---|
| Elbit Systems Ltd |
| Rheinmetall AG |
| Teledyne FLIR LLC |
| Thales |
| Safran SA |
| BAE Systems |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Others |
Value Network & Pricing Analysis
Solid-state laser rangefinder substitution for discrete optical benches redraws procurement economics while compressing supplier margins across Israeli and United States foundry clusters. This component transition simultaneously elevates firmware-dependent pricing models and concentrates thermal substrate supply in captive gallium arsenide facilities.
Pricing Analysis
MIL-STD-461G electromagnetic compatibility mandates dictate the pricing tier structure across naval electro-optical procurement. Three-tier pricing separates MIL-STD-810H-qualified hardened systems from commercial-aerospace equivalents and uncooled economy-tier thermal cores. Price differentiation hinges on certification grade against NATO STANAG 4670 interface standards and sovereign security clearance requirements. Margins are tightening due to bundled multi-year framework agreements that compress hardware premiums into through-life service contracts. Coast Guard procurement officers exhibit highest price sensitivity for littoral surveillance missions, while naval surface combatant programs prioritize electromagnetic hardening over unit cost.
Supply Chain Analysis
Inbound logistics costs through Israeli and United States defense electronics corridors face container availability constraints on specialized semiconductor foundry lanes. Gallium arsenide substrate production draws from captive facilities in Israel and the United States, with indium antimonide detector processing anchored in rare earth supply chains subject to export control fluctuations. Single-source vulnerability concentrates in cooled thermal core focal plane arrays where semiconductor lithography capacity lacks geographic diversification. Distribution runs through prime contractor integration channels that bundle electro-optical subsystems into platform-level combat management solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as software-defined sensor roadmaps splinter procurement across legacy analog retrofit and digital-native platform categories. Distributed maritime operations create niche entry points for modular payload specialists.
For Market Incumbents: Shield algorithm library certification against EU AI Act risk classification timelines by pre-documenting machine learning models at design stage. Prioritize captive gallium arsenide foundry capacity expansion to preserve margin on cooled thermal cores amid substrate scarcity. Consolidate integrated logistics capabilities to capture multi-year framework agreements displacing component specialists lacking sovereign security clearances.
For New Entrants and Emerging Players: Lead with software-reconfigurable thermal cores targeting legacy Arleigh Burke-class destroyer retrofit markets constrained by proprietary analog data bus integration challenges. Target Japan's indigenous content thresholds for maritime patrol vessel programs where local assembly mandates create technology transfer entry points. Pursue coast guard exclusive economic zone monitoring applications where reduced stabilization accuracy requirements lower certification barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale specialists with captive semiconductor capacity and ISO 9001 plus AQAP 2110 quality certifications. Long-term viability hinges on algorithm library depth and foundry access rather than discrete hardware margins. Acquisition target archetype: electro-optics specialists with pre-certified automatic target recognition databases and established NATO STANAG 4670 interface compliance. Watch for inflection in distributed sensor network R&D allocation as signal of data fusion architecture prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Secures gallium arsenide substrate supply for cooled thermal core production against Israeli and United States concentration. |
| Algorithm Library Certification | Pre-positions machine learning models for EU AI Act conformity assessment before design-stage documentation mandates harden. |
| Integrated Mast Architecture Development | Compresses sensor apertures into stealth-optimized envelopes for Thales-class stealth-optimized naval platforms. |
| Software-Defined Sensor Convergence | Opens retrofit markets for legacy surface combatants through firmware-reconfigurable thermal detection bands. |
| Multi-Year Framework Agreement Pursuit | Captures United Kingdom Type 26 and Australia Hunter-class performance-based availability contract structures. |
Research Methodology
Cross-validation between naval procurement officer interviews and defense electronics trade documentation anchors the qualitative findings. Primary fieldwork engaged platform engineering directors, combat management system integrators, electro-optics R&D leads, and shipyard procurement managers across United States, United Kingdom, Japanese, and German naval modernization programs. Secondary validation drew from NATO STANAG technical specifications, EU AI Act regulatory filings, Japan Acquisition Technology and Logistics Agency procurement notices, and United States Navy MIL-STD documentation. Bottom-up sensor unit shipment estimates triangulated against top-down fleet modernization budget allocations.
Sensitivity analysis around gallium arsenide substrate availability and EU AI Act implementation timelines shaped projection confidence intervals across the modeling period. Segmentation dimensions modeled include product type, technology tier, end user category, and application mission profile alongside regional regulatory cluster alignment. CAGRs derived from fleet replacement cycle analysis and distributed maritime operations capability gap assessments. Industry-specific forecast inputs encompassed electromagnetic compatibility mandate adoption curves and hyperspectral signature library training data availability.
The analysis sits within stated boundaries; outcomes outside allied naval procurement continuity or semiconductor export control stability would require recalibration. Forecasts reflect assumptions regarding NATO interoperability standard persistence and sovereign AI certification regime convergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
UXO Detection Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Military Jammer Market
Military Surveillance
Global Radar Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market