
 Inspection Drones in Confined Space Market | 2026-2036
Inspection Drones in Confined Space Market Size, Share, and Industry Trends Forecast 2026-2036
Inspection Drones in Confined Space Market Analysis
Multi-source procurement for drone platforms and sensor payloads is rebalancing as end users seek supply chain resilience against component shortages. Flyability leverages its collision-tolerant cage design to sustain premium positioning in nuclear and chemical vessel inspections. ScoutDI anchors Nordic offshore energy demand with marine-certified tethered systems. DJI competes aggressively on manufacturing scale across utility boiler and tunnel applications.
Inspection drones in confined space are unmanned aerial systems engineered with protective exoskeletons, obstacle-avoidance LiDAR, and real-time gas detection to operate inside tanks, silos, ducts, and pressure vessels where GPS denial and collision risks prohibit conventional drones. Their primary purpose is eliminating human entry into hazardous atmospheres while capturing millimetric defect imagery for predictive maintenance. Multirotor configurations dominate current deployments due to hovering precision in vertical shafts, though tethered variants are capturing margin pools where continuous power and data integrity are non-negotiable. Thermal imaging payloads lead technology adoption in high-temperature process equipment, while ultrasonic integration remains nascent but fastest-growing for wall-thickness measurement without surface contact.
FAA Part 107 waivers for beyond-visual-line-of-sight operations inside structures shape product development timelines for US manufacturers. OSHA 1910.146 confined space standards directly convert to drone procurement budgets as operators calculate cost-per-inspection against manned entry teams. Stakeholders must monitor evolving EPA methane detection mandates and state-level pipeline safety directives that will determine whether LiDAR or thermal sensor packages become the compliance default for underground storage and distribution infrastructure.
Market Dynamics
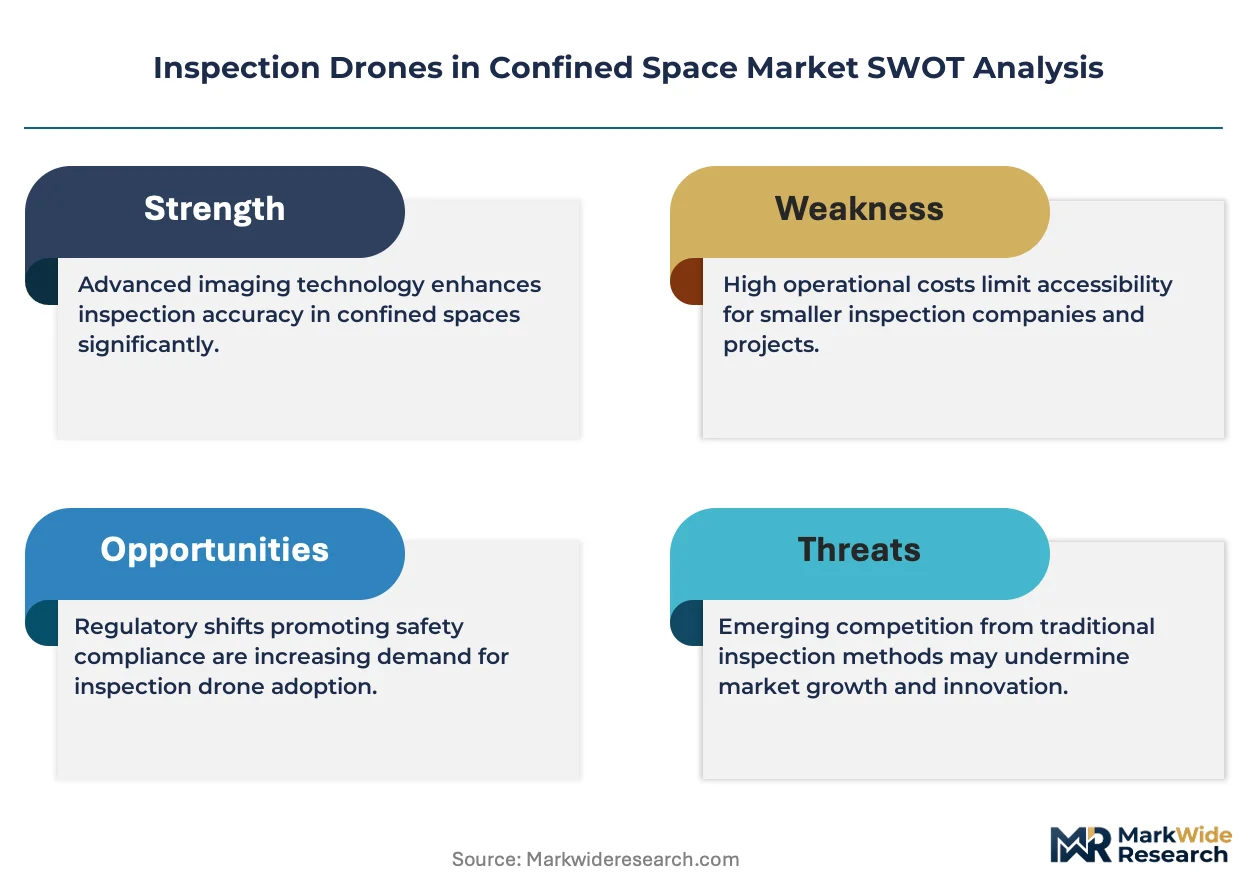
OSHA confined space entry standards are converting directly to drone procurement budgets as operators calculate cost-per-inspection against manned rope-access teams, while FAA Part 107 waiver complexity shapes product development timelines for collision-tolerant platforms.
Growth Catalysts
- Regulatory compliance pressure:OSHA 1910.146 mandates eliminate human entry into hazardous atmospheres, forcing asset owners to automate tank and vessel inspections.
- Flare stack integrity programs:Oil and gas operators in Texas, Louisiana, and North Dakota are expanding autonomous aerial fleets to replace scaffolding crews on elevated structures.
- Real-time gas detection integration:Sensor fusion with onboard atmospheric monitoring enables continuous safety validation during internal tank operations.
Market Restraints
- LiDAR and thermal sensor cost volatility:Precision payload pricing constrains fleet scaling for mid-size inspection contractors.
- Component supply concentration:Critical flight controllers and brushless motors source predominantly from East Asian manufacturing clusters.
- GPS-denied navigation limitations:Magnetic interference inside steel vessels degrades compass reliability, requiring expensive visual-inertial odometry upgrades.
Strategic Opportunities
- Ultrasonic wall-thickness measurement:Non-contact corrosion assessment without surface preparation opens predictive maintenance contracts in chemical processing.
- EPA methane detection mandates:Upcoming underground storage regulations will determine whether thermal or LiDAR packages become compliance defaults.
- Nordic offshore wind expansion:Marine-certified tethered systems address turbine foundation inspections in North Sea salt-air environments.
Industry Challenges
- FAA Part 107 waiver processing delays:Beyond-visual-line-of-sight approvals for internal structure operations extend sales cycles by months.
- Legacy asset integration complexity:Enterprise maintenance management systems require custom API development to ingest drone-derived defect data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inspection Drones in Confined Space Market |
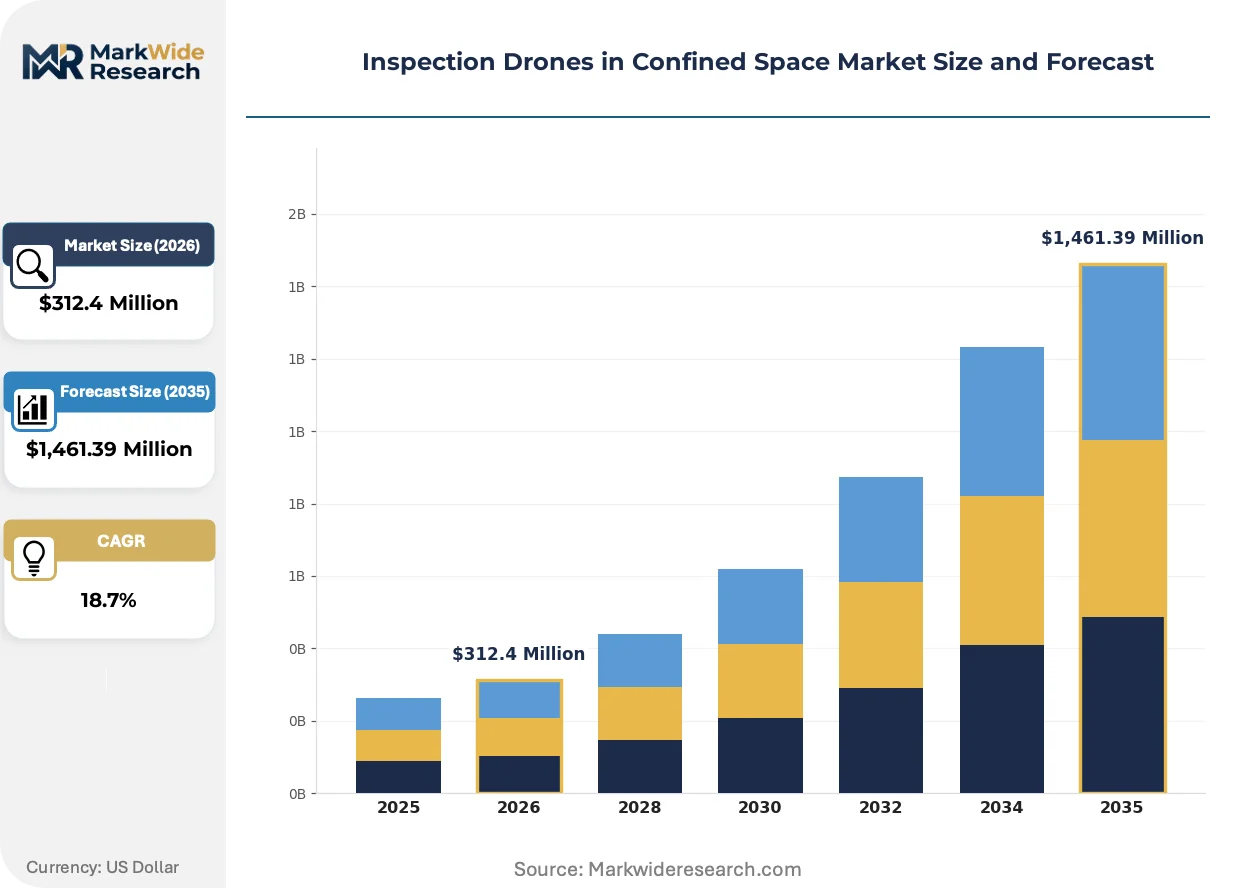
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed Wing, Hybrid, Tethered End User: Construction, Oil & Gas, Utilities, Mining Technology: Visual, Thermal, LiDAR, Ultrasonic Application: Inspection, Surveying, Monitoring, Maintenance |
| Companies Covered | ACSL Ltd, Multinnov, Flyability, Avetics, Altomaxx, DJI, ScoutDI, AETOS, Flybotix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inspection Drones in Confined Space Market Emerging Trajectories
Collision-tolerant exoskeletons and tethered power architectures are reshaping platform design priorities as end-users prioritize operational continuity over acquisition cost in hazardous environment deployments.
Tethered drone systems with continuous power and fiber-optic data links are expanding into nuclear containment and chemical pressure vessel inspections where mission duration exceeds battery chemistry limits. Refinery operators in the US Gulf Coast are standardizing these configurations for 8-hour shift-aligned inspection cycles. The technology is expanding into margin pools previously served by robotic crawlers, compressing the addressable market for ground-based alternatives.
OSHA confined space entry standard updates are tightening respiratory protection requirements for manned tank entry, accelerating substitution toward remotely operated aerial platforms. The regulatory friction converts directly to capital allocation shifts as safety managers face elevated liability exposure from traditional rope-access methods. Petrochemical clusters in Texas and Louisiana are responding fastest, embedding drone procurement into annual turnaround budgets.
Service unbundling is fragmenting the traditional integrated vendor model as end-users separately source airframes, sensor payloads, and pilot services. Independent inspection contractors in North Dakota's Bakken formation now assemble multi-vendor stacks rather than purchasing turnkey systems. This pattern concentrates most visibly among mid-size operators lacking dedicated aviation departments but requiring specialized thermal and ultrasonic configurations.
Inspection Drones in Confined Space Market Segmentation
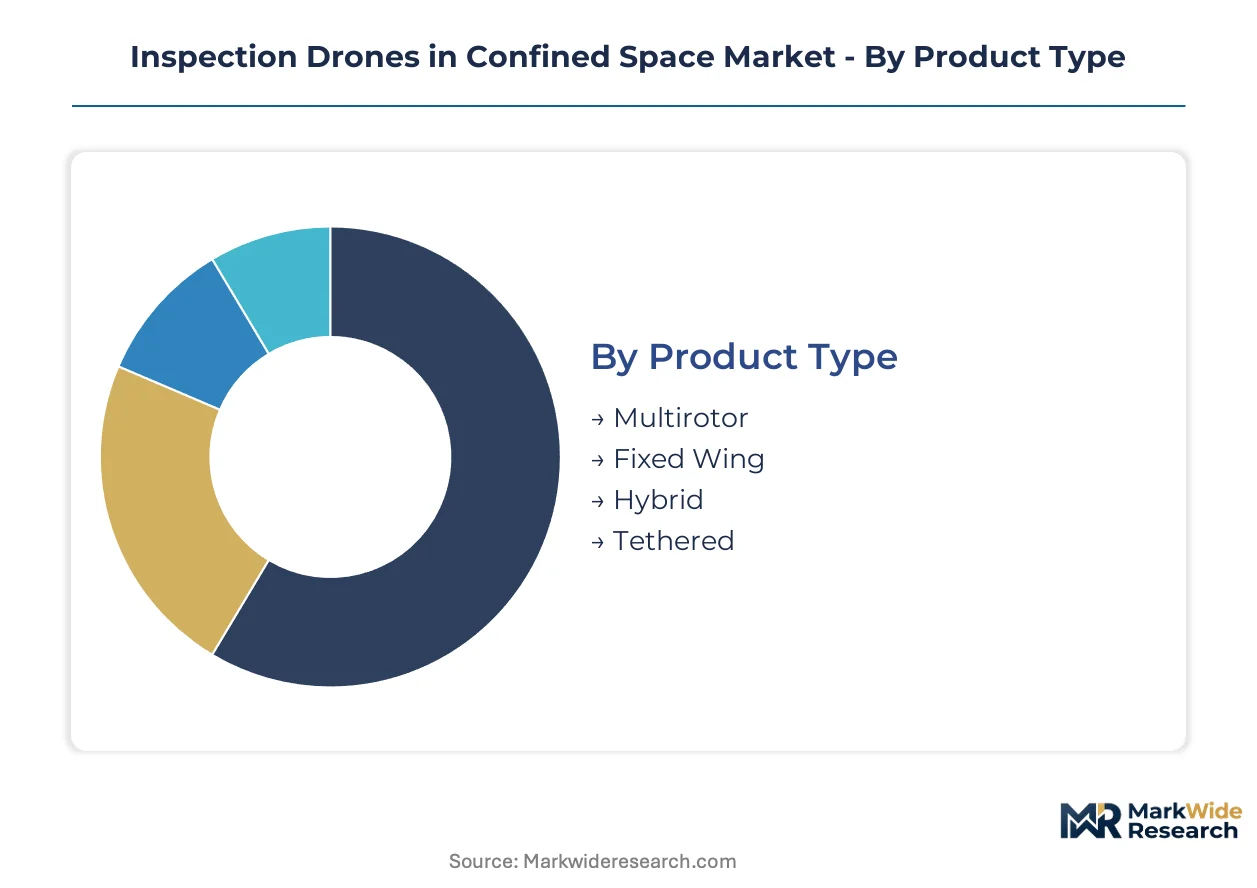
Platform architecture, sensor payload, and operational purpose define procurement decisions in confined space drone deployments. Buyers prioritize collision tolerance against mission duration, regulatory compliance against inspection depth, and data fidelity against platform cost.
Product Type:
Flight configuration determines where operators can deploy inside GPS-denied steel structures and how long missions can sustain without human intervention.
- Multirotor:Quad- and hexacopter designs dominate vertical shaft inspections in silos and pressure vessels. Hovering precision matters most in Texas and Louisiana refineries where flare stack internal baffles require millimetric positioning.
- Tethered:Continuous power and fiber-optic data links enable 8-hour shift-aligned inspection cycles in nuclear containment vessels. US Gulf Coast operators are standardizing these for chemical pressure vessel work, compressing demand for robotic crawlers.
- Fixed Wing:Deployed in large-diameter storage tanks and mine shafts where linear flight paths suffice. Battery constraints limit mission duration to under 45 minutes in most steel-enclosed environments.
- Hybrid:VTOL-capable fixed-wing platforms bridge hovering precision with extended range. Adoption concentrates in mining operations across North Dakota where vertical shafts connect to horizontal drifts.
Multirotor systems lead volumes today; tethered configurations are gaining share fastest as OSHA respiratory protection tightening accelerates substitution away from manned entry teams.
End User:
Asset complexity and regulatory exposure shape technology requirements across verticals, with liability thresholds converting directly to automation budgets.
- Oil & Gas:Flare stack integrity programs and tank farm atmospheric monitoring drive fleet expansion. North Dakota Bakken operators calculate cost-per-inspection against rope-access teams, embedding drone procurement into turnaround budgets.
- Utilities:Boiler tube inspections and underground vault assessments require thermal payloads for hot-spot detection. Texas utility operators face FERC pipeline safety directives that elevate predictive maintenance automation priorities.
- Construction:Tunnel boring machine follow-up and concrete void detection utilize visual-inertial odometry for GPS-denied navigation. Project contractors prioritize acquisition cost over sensor sophistication in this segment.
- Mining:Ore pass hang-up assessments and raise bore stability inspections demand collision-tolerant exoskeletons. Underground operations in salt-air environments specify marine-certified tethered systems for continuous ventilation shaft monitoring.
Oil and Gas leads volumes today; Utilities are climbing the fastest as EPA methane detection mandates reshape underground storage inspection protocols.
Technology:
Sensor fusion capabilities determine whether platforms can replace multiple manned inspection modalities in a single deployment.
- Thermal:Infrared imaging detects hot spots in high-temperature process equipment and identifies insulation failures in refinery vessels. Integration with real-time gas detection enables continuous safety validation during internal tank operations.
- LiDAR:Obstacle-avoidance and millimetric defect mapping function in magnetic-interference environments where compass reliability degrades. Cost volatility in precision payload pricing constrains fleet scaling for mid-size inspection contractors.
- Visual:High-resolution RGB cameras remain the baseline for crack detection and corrosion assessment. Standard configurations suffice where surface preparation is possible prior to inspection.
- Ultrasonic:Non-contact wall-thickness measurement without surface preparation opens predictive maintenance contracts in chemical processing. The capability remains nascent but represents the steepest expansion trajectory as corrosion monitoring contracts extend to multi-year engagements.
Thermal payloads lead volumes today; Ultrasonic integration is expanding most quickly as asset owners seek to eliminate scaffolding for thickness verification.
Application:
Mission purpose dictates platform-sensor pairing and determines whether outcomes justify FAA Part 107 waiver complexity for beyond-visual-line-of-sight operations.
- Inspection:Defect detection in tanks, vessels, and ducts constitutes the core use case driving OSHA confined space substitution. Procurement budgets convert directly from manned entry cost calculations.
- Monitoring:Continuous atmospheric validation and structural health surveillance require persistent deployment architectures. Tethered systems capture this margin pool where battery chemistry limits prohibit intermittent recharging.
- Surveying:Volumetric measurement and as-built documentation utilize LiDAR point clouds for digital twin construction. Mining operators in North Dakota deploy these for ore pass geometry verification.
- Maintenance:Coating application and minor repair interventions remain experimental, with most platforms limited to observation and data capture rather than physical manipulation.
Inspection leads volumes today; Monitoring is gaining share fastest as real-time gas detection integration enables shift-aligned continuous operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor concentrates immediate procurement volumes as OSHA 1910.146 enforcement tightens across Texas and Louisiana refineries. Regulatory pressure converts directly to capital allocation shifts as operators replace rope-access teams with collision-tolerant aerial platforms.
United States
Flare stack integrity programs and pressure vessel automation drive fleet expansion across Texas, Louisiana, and North Dakota. FAA Part 107 waiver complexity shapes product development timelines for beyond-visual-line-of-sight operations inside steel structures. Houston anchors the largest concentration of refinery operators embedding drone procurement into annual turnaround budgets.
Norway
North Sea offshore wind foundation inspections and subsea infrastructure monitoring create sustained demand for marine-certified tethered systems. The country's petroleum regulator mandates continuous structural health surveillance for aging platforms. Stavanger hosts the primary cluster of energy operators standardizing 8-hour shift-aligned inspection cycles.
Germany
Chemical processing plant automation and nuclear containment vessel protocols elevate collision-tolerant platform specifications. REACH compliance requirements for atmospheric monitoring inside tanks accelerate sensor fusion adoption. The Ruhr industrial region concentrates predictive maintenance contracts for wall-thickness measurement without surface preparation.
China
MIIT standards for industrial UAV navigation in GPS-denied environments reshape domestic platform engineering priorities. State-owned refinery operators in Shandong and Jiangsu provinces calculate cost-per-inspection against traditional scaffolding crews. The Yangtze River Delta anchors manufacturing scale for brushless motors and precision flight controllers.
United Kingdom
North Sea decommissioning schedules and offshore platform life-extension programs sustain tethered system demand. The Health and Safety Executive's confined space guidance converts to procurement budgets for atmospheric monitoring integration. Aberdeen maintains the primary service provider cluster for marine-certified inspection operations.
Inspection Drones in Confined Space Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized certification pathways for nuclear and chemical vessel applications. The vendor base stratifies across three functional tiers: collision-tolerance specialists commanding premium positioning, scale-driven manufacturers competing on unit economics, and regional system integrators assembling multi-vendor stacks. Strategic moves concentrate on sensor payload partnerships and FAA certification acceleration rather than horizontal consolidation.
Within the collision-tolerance tier, Flyability exemplifies premium positioning through protective exoskeleton design, while ScoutDI anchors Nordic offshore demand with marine-certified tethered architectures. DJI occupies the scale-driven segment, leveraging manufacturing breadth across utility and tunnel applications. These three represent distinct competitive vectors: engineering-intensive specialization, regional regulatory alignment, and production cost compression.
| Leading Market Players |
|---|
| ACSL Ltd |
| Multinnov |
| Flyability |
| Avetics |
| Altomaxx |
| DJI |
| ScoutDI |
| AETOS |
| Flybotix |
| Others |
Supply Flow & Price Mechanics
OSHA respiratory protection tightening in Texas and Louisiana refineries is forcing mid-size inspection contractors toward multi-vendor procurement stacks, compelling suppliers to unbundle integrated platforms and compressing margins on turnkey systems while elevating component-level price transparency.
Pricing Analysis
LiDAR and thermal sensor cost volatility passes through directly to platform pricing, with three-tier pricing structure across premium, standard, and economy levels separating FAA-certified collision-tolerant systems from uncertified utility configurations. Price differentiation hinges on OSHA compliance documentation depth and FAA Part 107 waiver support services. Pricing pressure stems from East Asian flight controller supply bottlenecks. Mid-size contractors exhibit highest price sensitivity; nuclear operators show lowest.
Supply Chain Analysis
Dual-sourcing mandates from US Gulf Coast operators require qualified backup suppliers for collision-tolerant airframes and gas detection payloads, stretching procurement timelines. Manufacturing concentrates in China, South Korea, and Taiwan for brushless motors, precision flight controllers, and LiDAR sensors. Supply chain risk centers on single-source vulnerability for visual-inertial odometry chipsets. Distribution runs through specialized industrial UAV distributors and direct OEM channels to large refinery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FAA Part 107 waiver complexity in the United States creates 6-12 month sales cycle premiums that Nordic operators bypass through EASA's more streamlined internal-structure approvals, compressing time-to-revenue for marine-certified tethered platforms.
For Market Incumbents: Extend collision-tolerance certification pathways into EPA methane detection compliance packages before ultrasonic integration commoditizes thickness measurement. Secure exclusive sensor fusion partnerships with gas detection specialists to lock out modular competitors. Capacity expansion in Stavanger addresses North Sea offshore wind demand directly. For New Entrants and Emerging Players: Independent inspection contractors in North Dakota's Bakken formation represent the most penetrable buyer archetype, lacking dedicated aviation departments but requiring specialized thermal configurations. White-space exists in ultrasonic payload-only sales to existing multirotor fleets. Go-to-market through regional industrial equipment distributors bypasses incumbent direct-sales relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with marine-certified tethered system specialists holding EASA approvals and North Sea operator relationships, positioned for offshore wind foundation inspection contracts. Five-to-ten year viability hinges on EPA methane mandate timing. Acquisition targets should demonstrate shift-aligned operational continuity. Watch OSHA 1910.146 enforcement intensity in Texas refineries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 107 Waiver Acceleration | Reduces sales cycle friction for beyond-visual-line-of-sight internal operations in US refineries. |
| Ultrasonic Sensor Integration Partnership | Opens predictive maintenance contracts in chemical processing without surface preparation requirements. |
| Marine Certification Expansion | Captures North Sea offshore wind foundation inspection demand from Stavanger operators. |
| Multi-Vendor Stack Assembly Service | Addresses mid-size contractor procurement preference in North Dakota Bakken formation. |
| Real-Time Gas Detection Fusion | Enables continuous atmospheric validation during OSHA-mandated tank entry substitution. |
Methodological Framework
Bottom-up refinery operator modeling reconciled against top-down sensor payload manufacturing tracking forms the analytical core of this study. Primary interviews with safety managers at Texas and Louisiana petrochemical facilities, FAA Part 107 waiver consultants, industrial UAV procurement leads, and collision-tolerance engineering directors combined with secondary validation against OSHA enforcement records, FAA waiver approval databases, EIA refinery capacity reports, and North Sea offshore wind project development filings. Triangulation between demand-side budget allocation data and supply-side component shipment tracking ensures cross-verified volume estimates.
Historical trendline analysis across platform deployment records and sensor adoption curves established baseline growth patterns. The projection framework segments by flight configuration, sensor payload type, end-use vertical, and regional regulatory cluster, with CAGRs derived from regression analysis against OSHA enforcement intensity indices and EPA rulemaking timelines. Industry-specific forecast inputs include refinery turnaround schedules, offshore wind foundation installation rates, and nuclear containment vessel inspection cycle frequencies.
Underlying measurement precision varies by segment; tethered system deployments and oil and gas procurement budgets carry tighter precision than emerging ultrasonic integration forecasts. Projections reflect assumptions regarding FAA waiver processing efficiency, LiDAR sensor cost stabilization, and OSHA respiratory protection rule finalization. Deviation in EPA methane detection mandate implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone-In-A-Box Market
UAV
Drone Tracking Antenna Market
UAV
North America Tactical UAV Market
UAV
North America Drone Software Market
UAV
UAV Simulator Software Market
UAV
Counter Drone System Market
UAV
Aerial Smart Weapons Market
UAV
North America Drones Market
UAV
Auto-Follow Drone Market
UAV
Global Drone Data Services Market
UAV
Utility Drone Market
UAV
UAV GNSS Antenna Market
UAV
Global Drone Sensor Market
UAV
UAV Navigation Systems Market
UAV
Global Drone Analytics Market
UAV
Europe Drones Market