
 North America Hydrographic Survey Equipment Market | 2026-2036
North America Hydrographic Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrographic Survey Equipment Market Insights
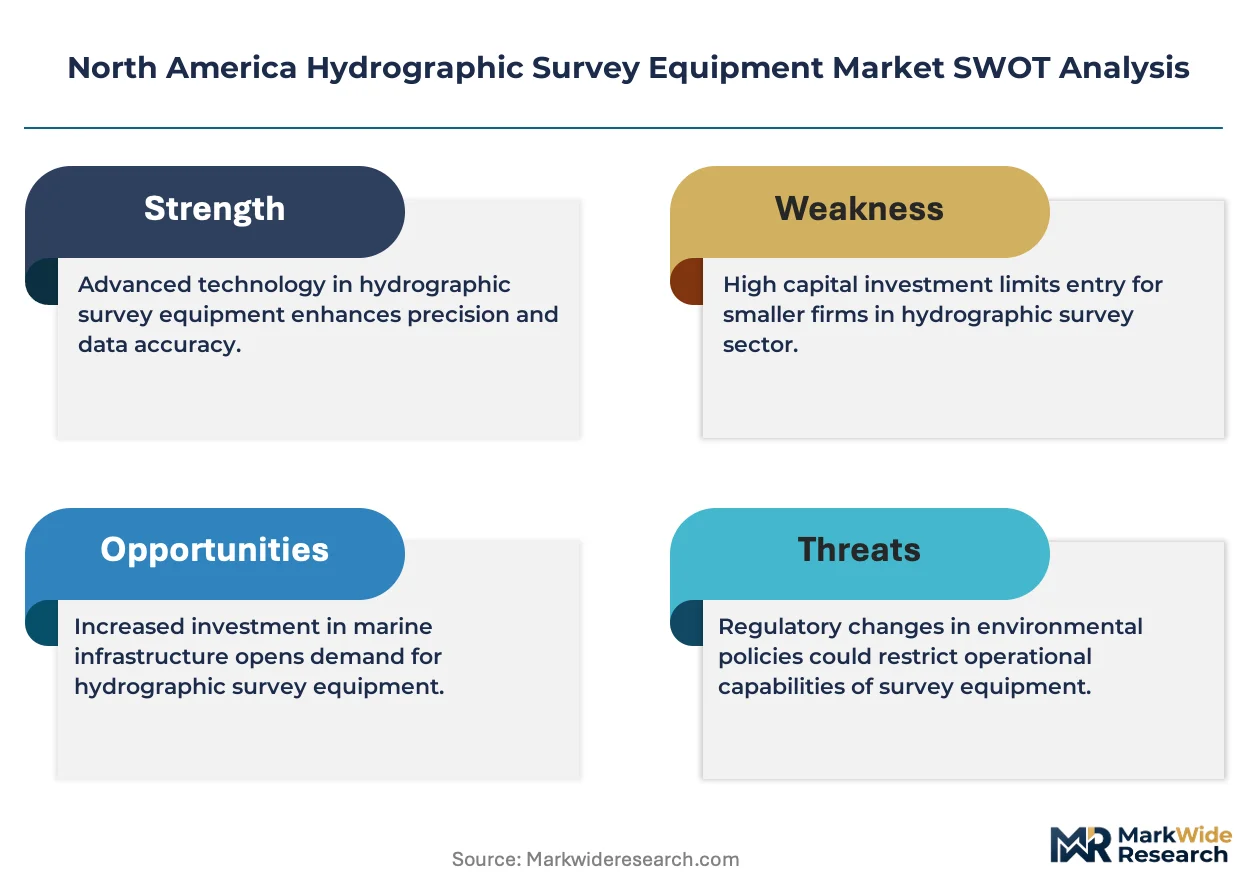
The capability gap between capital-heavy sonar manufacturers and software-centric data processors is collapsing as integrated platform economics favor end-to-end vendors. Teledyne Marine Technologies Incorporated leverages captive sensor production across its marine instrumentation portfolio. EdgeTech anchors its position through specialized acoustic release and side-scan technologies. Xylem competes with water analytics expertise that extends into bathymetric monitoring networks.
North America hydrographic survey equipment encompasses sonar, positioning, and data acquisition systems engineered to measure water depth, seafloor topography, and submerged object detection with sub-meter accuracy, primarily serving maritime safety, resource extraction, and environmental compliance. Multibeam echo sounding dominates technology procurement due to wide swath coverage and high point density for commercial port expansions. Single beam echo sounding retains cost advantages in inland waterway and small-craft applications. Government agencies represent the largest end-user segment given sustained NOAA and U.S. Army Corps of Engineers charting mandates.
The U.S. National Oceanic and Atmospheric Administration enforces nautical charting standards that directly dictate survey frequency and equipment certification requirements for federal contractors. Canadian Hydrographic Service standards align with International Hydrographic Organization protocols, creating cross-border interoperability demands for vendors serving both markets. State-level coastal zone management programs in California and Florida layer additional environmental review requirements onto marine construction surveys. Stakeholders must monitor evolving federal infrastructure spending allocations and offshore lease schedule accelerations to align production capacity with procurement waves.
Market Dynamics
Offshore wind lease accelerations along the Atlantic seaboard are compressing survey timelines and forcing multibeam sonar procurement cycles into 18-month windows, collapsing traditional equipment planning horizons for contractors serving Bureau of Ocean Energy Management developments.
Growth Catalysts
- NOAA Charting Mandates:The U.S. National Oceanic and Atmospheric Administration requires updated nautical charting standards that dictate federal contractor certification and survey frequency, sustaining baseline equipment demand regardless of commercial cycles.
- Gulf of Mexico Corridor Concentration:Louisiana and Texas harbor dense clusters of offshore oil platform decommissioning and coastal restoration projects requiring high-resolution bathymetric mapping.
- Multibeam Echo Sounding:Wide swath coverage technology enables single-vessel surveys to replace multi-pass single-beam operations, reducing day rates for port expansion contractors.
Market Restraints
- Sensor Supply Concentration:Piezoelectric ceramic substrates for transducer arrays concentrate among Japanese and German specialty material suppliers, creating input vulnerability for North American sonar manufacturers.
- Technical Limitation:Acoustic shadowing in complex seabed geometries near submarine canyon walls forces redundant survey passes, inflating operational costs beyond initial vessel day-rate estimates.
- Regulatory Friction:Canadian Hydrographic Service alignment with International Hydrographic Organization protocols creates dual-certification burdens for vendors seeking cross-border contract eligibility.
Strategic Opportunities
- California Coastal Zone Management:State-level environmental review requirements for marine construction surveys layer additional compliance-driven equipment procurement onto federally mandated programs.
- Autonomous Underwater Vehicle Convergence:Integration of multibeam payloads with untethered AUV platforms eliminates surface vessel dependency for deep-water pipeline inspection routes.
- Florida Reef Restoration:Coral transplantation and artificial reef deployment programs generate recurring shallow-water survey demand distinct from commercial port or offshore energy applications.
Industry Challenges
- Hydrographic Surveyor Certification Bottlenecks:International Hydrographic Organization Category A training programs produce fewer qualified operators than BOEM lease round staffing requirements, compressing crew availability.
- Legacy Data Integration Complexity:Decades of single-beam archival surveys in Army Corps of Engineers databases resist automated fusion with modern multibeam point clouds, forcing manual reprocessing contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrographic Survey Equipment Market |
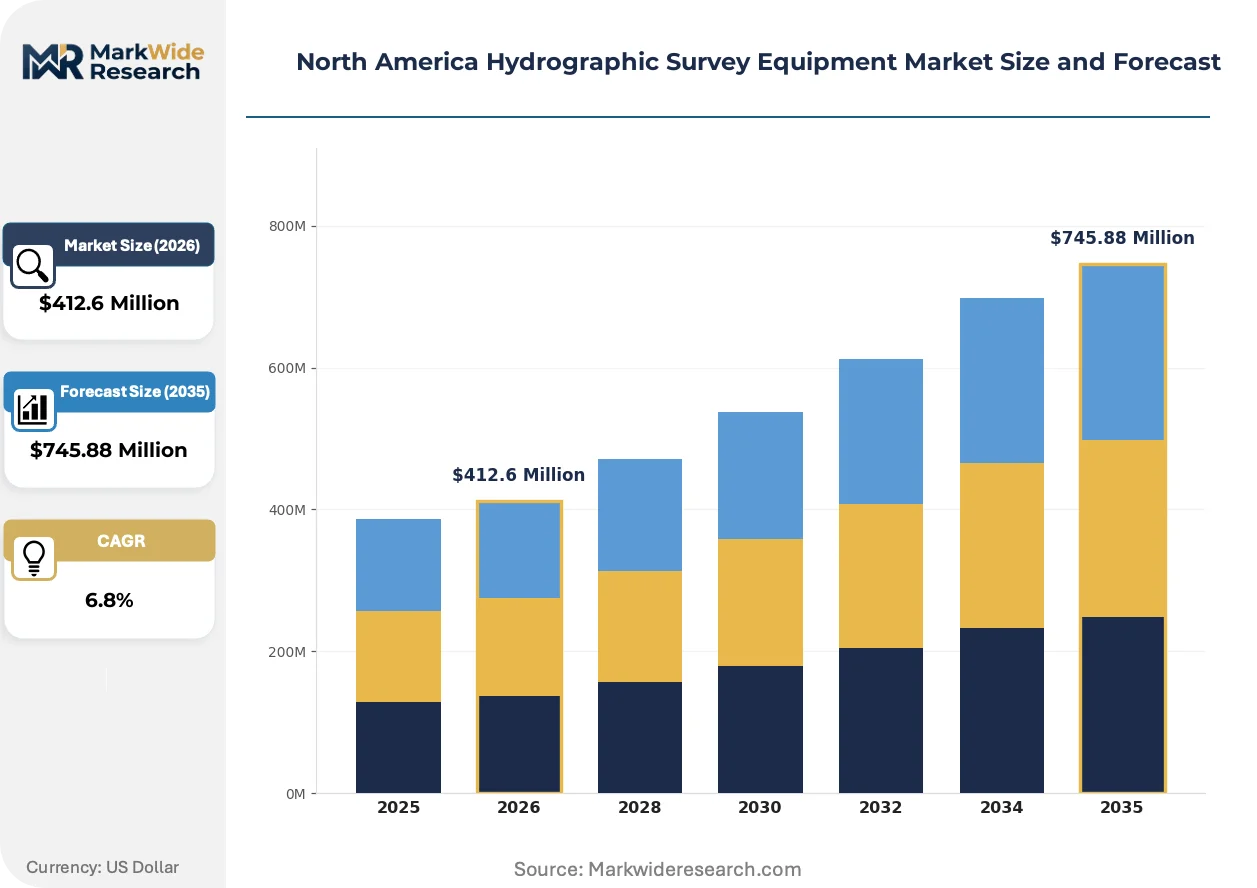
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sonar Systems, GPS Units, Data Loggers, Sub-bottom Profilers End User: Government Agencies, Research Institutions, Environmental Consultants, Oil & Gas Companies Technology: Multibeam Echo Sounding, Single Beam Echo Sounding, Lidar, Acoustic Doppler Application: Marine Research, Coastal Management, Resource Assessment, Navigation |
| Companies Covered | Teledyne Marine Technologies Incorporated, Trimble Applanix, Chesapeake Technology, Esri North America, R2Sonic, EdgeTech, Xylem, CEE HydroSystems, Seafloor Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrographic Survey Equipment Market Trends and Innovations
Competitive positioning in hydrographic survey equipment is collapsing around integrated platform economics, with end-to-end vendors capturing procurement decisions previously fragmented between sensor specialists and software processors.
Cloud-native data processing architectures are supplanting vessel-side workstation dependency for point cloud classification and quality control. Offshore wind developers in Massachusetts and New Jersey are adopting shore-based processing centers to reduce vessel charter durations. This compression of at-sea operational windows is forcing equipment vendors to bundle satellite uplink hardware with sonar sales.
The U.S. Bureau of Ocean Energy Management's renewable energy regulations now mandate pre-construction benthic habitat assessments with sub-meter vertical accuracy for all lease areas. This precision requirement disqualifies legacy single-beam systems from Atlantic coast procurement competitions. Survey contractors are responding by retiring shallow-water analog equipment ahead of depreciation schedules.
Charter arrangements are displacing equipment ownership for midsize environmental consultancies serving state coastal agencies. California and Florida-based firms now source multibeam systems through vessel-operating lessors rather than capital balance sheets, transferring obsolescence risk to specialized marine equipment lessors concentrated in Louisiana and Texas ports.
North America Hydrographic Survey Equipment Market Segmentation
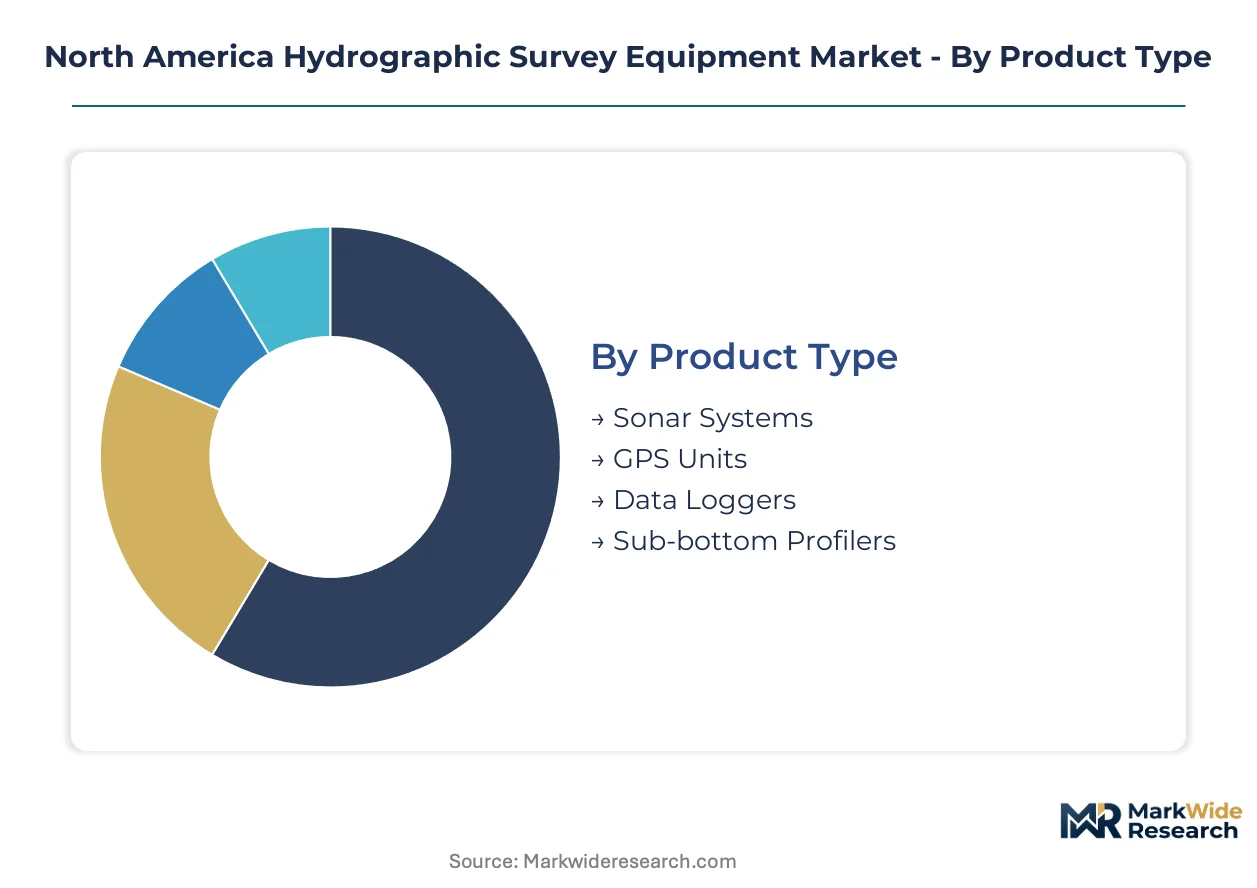
Equipment procurement patterns across North America diverge sharply between federal mandate-driven replacement cycles and commercial project-based spot purchasing. Understanding margin distribution by product configuration and end-user contracting structure enables vendors to align R&D investment with where purchasing authority actually concentrates.
Product Type:
Premium margin pools sit with integrated sensor platforms that bundle transducer arrays with embedded positioning correction, while commoditized standalone components face pricing pressure from offshore wind procurement aggregators.
- Sonar Systems:Multibeam and side-scan configurations generate the highest equipment revenue per vessel installation. Gulf of Mexico offshore platform decommissioning projects in Louisiana and Texas drive concentrated procurement of deep-rated hull-mounted arrays.
- GPS Units:RTK-GNSS receivers with heave compensation command pricing premiums over standard differential units. Port expansion contractors in California and Florida specify centimeter-level vertical accuracy for dredging volume calculations.
- Data Loggers:Edge-computing architectures with real-time quality control algorithms are displacing legacy storage-only units.
- Sub-bottom Profilers:Chirp systems for shallow sediment stratigraphy serve coastal restoration and pipeline burial assessment.
The dominant share belongs to Sonar Systems, while GPS Units is closing the gap fastest as positioning accuracy requirements tighten under Bureau of Ocean Energy Management specifications.
End User:
Contracting authority concentrates with entities holding multi-year federal appropriations, while commercial purchasers operate on compressed procurement windows tied to lease round schedules.
- Government Agencies:NOAA and U.S. Army Corps of Engineers maintain sustained equipment replacement programs with certified vendor lists. Charting mandates in the Atlantic seaboard and Gulf corridor generate predictable multiyear procurement pipelines.
- Oil & Gas Companies:Offshore lease operators in the Gulf of Mexico deploy high-specification multibeam suites for pre-drill site surveys and pipeline route engineering. Decommissioning liability assessments are expanding survey frequency beyond exploration phases.
- Environmental Consultants:Midsize firms serving state coastal agencies increasingly source equipment through Louisiana and Texas-based vessel lessors rather than capital purchases.
- Research Institutions:Academic vessel operators prioritize modular payload flexibility over single-purpose integrated systems.
Government Agencies command the largest equipment installed base, though Oil & Gas Companies are gaining share fastest as offshore wind lease rounds accelerate Atlantic coast survey demand.
Technology:
Performance differentiation now hinges on swath coverage width and point density rather than raw depth rating, shifting R&D investment toward beam-forming algorithms and motion compensation integration.
- Multibeam Echo Sounding:Wide-swath bathymetry with backscatter intensity mapping has become the default specification for commercial port expansions. Massachusetts and New Jersey offshore wind developers mandate sub-meter vertical accuracy that disqualifies legacy alternatives.
- Single Beam Echo Sounding:Compact hull-mounted units retain cost advantages for inland waterway maintenance and small-craft applications. Army Corps of Engineers districts in the Mississippi River basin continue specifying single-beam for routine channel condition surveys.
- Lidar:Airborne bathymetric laser systems penetrate shallow turbid water for coral reef and seagrass mapping in Florida coastal zones.
- Acoustic Doppler:Current profiling configurations support sediment transport studies and tidal energy site assessment.
Multibeam Echo Sounding holds the technology leadership position, while Lidar is expanding most quickly as state environmental review requirements layer additional shallow-water mapping mandates onto federal programs.
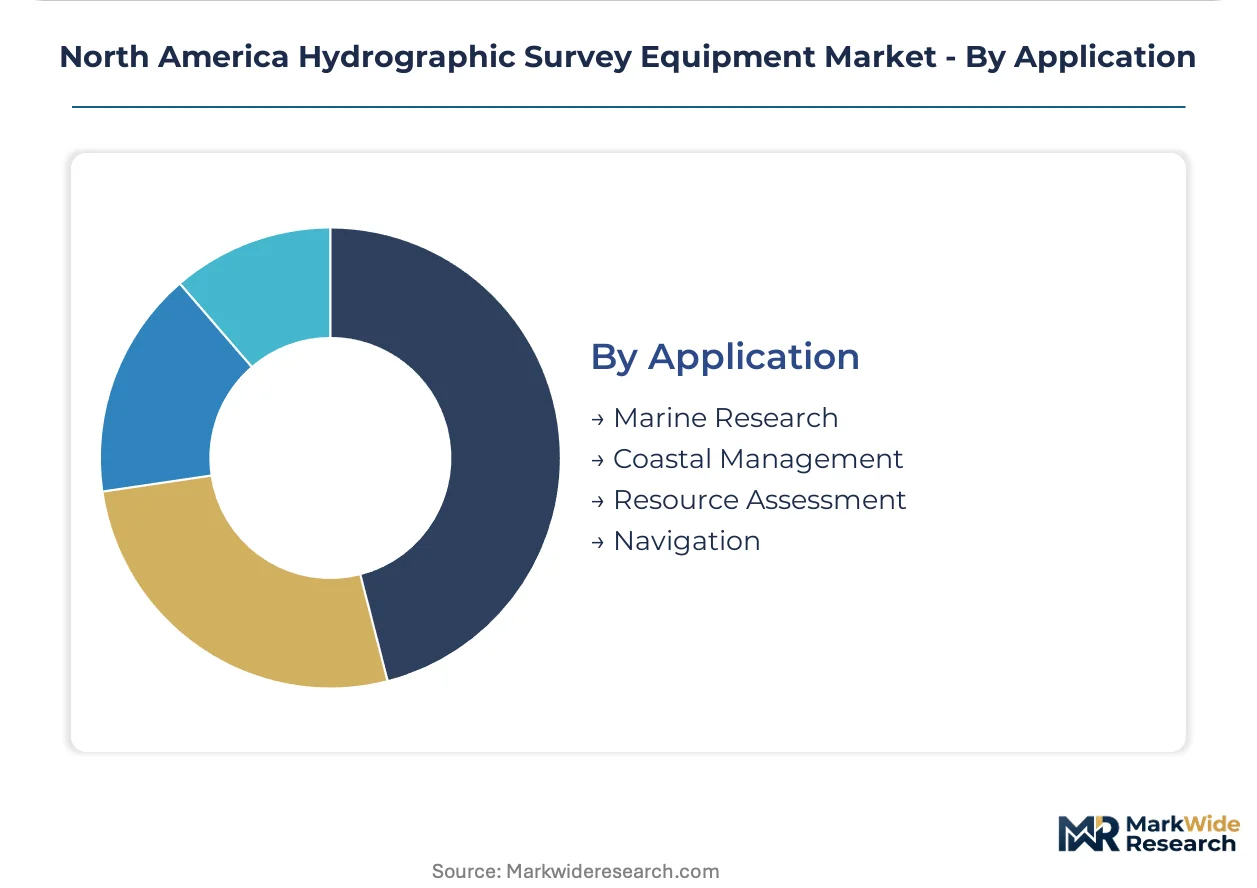
Application:
Revenue stability varies dramatically between cyclical resource extraction surveys and recurring coastal maintenance programs with multi-decade funding authorization.
- Navigation:Nautical charting under NOAA and Canadian Hydrographic Service jurisdiction sustains baseline demand regardless of commercial cycles. Federal contractor certification requirements create vendor stickiness in this segment.
- Coastal Management:California and Florida state-level environmental review programs generate recurring shallow-water survey demand for marine construction permitting. Artificial reef deployment and coral restoration in Florida waters require repeated post-construction monitoring.
- Resource Assessment:Offshore wind benthic habitat surveys and oil platform decommissioning site assessments operate on project-specific timelines.
- Marine Research:Academic vessel operations depend on federal science agency grant cycles with irregular equipment replacement schedules.
Navigation maintains the most stable demand profile, though Coastal Management is climbing the fastest as state environmental compliance layers onto federal infrastructure spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America hydrographic survey equipment trade flows reflect a net import position in specialized transducer ceramics and a net export position in integrated sonar platforms. Canadian and Mexican demand draws heavily on U.S.-assembled systems, while component sourcing reaches overseas for piezoelectric substrates.
United States
Atlantic offshore wind lease rounds in Massachusetts and New Jersey compress survey timelines to 18-month procurement windows. The Bureau of Ocean Energy Management mandates sub-meter vertical accuracy for benthic habitat assessments. Gulf of Mexico corridor activity from Texas through Louisiana concentrates decommissioning surveys and coastal restoration bathymetry.
Canada
Arctic shipping route preparation and port modernization in British Columbia sustain multibeam echo sounder demand. The Canadian Hydrographic Service maintains alignment with International Hydrographic Organization protocols, creating certification requirements for federal contractors. Vancouver and Halifax harbor clusters anchor equipment deployment for Pacific and Atlantic seaboard charting programs.
Mexico
Port expansion at Lázaro Cárdenas and energy infrastructure in the Gulf of Campeche generate survey contracting opportunities. Mexican maritime authorities coordinate with U.S. standards for cross-border waterway management. Tampico and Veracruz serve as concentration points for Pemex-related pipeline route surveys and coastal engineering.
North America Hydrographic Survey Equipment Market Competitive Landscape
Concentration sits with integrated platform vendors that bundle transducer arrays, positioning correction, and data processing architectures. The vendor landscape separates into three archetypes: captive sensor manufacturers with marine instrumentation portfolios, specialized acoustic technology developers, and water analytics firms extending into bathymetric monitoring. Competitive moves center on backward integration into transducer ceramic supply and satellite uplink hardware bundling for shore-based processing workflows.
Among sensor-integrated specialists, Teledyne Marine Technologies Incorporated anchors the captive production archetype through its marine instrumentation portfolio. EdgeTech occupies a position exemplifying specialized acoustic release and side-scan technology concentration. Xylem represents the water analytics extension pattern, leveraging monitoring network expertise into bathymetric applications. These three firms illustrate the platform economics shift collapsing procurement decisions toward end-to-end vendors.
| Leading Market Players |
|---|
| Teledyne Marine Technologies Incorporated |
| Trimble Applanix |
| Chesapeake Technology |
| Esri North America |
| R2Sonic |
| EdgeTech |
| Xylem |
| CEE HydroSystems |
| Seafloor Systems |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-day lead times for piezoelectric ceramic substrates from Japanese and German specialty suppliers concentrate pricing power upstream, forcing North American sonar manufacturers to absorb cost volatility or pass through to offshore wind developers with compressed 18-month procurement windows. This inventory exposure at the transducer array level shapes how integrated platform vendors bundle positioning correction and data processing to defend margin pools.
Pricing Analysis
Configured-to-order multibeam systems command spreads of 40-60 percent above standard hull-mounted configurations, with pricing stratifying across IHO-certified, commercial-grade, and inland waterway tiers. Project-based contracting dominates Atlantic seaboard offshore wind procurement, while NOAA and Army Corps of Engineers sustain annual replacement programs with less elasticity. Price differentiation hinges on vertical accuracy certification and real-time motion compensation integration. Cost compression in standard single-beam units is intensifying because environmental consultancies now source through Louisiana and Texas-based vessel lessors rather than capital purchases.
Supply Chain Analysis
Inventory concentration for piezoelectric ceramics in Japan and Germany, plus precision machining capacity in the United States and Canada, creates geographic dependency for transducer array fabrication. Raw material flows draw from rare-earth element processing in China, nickel alloy forging in South Korea, and semiconductor-grade epoxy packaging in Taiwan. Single-source vulnerability sits with Japanese ceramic substrate suppliers holding 70-plus percent of high-frequency transducer feedstock. Distribution runs through direct OEM relationships for federal contractors and vessel-operating lessors for commercial spot purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hydrographic survey equipment market rewards vendors who control scarce IHO Category A surveyor certification pipelines and captive transducer ceramic supply, as Bureau of Ocean Energy Management lease rounds outstrip qualified crew availability.
For Market Incumbents: Compound platform stickiness by bundling satellite uplink hardware with sonar sales to capture shore-based processing workflows, and deepen backward integration into piezoelectric ceramic supply to offset Japanese supplier concentration. Autonomous underwater vehicle payload integration threatens standalone sensor vendors who lack end-to-end data architectures. For New Entrants and Emerging Players: Anchor in Florida reef restoration and California coastal zone management programs, where state environmental review requirements layer recurring shallow-water survey demand atop federal mandates. Artificial reef deployment monitoring offers the most penetrable application, with go-to-market traction through vessel-operating lessor partnerships rather than direct capital sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because NOAA charting mandates and BOEM benthic habitat assessment rules create decade-long equipment replacement cycles insulated from commodity volatility. Acquisition targets should display IHO certification depth and AUV payload integration roadmaps. The signal to watch is Bureau of Ocean Energy Management lease schedule acceleration beyond current Atlantic seaboard rounds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Ceramics | Captive supply of piezoelectric substrates neutralizes Japanese supplier concentration risk for federal contractors. |
| Satellite Uplink Hardware Bundling | Shore-based processing workflows reduce vessel charter durations for Massachusetts and New Jersey offshore wind developers. |
| AUV Payload Integration | Untethered platforms eliminate surface vessel dependency for deep-water pipeline inspection routes in the Gulf of Mexico. |
| IHO Category A Certification Investment | Federal contractor eligibility hinges on surveyor training pipeline depth amid BOEM lease round staffing shortages. |
| Vessel Lessor Partnership Development | Equipment-as-a-service models transfer obsolescence risk from California and Florida environmental consultancies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hydrographic survey contractors, NOAA procurement officers, offshore wind project developers, and vessel-operating lessor executives. Secondary validation drew from Bureau of Ocean Energy Management lease filings, U.S. Army Corps of Engineers charting appropriations, Canadian Hydrographic Service standards documentation, and International Hydrographic Organization certification records. Bottom-up equipment shipment estimates and top-down federal contracting value analysis were triangulated to anchor volume and value outputs.
Across the analysis window, the forecasting framework modeled demand by product type, end-user contracting structure, technology performance tier, and application funding stability. CAGRs were derived from equipment replacement cycle analysis and federal infrastructure appropriation trajectories. Key inputs included BOEM lease round schedules, NOAA nautical charting mandate refresh cycles, and offshore wind turbine foundation installation timelines.
Material uncertainties — federal infrastructure spending reallocation, IHO certification program expansion rates, and transducer ceramic supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding sustained charting mandate enforcement and Atlantic seaboard offshore wind development continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Military Jammer Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
UXO Detection Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market