
 Defense Geospatial Market | 2026-2036
Defense Geospatial Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Geospatial Market Analysis
Resolution-grade satellite imagery is redrawing competitive benchmarks across defense geospatial procurement. Thales Group leverages its dual-use satellite manufacturing base to sustain European government contracts. Raytheon Technologies Corporation anchors US defense geospatial integration through classified sensor-to-shooter networks. Lockheed Martin Corporation dominates high-altitude persistent infrared platforms that feed geospatial exploitation systems.
Defense geospatial systems encompass the acquisition, processing, analysis, and dissemination of spatially referenced information to support military operations, typically involving panchromatic resolutions below 0.5 meters and multispectral bands from visible to short-wave infrared for target discrimination. These systems enable precision navigation, battlespace visualization, and real-time situational awareness for commanders across terrestrial and maritime domains. Satellite imagery retains the largest revenue share among product types due to constellation replenishment cycles and sovereign capacity investments, while geospatial analysis tools demonstrate the fastest expansion as defense agencies deploy machine learning for automated feature extraction. Intelligence agencies represent a concentrated end-user segment with specialized secure infrastructure requirements, whereas defense contractors absorb growing volumes of geospatial subcontracts for platform integration.
US National Geospatial-Intelligence Agency standards, NATO STANAG 2592 for digital geographic information exchange, and EU Space Programme Security Regulations collectively shape product certification, data interoperability mandates, and cross-border sharing protocols for defense geospatial vendors. Compliance with these frameworks determines market access for non-sovereign suppliers and drives R&D investment in encryption-hardened distribution architectures. Stakeholders must monitor accelerating classification of commercial remote sensing capabilities and corresponding restrictions on foreign ownership of ground segment infrastructure.
Market Dynamics
The migration from classified government-only satellite constellations to hybrid commercial-military architectures is compressing procurement cycles and fragmenting vendor hierarchies across defense geospatial supply chains.
Growth Catalysts
- AI-Enhanced Imagery Analysis:Machine learning algorithms for automated feature extraction are accelerating intelligence production timelines. Defense agencies are mandating these capabilities for battlespace visualization platforms.
- NATO STANAG 2592:Standardization for digital geographic information exchange is forcing system interoperability upgrades across member states. This creates replacement demand for legacy proprietary formats.
- Space-Based Reconnaissance:Sovereign capacity investments in dedicated military satellite constellations are driving ground segment procurement. National security priorities in the United States are expanding budget allocations for orbital assets.
Market Restraints
- Launch Cost Volatility:Dependence on limited heavy-lift providers concentrates risk for constellation deployment schedules. Geopolitical tensions affecting launch site access compound schedule uncertainty.
- Technical Limitations:Persistent cloud cover in tropical operational theaters degrades electro-optical sensor utility. Synthetic aperture radar alternatives require substantially higher processing infrastructure investment.
- Regulatory Friction:Accelerating classification of commercial remote sensing capabilities under US National Geospatial-Intelligence Agency directives restricts foreign ownership of ground segment infrastructure. Non-sovereign suppliers face market access barriers.
Strategic Opportunities
- Underpenetrated Sovereign Capacity:European Union member states lacking independent satellite manufacturing bases present integration contract opportunities for specialized subsystem vendors.
- Technology Convergence:Fusion of hyperspectral imaging with signals intelligence payloads is creating multi-intelligence platform demand. Prime contractors are soliciting compact sensor package designs.
- EU Space Programme Security Regulations:Certification frameworks for encrypted distribution architectures are creating first-mover advantages for compliance-ready vendors. R&D investment in hardened ground stations qualifies for strategic funding.
Industry Challenges
- Specialized Talent Scarcity:Clearance-qualified geospatial data scientists with machine learning expertise command premium compensation. Defense contractors compete with commercial technology firms for identical skill profiles.
- Integration Complexity:Legacy command-and-control systems require costly middleware development to interface with modern AI-enhanced exploitation platforms. Fielded systems span decades of procurement cycles with incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Geospatial Market |
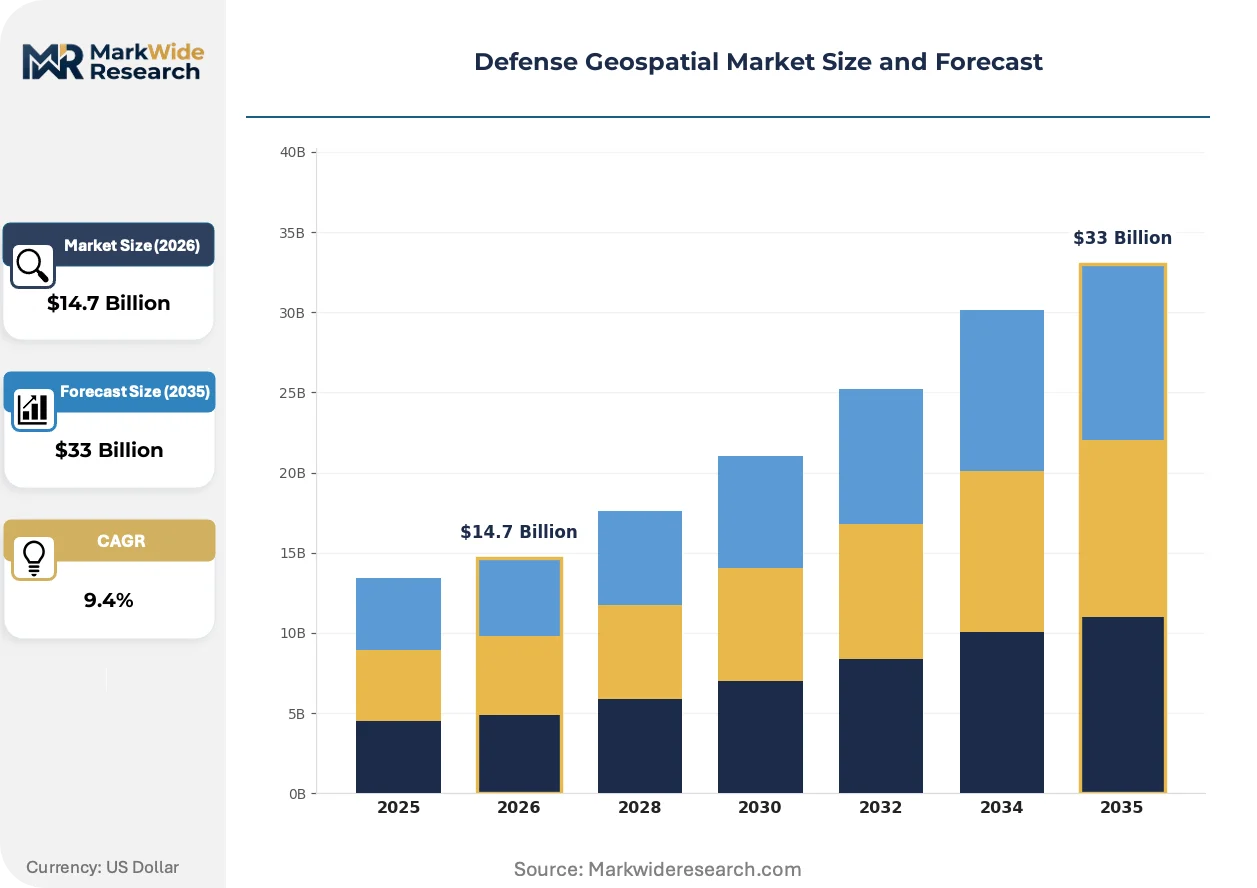
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Imagery, Aerial Surveys, Geospatial Analysis Tools, Mapping Software End User: Military, Intelligence Agencies, Defense Contractors, Government Organizations Technology: Remote Sensing, GIS, 3D Modeling, Data Analytics Application: Border Security, Tactical Planning, Environmental Monitoring, Disaster Management |
| Companies Covered | Airbus Group, Thales Group, Raytheon Technologies Corporation, Leidos Holdings Inc., L3Harris Technologies Inc., Lockheed Martin Corporation, BAE Systems plc, Hexagon AB, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Geospatial Market Emerging Trajectories
Resolution thresholds and processing latency are becoming the decisive competitive variables as defense agencies demand actionable intelligence within minutes of sensor contact rather than hours.
Small satellite constellations delivering sub-meter resolution through distributed architectures are supplanting monolithic high-value assets as the preferred procurement model. Intelligence agencies are accelerating adoption of these proliferated systems for resilience against anti-satellite threats. The shift is compressing prime contractor margins while elevating subsystem specialists with miniaturization expertise.
EU Space Programme Security Regulations now mandate encryption-hardened distribution architectures for all cross-border geospatial data sharing. Vendors must demonstrate compliance with these frameworks to access NATO procurement channels. European defense contractors are restructuring supply chains to capture sovereign ground segment contracts previously awarded to non-EU suppliers.
Intelligence consumers are unbundling after-sales service from platform procurement, contracting directly with specialized analytics firms for exploitation support. This disintermediation is eroding traditional prime contractor recurring revenue streams. The United States National Geospatial-Intelligence Agency is piloting this model most aggressively through its commercial imagery program office.
Defense Geospatial Market Segmentation
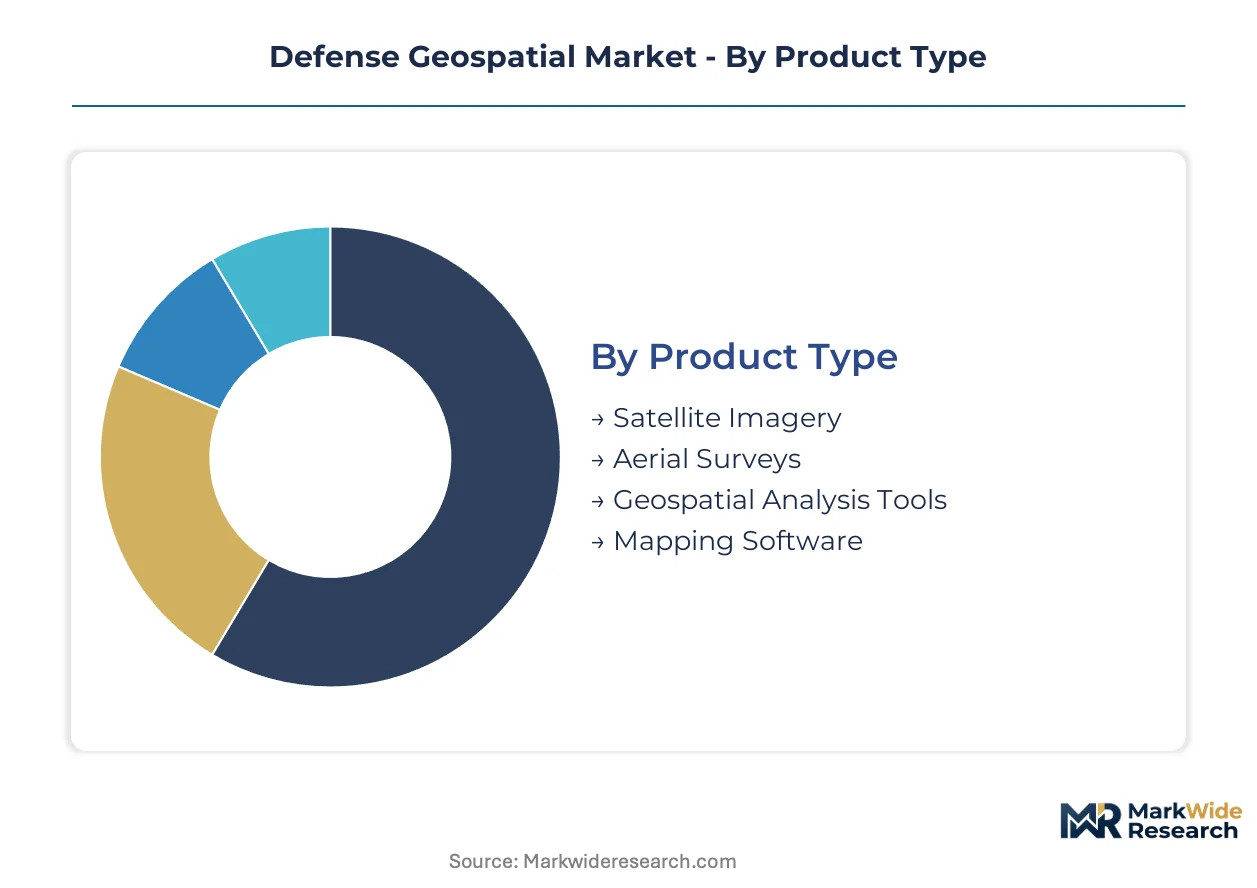
Defense geospatial procurement channels diverge sharply by product complexity and security classification. Satellite imagery flows through sovereign space agencies and classified prime contracts, while software tools increasingly reach end-users via commercial distribution licenses with encryption overlays.
Product Type:
Satellite imagery and analysis tools dominate prime contractor portfolios, with aerial surveys and mapping software filling capability gaps through subcontractor networks.
- Satellite Imagery:Panchromatic resolutions below 0.5 meters and multispectral bands from visible to short-wave infrared enable target discrimination. US National Geospatial-Intelligence Agency modernization directives are accelerating constellation replenishment investments. By volume, satellite imagery leads. By growth pace, geospatial analysis tools are climbing the fastest.
- Geospatial Analysis Tools:Machine learning algorithms for automated feature extraction compress intelligence production timelines. NATO STANAG 2592 standardization mandates are forcing interoperability upgrades across member state procurement channels.
- Aerial Surveys:Manned and unmanned platforms deliver rapid-response collection in denied orbital access zones.
- Mapping Software:Digital terrain elevation data and vector feature sets support precision navigation systems.
Sovereign capacity investments concentrate procurement for satellite imagery, while commercial licensing models are expanding access to analysis tools.
End User:
Intelligence agencies and military commands absorb the highest-value platforms, with defense contractors and civilian government organizations accessing tools through tiered security clearances.
- Intelligence Agencies:Specialized secure infrastructure requirements and compartmentalized data handling protocols define procurement specifications. US National Geospatial-Intelligence Agency commercial imagery program office is piloting direct analytics firm contracts.
- Military:Battlespace visualization and real-time situational awareness drive demand for sensor-to-shooter network integration. NATO standardization requirements are accelerating system upgrades across terrestrial and maritime operational domains.
- Defense Contractors:Platform integration subcontracts absorb growing volumes of geospatial middleware development for legacy command-and-control interfaces.
- Government Organizations:Civilian disaster response and border management applications utilize downgraded resolution products with relaxed distribution restrictions.
Military end-users command the largest contract values. Intelligence agencies are expanding most quickly as AI-enhanced exploitation capabilities proliferate.
Technology:
Remote sensing hardware commands capital-intensive procurement cycles, while data analytics and GIS software compress development timelines through commercial technology adaptation.
- Remote Sensing:Electro-optical, synthetic aperture radar, and hyperspectral payloads span satellite and aerial platforms. Persistent cloud cover in tropical theaters degrades electro-optical utility and drives SAR infrastructure investment.
- Data Analytics:Automated feature extraction and predictive terrain analysis reduce analyst workload. Clearance-qualified geospatial data scientists with machine learning expertise command premium compensation.
- GIS:Spatial database management and cartographic production tools support mission planning workflows.
- 3D Modeling:Digital elevation models and urban terrain reconstruction enable virtual mission rehearsal environments.
Remote sensing anchors platform procurement budgets. Data analytics is gaining share fastest as agencies mandate AI-enhanced exploitation.
Application:
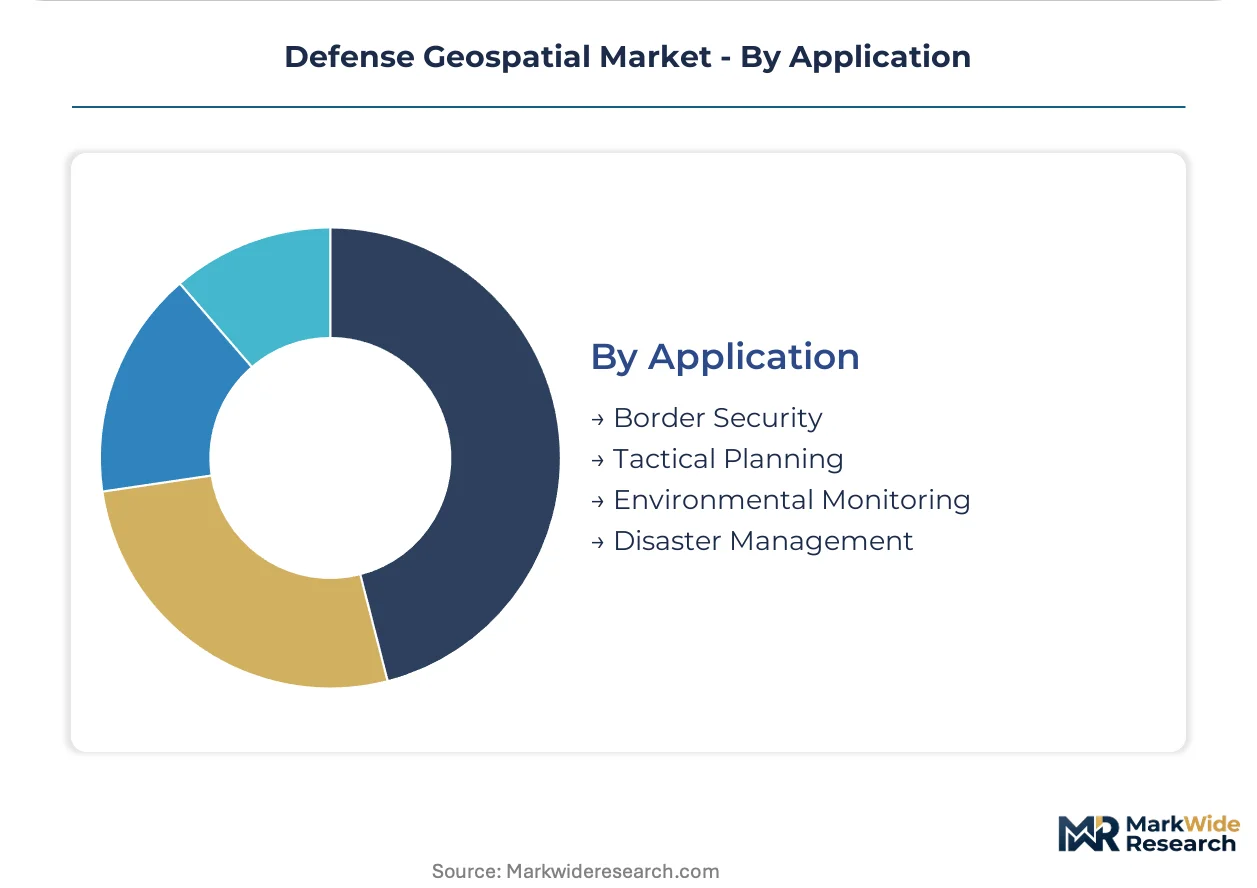
Tactical planning and border security absorb classified high-resolution products, while environmental monitoring and disaster management utilize commercial-grade distribution channels with reduced encryption requirements.
- Tactical Planning:Real-time route analysis and obstacle avoidance depend on sub-meter resolution with low latency delivery. Small satellite constellations are displacing monolithic assets for resilience against anti-satellite threats.
- Border Security:Persistent surveillance of maritime and land boundaries requires multi-sensor fusion and automated anomaly detection. EU Space Programme Security Regulations mandate encryption-hardened architectures for cross-border data sharing.
- Environmental Monitoring:Change detection for infrastructure and natural resource assessment utilizes lower classification thresholds.
- Disaster Management:Rapid damage assessment and relief coordination leverage commercial imagery with expedited licensing.
Border security contracts generate the most recurring revenue. Tactical planning shows the steepest expansion trajectory as distributed constellation architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense geospatial procurement flows predominantly from net importer positions toward sovereign capacity builders. Export-oriented satellite manufacturing clusters in France and the United States supply ground segment infrastructure to allies lacking indigenous orbital assets.
United States
The National Geospatial-Intelligence Agency directs procurement for AI-enhanced imagery analysis and space-based reconnaissance constellations. Budget allocations through classified program offices prioritize sensor-to-shooter network integration. Denver-Aurora corridor hosts concentrated prime contractor operations feeding federal geospatial infrastructure.
France
Thales Group anchors European satellite manufacturing through dual-use production lines serving military and commercial clients. EU Space Programme Security Regulations mandate encryption-hardened architectures for cross-border data sharing. Toulouse aerospace cluster sustains sovereign orbital capacity independent of transatlantic supply chains.
Germany
Bundeswehr modernization programs drive demand for NATO STANAG 2592 compliant geospatial systems. Federal Office for Information Security certification requirements shape vendor selection for classified ground segment contracts. Munich-Stuttgart industrial corridor concentrates subsystem specialists supporting prime integration.
United Kingdom
UK Space Agency coordinates sovereign satellite procurement alongside Five Eyes intelligence sharing agreements. National Security Strategic Investment Fund directs capital toward domestic geospatial analytics capabilities. Harwell Science and Innovation Campus clusters emerging space technology ventures adjacent to defense research establishments.
Israel
Israel Defense Forces operate autonomous electro-optical and synthetic aperture radar constellations for regional intelligence coverage. Ministry of Defense procurement prioritizes miniaturized sensor packages for tactical unmanned platforms. Beersheba cyber-technology corridor integrates geospatial exploitation with signals intelligence operations.
Defense Geospatial Market Vendor Landscape
Concentration sits with integrated aerospace primes possessing sovereign satellite manufacturing bases and classified security clearances. Mid-tier specialists capture subsystem contracts for miniaturized sensors and encrypted ground stations. Two strategic archetypes dominate: vertically integrated orbital platform builders and analytics-focused software vendors. Competitive positioning hardens through exclusive prime contractor relationships with national space agencies and direct licensing of machine learning exploitation algorithms.
Among transatlantic aerospace conglomerates, Thales Group, Raytheon Technologies Corporation, and Lockheed Martin Corporation exemplify the integrated platform archetype. Thales occupies a position bridging European sovereign capacity requirements with dual-use commercial satellite production. Raytheon Technologies anchors US defense geospatial integration through classified network architectures. Lockheed Martin represents high-altitude persistent infrared platform dominance feeding downstream exploitation systems. These three entities collectively shape procurement standards that smaller subsystem vendors must satisfy for market access.
| Leading Market Players |
|---|
| Airbus Group |
| Thales Group |
| Raytheon Technologies Corporation |
| Leidos Holdings Inc. |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Hexagon AB |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term classified prime contracts with sovereign space agencies lock in both supply access and price visibility for satellite imagery procurement, insulating incumbent vendors from spot-market volatility while compressing margins for subsystem specialists competing on fixed-price integration bids. NATO STANAG 2592 compliance mandates and EU Space Programme Security Regulations further harden procurement specifications, embedding certification costs into baseline pricing structures across transatlantic defense geospatial channels.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing for geospatial analysis tools, with intelligence agencies commanding premium licensing for compartmentalized secure infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates classified satellite tasking rights from commercial imagery resale and downgraded civilian applications. Cost compression in standard-tier aerial survey services is intensifying because small satellite constellations displace manned collection platforms. Defense contractors exhibit highest price sensitivity due to fixed-price subcontract exposure, while sovereign space agencies demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
Heavy-lift launch capacity concentration at Cape Canaveral, Kourou, and Baikonur Cosmodrome underwrites constellation deployment schedules for defense geospatial operators. Satellite bus manufacturing draws from specialized composite structures, radiation-hardened electronics, and precision optical components. Single-source vulnerability persists for synthetic aperture radar payload integration, where qualified vendors number below five globally. Distribution runs through classified prime contractor networks with encryption-hardened ground segment handoffs to national intelligence agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The defense geospatial sector rewards vendors controlling clearance-qualified machine learning talent pools, where scarcity of geospatial data scientists with both security credentials and automated feature extraction expertise constrains expansion timelines for all but the largest primes.
For Market Incumbents: Compound exclusive relationships with national space agencies through embedded R&D investment in AI-enhanced exploitation platforms, insulating against disintermediation by direct analytics firm contracts. Deepen backward integration into miniaturized sensor packages to capture subsystem margins eroding under proliferated constellation procurement models. Prioritize NATO STANAG 2592 certification maintenance as a barrier against emerging European subsystem specialists. For New Entrants and Emerging Players: EU Space Programme Security Regulations fast-track compliance offers market access to NATO procurement channels previously blocked to non-sovereign suppliers. White-space concentration sits with encrypted ground station architecture for cross-border data sharing, where incumbent prime contractor restructuring creates vendor substitution opportunities. Target Bundeswehr modernization programs through Munich-Stuttgart subsystem specialist clustering. Lead with compact multi-intelligence payload designs solicited by primes for technology convergence roadmaps. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors analytics-focused software vendors with direct licensing relationships to intelligence agencies. Long-term viability hinges on unbundling exploitation services from platform procurement, a structural shift eroding traditional prime recurring revenue streams. Acquisition target archetype: mid-tier firms with NATO STANAG 2592 compliance and machine learning algorithm portfolios. Monitor classification acceleration under US National Geospatial-Intelligence Agency directives as inflection indicator for commercial remote sensing market access restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Exploitation Platform Development | Automated feature extraction capabilities address National Geospatial-Intelligence Agency mandates for compressed intelligence production timelines. |
| NATO STANAG 2592 Certification Investment | Interoperability compliance unlocks replacement demand across member state legacy system upgrade cycles. |
| Small Satellite Constellation Integration | Proliferated architectures satisfy resilience requirements against anti-satellite threats while displacing monolithic asset procurement. |
| Encryption-Hardened Ground Station Buildout | EU Space Programme Security Regulations mandate hardened distribution architectures for cross-border geospatial data sharing. |
| Direct Analytics Firm Contracting | Intelligence agency pilot programs disintermediate traditional prime contractor after-sales service revenue streams. |
Methodological Framework
Cross-validation between primary interviews with defense geospatial program managers, satellite systems engineers, intelligence agency procurement officers, and geospatial data scientists anchors the qualitative findings against secondary validation through NATO standardization documentation, US National Geospatial-Intelligence Agency modernization directives, EU Space Programme Security Regulations, and classified program budget justifications. Bottom-up and top-down triangulation reconciles subsystem vendor revenue disclosures with sovereign space agency procurement allocations.
Sensitivity analysis across the projection horizon tests demand elasticity for satellite imagery versus geospatial analysis tools, with segmentation dimensions spanning product type, end-user security classification, remote sensing technology, and application criticality. CAGRs derive from modeled replacement cycles for legacy command-and-control systems and sovereign capacity investment trajectories in orbital assets. Forecast inputs include constellation replenishment schedules and AI-enhanced exploitation adoption curves mandated by defense agencies.
Decision-makers should treat outputs as directional under assumptions of sustained NATO interoperability investment and stable launch site access; material deviation in geopolitical tensions affecting heavy-lift provider availability would warrant model refresh. Practitioners should keep alternative scenarios live as classification thresholds for commercial remote sensing capabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
North America Passive Radar Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Military Jammer Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Early Warning Radar Market