
 Long Range Radar Systems Market | 2026-2036
Long Range Radar Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Long Range Radar Systems Market Analysis
Defense ministries are reorganizing procurement priorities toward dual-use surveillance and weather detection capabilities. Thales Group leverages its European manufacturing footprint to sustain long-range naval radar contracts. Lockheed Martin Corporation anchors North American demand through its dominance in ballistic missile defense radars. RTX Corporation specializes in gallium nitride transmitter technology for next-generation phased arrays.
Long range radar systems employ radio frequency energy to detect, track, and classify objects at distances exceeding 200 nautical miles, typically operating in L-band through X-band frequencies with active electronically scanned arrays enabling simultaneous multi-target tracking. These systems serve military early warning, civilian air traffic management, and autonomous vehicle perception functions. Pulsed radar architectures occupy the largest installed base due to proven performance in adverse weather conditions, while FMCW radar segments attract R&D investment for automotive and maritime collision avoidance applications. The surveillance application category leads value generation, though weather detection arrays represent the fastest-growing sub-segment as climate resilience infrastructure spending accelerates.
The FAA mandates specific performance standards for en-route and terminal area surveillance equipment, while the EU Green Deal's transport decarbonization targets indirectly shape maritime radar modernization requirements through port electrification timelines. NATO's air command and control system standards create interoperability obligations that filter down to national procurement specifications. Stakeholders must monitor gallium nitride supply chain concentration and semiconductor export control expansions when planning component sourcing strategies.
Market Dynamics
Gallium nitride transmitter technology is supplanting legacy gallium arsenide components in phased array architectures, compressing unit costs while extending detection ranges for defense and civilian applications.
Growth Catalysts
- FAA NextGen Mandate:The FAA's air traffic control modernization directive requires long-range surveillance radar upgrades across US terminal and en-route facilities, creating sustained procurement pipelines for manufacturers.
- Ballistic Missile Defense:Pentagon budget allocations for early warning systems are accelerating demand for L-band and S-band arrays capable of discriminating complex threat trajectories.
- Climate Resilience Infrastructure:Weather detection radar procurement is expanding as national meteorological services prioritize dual-use surveillance platforms for severe storm prediction.
Market Restraints
- Semiconductor Export Controls:US Bureau of Industry and Security restrictions on gallium nitride substrate exports are constraining supply availability for non-allied defense contractors.
- High Development Costs:Active electronically scanned array engineering requires specialized cleanroom fabrication facilities, limiting viable supplier pools to capital-intensive incumbents.
- Legacy System Interoperability:NATO air command standards create integration burdens for new entrants attempting to displace installed rotating antenna systems.
Strategic Opportunities
- Autonomous Maritime Navigation:FMCW radar architectures are penetrating commercial shipping collision avoidance systems as International Maritime Organization safety mandates tighten.
- Urban Air Mobility Corridors:FAA-designated advanced air mobility routes in Dallas-Fort Worth and Los Angeles require novel surveillance coverage for low-altitude drone traffic.
- Dual-Use Weather-Military Platforms:European defense ministries are consolidating meteorological and air defense procurement under single-array specifications, opening integrated system contracts.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized microwave circuit design expertise concentrates within defense contractors, constraining workforce mobility for commercial radar developers.
- Phased Array Thermal Management:Gallium nitride power density generates cooling requirements that extend qualification timelines for fielded systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Range Radar Systems Market |
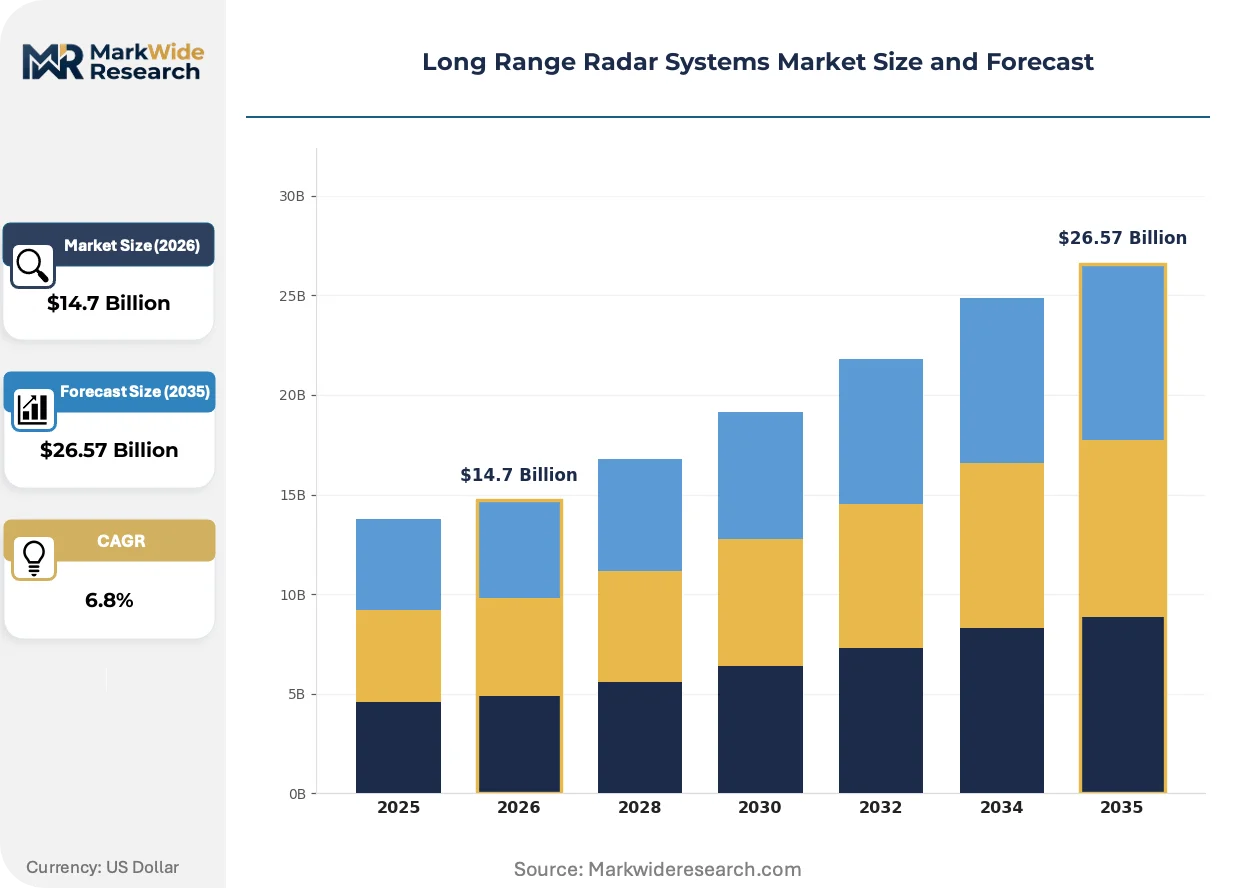
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FMCW Radar, Pulsed Radar, Continuous Wave Radar, Hybrid Radar End User: Aerospace, Defense, Automotive, Maritime Technology: Millimeter Wave, LIDAR, Infrared, Ultrasonic Application: Surveillance, Navigation, Traffic Monitoring, Weather Detection |
| Companies Covered | Thales Group, Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, HENSOLDT AG, Bosch, Continental AG, Raytheon Technologies, BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Range Radar Systems Market Emerging Trajectories
Digital beamforming architectures are redefining signal processing economics, enabling software-defined radar platforms that adapt mission profiles without hardware modification. This shift is compressing development cycles and expanding addressable applications.
Software-defined radio backends are supplanting analog signal chains in next-generation surveillance arrays. Defense procurement offices in the United States and United Kingdom are mandating open architecture standards that accelerate vendor substitution. This transition is collapsing proprietary subsystem margins while elevating firmware and algorithm licensing value.
The EU Green Deal's transport decarbonization targets are indirectly accelerating maritime radar modernization through port electrification timelines. Harbor authorities in Rotterdam and Hamburg are specifying low-power solid-state arrays to align with shore power infrastructure investments. Container shipping lines are responding by retrofitting vessel-mounted FMCW systems for emissions-compliant navigation.
Defense ministries are consolidating sustainment contracts under performance-based logistics frameworks rather than discrete spare part purchases. This restructuring transfers operational risk to prime contractors while compressing aftermarket revenue predictability. The United Kingdom's Royal Air Force and Australia's Defence Force have pioneered these arrangements for early warning radar networks.
Long Range Radar Systems Market Segmentation
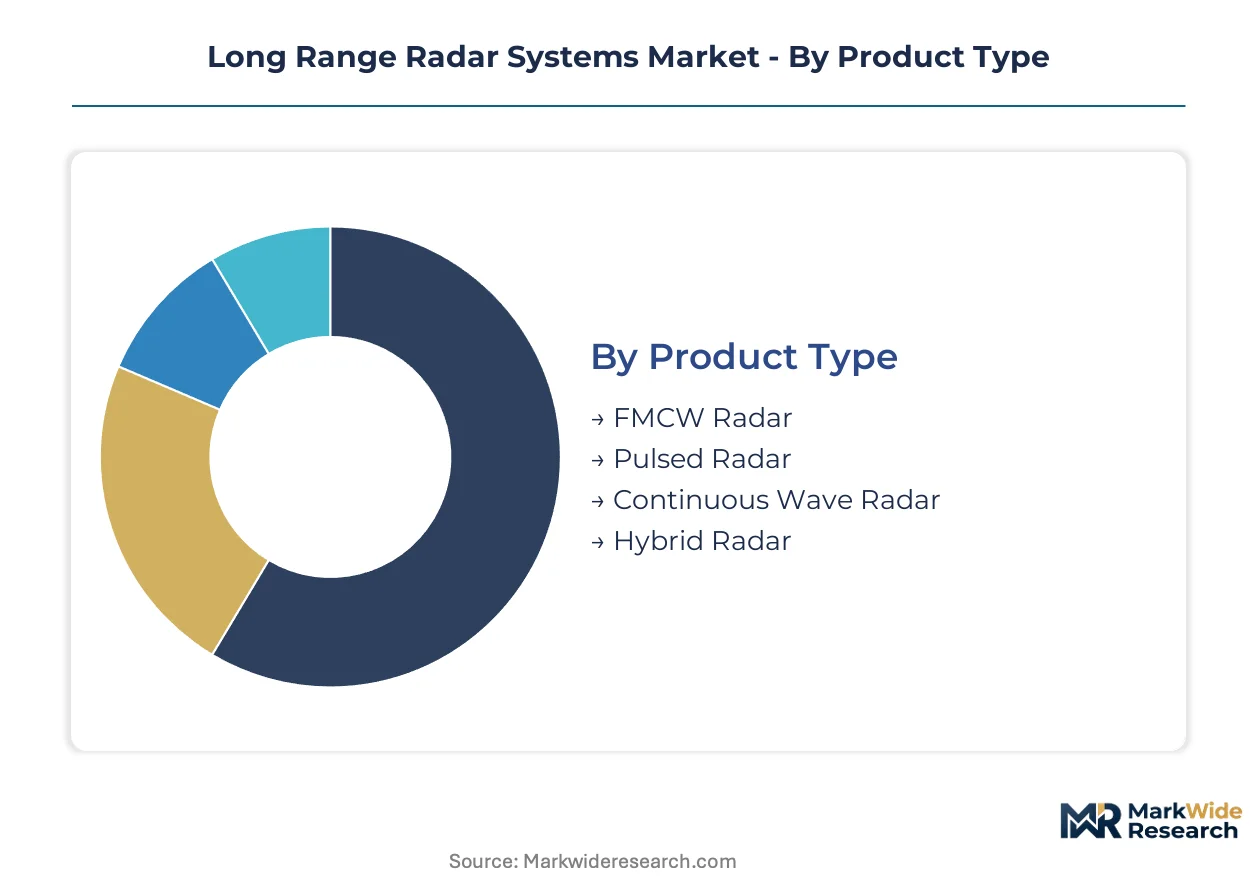
Long range radar systems fragment across four distinct taxonomies that shape procurement channels and margin structures. Product architecture determines whether contracts flow through defense primes or commercial integrators. End-user verticals dictate certification requirements and sales cycle duration. Technology choices and application focus further stratify vendor positioning and aftermarket revenue potential.
Product Type:
Defense procurement offices and commercial integrators source distinct architectures through separate contracting channels, with military contracts favoring established suppliers while automotive and maritime buyers increasingly direct-source specialized variants.
- Pulsed Radar:Transmits discrete bursts of radio frequency energy with high peak power, enabling detection beyond 200 nautical miles through atmospheric clutter. Demand concentrates in Pentagon ballistic missile defense programs and FAA en-route surveillance modernization, where proven performance in adverse weather justifies premium procurement timelines.
- FMCW Radar:Frequency-modulated continuous wave architectures compress transmitter duty cycles while maintaining constant illumination, reducing power consumption and enabling compact form factors. Automotive tier-1 suppliers and maritime collision avoidance integrators are channeling R&D budgets toward solid-state FMCW arrays for autonomous navigation systems.
- Continuous Wave Radar:Simple unmodulated carrier designs serve specialized Doppler velocity measurement applications with minimal component complexity.
- Hybrid Radar:Combines pulsed and continuous wave modes within unified apertures for multi-mission flexibility in naval surface combatants.
Pulsed radar dominates installed base across military early warning networks. FMCW radar is where expansion concentrates as commercial autonomy applications multiply.
End User:
Customer type determines whether procurement flows through national defense ministries, civil aviation authorities, or commercial fleet operators with divergent technical specifications and contract structures.
- Defense:National ministries in the United States, United Kingdom, and Australia fund long-range early warning arrays through multi-year procurement frameworks with performance-based logistics sustainment. NATO air command interoperability mandates create vendor lock-in around certified subsystem suppliers.
- Aerospace:Civil aviation authorities and airport operators purchase en-route and terminal area surveillance equipment under FAA NextGen and EU SESAR modernization mandates, with certification cycles spanning 18-36 months.
- Maritime:Container shipping lines and harbor authorities specify vessel-mounted and shore-based collision avoidance systems, with Rotterdam and Hamburg port electrification timelines accelerating solid-state array adoption.
- Automotive:Tier-1 suppliers integrate long-range perception modules for highway autopilot functions, though current generation systems rarely exceed 300-meter reliable detection.
Defense vertical commands highest unit values and longest contract durations. Aerospace is climbing the fastest as FAA NextGen and EU SESAR implementation schedules compress.
Technology:
Sensor modality selection reflects trade-offs between detection range, angular resolution, and environmental robustness, with radio frequency options maintaining cost advantages over optical alternatives at extended distances.
- Millimeter Wave:30-300 GHz operation enables compact antenna apertures with fine range resolution, penetrating precipitation that degrades optical sensors. Automotive and short-range defense applications favor 77-81 GHz automotive radar and 94 GHz military seekers where semiconductor cost curves have steepened.
- LIDAR:Laser-based ranging delivers centimeter-scale precision for urban air mobility corridor mapping and autonomous vehicle localization, though atmospheric attenuation limits effective range below 150 meters in adverse conditions.
- Infrared:Passive thermal detection complements active radar in dual-spectrum military targeting pods and search-and-track systems.
- Ultrasonic:Sub-200 kHz acoustic ranging serves specialized short-range proximity applications with minimal electromagnetic signature.
Millimeter wave claims dominant share of deployed long-range detection infrastructure. LIDAR is gaining share fastest where precision mapping commands premium pricing.
Application:
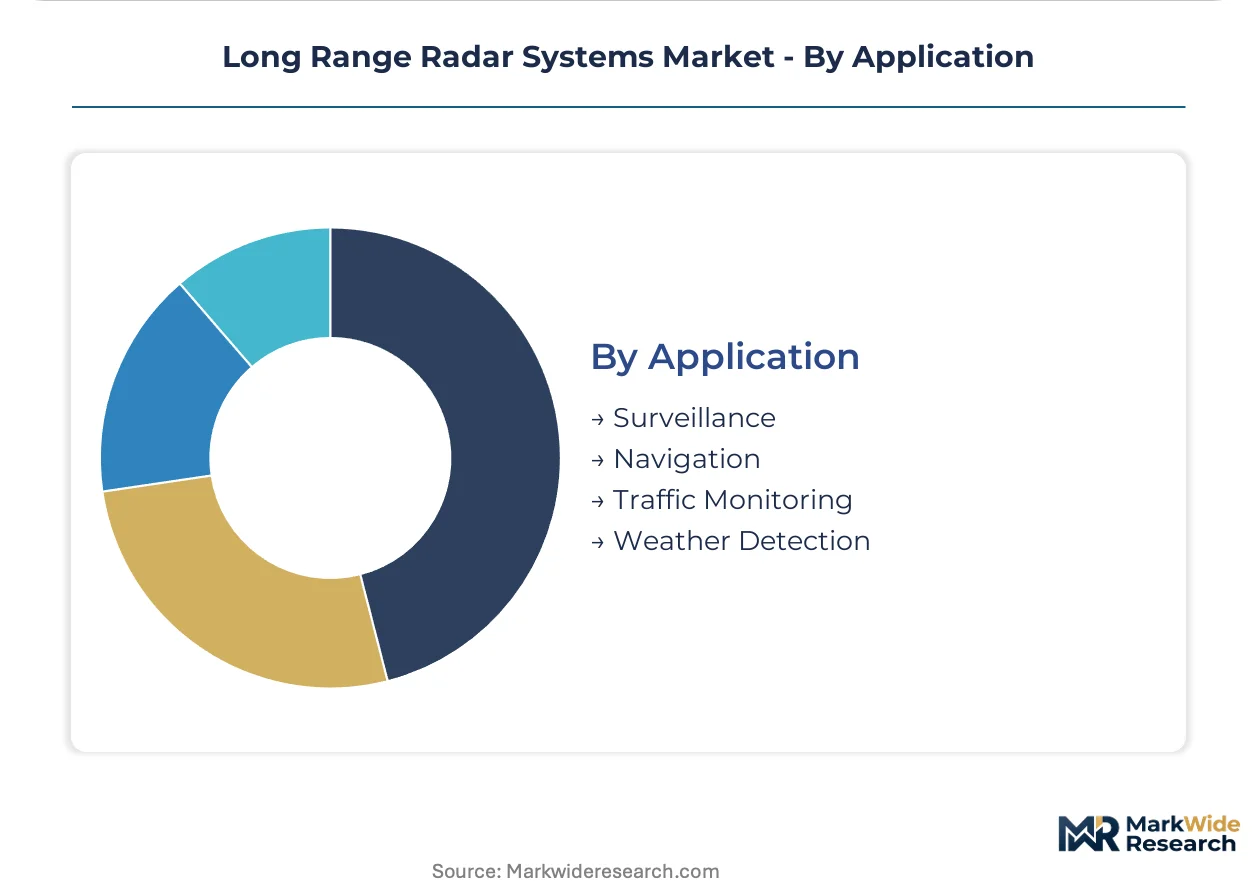
Functional purpose determines array sizing, processing architecture, and software mission profiles, with surveillance platforms requiring 360-degree coverage while navigation systems prioritize forward-sector reliability.
- Surveillance:Ground-based and airborne early warning systems demand rotating or electronically scanned arrays with simultaneous multi-target tracking across azimuth and elevation. Pentagon budget allocations for ballistic missile defense and NATO air policing sustain procurement pipelines for L-band and S-band long-range platforms.
- Weather Detection:Dual-polarization Doppler arrays serve national meteorological services with severe storm prediction and precipitation measurement capabilities. Climate resilience infrastructure spending in the United States and European Union is accelerating deployment timelines for next-generation weather radar networks.
- Navigation:Maritime collision avoidance and autonomous vehicle path planning require real-time obstacle classification with high update rates.
- Traffic Monitoring:Highway and corridor surveillance applications prioritize cost-optimized hardware with centralized processing architectures.
Surveillance application claims largest cumulative installed value. Weather detection is expanding most quickly as meteorological services consolidate procurement with defense ministries under dual-use platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' ballistic missile early warning grid spanning Alaska, California, and Greenland anchors Western hemisphere demand for phased array infrastructure. This continental-scale sensor network underwrites procurement volumes that exceed individual European national defense budgets.
United States
Pentagon allocations for L-band and S-band early warning arrays drive sustained demand through 2035. FAA NextGen mandates require surveillance radar upgrades across terminal and en-route facilities nationwide. The Alaska Radar System and Cape Cod installations represent concentrated deployment clusters for ballistic missile defense infrastructure.
Germany
HENSOLDT AG's domestic manufacturing base secures NATO air policing contracts and naval surface combatant programs. EU Green Deal port electrification timelines in Hamburg and Bremen accelerate solid-state maritime radar adoption. The country's central European geography positions it as a hub for integrated air defense command systems.
United Kingdom
The Royal Air Force's performance-based logistics frameworks for early warning radar networks transfer operational risk to prime contractors. BAE Systems plc anchors domestic supply chains for airborne and ground-based surveillance platforms. Scotland hosts key radar testing and integration facilities for NATO interoperability certification.
Japan
Ballistic missile defense cooperation with the United States drives procurement of AN/TPY-2 and successor radar platforms. METI industrial policy supports domestic gallium nitride substrate development to reduce import dependency. Kyushu-based manufacturing clusters specialize in phased array component fabrication for maritime patrol applications.
Australia
The Defence Force's Jindalee Operational Radar Network expansion exemplifies over-the-horizon surveillance investment. Performance-based sustainment contracts for northern early warning infrastructure mirror UK procurement models. Darwin and Exmouth host concentrated deployment sites for Indo-Pacific maritime domain awareness.
Long Range Radar Systems Market Vendor Landscape
Concentration sits with defense primes possessing cleanroom fabrication capabilities and NATO certification heritage. The vendor base separates into three tiers: integrated systems houses with satellite and electronic warfare portfolios; specialized radar subsystem suppliers focused on transmit-receive module production; and automotive tier-1s entering commercial FMCW segments. Dominant competitive moves include gallium nitride technology licensing agreements and performance-based logistics contract restructuring that transfers operational risk from government buyers to prime contractors.
Within the integrated systems tier, Lockheed Martin Corporation and RTX Corporation exemplify archetypes combining ballistic missile defense heritage with FAA-certified air traffic management platforms. Thales Group occupies a distinct position bridging European defense ministry requirements and civil aviation authority specifications. These three anchors demonstrate how geographic regulatory alignment—Pentagon procurement frameworks, EU Green Deal port mandates, and NATO interoperability standards—shapes competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Thales Group |
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| HENSOLDT AG |
| Bosch |
| Continental AG |
| Raytheon Technologies |
| BAE Systems plc |
| Others |
Supply Flow & Price Mechanics
FAA NextGen certification requirements gate both supplier qualification timelines and price differentiation between certified and uncertified array manufacturers. Defense procurement offices impose identical technical standards across Pentagon and NATO contracts, compressing margin variance for established primes while elevating premiums for dual-use platforms bridging military and civil aviation specifications.
Pricing Analysis
Volume-discount tiering structures separate Pentagon multi-year framework awards from discrete commercial maritime purchases. Three-tier pricing stratifies across ballistic missile defense arrays, FAA-certified air traffic management platforms, and automotive FMCW modules. Price differentiation rests on gallium nitride transmitter certification grade and performance-based logistics bundling. Cost compression in automotive tiers intensifies as Tier-1 suppliers consolidate sourcing. Maritime harbor authorities exhibit highest price sensitivity; defense ministries demonstrate lowest sensitivity due to mission-critical specifications.
Supply Chain Analysis
Inbound logistics costs from Asian gallium nitride substrate manufacturers through West Coast ports constrain just-in-time delivery for domestic cleanroom fabrication. Supply concentration centers on Japan, South Korea, and the United States for high-purity semiconductor substrates. Raw material dependencies span gallium nitride wafers, specialized ceramic packaging, and precision microwave components. Single-source vulnerability persists around qualified transmitter-receive module suppliers. Distribution runs through defense prime contractor networks for military end-users and direct OEM relationships for automotive integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as FAA urban air mobility corridor designations create specialized surveillance niches beyond traditional defense and civil aviation procurement channels.
For Market Incumbents: Shield ballistic missile defense franchise positions through captive gallium nitride substrate supply arrangements and accelerated FAA dual-certification for next-generation arrays. Emerging automotive Tier-1 entrants threaten rotating antenna replacement cycles with solid-state FMCW alternatives. Vertical integration into transmitter-receive module fabrication preserves margin structure against commoditization pressure.
For New Entrants and Emerging Players: Lead with software-defined radar backends for FAA-designated advanced air mobility routes in Dallas-Fort Worth and Los Angeles, where incumbent coverage gaps create white-space entry points. Urban air mobility corridor surveillance represents the most penetrable segment given absence of legacy rotating antenna infrastructure. Partner with regional airport authorities on pilot deployment programs to establish reference architectures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates with underperforming radar subsystem divisions lacking scale for gallium nitride transition investments. Long-term viability over the coming decade hinges on positioning within software-defined architectures and open standards compliance. Monitor FAA urban air mobility route certification timelines as inflection indicator for commercial segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Technology Licensing | Accelerates transmitter efficiency gains for Pentagon early warning arrays and FAA NextGen platforms. |
| Performance-Based Logistics Restructuring | Transfers operational risk from Royal Air Force and Australian Defence Force to prime contractors. |
| Dual-Use Weather-Military Platform Consolidation | Captures EU Green Deal climate resilience infrastructure spending through integrated array specifications. |
| Software-Defined Radar Backend Development | Enables mission profile adaptation without hardware modification for NATO interoperability requirements. |
| Urban Air Mobility Corridor Surveillance Deployment | Addresses FAA-designated route coverage gaps in Dallas-Fort Worth and Los Angeles metropolitan areas. |
Methodological Framework
A spread of perspectives from Pentagon procurement officers, FAA certification engineers, Tier-1 automotive supplier executives, and maritime harbor authority technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with defense prime contractor program managers and commercial radar integrators. Secondary validation drew from FAA NextGen implementation documentation, Pentagon budget justification materials, EU Green Deal transport decarbonization filings, and NATO air command interoperability standards. Bottom-up segment sizing triangulated against top-down defense and civil aviation expenditure aggregates.
Segmentation dimensions modeled span product architecture, end-user vertical, technology modality, and application function across the projection horizon. Pulsed versus FMCW versus hybrid radar configurations, defense versus aerospace versus maritime versus automotive demand, millimeter wave versus LIDAR versus infrared detection, and surveillance versus weather detection versus navigation use-cases structured the analytical framework. CAGRs derived from deployment pipeline analysis against historical procurement cycle patterns. Gallium nitride substrate supply availability and FAA urban air mobility route designation schedules served as industry-specific forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained Pentagon budget allocation trajectories and FAA NextGen implementation schedules would require recalibration. Forecasts reflect documented assumptions regarding semiconductor export control stability and NATO interoperability standard continuity. Gallium nitride supply chain concentration and climate resilience infrastructure spending acceleration represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
North America Passive Radar Market