
 Infrared Anti-Sniper Detection Software Market | 2026-2036
Infrared Anti-Sniper Detection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Anti-Sniper Detection Software Market Analysis
The capability gap between full-spectrum defense primes and sensor-software specialists is reorganizing competitive dynamics in infrared anti-sniper detection. Rheinmetall AG leverages its vehicle integration heritage to anchor battlefield system architectures. Rafael Advanced Defense Systems Ltd. competes through proprietary electro-optical payload expertise honed in active conflict zones. Thales Group dominates European procurement channels with end-to-end command-and-control linkages.
Infrared anti-sniper detection software processes thermal signatures and muzzle flash events to locate concealed shooters in real time, typically operating across 3-5 micron and 8-12 micron spectral bands with sub-second latency requirements. Integrated Systems command the largest contract values by bundling hardware-software stacks for military vehicle programs. Machine Learning represents the fastest-expanding technology segment as neural networks reduce false positives from environmental heat sources. Cloud-Based Software remains nascent in defense applications due to data sovereignty constraints, though hybrid architectures gain traction in law enforcement deployments.
FDA oversight applies to thermal imaging exports under dual-use regulations, while ITAR frameworks govern US-origin software transfers to allied militaries. The EU AI Act introduces conformity assessment obligations for autonomous targeting assistance, directly affecting product development cycles for European suppliers. Stakeholders must weigh software localization mandates against the cost of maintaining multiple national certification pathways.
Market Dynamics
The EU AI Act's conformity assessment mandates for autonomous targeting assistance are compressing product development timelines for European defense software suppliers. Military procurement officers now demand explainable AI architectures in sniper detection systems, forcing algorithmic transparency retrofits across existing platforms.
Growth Catalysts
- Acoustic-Optical Fusion:NATO forward operating bases are mandating multi-spectral sensor integration for perimeter defense, creating pull-through demand for software that correlates infrared signatures with acoustic shockwave data.
- ITAR-Aligned Allied Exports:The US State Department's streamlined licensing for Five Eyes partners accelerates software deployment cycles for allied vehicle programs.
- Machine Learning Inference:Neural network architectures trained on thermal clutter datasets reduce false positive rates below operational thresholds, satisfying military latency requirements for sub-second shooter localization.
Market Restraints
- Indium Antimonide Detector Costs:Cryogenic cooling requirements for mid-wave infrared focal plane arrays inflate hardware-software bundle pricing, limiting law enforcement adoption outside federal agencies.
- Data Sovereignty Mandates:Bundeswehr cloud restrictions and French defense ministry localization rules fragment software architectures, raising compliance overhead for multi-national suppliers.
- Acoustic Suppressor Proliferation:Widespread muzzle device adoption reduces muzzle flash visibility, degrading single-spectral infrared detection efficacy in asymmetric conflict zones.
Strategic Opportunities
- Urban Law Enforcement:German state police forces and US metropolitan SWAT units represent underpenetrated demand for vehicle-mounted detection systems with reduced military specification overhead.
- Hybrid Cloud Architectures:Edge-computing deployments with classified backend synchronization satisfy operational security requirements while enabling fleet-wide model updates.
- Long-Wave Infrared Convergence:Uncooled microbolometer integration with machine learning pipelines eliminates cryogenic dependencies, opening portable and dismounted soldier applications.
Industry Challenges
- Electro-Optical Systems Integration:Legacy vehicle battle management systems lack standardized data buses for real-time thermal video ingestion, requiring costly middleware development.
- EU AI Act Certification Timelines:Conformity assessment procedures for high-risk AI systems extend product validation cycles by 18-24 months, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Anti-Sniper Detection Software Market |
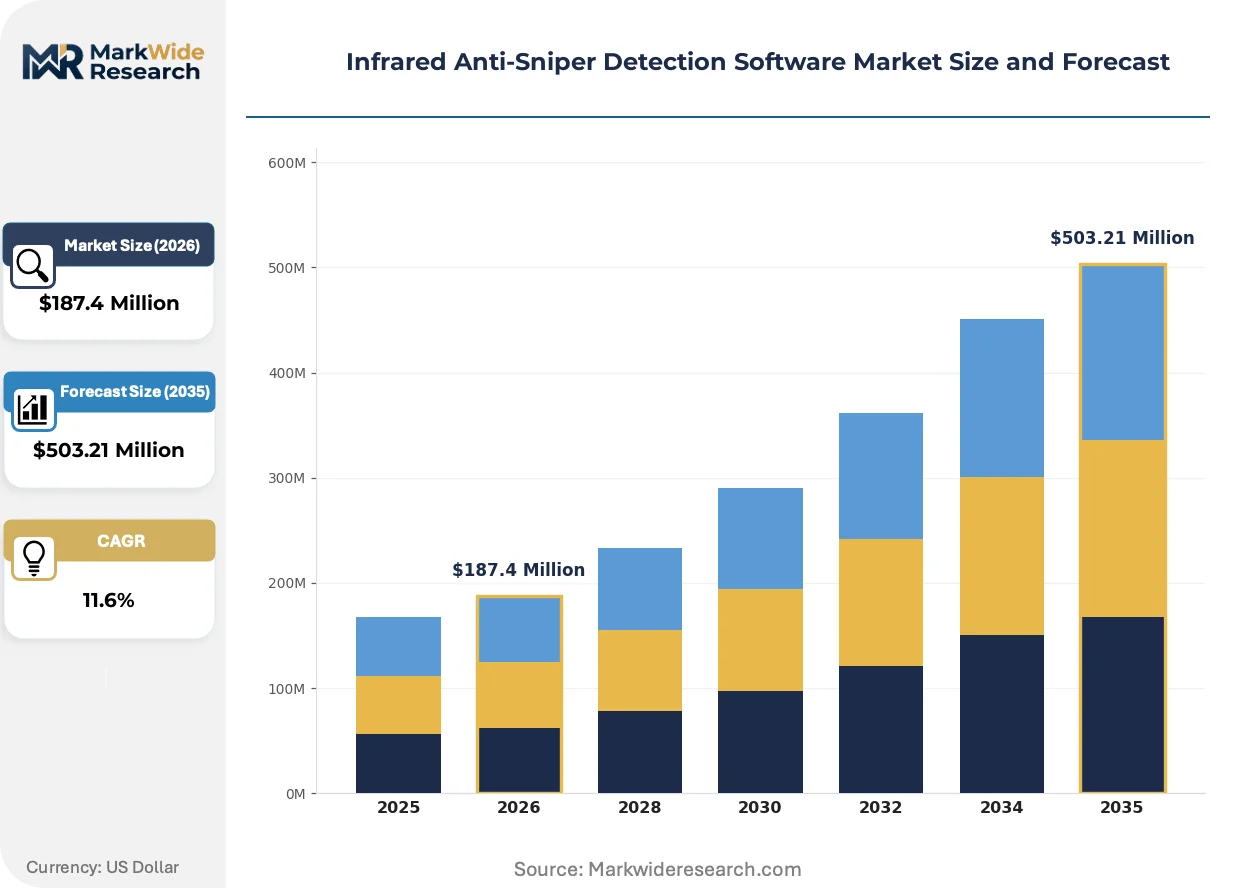
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Solutions, Integrated Systems, Mobile Applications, Cloud-Based Software Technology: Image Processing, Signal Analysis, Machine Learning, Real-Time Tracking Deployment: On-Premises, Cloud Deployment, Hybrid Solutions, Edge Computing End User: Military Organizations, Law Enforcement, Private Security, Government Agencies |
| Companies Covered | Thales Group, Rheinmetall AG, Textron Systems, QinetiQ North America, Safran Electronics & Defense, CILAS, Rafael Advanced Defense Systems Ltd., Microflown AVISA, Databuoy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Anti-Sniper Detection Software Market Emerging Trajectories
Algorithmic processing at the sensor edge is displacing centralized server architectures across military detection programs. Thermal signature analysis now occurs within weapon station computers, reducing bandwidth requirements and latency for vehicle-mounted sniper countermeasures.
Uncooled microbolometer arrays with on-chip neural accelerators are miniaturizing infrared detection payloads for dismounted soldier applications. Israeli Defense Forces and German mechanized infantry units are field-testing helmet-integrated thermal warning systems. This miniaturization is compressing the addressable hardware-software bundle, forcing suppliers to extract value through algorithm licensing rather than integrated system sales.
The EU AI Act's high-risk AI system classification applies conformity assessment obligations to autonomous targeting assistance modules. European defense ministries now require algorithmic audit trails and human-in-the-loop verification protocols. French and German vehicle programs are most affected, with Thales and Rheinmetall restructuring development workflows to document training data provenance and decision boundary specifications.
Defense procurement officers are unbundling software licenses from hardware platforms, treating detection algorithms as separate line items in vehicle upgrade contracts. This disaggregation is replacing traditional sole-source integrated system awards with competitive software-only competitions. The United States Army's Stryker fleet modernization and Israeli Merkava active protection programs exhibit this pattern most prominently.
Infrared Anti-Sniper Detection Software Market Segmentation
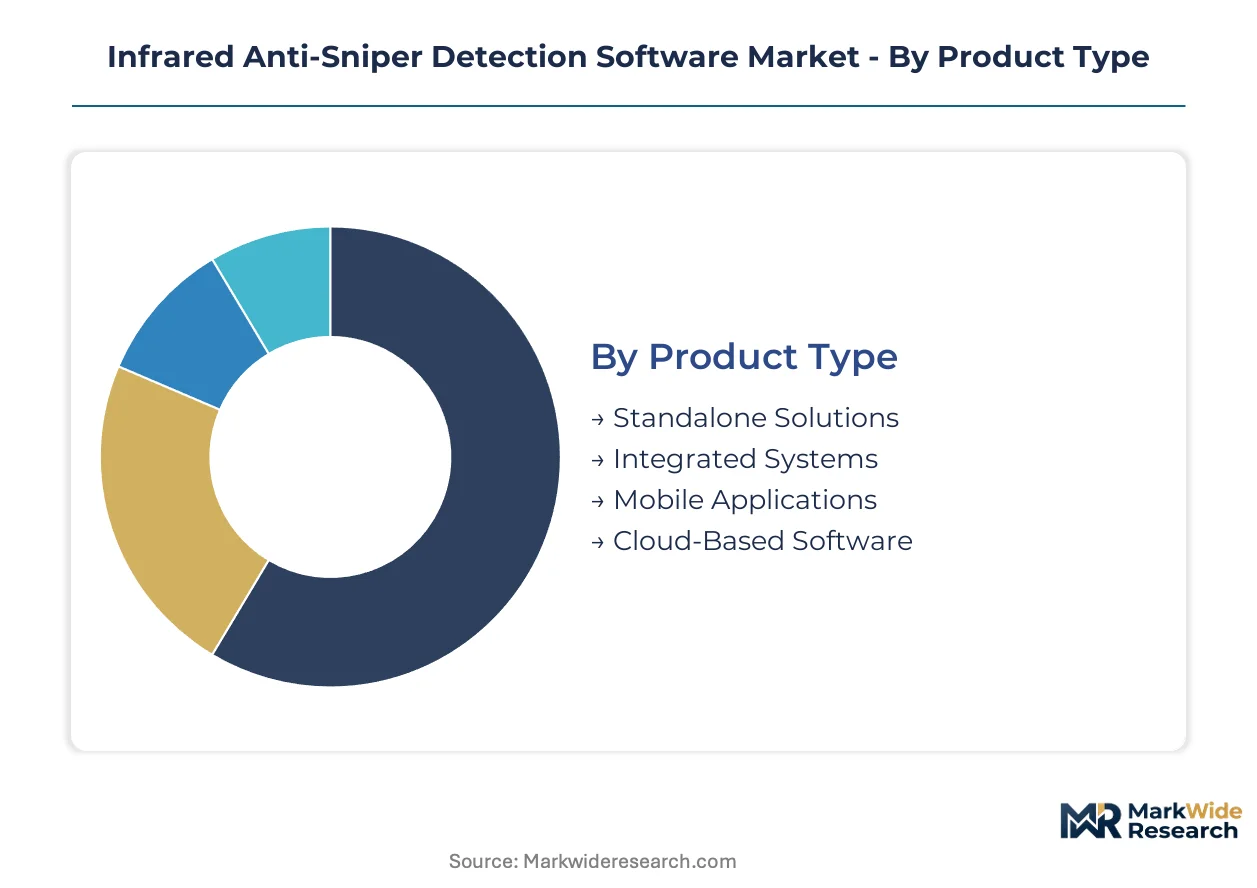
Segmentation in infrared anti-sniper detection software reveals how procurement patterns split between hardened military specifications and adaptable commercial architectures. Regulatory frameworks from the EU AI Act to ITAR licensing create divergent compliance burdens across product categories, reshaping supplier specialization.
Product Type:
EU AI Act conformity assessments and ITAR export controls impose divergent certification costs across hardware-software bundles versus standalone code distribution.
- Integrated Systems:Bundled sensor-processor-software stacks dominate NATO vehicle programs with sub-second latency guarantees. Bundeswehr Stryker modernization contracts and Israeli Merkava active protection upgrades anchor procurement volumes through sole-source awards.
- Standalone Solutions:Modular software licenses deploy atop existing thermal cameras and battle management systems. US metropolitan SWAT units and German state police forces favor this architecture for reduced military specification overhead and faster procurement cycles.
- Mobile Applications:Tablet-based shooter localization for dismounted infantry and law enforcement patrol units.
- Cloud-Based Software:Federated learning architectures for fleet-wide model updates; constrained by French defense ministry localization mandates and Bundeswehr cloud sovereignty rules.
Established volume favors Integrated Systems; emerging adoption favors Standalone Solutions.
Technology:
Processing architectures differentiate by computational cost tier and false-positive tolerance thresholds demanded by end-use mission profiles.
- Machine Learning:Neural networks trained on thermal clutter datasets reduce false positive rates below operational thresholds. The US Army's Stryker fleet modernization and IDF field trials drive inference engine procurement for vehicle-mounted systems.
- Real-Time Tracking:Kalman-filter-based trajectory prediction for moving shooter scenarios in urban combat environments.
- Image Processing:Classical computer vision pipelines for spectral signature extraction in 3-5 micron and 8-12 micron bands.
- Signal Analysis:Acoustic shockwave correlation algorithms for muzzle blast triangulation when thermal signatures degrade.
Defense procurement concentrates spend on Machine Learning; law enforcement gravitates toward Image Processing for interpretability requirements.
Deployment:
Data residency regulations and operational security protocols fragment architecture choices across allied defense ministries.
- Edge Computing:On-sensor neural accelerators process thermal video within weapon station computers, eliminating bandwidth dependencies. IDF helmet-integrated warning systems and German mechanized infantry trials miniaturize this architecture for dismounted applications.
- Hybrid Solutions:Classified backend synchronization enables fleet-wide model updates while preserving operational security at the tactical edge.
- On-Premises:Air-gapped installations for command-and-control facilities with strict data sovereignty requirements.
- Cloud Deployment:Limited to law enforcement training environments; blocked by military data classification rules.
Military procurement locks in Edge Computing; hybrid architectures gain traction in federal law enforcement modernization programs.
End User:
Budget scale and operational tempo create distinct specification tiers across government customer segments.
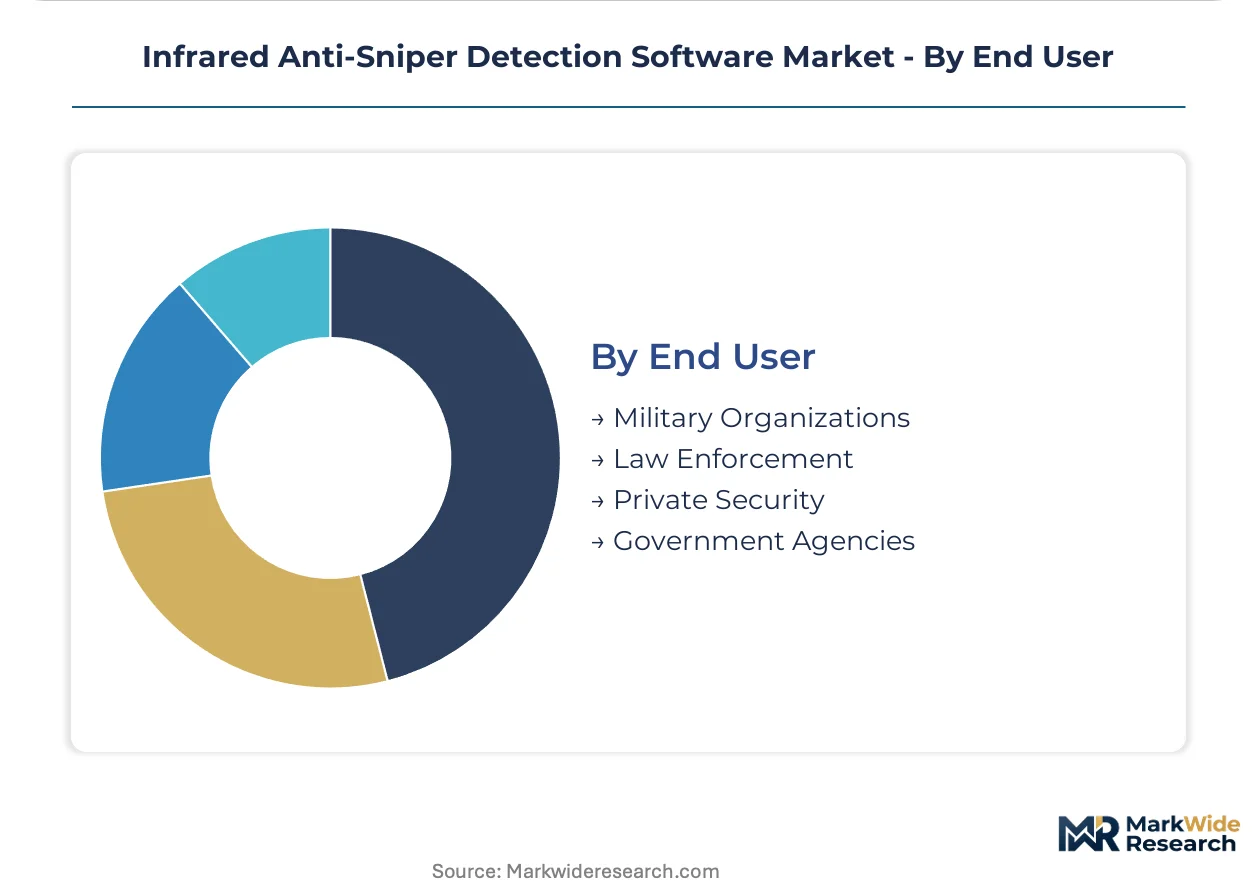
- Military Organizations:Full-spectrum requirements spanning vehicle integration, dismounted soldier systems, and forward operating base perimeter defense. NATO procurement channels and US Five Eyes export licensing dominate contract flow.
- Law Enforcement:Reduced specification overhead enables faster deployment for US metropolitan SWAT and German state police vehicle programs.
- Government Agencies:Border protection and critical infrastructure security applications with intermediate threat response timelines.
- Private Security:Executive protection and high-value facility defense with commercial-grade thermal sensor compatibility.
Contract value concentrates with Military Organizations; procurement velocity favors Law Enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply by geography. The United States prioritizes vehicle-mounted systems for mechanized brigades, while Israel emphasizes dismounted soldier protection, and Germany navigates EU AI Act compliance for algorithmic transparency mandates.
United States
The US Army's Stryker fleet modernization and Marine Corps vehicle programs drive integrated system demand. ITAR licensing frameworks govern software exports to Five Eyes partners, creating compliance overhead for cross-border deployments. Textron Systems and QinetiQ North America anchor development activity in Massachusetts and Virginia defense corridors.
Germany
Bundeswehr mechanized infantry units fund sniper countermeasure integration into Leopard and Puma vehicle programs. The EU AI Act imposes 18-24 month conformity assessment timelines for autonomous targeting assistance modules. Rheinmetall AG concentrates engineering resources in Düsseldorf and Unterlüß for NATO-compatible system architectures.
Israel
Israeli Defense Forces field-test helmet-integrated thermal warning systems for dismounted urban combat scenarios. National security doctrine prioritizes rapid shooter localization in asymmetric conflict zones. Rafael Advanced Defense Systems Ltd. maintains development headquarters in Haifa with active combat validation protocols.
France
French defense ministry localization rules fragment software architectures for multi-national suppliers. Thales Group leverages end-to-end command-and-control linkages to dominate European procurement channels. The EU AI Act's high-risk AI classification applies directly to autonomous targeting assistance under development in Paris and Bordeaux facilities.
United Kingdom
UK Ministry of Defence procurement aligns with NATO acoustic-optical fusion mandates for forward operating base protection. QinetiQ North America and Safran Electronics & Defense compete for vehicle program integration contracts. British Army trials emphasize explainable AI architectures to satisfy algorithmic transparency requirements.
Infrared Anti-Sniper Detection Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in infrared anti-sniper detection software. Full-spectrum defense primes control vehicle program awards through sole-source relationships, while sensor-software specialists capture modular retrofit opportunities. Three archetypes dominate: vehicle integration heritage players, electro-optical payload specialists, and acoustic-optical fusion innovators. Competitive moves concentrate on algorithm licensing unbundled from hardware platforms and hybrid cloud architectures that satisfy data sovereignty constraints.
Within the integrated systems tier, Rheinmetall AG and Thales Group exemplify vehicle integration heritage players leveraging NATO procurement channels. Rafael Advanced Defense Systems Ltd. occupies a distinct position as an electro-optical payload specialist with combat-validated thermal detection architectures. These three entities represent contrasting geographic and technical positioning strategies across US, European, and Israeli defense procurement ecosystems.
| Leading Market Players |
|---|
| Thales Group |
| Rheinmetall AG |
| Textron Systems |
| QinetiQ North America |
| Safran Electronics & Defense |
| CILAS |
| Rafael Advanced Defense Systems Ltd. |
| Microflown AVISA |
| Databuoy Corporation |
| Others |
Supply Flow & Price Mechanics
Uncooled microbolometer substitution for cryogenically-cooled indium antimonide detectors is redrawing supply geography toward East Asian sensor foundries while collapsing pricing premiums previously commanded by military-grade thermal hardware. This substitution cascade compresses integrated system margins and forces algorithm licensing to carry revenue load.
Pricing Analysis
After-sales algorithm updates and fleet-wide model retraining contracts now generate lifetime value exceeding initial hardware-software bundle sales. Three-tier pricing structure across military-specification, federal law enforcement, and state-level police tiers reflects ITAR compliance overhead and latency-performance differentiation. Cost compression in mid-wave infrared hardware stems from uncooled sensor proliferation. State police procurement units exhibit highest price sensitivity due to constrained capital budgets; NATO vehicle programs demonstrate lowest sensitivity given operational-critical specifications.
Supply Chain Analysis
Strategic stockpiling of indium antimonide focal plane arrays persists among US and Israeli defense contractors despite uncooled microbolometer advances, reflecting combat-validated performance requirements. Manufacturing concentrates in the United States, Israel, and Germany, with sensor fabrication anchored in specialized foundries. Supply chains draw from rare earth processing facilities, semiconductor-grade germanium suppliers, and neural accelerator chip vendors. Single-source vulnerability runs through cryogenic cooler subassemblies. Distribution runs through sole-source vehicle program awards and competitive software-only retrofit competitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification constitutes a regulatory inflection compressing development timelines and forcing algorithmic transparency investments that favor capitalized incumbents.
For Market Incumbents: Secure ITAR-aligned certification pathways for Five Eyes export licensing to maintain allied vehicle program access against emerging sensor-software specialists. Deepen backward integration into uncooled microbolometer supply through captive foundry relationships or long-term offtake agreements with Taiwanese and Chinese sensor manufacturers. For New Entrants and Emerging Players: Anchor in German state police and US metropolitan SWAT vehicle retrofit markets where procurement velocity exceeds military specification cycles and algorithm-only licensing models bypass hardware integration barriers. Target hybrid cloud architectures for federal law enforcement fleets as a beachhead segment with data sovereignty requirements less restrictive than Bundeswehr deployments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed acoustic sensor specialists possessing NATO reference deployments but lacking electro-optical fusion capabilities. Long-term viability hinges on convergence with machine learning inference engines. Watch IDF helmet-integrated warning system field trial outcomes as signal for dismounted soldier market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Unbundling | Separates software revenue from hardware platforms, enabling competitive retrofit competitions against sole-source incumbents. |
| EU AI Act Conformity Investment | Thales and Rheinmetall restructuring development workflows to document training data provenance for high-risk system classification. |
| Hybrid Cloud Architecture Deployment | Edge-computing with classified backend synchronization satisfies French defense ministry localization mandates while enabling fleet updates. |
| Uncooled Microbolometer Integration | Eliminates cryogenic dependencies, opening portable applications for Israeli and German mechanized infantry trials. |
| Acoustic-Optical Fusion Development | NATO forward operating base mandates create pull-through demand correlating infrared signatures with acoustic shockwave data. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, vehicle platform engineers, thermal sensor R&D directors, and software integration specialists. Secondary validation drew from ITAR licensing disclosures, EU AI Act conformity assessment documentation, NATO procurement databases, and SEC filings of publicly traded defense primes. Bottom-up segment sizing triangulated against top-down military expenditure allocation models.
Across the analysis window, forecasts employed a cohort-based adoption model segmented by deployment architecture, end-user organization type, spectral band configuration, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical vehicle program upgrade cycles and law enforcement modernization appropriations. Neural network inference engine procurement volumes and acoustic-optical fusion system fielding rates served as industry-specific demand proxies.
Decision-makers should treat outputs as directional under assumptions of sustained NATO defense spending and stable ITAR licensing frameworks; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement intensity or acoustic suppressor proliferation crosses operational efficacy thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Night Vision Devices Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Global Airport Surveillance Radar Market