
 Electronically Scanned Array Radar Market | 2026-2036
Electronically Scanned Array Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Electronically Scanned Array Radar Market Analysis
The capital-intensity divergence between prime contractors and subsystem specialists is unwinding as sovereign governments demand domestic production quotas. Raytheon Technologies Corporation leverages its vertically integrated gallium nitride foundry capacity to capture fighter radar retrofit programs. Lockheed Martin Corporation anchors the F-35 Lightning II's AN/APG-81 program, sustaining long-term revenue visibility through sole-source contracts. Saab AB competes in the mid-tier segment with its Erieye airborne early warning platform, specializing in Erieye ER upgrades for non-NATO export customers.
Electronically scanned array radar employs thousands of individual transmit-receive modules arranged in a flat aperture, steering radio frequency beams through phase interference rather than mechanical rotation. Active electronically scanned array variants dominate procurement budgets because each element contains independent amplification, enabling simultaneous multi-target tracking and electronic warfare functions. Passive electronically scanned array technology occupies cost-sensitive maritime patrol niches where reliability outweighs performance. Digital beamforming architectures represent the fastest-growing segment as software-defined waveforms displace analog hardware in next-generation spaceborne surveillance constellations.
The United States Department of Defense mandates MIL-STD-461 electromagnetic compatibility and MIL-STD-810 environmental ruggedness for all deployed radar systems, forcing non-U.S. suppliers to establish American engineering subsidiaries. The European Union's F-Gas Regulation restricts sulfur hexafluoride use in ground-based radar cooling systems, accelerating transition to liquid-cooled solid-state designs. Stakeholders must monitor how export control revisions under the U.S. International Traffic in Arms Regulations reshape technology transfer pathways for gallium nitride semiconductor processes.
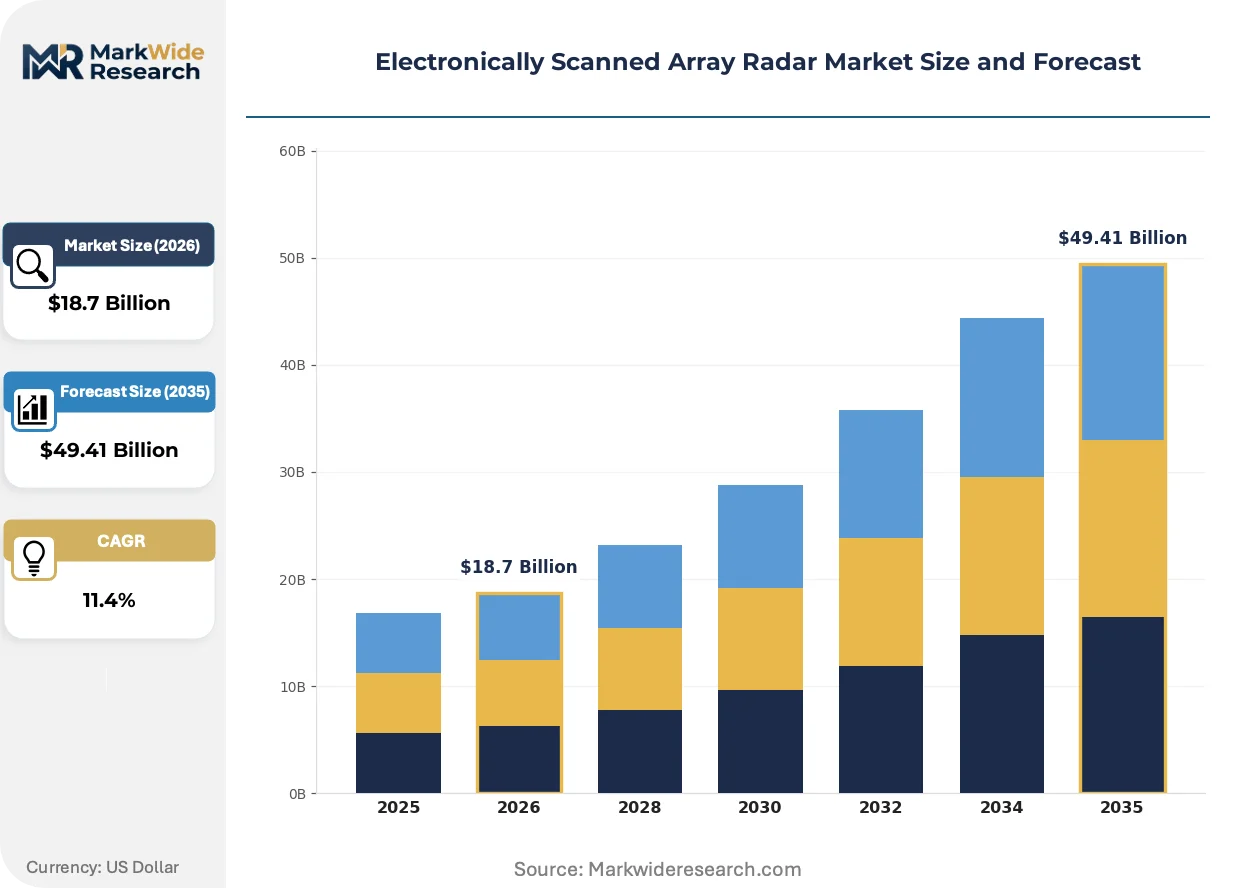
Market Dynamics
The transition from mechanically scanned arrays to solid-state active electronically scanned arrays is restructuring defense procurement specifications across NATO member states and reshaping foundry capacity allocation for gallium nitride semiconductors.
Growth Catalysts
- F-Gas Regulation:The European Union's F-Gas Regulation restricts sulfur hexafluoride in ground-based radar cooling systems, forcing accelerated transition to liquid-cooled solid-state designs and expanding retrofit demand for existing installations.
- Maritime patrol modernization:Naval defense procurement across NATO member states is accelerating AESA radar adoption for frigate and destroyer platforms, with specifications mandating simultaneous multi-target tracking capabilities.
- Gallium nitride foundry expansion:Sovereign governments are demanding domestic production quotas for wide-bandgap semiconductor processes, unlocking captive supply chains for transmit-receive module fabrication.
Market Restraints
- Gallium nitride substrate concentration:Foundry capacity for high-purity gallium nitride wafers concentrates among a limited supplier base, creating input bottleneck risk for transmit-receive module production.
- ITAR compliance friction:The U.S. International Traffic in Arms Regulations imposes technology transfer restrictions on semiconductor process exports, forcing non-U.S. suppliers to establish American engineering subsidiaries.
- Passive array cost competition:Passive electronically scanned array technology retains cost advantage in maritime patrol niches where reliability requirements outweigh performance specifications, limiting AESA penetration in budget-constrained segments.
Strategic Opportunities
- Spaceborne surveillance constellations:Digital beamforming architectures represent emerging demand from low-earth orbit satellite operators requiring software-defined waveform flexibility for persistent earth observation.
- Non-NATO export markets:Mid-tier airborne early warning platforms with Erieye ER upgrade paths are capturing defense modernization budgets in regions outside traditional NATO procurement frameworks.
- Fighter radar retrofit cycles:Fourth-generation fighter fleets in service across multiple air forces require AESA upgrades to maintain electronic warfare parity, creating aftermarket module demand independent of new platform procurement.
Industry Challenges
- Transmit-receive module calibration expertise:The precision alignment of thousands of individual array elements demands specialized RF engineering talent that defense contractors struggle to recruit and retain.
- MIL-STD-461 certification timelines:Electromagnetic compatibility testing for military deployments extends development cycles, compressing competitive windows for platform integration bids.
- Legacy platform integration complexity:Mechanical and thermal interfaces on existing airframes and vessels constrain AESA aperture sizing, forcing performance trade-offs in retrofit configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronically Scanned Array Radar Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Phased Array, Active Electronically Scanned Array, Passive Electronically Scanned Array, Digital Beamforming End User: Defense, Aviation, Maritime, Automotive Installation: Ground-Based, Airborne, Spaceborne, Shipborne Application: Surveillance, Targeting, Navigation, Tracking |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Saab AB, Thales Group, Leonardo S.p.A., Israel Aerospace Industries, Aselsan A.S., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronically Scanned Array Radar Market Emerging Trajectories
Digital beamforming architectures are supplanting analog hardware across next-generation radar platforms, while regulatory mandates and procurement model evolution are restructuring competitive positioning among subsystem suppliers.
Gallium nitride monolithic microwave integrated circuits are supplanting gallium arsenide amplification stages in transmit-receive modules. Fighter radar retrofit programs and naval surface combatant modernization drives are adopting the technology at accelerated procurement cycles. This material transition is supplanting legacy thermal management requirements while compressing module form factors for constrained aperture installations.
The European Union's F-Gas Regulation is phasing down sulfur hexafluoride use in high-voltage switchgear and cooling systems. Ground-based radar installations must transition to liquid-cooled solid-state designs or face operational restrictions. Maritime surveillance platforms in European waters are most affected, with operators accelerating solid-state array procurement to preempt compliance deadlines.
Defense procurement offices are consolidating subsystem sourcing under platform prime contractors rather than awarding separate radar contracts. The channel shift concentrates specification influence with airframe and vessel integrators, displacing direct radar manufacturer relationships with end-users. This pattern is most visible in United States Department of Defense fighter and maritime programs where sole-source contracting dominates platform lifecycle sustainment.
Electronically Scanned Array Radar Market Segmentation
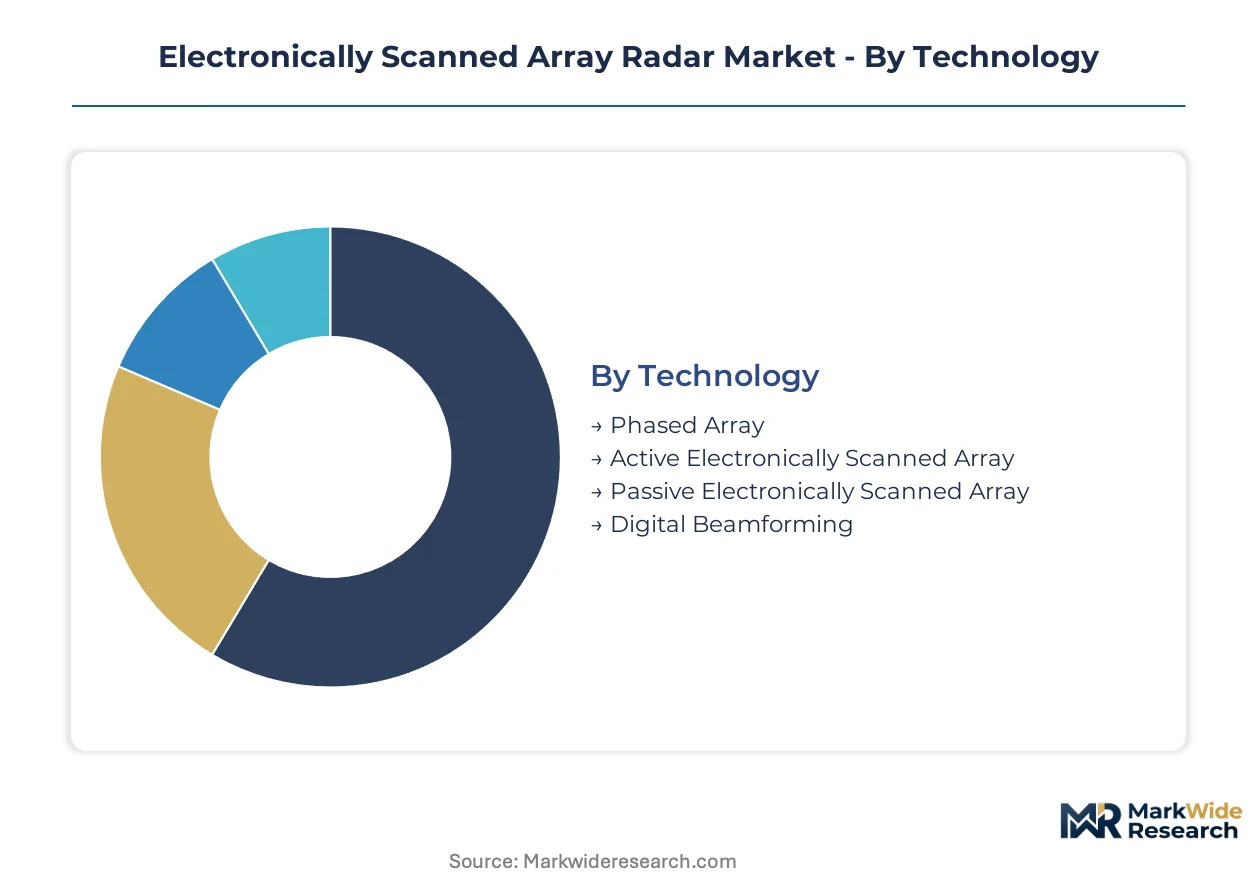
Segmentation in electronically scanned array radar markets reveals how procurement specifications diverge across defense, commercial aviation, and emerging automotive domains. Technology choices determine thermal management requirements and foundry capacity allocation, while installation platforms constrain aperture sizing and beamforming architectures.
Technology:
Active electronically scanned array technology faces substitution pressure from digital beamforming architectures in next-generation spaceborne surveillance constellations, while passive arrays retain cost advantage in maritime patrol niches where reliability outweighs performance.
- Active Electronically Scanned Array:Each transmit-receive module contains independent gallium nitride amplification, enabling simultaneous multi-target tracking and electronic warfare functions. Demand concentrates in United States Department of Defense fighter modernization programs where MIL-STD-461 electromagnetic compatibility mandates drive specification rigor.
- Digital Beamforming:Software-defined waveforms displace analog hardware through field-programmable gate array processing, allowing post-deployment waveform updates. Low-earth orbit satellite operators in the United States and European Union are adopting this architecture for persistent earth observation flexibility.
- Phased Array:Legacy mechanically steered architectures with centralized radio frequency distribution.
- Passive Electronically Scanned Array:Centralized amplification feeds phase-shifting elements, trading performance for thermal simplicity in cost-constrained maritime patrol applications.
Active electronically scanned array anchors the volume base while digital beamforming gains share at the steepest rate.
End User:
Defense procurement dominates capital allocation, yet aviation and maritime segments exhibit divergent cost sensitivity that reshapes technology selection across customer tiers.
- Defense:Sovereign governments mandate domestic gallium nitride foundry quotas and sole-source platform sustainment contracts. The United States Department of Defense sustains multi-billion-dollar modernization programs for fighter and maritime platforms through AN/APG-81 and naval surface combatant radar retrofits.
- Maritime:NATO frigate and destroyer specifications require simultaneous multi-target tracking, accelerating solid-state array adoption. European Union F-Gas Regulation compliance deadlines force transition from sulfur hexafluoride cooling systems to liquid-cooled designs.
- Aviation:Commercial airframe integrators specify weather radar and terrain mapping systems with stricter weight and power constraints than military counterparts.
- Automotive:Emerging demand from autonomous vehicle developers for high-resolution 4D imaging radar in advanced driver-assistance systems.
Defense procurement commands the revenue concentration while maritime retrofits expand most quickly under regulatory compulsion.
Installation:
Platform physics determine aperture sizing limits, with airborne and spaceborne installations imposing the most severe form-factor constraints on transmit-receive module density.
- Airborne:Fighter airframe thermal and mechanical interfaces constrain active electronically scanned array aperture dimensions, forcing performance trade-offs in fourth-generation fleet retrofits. The United States, United Kingdom, and Japan dominate platform integration demand.
- Shipborne:Naval surface combatants accommodate larger arrays with integrated mast structures, enabling full-specification multi-function radar performance. NATO member states drive procurement acceleration for frigate and destroyer modernization.
- Ground-Based:Fixed installations support ballistic missile defense and long-range air surveillance with fewer weight constraints.
- Spaceborne:Low-earth orbit constellations demand radiation-hardened digital beamforming with minimal power budgets and software reconfigurability.
Shipborne installations anchor the volume base while spaceborne configurations climb the fastest on surveillance constellation deployment timelines.
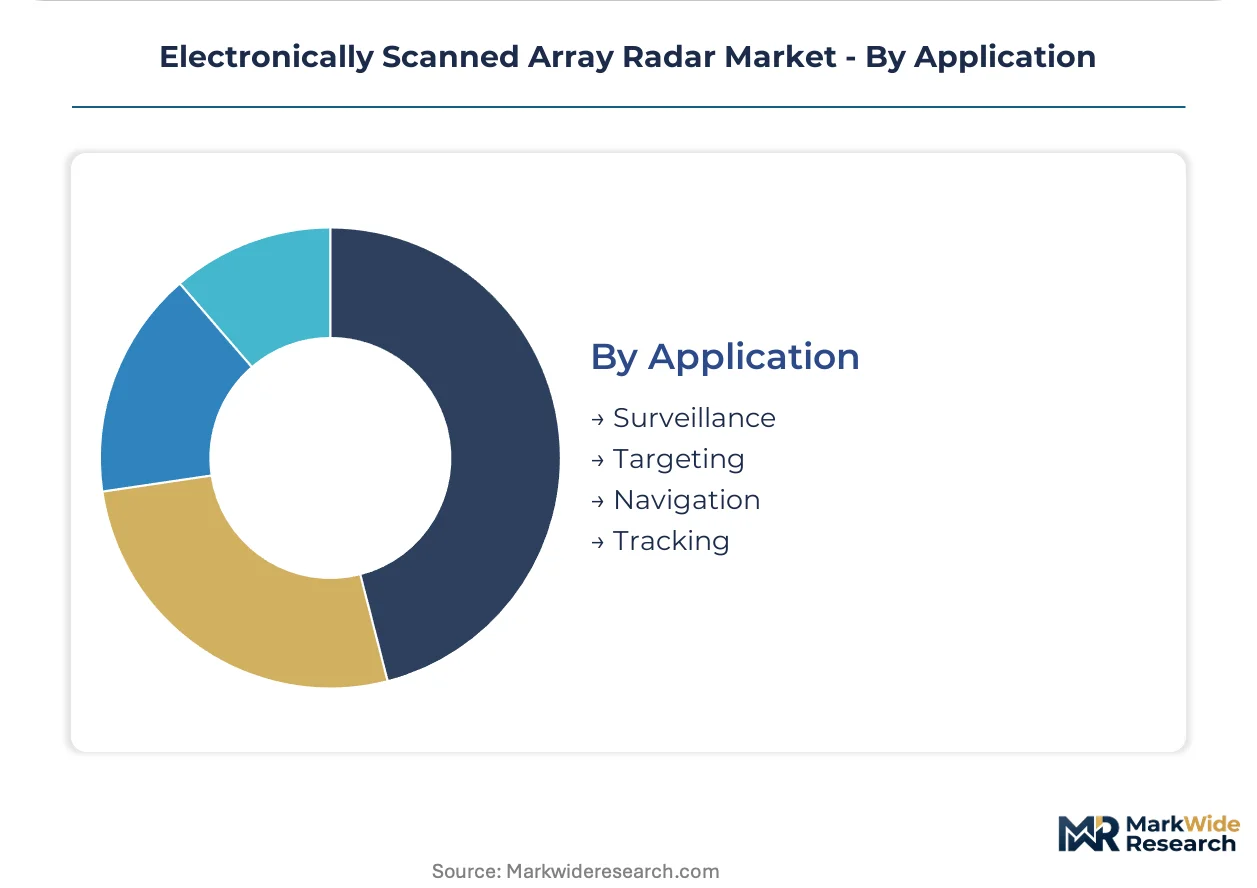
Application:
Surveillance and targeting applications diverge in waveform complexity requirements, with targeting demanding higher update rates and precision track files.
- Surveillance:Wide-area volume search requires sustained beam dwell times and rotating or electronically scanned coverage patterns. Maritime domain awareness missions in European and Indo-Pacific waters prioritize this application.
- Targeting:Fire control quality track generation demands rapid revisit rates and high-range-resolution waveforms. Precision engagement requirements in the United States and allied fighter programs concentrate demand here.
- Tracking:Multi-target correlation and identification friend-or-foe integration for dense airspace environments.
- Navigation:Terrain following and all-weather approach guidance for military and select commercial aviation platforms.
Surveillance anchors the volume base while targeting gains share at the steepest rate under precision engagement modernization priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with United States primes commanding sole-source fighter radar contracts, while European suppliers absorb compliance costs from F-Gas Regulation cooling system transitions without equivalent margin recovery mechanisms.
United States
The Department of Defense sustains multi-billion-dollar modernization programs for F-35 Lightning II and fourth-generation fighter retrofits. ITAR restrictions on gallium nitride semiconductor exports force foreign suppliers to establish American engineering subsidiaries. Massachusetts and Texas host concentrated defense electronics clusters where Raytheon Technologies operates vertically integrated foundry capacity.
United Kingdom
Royal Navy Type 26 frigate procurement mandates simultaneous multi-target tracking capabilities for maritime domain awareness. BAE Systems anchors domestic radar integration through platform prime contracting structures. Scotland's naval shipbuilding corridor around Glasgow drives shipborne array specification development.
Germany
Luftwaffe Tornado replacement programs and naval frigate modernization accelerate solid-state array adoption. KBA and federal procurement offices enforce domestic production quotas for wide-bandgap semiconductors. Bavaria's defense electronics corridor around Munich concentrates subsystem engineering talent for transmit-receive module calibration.
Japan
Air Self-Defense Force F-15J fighter retrofits and maritime patrol aircraft upgrades drive AESA module demand. METI coordinates domestic gallium nitride foundry expansion to reduce import dependency. Nagoya's aerospace manufacturing cluster hosts platform integration facilities for Mitsubishi Heavy Industries radar programs.
Israel
Israel Aerospace Industries anchors airborne early warning and fighter radar exports to non-NATO markets. The national defense establishment prioritizes software-defined waveform development for electronic warfare integration. Tel Aviv's defense technology corridor concentrates RF engineering expertise for compact array designs.
Electronically Scanned Array Radar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated primes commanding fighter radar sole-source contracts while mid-tier specialists compete on upgrade cycle timing. The vendor base concentrates around platform integrators rather than standalone radar manufacturers, reflecting procurement office consolidation of subsystem sourcing. Two strategic archetypes dominate: gallium nitride foundry-integrated primes and software-defined beamforming specialists. Competitive moves center on captive semiconductor supply chain construction and digital architecture licensing partnerships.
Among United States-based defense primes, Raytheon Technologies Corporation and Lockheed Martin Corporation exemplify the foundry-integrated archetype through fighter radar platform anchoring. Saab AB occupies a distinct position within the mid-tier export specialist archetype, serving non-NATO airborne early warning demand through upgrade pathway contracting.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Saab AB |
| Thales Group |
| Leonardo S.p.A. |
| Israel Aerospace Industries |
| Aselsan A.S. |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Twenty-four to thirty-six month lead times for high-purity gallium nitride substrates concentrate pricing power with Japanese and American wafer suppliers, while defense primes with captive foundry capacity extract configuration premiums from NATO procurement offices facing sole-source contract constraints.
Pricing Analysis
Configured-to-order pricing for fighter radar retrofits commands substantial premiums over standard maritime patrol configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in passive array segments is intensifying because European F-Gas Regulation compliance deadlines force accelerated liquid-cooled solid-state transitions. Maritime patrol operators exhibit highest price sensitivity; United States Department of Defense fighter programs demonstrate lowest sensitivity due to electronic warfare parity mandates.
Supply Chain Analysis
Japan and the United States anchor high-purity gallium nitride wafer production, while Taiwan and South Korea concentrate backend packaging and testing for transmit-receive modules. Defense contractors draw from specialized RF engineering talent pools, rare earth magnet suppliers, and radiation-hardened semiconductor foundries. Single-source vulnerability concentrates in substrate-grade gallium nitride boule growers. Distribution runs through platform prime contractors rather than direct radar manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision alignment expertise for thousands of array elements represents the critical chokepoint, with defense contractors competing for RF engineering talent that transmit-receive module calibration demands.
For Market Incumbents: Secure captive gallium nitride foundry capacity through backward integration into substrate-grade wafer production, insulating against Japanese supplier concentration. Deepen software-defined waveform development partnerships with low-earth orbit satellite operators before digital beamforming architectures displace analog hardware dominance. Lockheed Martin's sole-source F-35 positioning demonstrates how platform anchoring neutralizes emerging entrant threats.
For New Entrants and Emerging Players: Lead with compact array designs for non-NATO airborne early warning markets where Erikeye ER upgrade pathways have validated mid-tier demand. Target maritime patrol niches where passive electronically scanned array cost advantages persist against AESA penetration. Position through licensing partnerships for gallium nitride monolithic microwave integrated circuit designs rather than competing for prime contractor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a sovereign-capability play because domestic production quotas for wide-bandgap semiconductors are restructuring competitive access across NATO member states. Acquisition focus centers on transmit-receive module calibration specialists with MIL-STD-461 certification track records. Watch for ITAR relaxation signals that would unlock technology transfer pathways for non-American engineering subsidiaries.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Expansion | Captive wafer production secures substrate supply against Japanese supplier bottlenecks for AESA programs. |
| Digital Beamforming Architecture Licensing | Software-defined waveform partnerships with satellite operators unlock low-earth orbit surveillance constellation demand. |
| MIL-STD-461 Certification Investment | Electromagnetic compatibility testing infrastructure compresses development cycles for platform integration bids. |
| Non-NATO Export Market Entry | Mid-tier airborne early warning platforms capture defense modernization budgets outside traditional procurement frameworks. |
| Transmit-Receive Module Calibration Talent Acquisition | RF engineering expertise alignment addresses precision array element positioning constraints in retrofit configurations. |
Methodological Framework
Desk research of defense procurement databases, gallium nitride foundry capacity disclosures, and regulatory filing repositories preceded structured interviews with radar subsystem engineering directors, Department of Defense program managers, transmit-receive module procurement leads, and electromagnetic compatibility testing specialists. Secondary validation drew from NATO defense expenditure reports, ITAR amendment tracking, European Union F-Gas Regulation implementation guidance, and semiconductor trade flow data. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Variance decomposition across technology, end user, installation, and application dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured active versus passive electronically scanned array splits, defense versus maritime versus aviation end-use concentration, airborne versus shipborne versus spaceborne platform constraints, and surveillance versus targeting application priorities. CAGRs derived from platform procurement cycle timing, retrofit fleet inventory analysis, and regulatory compliance deadline clustering. Forecast inputs included gallium nitride substrate capacity expansion announcements and sole-source contract renewal patterns.
The analysis sits within stated boundaries; outcomes outside sustained United States Department of Defense modernization funding or accelerated European F-Gas Regulation enforcement would require recalibration. Forecasts reflect assumptions regarding transmit-receive module yield rates, ITAR technology transfer stability, and sovereign domestic production quota implementation. Recalibration cycles align with material shifts in defense procurement office consolidation patterns and gallium nitride foundry capacity allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
EO/IR Gimbal Market