
 AI-Based Medical Imaging Algorithm Validation Test Platforms Market | 2026-2036
AI-Based Medical Imaging Algorithm Validation Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Based Medical Imaging Algorithm Validation Test Platforms Market Insights
The acute shortage of clinical AI validation engineers is unwinding the pace at which imaging algorithms reach regulatory clearance. GE HealthCare leverages its installed base of imaging hardware to bundle validation services directly with device contracts. Siemens Healthineers anchors its platform strategy on proprietary digital twin simulations that reduce physical testing cycles. NVIDIA competes by extending its GPU-accelerated compute stack into edge validation nodes for real-time algorithm stress-testing.
AI-based medical imaging algorithm validation test platforms constitute software-hardware systems that execute standardized performance benchmarking against curated medical image datasets, typically measuring sensitivity, specificity, and area-under-curve metrics across diverse patient demographics. These systems enable manufacturers to demonstrate clinical efficacy prior to regulatory submission. Automated validation tools dominate current procurement budgets due to their integration with continuous integration pipelines, while data annotation platforms represent the fastest-expanding segment as synthetic data generation reduces dependency on scarce labeled clinical archives. Cloud-based deployment captures the largest margin pool among delivery models because subscription economics lower upfront capital barriers for mid-sized device developers.
The FDA pre-certification framework and EU MDR Class IIa/IIb requirements for AI diagnostic software shape product roadmaps by mandating traceable validation documentation across algorithm versions. ISO 13485 quality management and IEC 62304 software lifecycle standards further constrain market access for platforms lacking structured risk management protocols. Stakeholders must weigh the trade-off between cloud scalability and on-premises data sovereignty as health systems tighten governance over cross-border patient imaging data.
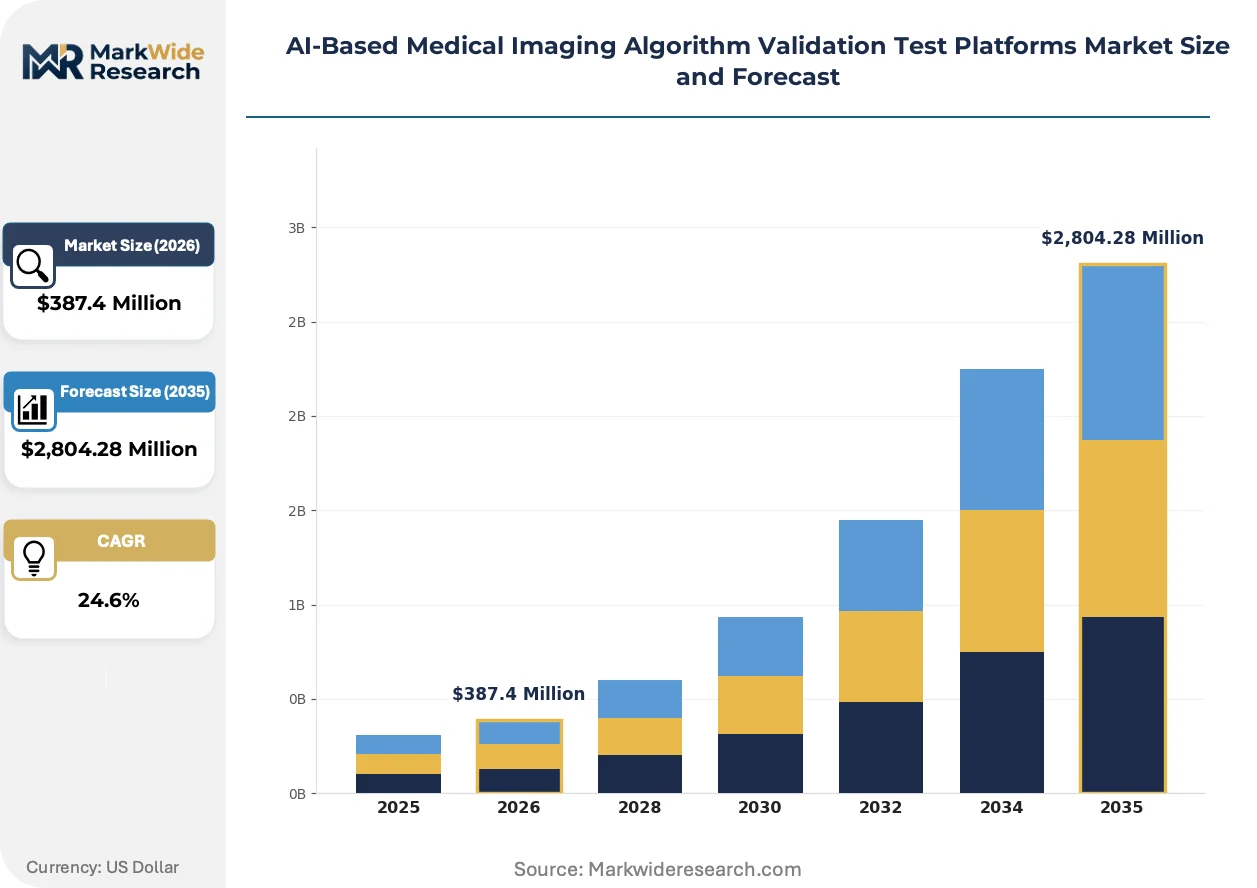
Market Dynamics
The FDA pre-certification framework and EU MDR Class IIa/IIb requirements are compressing validation timelines while expanding documentation burdens for AI diagnostic developers.
Growth Catalysts
- FDA Pre-Certification Framework:The United States regulator's streamlined pathway accelerates algorithm clearance for manufacturers demonstrating robust quality management, pulling forward platform procurement budgets.
- Cloud Infrastructure Scalability:Health systems in Germany and the United Kingdom prioritize subscription-based validation tools that eliminate upfront capital expenditure for mid-sized device developers.
- Synthetic Data Generation:Algorithmic creation of annotated medical images reduces dependency on scarce clinical archives, enabling validation against rare disease presentations without patient recruitment bottlenecks.
Market Restraints
- Clinical AI Engineer Scarcity:The acute shortage of validation specialists with dual competency in machine learning and regulatory science extends clearance timelines and inflates labor costs for platform operators.
- Cross-Border Data Sovereignty:Health systems in France and Switzerland impose strict governance over patient imaging data export, fragmenting cloud deployment architectures and raising compliance overhead.
- Physical Testing Cycle Dependency:Legacy validation protocols requiring hardware-in-the-loop testing resist full automation, constraining throughput for edge deployment scenarios.
Strategic Opportunities
- EU AI Act Conformity Assessment:The European Union's risk-based classification system for AI medical devices creates dedicated demand for validation platforms demonstrating transparency and bias mitigation capabilities.
- Digital Twin Convergence:Integration of physics-based simulation with generative adversarial networks enables synthetic stress-testing of algorithms across anatomical variations without physical phantom production.
- India Diagnostic Laboratory Expansion:Private imaging chains in Maharashtra and Karnataka seek automated validation tools to support indigenous AI development for tuberculosis and diabetic retinopathy screening.
Industry Challenges
- ISO 13485 Quality Management Integration:Device developers struggle to embed validation platform outputs into structured risk management protocols required for MDR technical documentation.
- Legacy PACS Interoperability:Hospital information systems built on DICOM variants resist seamless API integration with cloud-based validation pipelines, forcing costly middleware development.
- Algorithm Version Traceability:Continuous learning systems that update post-deployment create documentation gaps that regulators in Health Canada and TGA jurisdictions treat as non-conforming submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Based Medical Imaging Algorithm Validation Test Platforms Market |
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $2,804.28 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Validation Tools, Simulation Software, Data Annotation Platforms, Quality Assurance Kits Application: Radiology, Pathology, Oncology, Cardiology, Neurology End User: Research Institutes, Diagnostic Laboratories, Medical Device Companies, Academic Hospitals Deployment: Cloud-Based, On-Premises, Hybrid Systems, Edge Computing |
| Companies Covered | QMENTA, FIND, GE HealthCare, Siemens Healthineers, Philips, Canon Medical Systems, NVIDIA, Microsoft, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Based Medical Imaging Algorithm Validation Test Platforms Market Trends and Innovations
Edge computing architectures and synthetic data pipelines are compressing validation cycles while regulatory harmonization efforts fragment across jurisdictions. These forces reshape platform design priorities and procurement criteria simultaneously.
Containerized micro-validation environments are miniaturizing. These modular software packages execute algorithm stress-testing on GPU-accelerated edge nodes without cloud data transmission. Diagnostic laboratories in the United States deploy these units for real-time performance monitoring of deployed AI tools. The technology is miniaturizing physical infrastructure requirements from server rooms to embedded devices, enabling point-of-care validation for rural imaging deployments.
The EU AI Act's risk-based conformity assessment framework imposes mandatory bias auditing and explainability documentation for high-risk medical AI. Device manufacturers must demonstrate performance parity across demographic subgroups before CE marking. Validation platforms lacking structured fairness metrics face exclusion from European procurement shortlists, forcing roadmap pivots toward interpretability tooling.
Hospital purchasing committees now unbundle validation services from device contracts, treating algorithm verification as a recurring operational expense rather than capital equipment. Third-party validation-as-a-service providers capture this spend in the United Kingdom and Netherlands, displacing manufacturer-captive testing programs. Radiology departments favor external validation to demonstrate institutional independence during malpractice defense.
AI-Based Medical Imaging Algorithm Validation Test Platforms Market Segmentation
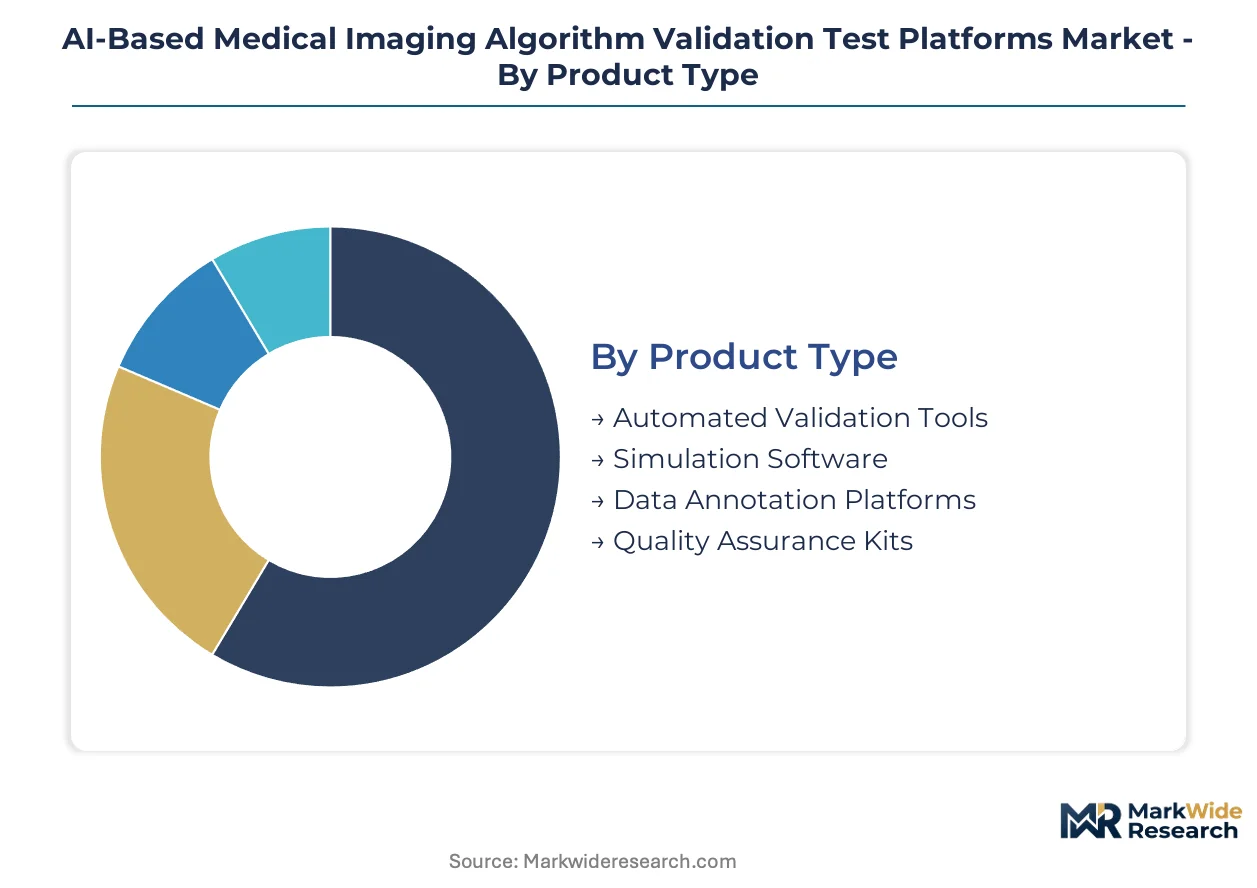
Segmentation in AI-based medical imaging algorithm validation test platforms reveals how procurement priorities diverge between regulatory compliance mandates and operational efficiency goals. Understanding these fault lines enables platform vendors to align product roadmaps with the specific technical documentation requirements that dominate purchasing decisions across end-user categories.
Product Type:
Substitution pressure concentrates on legacy quality assurance kits as automated pipelines displace manual validation workflows in FDA pre-certification programs.
- Automated Validation Tools:These systems execute continuous integration pipelines that benchmark algorithm performance against curated datasets, measuring sensitivity and specificity metrics without human intervention. Diagnostic laboratories in the United States prioritize these tools to compress clearance timelines for radiology AI submissions. Demand concentrates where FDA pre-certification frameworks reward manufacturers demonstrating robust quality management systems.
- Simulation Software:Physics-based digital twin environments generate synthetic medical images for stress-testing algorithms across anatomical variations without physical phantom production. Siemens Healthineers anchors its platform strategy on proprietary simulation capabilities that reduce hardware-in-the-loop testing cycles. German and United Kingdom health systems favor subscription deployment to eliminate upfront capital barriers.
- Data Annotation Platforms:Synthetic data generation reduces dependency on scarce labeled clinical archives, enabling validation against rare disease presentations.
- Quality Assurance Kits:Legacy manual testing packages face displacement as automated tools capture procurement budgets.
Automated validation tools retain volume leadership; data annotation platforms hold the steepest expansion curve.
Application:
Cost tier stratification separates high-complexity oncology validation from commoditized radiology benchmarking as reimbursement differentials reshape R&D allocation.
- Radiology:Chest X-ray and CT algorithm validation dominates current platform utilization due to high imaging volumes and mature regulatory pathways. Academic hospitals in Maharashtra and Karnataka deploy automated tools for tuberculosis screening algorithm development. Procurement concentrates where private imaging chains seek indigenous AI capabilities.
- Oncology:Tumor segmentation and treatment response monitoring demand specialized validation against longitudinal patient cohorts with histopathological correlation. The EU AI Act's risk-based classification elevates documentation requirements for high-risk cancer diagnostics, forcing platform vendors to embed fairness metrics and explainability tooling.
- Pathology:Whole-slide image analysis requires validation against digital pathology archives with standardized staining protocols.
- Cardiology:Echocardiography and cardiac MRI algorithm testing focuses on hemodynamic measurement accuracy.
- Neurology:Stroke detection and neurodegenerative disease imaging validation faces longer clearance timelines due to outcome uncertainty.
Radiology commands the largest installed base; oncology is climbing the fastest as precision medicine investments accelerate.
End User:
Customer type determines pricing architecture as medical device companies absorb platform costs into regulatory submissions while diagnostic laboratories treat validation as recurring operational expenditure.
- Medical Device Companies:These organizations integrate validation platforms into structured risk management protocols required for MDR technical documentation and FDA 510(k) submissions. GE HealthCare bundles validation services directly with imaging hardware contracts to lock in recurring revenue streams. Procurement concentrates among mid-sized developers seeking cloud scalability without capital expenditure.
- Diagnostic Laboratories:Third-party validation-as-a-service providers capture spend in the United Kingdom and Netherlands as radiology departments favor external verification to demonstrate institutional independence. Hospital purchasing committees now unbundle validation from device contracts, treating algorithm verification as operational expense.
- Research Institutes:Academic validation programs prioritize synthetic data generation for rare disease algorithm development.
- Academic Hospitals:Teaching institutions balance regulatory compliance with educational mission requirements.
Medical device companies retain volume leadership; diagnostic laboratories are gaining share fastest as external validation displaces captive testing.
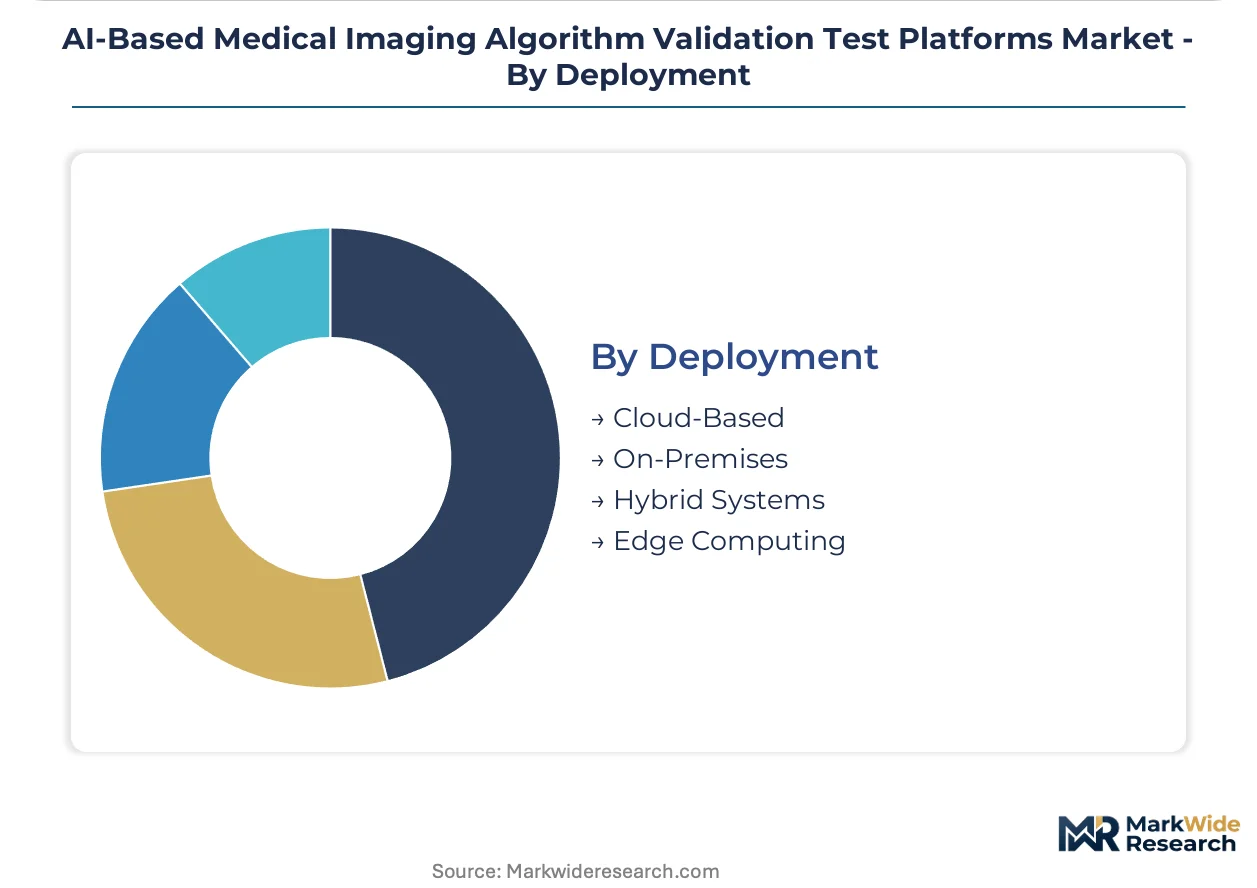
Deployment:
Supply concentration in cloud infrastructure is forcing architectural fragmentation as data sovereignty requirements in France and Switzerland resist centralized processing.
- Cloud-Based:Subscription economics lower upfront capital barriers for mid-sized device developers while enabling elastic compute scaling for large-scale validation campaigns. Health systems in Germany and the United Kingdom prioritize these models to eliminate server room infrastructure. NVIDIA extends GPU-accelerated compute stacks into cloud validation nodes for real-time algorithm stress-testing.
- Edge Computing:Containerized micro-validation environments execute algorithm stress-testing on GPU-accelerated nodes without data transmission. Diagnostic laboratories in the United States deploy these units for real-time performance monitoring of deployed AI tools. The technology miniaturizes physical infrastructure from server rooms to embedded devices.
- On-Premises:Health systems in France and Switzerland impose strict governance over patient imaging data export, preserving demand for local infrastructure.
- Hybrid Systems:Split architectures process sensitive data locally while leveraging cloud compute for non-identifiable synthetic validation.
Cloud-based deployment retains volume leadership; edge computing holds the steepest expansion trajectory as point-of-care validation requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Validation platform consumption patterns diverge sharply between jurisdictions with mature pre-certification frameworks and emerging markets building indigenous AI capabilities from scratch. Cloud deployment dominates in Germany and the United Kingdom where health systems prioritize subscription economics, while France and Switzerland preserve on-premises infrastructure under strict data sovereignty governance. The United States anchors procurement volume through FDA pre-certification pull-through, though India diagnostic laboratory chains are accelerating fastest as tuberculosis and diabetic retinopathy screening programs scale.
United States
FDA pre-certification programs compress clearance timelines for radiology AI developers, pulling forward platform procurement budgets among mid-sized device manufacturers. HIPAA constraints and state-level data breach notification laws shape hybrid deployment architectures that process sensitive imaging locally while leveraging cloud compute for synthetic validation. Academic medical centers in Boston and the San Francisco Bay Area anchor demand for automated continuous integration pipelines that benchmark algorithm performance against curated chest X-ray and CT datasets.
Germany
EU MDR Class IIa/IIb technical documentation requirements mandate traceable validation protocols that device developers embed into structured risk management systems. The national implementation of the EU AI Act risk-based conformity assessment elevates demand for platforms demonstrating bias mitigation and explainability capabilities. Siemens Healthineers anchors proprietary digital twin simulation capabilities from its Erlangen headquarters, reducing hardware-in-the-loop testing cycles for European radiology AI submissions.
United Kingdom
NHS procurement frameworks treat algorithm verification as recurring operational expenditure rather than capital equipment, displacing manufacturer-captive testing programs with third-party validation-as-a-service providers. The Medicines and Healthcare products Regulatory Agency aligns with FDA pre-certification principles through its Software as a Medical Device guidance, accelerating platform adoption among diagnostic laboratories. London-based radiology departments favor external validation to demonstrate institutional independence during malpractice defense proceedings.
France
CNIL data governance requirements and strict patient imaging data export restrictions fragment cloud deployment architectures, preserving demand for on-premises validation infrastructure among Paris-region academic hospitals. ANSM regulatory science programs emphasize algorithm version traceability for continuous learning systems that update post-deployment. The Île-de-France medical device cluster concentrates development of pathology AI validation tools against digital archives with standardized staining protocols.
India
CDSCO medical device rules and state-level diagnostic laboratory licensing frameworks drive procurement of automated validation tools among private imaging chains in Maharashtra and Karnataka. The PLI scheme for pharmaceuticals and medical devices incentivizes indigenous AI development for tuberculosis screening and diabetic retinopathy detection. Mumbai and Bangalore anchor validation platform demand as health systems build regulatory submission capabilities for export-oriented radiology AI products.
AI-Based Medical Imaging Algorithm Validation Test Platforms Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in a structure shaped by bundled hardware-software contracts and subscription-based validation services. Imaging equipment manufacturers leverage installed device bases to lock in recurring validation revenue, while cloud infrastructure providers extend GPU-accelerated compute stacks into edge deployment nodes. Strategic archetypes include hardware-integrated platform bundlers, independent software validation specialists, and hyperscale cloud infrastructure providers. Dominant competitive moves center on proprietary digital twin simulation capabilities and containerized micro-validation environments that miniaturize physical infrastructure requirements.
Among imaging equipment manufacturers, GE HealthCare and Siemens Healthineers occupy positions that exemplify hardware-integrated platform strategies, bundling validation services directly with device contracts to capture recurring revenue streams. NVIDIA represents the hyperscale infrastructure archetype, extending GPU-accelerated compute into edge validation nodes for real-time algorithm stress-testing. These three anchors illustrate how competitive positioning stratifies between captive ecosystem control and open infrastructure provision.
| Leading Market Players |
|---|
| QMENTA |
| FIND |
| GE HealthCare |
| Siemens Healthineers |
| Philips |
| Canon Medical Systems |
| NVIDIA |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for GPU-accelerated edge validation nodes concentrate pricing power among cloud infrastructure providers in the United States and Germany, while subscription contract structures compress upfront capital barriers for mid-sized device developers seeking FDA pre-certification compliance.
Pricing Analysis
Long-term subscription contracts dominate procurement relationships as health systems in Germany and the United Kingdom prioritize SaaS-tiered pricing that eliminates server room infrastructure investment. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with fully validated platforms commanding premium positioning over basic quality assurance kits. Pricing pressure stems from synthetic data generation tools reducing dependency on scarce clinical archives, compressing margins for traditional annotation services. Diagnostic laboratories exhibit highest price sensitivity due to unbundled validation-as-a-service procurement, while medical device companies absorb platform costs into regulatory submission budgets with lower elasticity.
Supply Chain Analysis
Inbound logistics costs for GPU hardware from Taiwan and South Korea into United States and German assembly facilities anchor supply chain risk assessments, with container availability fluctuations on Asia-Europe trade lanes constraining edge node deployment timelines. Component sourcing draws from NVIDIA GPU fabrication in Taiwan, specialized DICOM middleware development in Germany, and synthetic data generation software engineering in the United States. Single-source vulnerability concentrates in advanced GPU supply where foundry capacity constraints create allocation bottlenecks for validation platform manufacturers. Distribution runs through direct OEM partnerships for hardware-integrated bundles and third-party validation-as-a-service providers for cloud-based subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in early-cycle recovery as FDA pre-certification framework expansions pull forward platform procurement budgets among mid-sized device developers seeking accelerated clearance pathways.
For Market Incumbents: Shield installed base revenue by embedding proprietary digital twin simulation capabilities into hardware contracts, creating switching costs that resist unbundling pressure from third-party validation-as-a-service providers. Deepen backward integration into synthetic data generation pipelines to capture margin pools currently flowing to independent annotation specialists. Prioritize ISO 13485 certification maintenance as EU MDR technical documentation requirements harden compliance barriers. For New Entrants and Emerging Players: Anchor in diagnostic laboratory external validation demand across Maharashtra and Karnataka, where CDSCO regulatory submission capabilities remain underdeveloped among private imaging chains. Target cloud-native automated validation tools for tuberculosis and diabetic retinopathy screening algorithms, segments where indigenous AI development incentives under the PLI scheme concentrate procurement attention. Pursue channel partnerships with established PACS vendors to overcome legacy DICOM interoperability friction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because FDA and EU AI Act documentation burdens structurally expand addressable market for validation infrastructure regardless of underlying AI algorithm performance trajectories. Acquisition candidates should demonstrate proprietary synthetic data generation capabilities or established hospital system relationships that resist displacement. Watch Health Canada and TGA jurisdiction alignment with FDA pre-certification principles as signal for demand acceleration in Commonwealth markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Streamlined clearance accelerates platform procurement among mid-sized radiology AI developers in the United States. |
| EU AI Act Conformity Assessment | Risk-based classification mandates bias auditing capabilities that reshape European platform vendor roadmaps toward explainability tooling. |
| Hospital System Partnership | Direct relationships with NHS procurement frameworks displace manufacturer-captive testing with recurring operational expenditure models. |
| Software Companion Development | Containerized micro-validation environments miniaturize infrastructure requirements for point-of-care rural imaging deployments. |
| Reimbursement Strategy | Algorithm verification cost absorption into device contracts versus unbundled service pricing determines customer segment targeting. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submission databases, EU MDR technical documentation filings, and hospital procurement contract records. Primary interviews engaged regulatory affairs leads at medical device companies, biomedical engineers at academic medical centers, GPO contracts managers, and cloud infrastructure procurement officers. Secondary validation drew from SEC filings of listed imaging equipment manufacturers, CMS Medicare reimbursement data, and CDSCO medical device registration records. Bottom-up sizing of validation platform deployments triangulates against top-down spending estimates from health system IT capital expenditure disclosures.
Segmentation dimensions modeled include product type, application specialty, end-user category, and deployment architecture across the projection horizon. The analytical framework derives CAGRs from algorithm clearance volume trajectories, health system procurement cycle timing, and regulatory framework expansion schedules. Synthetic data generation adoption curves and edge computing infrastructure deployment rates inform scenario-weighted outcomes throughout the forecast period.
Material uncertainties — regulatory harmonization failures between FDA and EU AI Act frameworks, acute clinical AI engineer scarcity extending beyond current labor market adjustments, and cross-border data sovereignty enforcement tightening — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding pre-certification program expansion and cloud infrastructure cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Mobile Vascular Imaging Market