
 Fluoroscopy Market | 2026-2036
Fluoroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroscopy Market Analysis
The capability gap between full-platform manufacturers and niche C-arm specialists is bifurcating competitive dynamics in fluoroscopy equipment. Siemens Healthineers leverages vertically integrated detector fabrication to sustain premium positioning across digital radiography lines. GE HealthCare anchors its installed base through long-term service contracts that lock hospital procurement committees into multi-year upgrade cycles. Ziehm Imaging GmbH specializes in mobile C-arm configurations that dominate ambulatory settings where space constraints and capital budgets limit fixed-room deployments.
Fluoroscopy employs continuous X-ray beam generation and real-time image intensification or flat-panel detection to visualize dynamic physiological processes during surgical intervention and diagnostic catheterization. Modern systems operate at 15-30 frames per second with pulsed exposure modes that reduce patient radiation dose by 50-75% compared to continuous acquisition protocols. C-arm systems command the largest revenue pool due to their irreplaceable role in interventional cardiology and orthopedic trauma suites, while flat panel detector technology is displacing legacy image intensifiers as the dominant sensor architecture. Digital fluorography represents the fastest-expanding technology segment, driven by hospital mandates for dose traceability and DICOM-integrated workflow management.
The FDA governs device clearance through 510(k) and PMA pathways that mandate clinical evidence for new fluoroscopy platforms, while the EPA enforces radiation safety standards under 21 CFR 1020.32 that limit air kerma rates and mandate exposure tracking. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical follow-up obligations that extend certification timelines for systems entering European hospital networks. Stakeholders must monitor how AI-enabled dose optimization algorithms reshape regulatory review categories and reimbursement qualification criteria across major health systems.
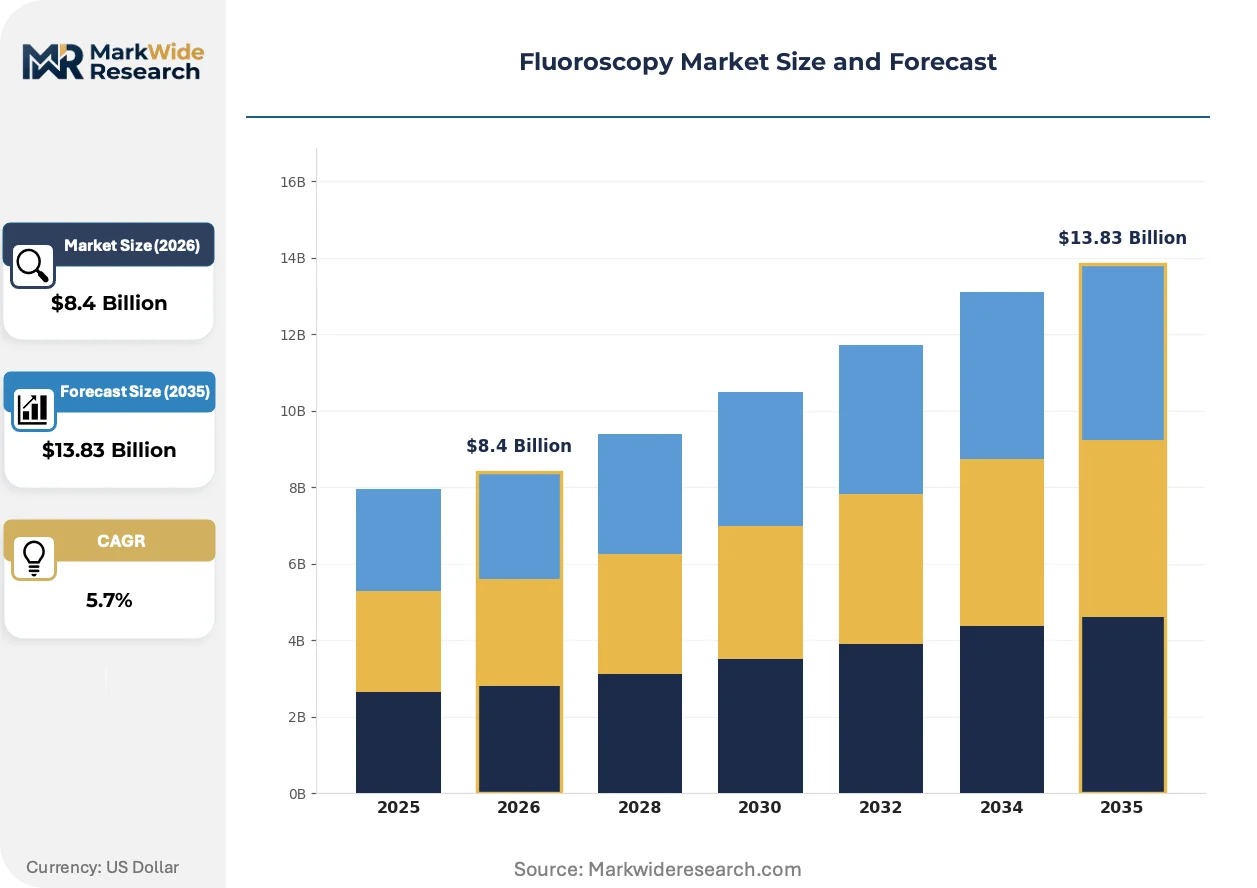
Market Dynamics
Flat-panel detector technology is compressing equipment replacement cycles as hospitals abandon image intensifier architectures for dose-traceable digital workflows, while regulatory mandates for radiation exposure tracking accelerate capital deployment toward integrated DICOM-compliant platforms.
Growth Catalysts
- Orthopedic surgical suite expansion:Hospital systems are retrofitting procedure rooms with C-arm fluoroscopy to support minimally invasive spine and joint interventions, creating pull-through demand for compatible imaging tables and navigation accessories.
- EPA 21 CFR 1020.32 compliance mandates:The regulation's air kerma rate limits and exposure tracking requirements force equipment upgrades, directly benefiting manufacturers with integrated dose monitoring software.
- Ambulatory surgical center proliferation:United States outpatient facilities are installing compact mobile C-arms to capture orthopedic trauma and pain management procedures shifting from inpatient settings.
Market Restraints
- Xenon flat-panel detector supply concentration:Production of high-purity amorphous selenium and cesium iodide scintillators concentrates among Asian material suppliers, creating input vulnerability for Western equipment manufacturers.
- EU MDR certification timeline extension:The regulation's stricter post-market surveillance obligations delay European hospital network approvals by 12-18 months compared to prior CE-marking pathways.
- Ultrasound-guided intervention substitution:Portable ultrasound systems are capturing low-complexity orthopedic and vascular access procedures previously requiring fluoroscopic guidance, compressing addressable procedure volume in cost-sensitive settings.
Strategic Opportunities
- AI-enabled dose optimization algorithms:Machine learning models that predict optimal pulse rates and collimation patterns are creating new regulatory review categories with first-mover advantage for integrated software-hardware platforms.
- India diagnostic imaging infrastructure buildout:The country's PLI scheme for medical electronics manufacturing is attracting joint ventures for localized C-arm assembly serving tier-2 and tier-3 city hospital networks.
- Subscription-based equipment access models:Per-procedure leasing arrangements are penetrating United States ambulatory surgical centers where capital constraints previously blocked fixed-room system acquisition.
Industry Challenges
- Medical physics specialist shortage:Hospital systems struggle to recruit qualified professionals capable of calibrating pulsed fluoroscopy protocols and validating AI-assisted dose reduction settings across multi-vendor installed bases.
- Legacy PACS integration complexity:Digital radiography upgrades require middleware development to bridge flat-panel detector outputs with decade-old hospital archive systems, extending deployment timelines and service costs.
- IP fragmentation across detector architectures:Patent thickets covering indirect conversion (scintillator plus photodiode) versus direct conversion (photoconductor) sensor designs complicate R&D roadmaps for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroscopy Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, C-arm Systems, Computed Radiography, Digital Radiography End User: Hospitals, Surgical Centers, Imaging Clinics, Diagnostics Laboratories Technology: Flat Panel Detectors, Image Intensifiers, Video Fluoroscopy, Digital Fluoroscopy Application: Orthopedics, Gastroenterology, Cardiology, Pain Management |
| Companies Covered | Siemens Healthineers, GE HealthCare, Koninklijke Philips NV, Canon Medical Systems Corporation, Shimadzu Corporation, Ziehm Imaging GmbH, Hologic Inc, Carestream Health, Hitachi Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroscopy Market Emerging Trajectories
Real-time imaging modalities are converging with surgical navigation and robotic positioning systems, compressing the boundaries between diagnostic visualization and therapeutic intervention. Equipment manufacturers are racing to embed intelligence at the detector level while regulatory frameworks scramble to categorize software-as-medical-device functionalities.
CMOS flat-panel detectors are supplanting legacy amorphous silicon architectures in premium C-arm configurations. Interventional cardiology departments at tertiary United States hospitals are adopting these sensors for their superior low-dose quantum efficiency and faster frame readout speeds. The shift is compressing price premiums for image intensifier-based systems and forcing mid-tier vendors to source CMOS backplanes from semiconductor foundries or exit the high-end mobile segment entirely.
The EU Medical Device Regulation's software classification guidance is redefining how AI-enabled fluoroscopy platforms enter European markets. Algorithms that autonomously adjust exposure parameters now trigger higher-risk device categories, extending clinical evidence requirements and notified body review timelines. Siemens Healthineers and GE HealthCare are responding by pre-submission engagement with BSI and TÜV SÜD to secure predicate device pathways for iterative algorithm updates.
Hospital procurement committees are unbundling long-term service contracts from initial equipment purchases, forcing manufacturers to compete on transparent parts-and-labor pricing. This behavioral shift is most pronounced in United States integrated delivery networks where capital equipment committees now separate imaging system acquisition from multi-year maintenance agreements. Vendors are countering with outcome-based uptime guarantees and remote diagnostics subscriptions that preserve recurring revenue streams without traditional lock-in structures.
Fluoroscopy Market Segmentation
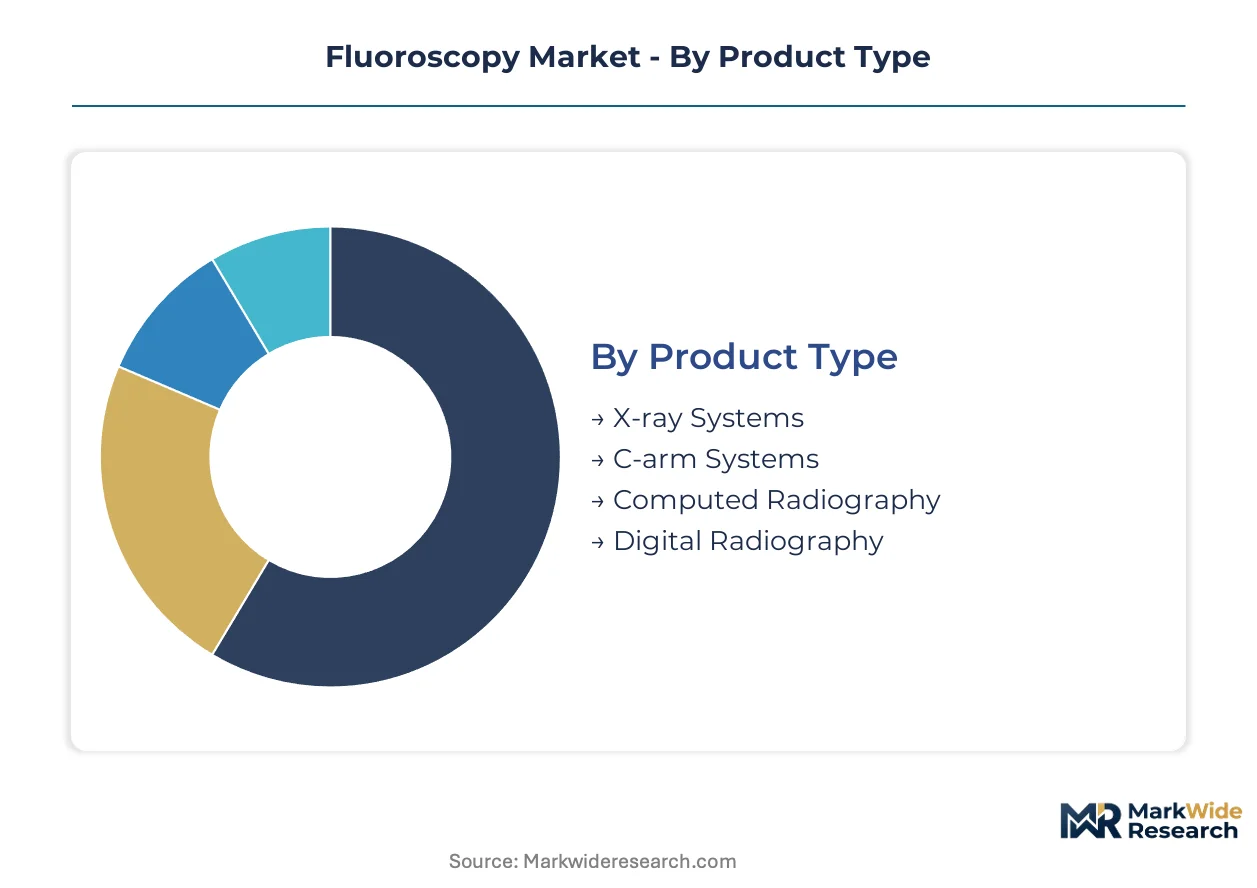
Segmentation in fluoroscopy equipment reveals distinct procurement patterns across facility types and clinical applications. Channel dynamics vary sharply between capital-intensive hospital networks and price-sensitive outpatient settings, with technology choices often predetermined by existing infrastructure compatibility.
Product Type:
Hospital procurement committees route fixed-room systems through group purchasing organizations, while ambulatory surgical centers favor mobile configurations acquired via specialty distributors.
- C-arm Systems:Mobile and fixed configurations deliver real-time intraoperative imaging through motorized isocentric rotation. United States ambulatory surgical centers are retrofitting compact C-arms for outpatient spine procedures, constrained by room dimensions and capital budgets.
- Digital Radiography:Flat-panel detector architectures replace cassette-based workflows with immediate image availability and DICOM-integrated storage. Hospital systems in Germany and France are mandating these upgrades to satisfy EU MDR traceability requirements and reduce repeat exposure incidents.
- X-ray Systems:Conventional radiographic platforms without fluoroscopic capability serve cost-sensitive diagnostic laboratories in India and Brazil.
- Computed Radiography:Phosphor plate systems persist in imaging clinics with legacy PACS infrastructure and limited upgrade capital.
By volume, C-arm Systems lead hospital procurement pipelines. By growth pace, Digital Radiography is expanding most quickly.
End User:
Facility scale dictates technology tier, with tertiary hospitals absorbing premium flat-panel systems and community settings prioritizing refurbished mobile units.
- Hospitals:Integrated delivery networks in the United States command multi-system contracts spanning interventional cardiology, orthopedic surgery, and emergency departments. Siemens Healthineers and GE HealthCare anchor these relationships through long-term service agreements that bundle preventive maintenance with software updates.
- Surgical Centers:Freestanding outpatient facilities in Texas and Florida are installing compact mobile C-arms to capture joint replacement and pain management procedures migrating from inpatient settings. Subscription-based equipment access models are penetrating this segment where capital constraints previously blocked acquisition.
- Imaging Clinics:Independent diagnostic facilities in tier-2 Indian cities are deploying refurbished image intensifier systems to serve government reimbursement panels.
- Diagnostics Laboratories:Pathology-focused operators in Brazil and Mexico utilize basic radiographic suites without real-time capability for chest and extremity studies.
Hospitals absorb the highest equipment value per site. Surgical Centers are gaining share fastest as procedure volume shifts outpatient.
Technology:
Sensor architecture determines dose efficiency and frame rate performance, with direct conversion photoconductors commanding premium positioning over indirect scintillator designs.
- Flat Panel Detectors:Amorphous selenium direct-conversion and cesium iodide indirect-conversion architectures deliver superior quantum efficiency at reduced patient dose. Tertiary cardiac catheterization laboratories in Japan and South Korea are adopting CMOS backplane variants for their faster readout speeds and lower electronic noise floors.
- Digital Fluoroscopy:Pulsed exposure protocols with automated brightness control enable dose traceability and ALARA compliance. The EPA's 21 CFR 1020.32 air kerma tracking mandates are accelerating hospital replacement of continuous acquisition systems.
- Image Intensifiers:Vacuum tube technology persists in refurbished equipment markets and developing economy installations where detector supply chain disruptions extend lead times.
- Video Fluoroscopy:Analog output systems with CCD cameras bridge legacy installations to modern PACS networks through digitization interfaces.
Flat Panel Detectors dominate new equipment shipments. Digital Fluoroscopy protocols are climbing the fastest as regulatory mandates tighten.
Application:
Clinical specialty determines frame rate requirements and procedural duration, with cardiac interventions demanding the highest temporal resolution and orthopedic trauma tolerating lower refresh rates.
- Orthopedics:Intraoperative imaging for fracture reduction, joint replacement, and spinal fusion requires C-arm mobility and surgical table compatibility. United States hospital systems are expanding dedicated orthopedic surgical suites with navigation-integrated fluoroscopy to support minimally invasive techniques.
- Cardiology:Percutaneous coronary intervention and electrophysiology procedures demand 15-30 frames per second with sub-millimeter spatial resolution. Interventional suites in Germany and the Netherlands are adopting CMOS detectors to reduce patient dose during prolonged complex cases.
- Pain Management:Fluoroscopically guided injections for epidural and facet joint delivery utilize lower-dose pulsed modes in office-based settings.
- Gastroenterology:Barium swallow and defecography studies employ intermittent capture rather than continuous fluoroscopy, permitting older equipment retention.
Orthopedics generates the highest procedure volume. Cardiology commands the steepest expansion trajectory as interventional volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoroscopy equipment trade flows reveal a pronounced import dependency in emerging diagnostic markets, while established manufacturing clusters in Germany, Japan, and the United States supply premium systems to hospital networks worldwide.
United States
Ambulatory surgical centers in Texas and Florida are retrofitting compact C-arm systems for outpatient spine and joint procedures. The FDA's 510(k) clearance pathway accelerates equipment replacement cycles for digital radiography upgrades. Siemens Healthineers and GE HealthCare anchor relationships with integrated delivery networks through long-term service agreements bundling preventive maintenance with software updates.
Germany
Interventional cardiology suites in Berlin and Munich are adopting CMOS flat-panel detectors to reduce patient dose during prolonged complex cases. The EU Medical Device Regulation imposes stricter post-market surveillance obligations that extend certification timelines for systems entering European hospital networks. Baden-Württemberg hosts manufacturing clusters producing high-precision C-arm components for export markets.
Japan
Tertiary cardiac catheterization laboratories in Tokyo and Osaka are deploying CMOS backplane variants for superior low-dose quantum efficiency and faster frame readout speeds. The PMDA governs device approval pathways that mandate clinical evidence for new fluoroscopy platforms. The Kanto region concentrates detector fabrication facilities serving domestic and Asia-Pacific demand.
India
Tier-2 city hospital networks in Maharashtra and Karnataka are deploying refurbished image intensifier systems to serve government reimbursement panels. The PLI scheme for medical electronics manufacturing attracts joint ventures for localized C-arm assembly. Imaging clinics in Gujarat and Tamil Nadu represent expansion targets for subscription-based equipment access models.
China
Diagnostic imaging infrastructure buildout in Sichuan-Chongqing and Shandong Peninsula regions drives procurement of cost-optimized digital fluoroscopy systems. The NMPA regulates medical device registration with accelerated pathways for domestically manufactured equipment. Yangtze River Delta clusters concentrate flat-panel detector component suppliers serving both domestic OEMs and export markets.
Fluoroscopy Market Vendor Landscape
Concentration sits with full-platform manufacturers possessing vertically integrated detector fabrication capabilities and established service networks. Siemens Healthineers and GE HealthCare command premium positioning through captive supply chains and multi-year hospital contracts. Mid-tier specialists compete on mobile configurations for space-constrained ambulatory settings. Competitive moves center on AI-enabled software integration and geographic expansion through joint ventures in India and Southeast Asia.
Within the premium-tier vector, Siemens Healthineers and GE HealthCare exemplify full-platform manufacturers leveraging in-house production of flat-panel detectors to sustain margin structures. Koninklijke Philips NV occupies a position bridging hospital-grade fixed systems and mobile configurations for outpatient networks. Ziehm Imaging GmbH represents the mobile C-arm specialist archetype, serving ambulatory surgical centers where capital budgets and room dimensions constrain fixed-room deployments. These three anchors illustrate how competitive positioning stratifies across integrated manufacturing depth versus focused specialization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Ziehm Imaging GmbH |
| Hologic Inc |
| Carestream Health |
| Hitachi Medical Systems |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at amorphous selenium foundries in Japan and South Korea shapes both component scarcity and price floors for flat-panel detector modules, compressing margins for Western equipment assemblers while elevating bargaining power for captive producers.
Pricing Analysis
Hospital procurement committees anchor equipment pricing through multi-year service bundling that obscures pure hardware costs. Three-tier pricing structure across premium, standard, and economy levels separates CMOS detector configurations from legacy amorphous silicon and refurbished image intensifier tiers. Cost compression in the economy tier is intensifying because Indian and Brazilian clinics source refurbished systems from decommissioned Western hospital fleets. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks absorb premium positioning through outcome-based uptime guarantees.
Supply Chain Analysis
Strategic stockpiling of cesium iodide scintillators and CMOS backplanes dominates procurement behavior among tier-one manufacturers, contrasting with just-in-time preferences for mechanical C-arm assemblies. Production concentrates in Japan, South Korea, and Germany for high-purity detector substrates, while China hosts downstream system integration facilities. Raw material dependencies span amorphous selenium photoconductors, cesium iodide scintillator crystals, and precision-machined isocentric rotation bearings. Single-source vulnerability concentrates in Asian material suppliers for high-purity amorphous selenium. Distribution runs through group purchasing organizations for hospital networks and specialty distributors for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) predicate pathways and EPA radiation safety compliance creates sticky installed bases resistant to displacement.
For Market Incumbents: Fortify captive detector fabrication capabilities through backward integration into amorphous selenium refining or exclusive offtake agreements with Japanese substrate suppliers. Lock hospital procurement committees into outcome-based service contracts that bundle preventive maintenance with iterative AI dose optimization software updates, neutralizing emerging entrants lacking regulatory clearance depth for autonomous exposure algorithms. For New Entrants and Emerging Players: Differentiate on subscription-based equipment access models targeting capital-constrained ambulatory surgical centers in Texas and Florida where per-procedure leasing penetrates faster than traditional purchase financing. Target tier-2 Indian city hospital networks deploying refurbished image intensifier systems, offering localized assembly partnerships under the PLI scheme with software-as-medical-device dose tracking that satisfies emerging regulatory mandates without full platform certification burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors detector-architecture specialists possessing CMOS backplane design capabilities and regulatory pre-submission relationships with FDA and notified bodies. Long-term viability hinges on software-hardware integration depth rather than pure hardware manufacturing scale. Acquisition candidates should demonstrate established AI-enabled dose optimization algorithms with predicate device pathways. Watch for inflection when EPA enforcement of 21 CFR 1020.32 exposure tracking mandates accelerates replacement cycles beyond historical equipment lifespans.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Dose Optimization Development | Autonomous exposure algorithms trigger higher-risk FDA device categories requiring clinical evidence investment. |
| CMOS Detector Backplane Sourcing Agreement | Semiconductor foundry partnerships secure low-dose quantum efficiency advantages for cardiac catheterization laboratories. |
| Subscription-Based Equipment Access Launch | Per-procedure leasing penetrates ambulatory surgical centers where capital constraints previously blocked acquisition. |
| Indian PLI Joint Venture Formation | Localized C-arm assembly serves tier-2 and tier-3 city hospital networks with government reimbursement panel access. |
| Outcome-Based Service Contract Restructuring | Uptime guarantees preserve recurring revenue streams as procurement committees unbundle maintenance from initial purchases. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and ambulatory surgical center administrators; and secondary validation through FDA 510(k) clearance databases, EPA radiation safety enforcement records, hospital procurement databases, and EU MDR notified body certification timelines. Bottom-up triangulation across equipment shipment volumes and top-down reconciliation with healthcare capital expenditure surveys anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product configuration (fixed-room versus mobile), detector architecture (direct versus indirect conversion), end-user facility type, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis, procedure volume migration patterns, and compliance-driven upgrade mandates. Forecast inputs incorporated EPA enforcement intensity projections and AI-enabled software classification guidance evolution from FDA and EU notified bodies.
Material uncertainties — supply chain disruptions in amorphous selenium substrate availability, accelerated ultrasound substitution in low-complexity procedures, and EU MDR certification timeline volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and hospital capital budget stability. Revision becomes warranted when EPA 21 CFR 1020.32 compliance inspection intensity crosses thresholds that force accelerated replacement beyond modeled equipment lifespans.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Specialty PACS Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Global Mini C-Arm Market