
 Asia-Pacific Fluoroscopy Market | 2026-2036
Asia-Pacific Fluoroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fluoroscopy Market Outlook
Aftermarket service revenue is rewriting profit structures across the Asia-Pacific fluoroscopy landscape. Siemens Healthineers leverages its extensive regional service footprint to capture long-term maintenance contracts. Canon Medical Systems Corporation anchors its position through localized technical training centers that reduce downtime for hospital clients. GE Healthcare competes by extending remote diagnostics capabilities that preempt hardware failures before they disrupt surgical schedules.
Fluoroscopy refers to real-time X-ray imaging using continuous radiation beams to visualize dynamic internal structures, with modern systems employing flat panel detectors achieving spatial resolution below 150 micrometers and frame rates exceeding 30 frames per second for cardiac catheterization guidance. Interventional fluoroscopy commands the largest installed base across Asia-Pacific cath labs, while portable fluoroscopy represents the fastest-expanding category as ambulatory surgical centers seek point-of-care imaging without fixed-room infrastructure. Flat panel detector technology leads technology transitions as image intensifier systems face obsolescence from dose optimization mandates.
Japan's PMDA maintains stringent quality management system inspections for fluoroscopy manufacturers, while Australia's TGA enforces IEC 60601-2-54 compliance for electromagnetic compatibility in clinical settings. China's NMPA requires in-country clinical trials for novel fluoroscopy systems before market authorization, creating extended timelines for first-time entrants. Stakeholders must weigh regulatory pathway complexity against the scale advantages of serving China's hospital procurement centralization and India's fragmented private provider network.
Market Dynamics
Flat panel detector technology is collapsing the installed base of image intensifier systems across Asia-Pacific cath labs, compressing replacement cycles and redistributing service revenue toward detector refurbishment networks.
Growth Catalysts
- China's NMPA Class III streamlining:Shortened registration timelines for digital flat-panel systems accelerate product introductions and expand vendor participation.
- Interventional cardiology volume surge:Tertiary hospitals in India, China, and Japan are expanding fluoroscopy suites to handle rising procedural demand.
- Hybrid operating room construction:Private healthcare chains across metropolitan India are modernizing surgical infrastructure with integrated imaging capabilities.
Market Restraints
- Flat panel detector supply concentration:Production of amorphous silicon TFT arrays concentrates in East Asian foundries, creating single-source vulnerability.
- Japan PMDA inspection intensity:Stringent quality management system audits extend manufacturer certification timelines and elevate compliance costs.
- X-ray tube replacement economics:High-voltage tube degradation drives recurring capital expenditure that constrains mid-tier hospital budgets.
Strategic Opportunities
- Vietnam and Indonesia hospital buildouts:Underpenetrated secondary cities present first-mover advantages for portable fluoroscopy deployment.
- Remote diagnostic service models:AI-enabled predictive maintenance reduces unplanned downtime and captures long-term service contracts.
- Ambulatory surgical center expansion:India's regulatory push for day-care procedures creates demand for mobile C-arm systems without fixed-room infrastructure.
Industry Challenges
- Clinical engineer scarcity:Specialized training for flat panel calibration and dose optimization lags equipment deployment across Southeast Asia.
- IEC 60601-2-54 electromagnetic compliance:Australia's TGA enforcement of compatibility standards complicates multi-vendor system integration in hybrid suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fluoroscopy Market |
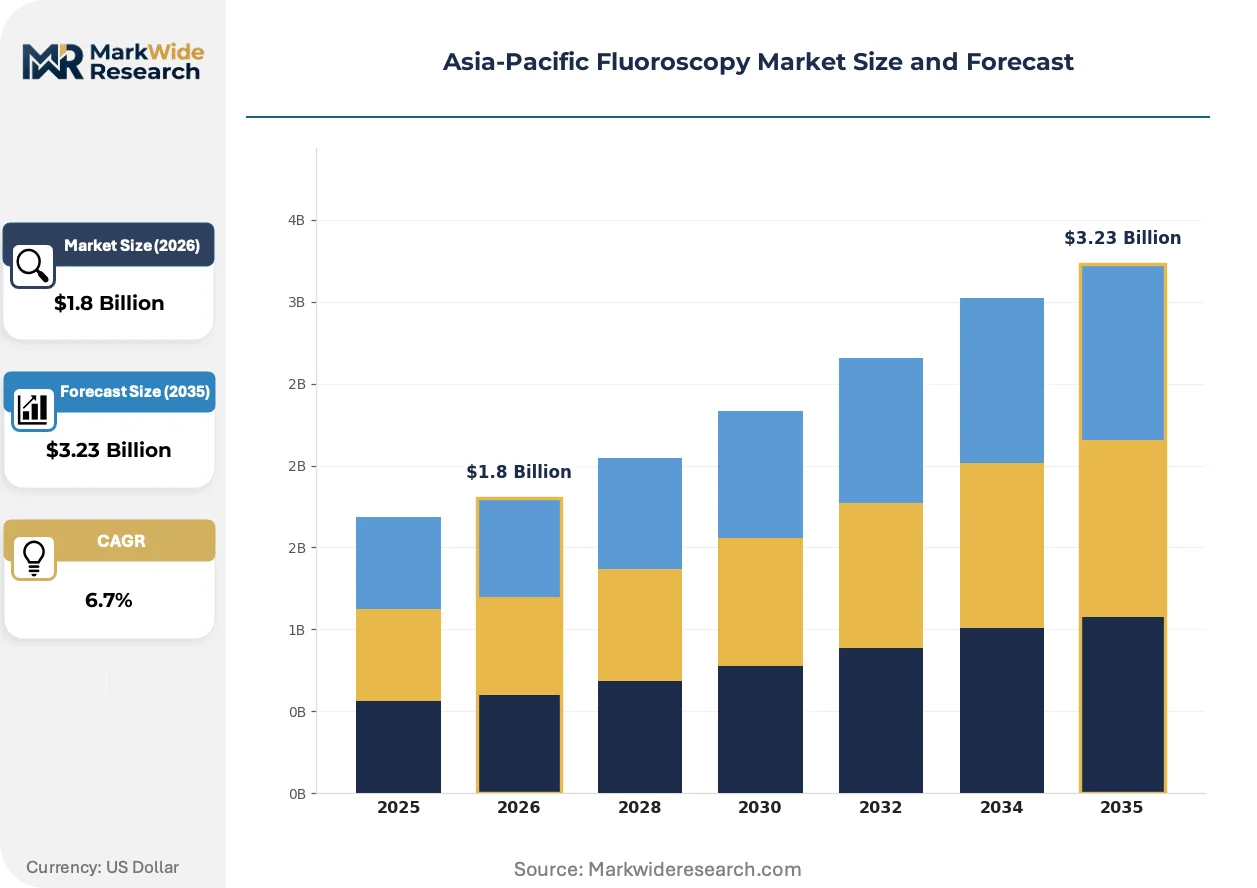
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiography, Angiography, Interventional Fluoroscopy, Portable Fluoroscopy Technology: Flat Panel Detector, Image Intensifier, Digital, Analog End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics Application: Cardiovascular Procedures, Gastrointestinal Procedures, Orthopedic Surgery, Urological Procedures |
| Companies Covered | Canon Medical Systems Corporation, GE Healthcare, Hitachi Medical Systems, Siemens Healthineers, Hologic Inc., Shimadzu Corporation, Koninklijke Philips NV, Ziehm Imaging GmbH, Carestream Health, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fluoroscopy Market Strategic Shifts
Artificial intelligence integration and detector material advances are compressing radiation dose thresholds while expanding real-time imaging capabilities across cardiac and orthopedic applications.
Photon-counting detector technology is collapsing the performance gap between diagnostic CT and interventional fluoroscopy. Japanese university hospitals are piloting cadmium-zinc-telluride sensors for ultra-low-dose cardiac catheterization. The structural consequence is collapsing price premiums for conventional energy-integrating detectors as performance benchmarks shift.
China's NMPA in-country clinical trial mandate for novel fluoroscopy systems creates extended authorization timelines for first-time entrants. Manufacturers must establish local investigator networks and patient recruitment infrastructure before market authorization. The policy most affects European vendors seeking to penetrate China's centralized hospital procurement system.
Service contract unbundling is fragmenting traditional equipment-vendor relationships. Indian private hospital chains now source preventive maintenance from third-party clinical engineering firms while retaining OEM support for detector replacement. This pattern concentrates in Maharashtra and Karnataka where independent service organizations have built technical training capacity.
Asia-Pacific Fluoroscopy Market Segmentation
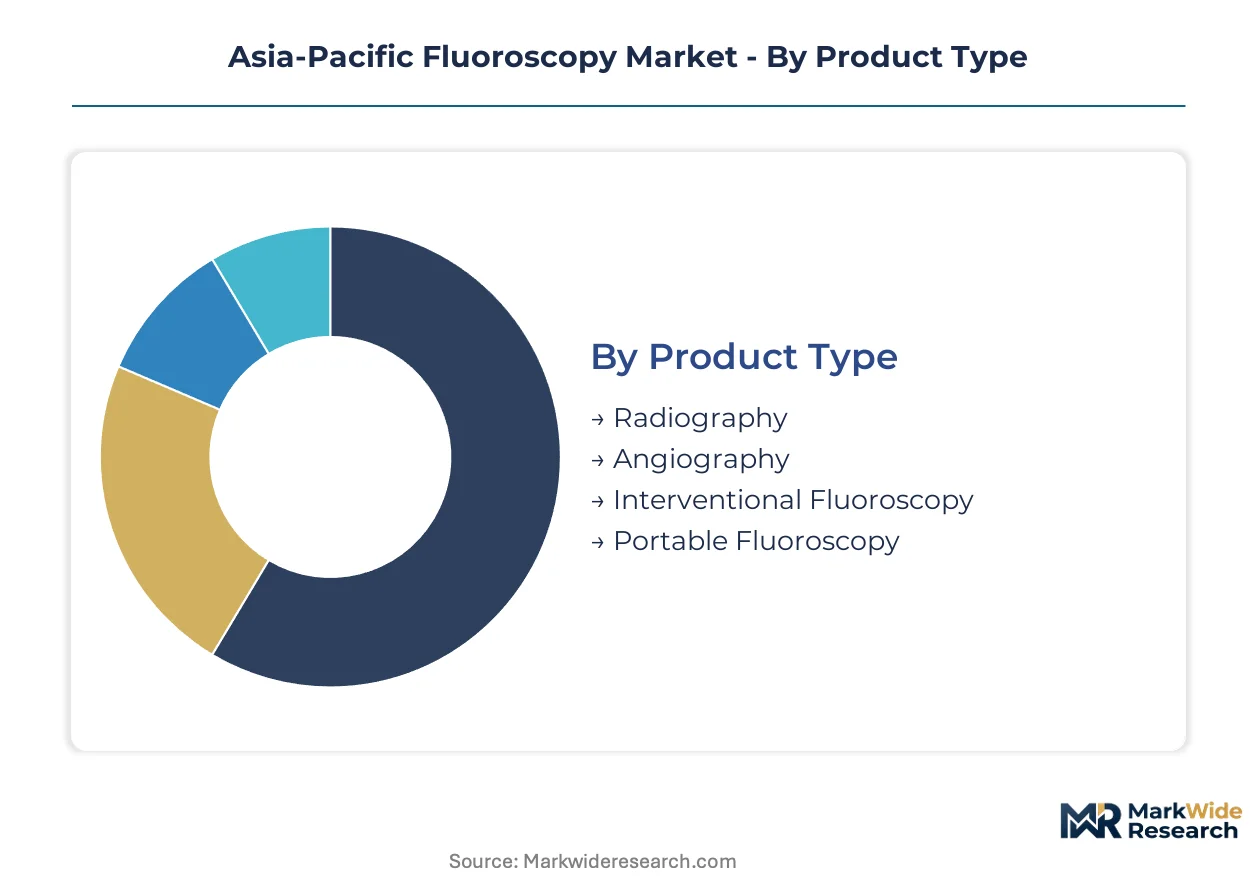
Fluoroscopy equipment segments across Asia-Pacific diverge sharply by capital intensity and clinical workflow integration. Procurement patterns in tertiary hospitals favor fixed-room systems with service bundling, while ambulatory expansion drives portable category growth.
Product Type:
Cost tier stratification separates fixed-installation systems from mobile units, with capital outlay determining hospital procurement sequencing across metropolitan India and China's tier-2 cities.
- Interventional Fluoroscopy:Real-time X-ray guidance systems for catheter-based procedures achieve spatial resolution below 150 micrometers with frame rates exceeding 30 frames per second. Tertiary cardiac centers in Japan and South Korea concentrate demand as PCI volumes expand beyond diagnostic capacity.
- Portable Fluoroscopy:Mobile C-arm units deploy without fixed-room infrastructure, enabling point-of-care imaging in emergency and orthopedic settings. India's ambulatory surgical center regulatory push and Indonesia's secondary hospital buildouts concentrate demand acceleration.
- Radiography:Static X-ray capture systems with fluoroscopic capability serve dual diagnostic functions in budget-constrained facilities.
- Angiography:Dedicated vascular imaging suites integrate 3D rotational capabilities for neurointerventional and peripheral procedures.
Interventional fluoroscopy holds installed capacity. Portable fluoroscopy is rotating up the share rankings.
Technology:
Detector architecture determines dose efficiency and image quality trajectories, with solid-state sensors displacing vacuum-tube intensifiers across Asia-Pacific replacement cycles.
- Flat Panel Detector:Amorphous silicon TFT arrays convert X-ray photons directly to digital signals, eliminating analog conversion losses. China's NMPA Class III streamlining accelerates vendor introductions, though East Asian foundry concentration creates supply vulnerability.
- Image Intensifier:Vacuum-tube technology with electron multiplication suffers from geometric distortion and dose inefficiency. Legacy installed base in Vietnam and Philippines rural hospitals sustues replacement demand as flat panel prices compress.
- Digital:Fully integrated digital acquisition chains enable DICOM-native workflow integration.
- Analog:Legacy signal processing persists in equipment nearing end-of-service life.
Flat panel detector systems command procurement preference. Image intensifier technology is climbing the fastest replacement priority lists.
End User:
Customer type shapes service contract structures and financing mechanisms, with public procurement centralization in China contrasting India's fragmented private provider network.
- Hospitals:Tertiary medical centers with cath lab and hybrid operating room infrastructure drive premium system demand. China's centralized hospital procurement and India's Apollo-Max Healthcare chains modernize suites simultaneously.
- Diagnostic Centers:Dedicated imaging facilities without inpatient services seek throughput-optimized configurations with rapid patient turnover.
- Research Laboratories:University hospitals in Japan pilot photon-counting cadmium-zinc-telluride sensors for ultra-low-dose protocols.
- Outpatient Clinics:Day-care procedure facilities require compact footprint systems with simplified operator interfaces.
Hospitals anchor equipment revenue. Diagnostic centers are gaining share fastest.
Application:
Clinical use case determines frame rate requirements, radiation dose tolerance, and anatomical coverage specifications across procedural categories.
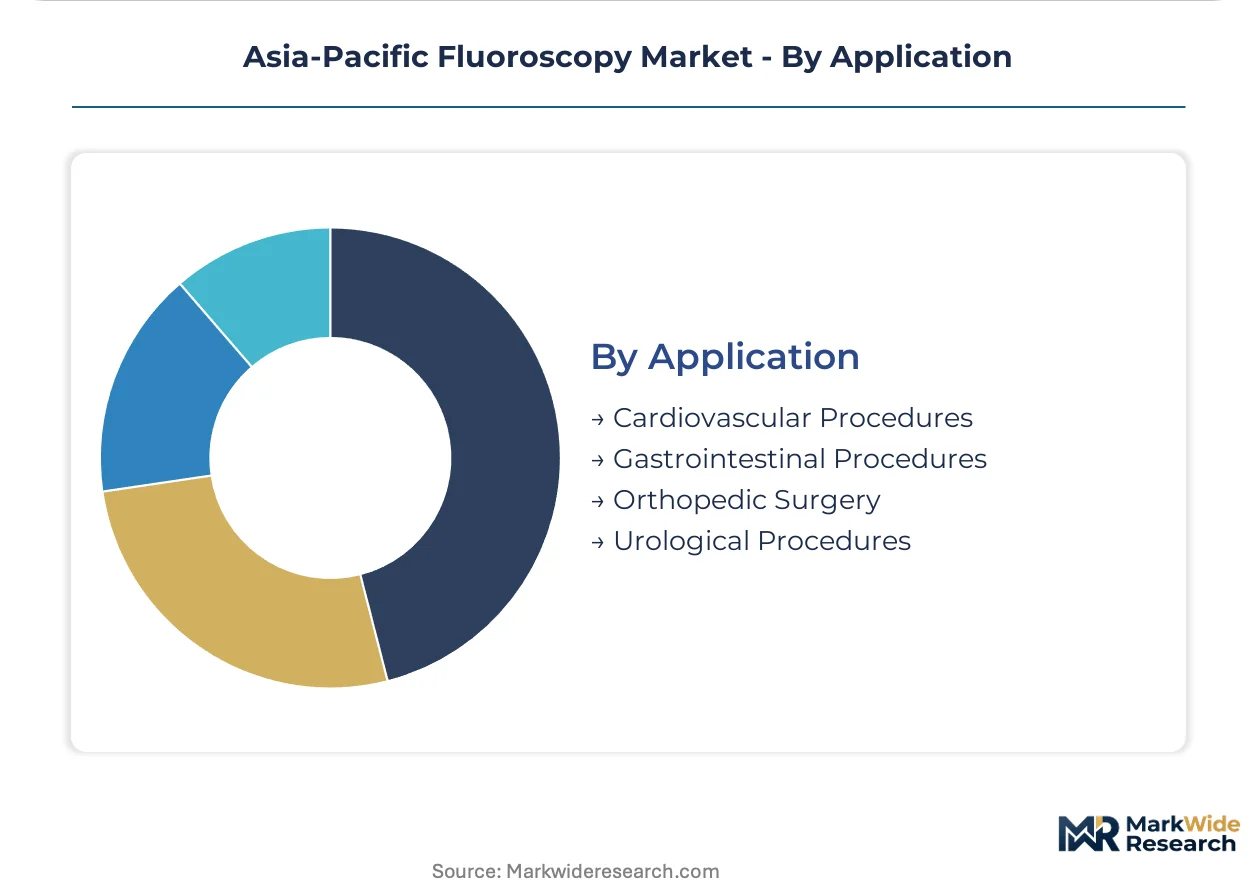
- Cardiovascular Procedures:Cardiac catheterization and electrophysiology mapping demand highest temporal resolution and lowest achievable dose. Japan's aging demographics and India's coronary disease burden concentrate procedural volume expansion.
- Orthopedic Surgery:Intraoperative fracture reduction and implant positioning require geometric accuracy without cardiac motion artifacts. Australia's TGA IEC 60601-2-54 compliance mandates complicate multi-vendor hybrid suite integration.
- Gastrointestinal Procedures:Barium studies and interventional endoscopy guidance utilize moderate frame rates with extended field coverage.
- Urological Procedures:Percutaneous nephrolithotomy and stent placement demand C-arm positioning flexibility.
Cardiovascular procedures absorb the largest fluoroscopy suite deployment. Orthopedic surgery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply between China's centralized hospital procurement and India's fragmented private provider networks, creating fundamentally different go-to-market requirements for fluoroscopy vendors.
China
Centralized hospital procurement concentrates demand for interventional fluoroscopy systems in tier-1 and tier-2 cities. NMPA's Class III medical device registration streamlining shortens timelines for digital flat-panel systems. Beijing-Tianjin-Hebei and Yangtze River Delta clusters drive replacement cycles as tertiary hospitals expand cath lab capacity.
India
Private healthcare chains in Maharashtra and Karnataka modernize hybrid operating rooms with integrated imaging capabilities. CDSCO regulatory pathways for imported Class C and D devices require local authorized representation. Metropolitan clusters around Mumbai, Delhi-NCR, and Bengaluru concentrate demand for portable C-arm systems in ambulatory surgical centers.
Japan
Aging demographics expand PCI volumes beyond diagnostic capacity at university hospitals. PMDA maintains stringent quality management system inspections that extend manufacturer certification timelines. Kanto and Kansai regions concentrate installed base upgrades as photon-counting detector pilots advance at Tokyo and Osaka academic medical centers.
Australia
TGA enforcement of IEC 60601-2-54 electromagnetic compatibility standards complicates multi-vendor hybrid suite integration. New South Wales and Victoria drive replacement demand as public hospital networks consolidate procurement. Research collaborations between university hospitals and detector manufacturers accelerate dose optimization protocol development.
South Korea
MFDS regulatory harmonization with international standards accelerates product registration for established vendors. Seoul Capital Area and Busan-Ulsan regions concentrate tertiary cardiac center expansion. National health insurance reimbursement structures favor fixed-installation systems with bundled service contracts over portable alternatives.
Asia-Pacific Fluoroscopy Market Competitive Environment
Capability concentration sits with detector technology specialists; scale advantage sits with diversified imaging conglomerates. The vendor base organizes into three tiers: integrated healthcare technology groups with full modality portfolios, dedicated cardiovascular imaging specialists, and regional service-focused distributors. Consolidation pressure intensifies as flat panel detector supply concentration forces equipment manufacturers toward backward integration or captive supply arrangements. Strategic moves center on service contract unbundling and AI-enabled predictive maintenance deployment.
Within the integrated healthcare technology tier, Siemens Healthineers, GE Healthcare, and Canon Medical Systems Corporation occupy positions defined by installed base scale and regional service footprint breadth. These entities exemplify archetypes ranging from European-engineered precision manufacturing to American diversified healthcare conglomerates to Japanese optoelectronics-derived medical imaging. Their competitive positioning derives from long-term maintenance contract capture and localized technical training infrastructure rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| GE Healthcare |
| Hitachi Medical Systems |
| Siemens Healthineers |
| Hologic Inc. |
| Shimadzu Corporation |
| Koninklijke Philips NV |
| Ziehm Imaging GmbH |
| Carestream Health |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in East Asian amorphous silicon TFT foundries is compressing flat panel detector pricing while simultaneously eroding supplier willingness to expand capacity, creating asymmetric pricing power that favors large equipment manufacturers with captive volume commitments.
Pricing Analysis
Long-term service contracts dominate fluoroscopy procurement across Asia-Pacific tertiary hospitals, with three-tier pricing structure across premium, standard, and economy levels anchored by detector performance specifications and NMPA registration tier. Price differentiation stems from after-sales service bundling and NMPA Class III certification status, with premium tiers capturing predictive maintenance and AI-enabled remote diagnostics. Cost compression in economy-tier portable systems is intensifying because Indian private hospital chains now unbundle preventive maintenance from OEM contracts. Metropolitan hospital clusters in China and India exhibit lowest price sensitivity due to centralized procurement scale, while secondary city hospitals in Vietnam and Indonesia face acute capital constraints.
Supply Chain Analysis
Tariff exposure between China and key detector component suppliers in Japan and South Korea dominates supply chain risk planning for fluoroscopy manufacturers serving the Asia-Pacific region. Production of amorphous silicon TFT arrays concentrates in Taiwan, South Korea, and Japan, while X-ray tube assemblies source primarily from Germany and Japan. Raw material dependencies span high-purity silicon substrates, rare-earth scintillator materials, and tungsten-rhenium filament alloys. Single-source vulnerability in CZT sensor production for photon-counting systems threatens next-generation rollout timelines. Distribution runs through regional authorized distributors in India and direct hospital sales teams in China's centralized procurement system.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific fluoroscopy market is approaching a platform-economics inflection as AI-enabled predictive maintenance and remote diagnostic interoperability reshape vendor-hospital relationships from transactional equipment sales toward integrated service ecosystems.
For Market Incumbents: Insulate installed base revenue by capturing long-term detector refurbishment contracts and establishing localized technical training centers that create switching costs for hospital clients. Siemens Healthineers and Canon Medical Systems Corporation exemplify this through regional service footprint expansion. Threats from third-party clinical engineering firms in Maharashtra and Karnataka demand channel control investments. Backward integration into flat panel detector supply or captive foundry arrangements represents the critical defensive lever. For New Entrants and Emerging Players: Build out ambulatory surgical center relationships in India's metropolitan clusters and portable C-arm deployment in Vietnam's secondary cities where fixed-room infrastructure constraints create white-space opportunity. The most penetrable segment is mobile fluoroscopy for day-care orthopedic procedures in Bengaluru and Ho Chi Minh City underpenetrated zones. A software-first go-to-market angle emphasizing AI dose optimization and DICOM-native workflow integration bypasses capital-intensive detector manufacturing barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable fluoroscopy sub-segments as solid-state detector prices compress and software differentiation supersedes hardware performance metrics. Long-term viability favors vendors with recurring service revenue exceeding forty percent of total sales. Acquisition targets should display regional service infrastructure in India or China paired with NMPA or CDSCO regulatory clearances. The signal to watch is hospital procurement centralization velocity in China's tier-2 cities as an indicator of pricing power erosion for non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Streamlining | Accelerates digital flat-panel system introductions by European and Japanese vendors into China's centralized hospital procurement. |
| Photon-Counting Detector Pilot Expansion | Positions Japanese university hospitals as ultra-low-dose protocol development centers, collapsing conventional detector price premiums. |
| Remote Diagnostic Service Model Deployment | Captures long-term maintenance contracts through AI-enabled predictive capabilities that preempt hardware failures. |
| Third-Party Clinical Engineering Partnership | Fragments traditional OEM relationships as Indian hospital chains source preventive maintenance from independent service organizations. |
| Hybrid Operating Room Infrastructure Buildout | Concentrates demand for integrated imaging capabilities in Maharashtra and Karnataka private healthcare chains. |
Study Parameters
The analysis maps interventional fluoroscopy, portable C-arm systems, and detector technology transitions, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at multinational manufacturers. Primary interviews combined with secondary validation from NMPA registration databases, CDSCO import records, hospital procurement disclosures, and PMDA quality management system inspection reports. Bottom-up equipment shipment tracking and top-down healthcare infrastructure spending analysis provided triangulation across market sizing estimates.
Assumption sets held NMPA regulatory streamlining timelines and India's ambulatory surgical center regulatory push as fixed baseline conditions, while varying flat panel detector supply concentration scenarios and photon-counting technology adoption curves across sensitivity analyses. Segmentation dimensions modeled include product type, detector technology architecture, end-user facility category, and clinical application with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle compression rates and procedural volume expansion in cardiovascular and orthopedic segments. Forecast inputs incorporated tertiary hospital cath lab capacity expansion plans and hybrid operating room construction pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic detector manufacturers or unexpected PMDA inspection intensity escalations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Cranial Doppler Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
China Digital Radiology Market