
 Generative AI in Clinical Trials Market | 2026-2036
Generative AI in Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Generative AI in Clinical Trials Market Insights
Biotechnology firms are collapsing historical reliance on contract research organizations for patient matching and protocol drafting, instead building in-house generative AI capabilities. IQVIA sustains its dominance through proprietary real-world data lakes integrated with large language models for regulatory submission drafting. Exscientia differentiates by embedding generative chemistry with trial simulation, collapsing traditional silos between molecule design and clinical feasibility. Microsoft anchors enterprise-grade deployments through Azure OpenAI Service partnerships with top-twenty pharmaceutical companies.
Generative AI in clinical trials encompasses transformer-based models, variational autoencoders, and generative adversarial networks trained on multimodal health data to synthesize patient cohorts, optimize trial protocols, and simulate biomarker responses. These systems process structured electronic health records, unstructured clinical notes, and genomic sequences through 512-token to 32k-token context windows, producing synthetic control arms and adaptive eligibility criteria that reduce enrollment timelines. Natural Language Processing leads technology adoption for regulatory document generation and adverse event narrative drafting, while Deep Learning captures margin pools in molecular response simulation for oncology trials. Patient Recruitment as a use case matures fastest across decentralized trial platforms, whereas Protocol Optimization remains nascent with concentrated vendor competition.
FDA's emerging guidance on AI-enabled drug development tools shapes validation requirements for synthetic data submissions, while the EU AI Act imposes conformity assessments on clinical decision-support systems deployed in European trials. HIPAA constraints on training data provenance force domestic vendors toward federated learning architectures or de-identification pipelines certified by institutional review boards. Stakeholders must monitor evolving precedents for regulatory acceptance of generative outputs in investigational new drug applications and determine whether to build compliant infrastructure internally or qualify through audited third-party platforms.
Market Dynamics
FDA guidance on AI-enabled drug development tools and the EU AI Act's risk classification framework are forcing pharmaceutical sponsors to rebuild validation pipelines for synthetic data submissions, compressing vendor qualification timelines and redrawing procurement criteria.
Growth Catalysts
- FDA AI Drug Development Guidance:The regulator's emerging validation standards for synthetic control arms accelerate sponsor willingness to submit generative outputs in investigational new drug applications.
- NIH-Funded Academic Medical Centers:These institutions in the United States are piloting transformer-based patient matching systems, creating reference implementations that lower adoption barriers for mid-tier biotech firms.
- Protocol Design Automation:Large language models trained on historical trial outcomes are collapsing manual drafting cycles from months to weeks for oncology and rare disease studies.
Market Restraints
- HIPAA Constraints on Training Data Provenance:HIPAA forces domestic vendors toward federated learning architectures or IRB-certified de-identification pipelines, raising infrastructure costs.
- EU AI Act Conformity Assessments:The regulation imposes mandatory third-party auditing on clinical decision-support systems deployed in European trials, extending time-to-market by 12-18 months.
- Computational Cost Volatility:Transformer models with 32k-token context windows require GPU clusters whose pricing fluctuates with semiconductor supply constraints in Taiwan and South Korea.
Strategic Opportunities
- Decentralized Trial Platforms:Patient recruitment use cases on these platforms remain underpenetrated in Germany and France, where site-centric traditions persist.
- Generative Chemistry-Trial Simulation Convergence:The integration of molecular design engines with feasibility forecasting creates white space for vendors collapsing silos between discovery and clinical operations.
- Japan's PMDA Digital Transformation:The regulator's 2023-2025 roadmap for AI-enabled submissions creates a regulatory tailwind for vendors establishing local validation partnerships.
Industry Challenges
- Biostatistician-Computational Linguist Collaboration Gap:Teams struggle to bridge statistical rigor requirements with prompt engineering for regulatory narrative generation.
- Legacy CTMS Integration Friction:Electronic data capture systems from the 2010s lack API architectures compatible with real-time synthetic patient injection, forcing costly middleware development.
- IRB Approval Uncertainty for Synthetic Arms:Institutional review boards apply inconsistent standards to patient-like data generation, stalling trial initiations at major academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative AI in Clinical Trials Market |
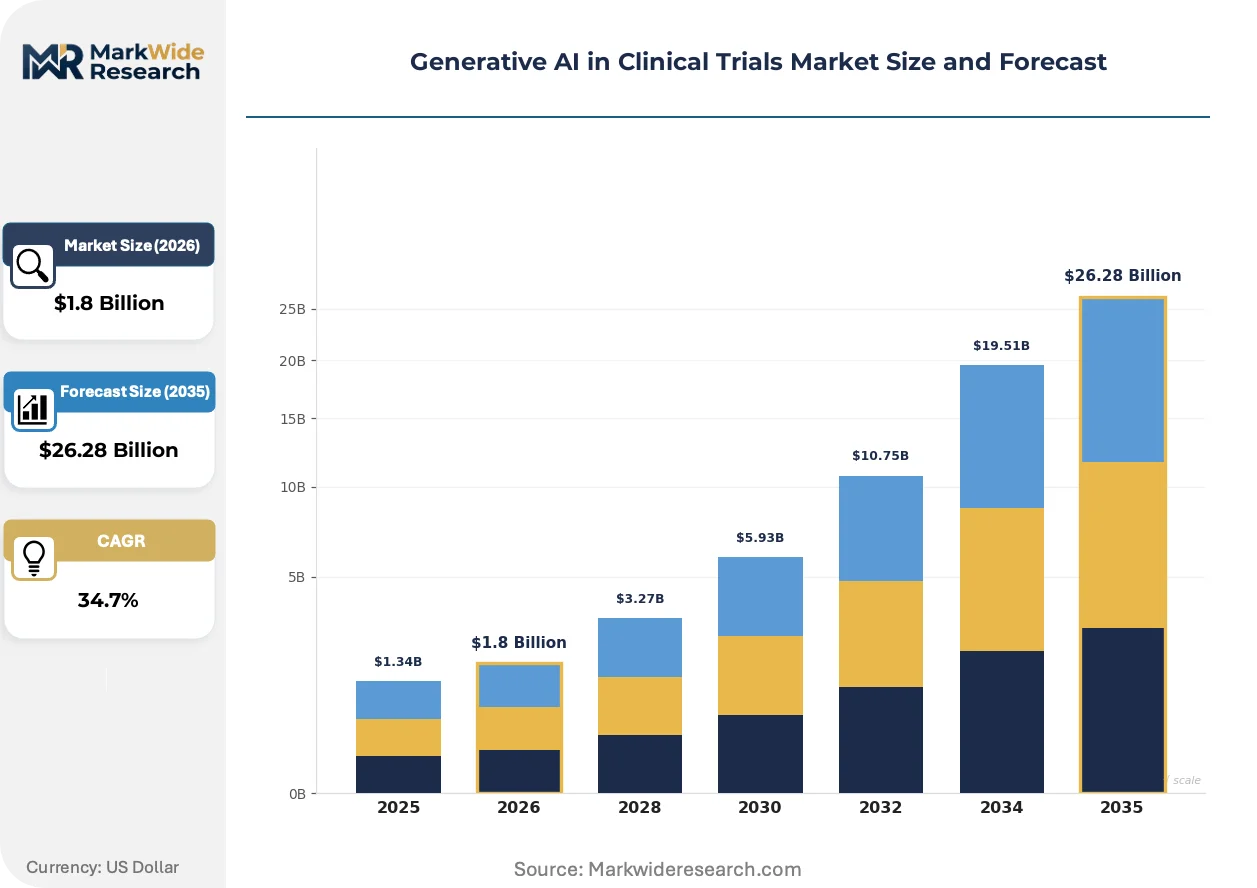
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Deep Learning, Predictive Analytics Use Case: Patient Recruitment, Data Analysis, Protocol Optimization, Risk Assessment End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, CROs Application: Oncology Trials, Cardiovascular Trials, Rare Disease Trials, Vaccine Trials |
| Companies Covered | IBM, Microsoft, Google Health, IQVIA, Parexel, ICON plc, Oracle Health, Exscientia, ConcertAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative AI in Clinical Trials Market Trends and Innovations
Transformer architectures are fragmenting established workflows across trial design, patient identification, and regulatory documentation, while compliance frameworks in Washington and Brussels force simultaneous infrastructure reinvention.
Multimodal foundation models processing structured electronic health records, unstructured clinical notes, and genomic sequences through expanded context windows are fragmenting traditional biostatistics workflows. Mid-size biotechnology firms in the United States are adopting these systems fastest, bypassing contract research organizations for cohort simulation. The technology is fragmenting vendor relationships that previously anchored trial operations to incumbent data providers.
The EU AI Act's risk-based classification for clinical decision-support systems imposes conformity assessment obligations on any generative tool influencing patient eligibility or endpoint adjudication. European pharmaceutical sponsors must now document training data provenance and algorithmic transparency to the satisfaction of notified bodies. Oncology trials with adaptive protocols face the steepest compliance burden, driving demand for audited third-party platforms over in-house builds.
Biopharma procurement teams are unbundling synthetic data generation from full-service contract research relationships, creating direct vendor contracts for specific trial phases. This pattern displaces the traditional bundled model where patient matching, protocol drafting, and regulatory submission support came from single providers. The shift is most visible in the United States, where sponsor headquarters clusters in Boston and San Francisco negotiate point-solution contracts with specialized AI vendors.
Generative AI in Clinical Trials Market Segmentation
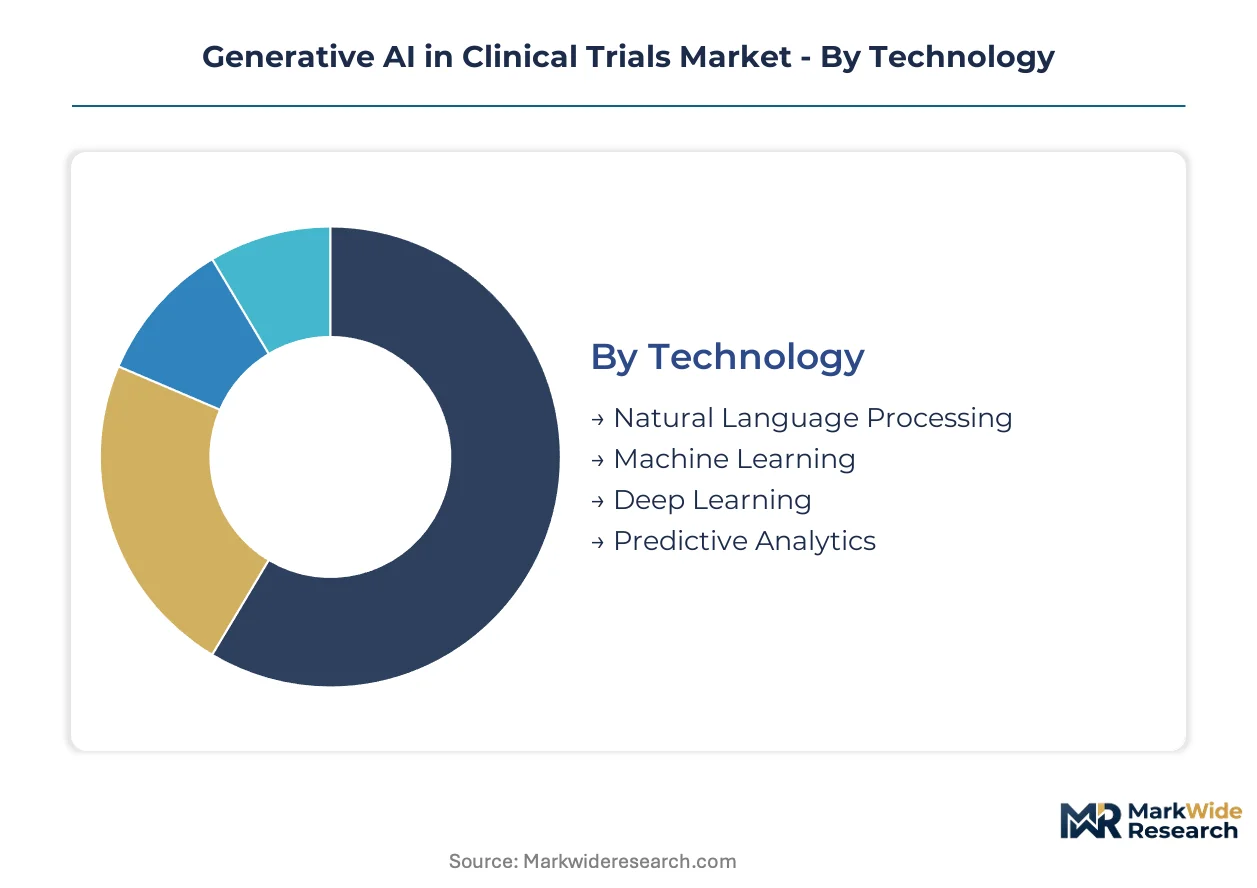
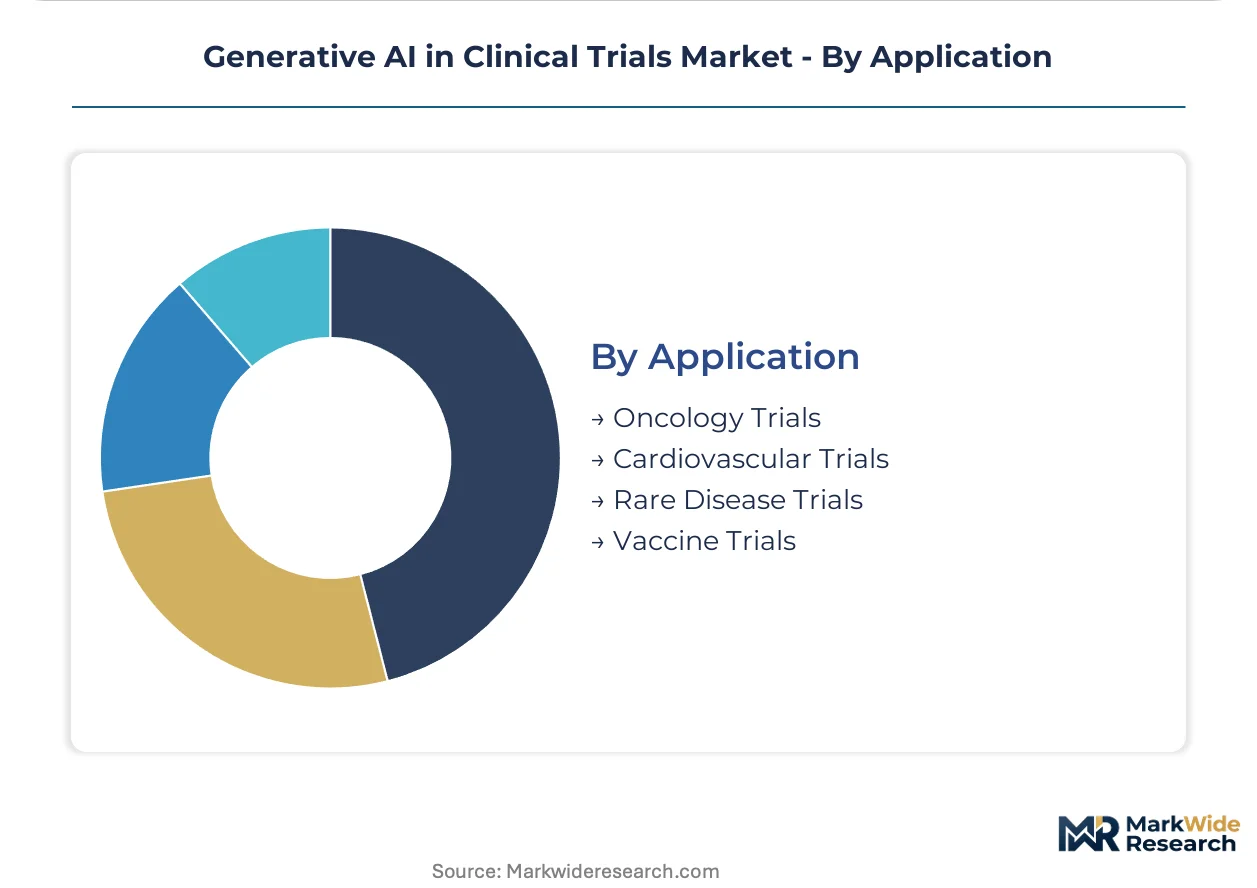
Generative AI deployment in clinical trials fragments across four distinct axes: underlying technology architecture, operational use case, organizational end user, and therapeutic application. Each dimension carries unique regulatory validation requirements and procurement patterns that reshape vendor positioning.
Technology:
FDA validation standards for synthetic data submissions create divergent compliance burdens across algorithmic approaches, with transformer-based architectures facing heightened scrutiny on training data provenance.
- Natural Language Processing:Transformer models with 512-token to 32k-token context windows process unstructured clinical notes and regulatory documents. Demand concentrates in Boston and San Francisco biopharma headquarters for adverse event narrative drafting and protocol generation, driven by FDA guidance on AI-enabled drug development tools.
- Deep Learning:Neural architectures simulate biomarker responses and molecular interactions through multimodal health data fusion. Oncology trials in NIH-funded academic medical centers deploy these systems for synthetic control arm generation, constrained by HIPAA-mandated federated learning infrastructure costs.
- Machine Learning:Supervised algorithms optimize patient matching through structured electronic health record feature extraction.
- Predictive Analytics:Statistical models forecast enrollment timelines and site performance for trial feasibility planning.
Natural Language Processing handles the majority of throughput; Deep Learning is expanding most quickly on regulatory acceptance.
Use Case:
Cost tier differentiation separates mature, audit-ready deployments from experimental implementations still navigating IRB approval uncertainty.
- Patient Recruitment:Decentralized trial platforms deploy transformer-based matching against real-world data lakes to collapse enrollment timelines from months to weeks. Germany and France show persistent underpenetration due to site-centric traditions, creating white space for vendor expansion.
- Protocol Optimization:Large language models trained on historical trial outcomes automate eligibility criteria drafting and adaptive design specification. Mid-tier biotechnology firms bypass contract research organizations for this capability, though EU AI Act conformity assessments extend European deployment timelines.
- Data Analysis:Synthetic patient generation and statistical modeling for interim analysis and futility assessment.
- Risk Assessment:Safety signal detection through automated adverse event narrative processing and pharmacovigilance reporting.
Patient Recruitment captures the largest installed base; Protocol Optimization is climbing the fastest as sponsors unbundle from full-service CRO relationships.
End User:
Customer type determines build-versus-buy calculus, with capital concentration in pharmaceutical sponsors enabling in-house capabilities that mid-market players must source externally.
- Pharmaceutical Companies:Top-twenty sponsors deploy enterprise-grade Azure OpenAI Service partnerships for end-to-end trial automation, integrating synthetic data generation with legacy CTMS through costly middleware development.
- Biotechnology Firms:Venture-backed developers prioritize point-solution contracts for specific trial phases over bundled CRO relationships, accelerating adoption of specialized AI vendors.
- Research Institutions:NIH-funded academic medical centers pilot reference implementations that lower adoption barriers for smaller sponsors.
- CROs:Incumbent service providers defend positioning through proprietary real-world data lake integration with large language models.
Pharmaceutical Companies dominate procurement volume; Biotechnology Firms are gaining share fastest through direct vendor relationships.
Application:
Therapeutic area specialization drives margin tiering, with oncology commanding premium pricing due to adaptive protocol complexity and biomarker simulation requirements.
- Oncology Trials:Multimodal foundation models process genomic sequences alongside structured and unstructured clinical data for synthetic control arm generation. EU AI Act risk classification imposes the steepest conformity burden here, favoring audited third-party platforms over in-house builds.
- Rare Disease Trials:Small patient populations necessitate synthetic cohort expansion and global site aggregation through generative patient matching, with Japan's PMDA digital transformation roadmap creating regulatory tailwinds for validation partnerships.
- Cardiovascular Trials:Large enrollment targets leverage predictive analytics for site selection and investigator identification.
- Vaccine Trials:Accelerated timelines deploy protocol automation for rapid adaptive design iteration.
Oncology Trials command the deepest technology penetration; Rare Disease Trials show the steepest expansion trajectory on synthetic data regulatory acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based biopharma clusters export generative AI validation expertise to European and Asian sponsors seeking FDA-aligned submission frameworks. Cross-border data governance friction shapes procurement patterns as vendors establish jurisdiction-specific compliance architectures.
United States
NIH-funded academic medical centers in Boston and San Francisco pilot transformer-based patient matching systems that serve as reference implementations for mid-tier biotechnology firms. FDA guidance on AI-enabled drug development tools accelerates sponsor willingness to submit synthetic control arms in investigational new drug applications. The Greater Boston corridor anchors enterprise-grade Azure OpenAI Service deployments among top-twenty pharmaceutical sponsors.
Germany
Site-centric trial traditions in Frankfurt and Munich create underpenetrated white space for decentralized platform vendors targeting patient recruitment automation. EU AI Act conformity assessments impose mandatory third-party auditing on clinical decision-support systems, extending time-to-market by 12-18 months. The Baden-Württemberg pharmaceutical cluster drives demand for audited third-party platforms over in-house generative AI builds.
United Kingdom
London-based contract research organizations defend positioning through proprietary real-world data lake integration with large language models for regulatory submission drafting. MHRA alignment with FDA validation standards for synthetic data creates regulatory continuity for sponsors operating across both jurisdictions. The Cambridge life sciences corridor concentrates venture-backed biotechnology firms pursuing direct vendor relationships for protocol optimization.
Japan
PMDA's 2023-2025 digital transformation roadmap for AI-enabled submissions creates regulatory tailwinds for vendors establishing local validation partnerships in Tokyo and Osaka. Rare disease trial sponsors leverage synthetic cohort expansion to address small patient population constraints. The Kanto region anchors pilot programs for generative chemistry-trial simulation convergence between molecular design engines and feasibility forecasting.
Switzerland
Basel-headquartered pharmaceutical majors deploy multimodal foundation models for oncology biomarker simulation under Swissmedic oversight of algorithmic transparency requirements. HIPAA-equivalent federal data protection law shapes training data provenance architectures for vendors serving both European and North American sponsors. The Zurich financial and regulatory infrastructure supports specialized AI vendor qualification for premium-tier trial automation contracts.
Generative AI in Clinical Trials Market Competitive Landscape
Player mix skews toward cloud hyperscalers, incumbent data providers, and specialized AI-native vendors. Consolidation pressure concentrates around proprietary real-world data access and regulatory validation credentials. Three archetypes dominate: infrastructure-anchored platforms, data-integrated service providers, and algorithm-specialized disruptors. Strategic moves center on unbundling synthetic data generation from full-service relationships and establishing jurisdiction-specific compliance architectures.
Within the infrastructure-anchored tier, Microsoft exemplifies enterprise-grade deployment scale through Azure OpenAI Service partnerships. IQVIA occupies a position representing data-integrated incumbency through proprietary real-world data lakes merged with large language models. Exscientia sits within the algorithm-specialized archetype, embedding generative chemistry capabilities with trial simulation workflows. These three anchors illustrate how competitive positioning fragments across technology depth, data access, and regulatory validation breadth.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Google Health |
| IQVIA |
| Parexel |
| ICON plc |
| Oracle Health |
| Exscientia |
| ConcertAI |
| Others |
Pricing and Supply Chain Analysis
GPU cluster utilization rates at Taiwan Semiconductor Manufacturing Company and Samsung Foundry determine compute cost floors for transformer model training, concentrating pricing power among cloud hyperscalers with captive semiconductor allocation while compressing margins for second-tier vendors lacking volume commitments.
Pricing Analysis
Next-generation transformer architectures with 32k-token context windows command three-to-four-fold premiums over legacy 512-token systems, while prior-generation variational autoencoders face commoditization in synthetic patient generation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platforms with audited training data provenance from uncertified point solutions and open-source alternatives. Cost compression in the standard tier is intensifying because mid-tier biotechnology firms unbundle from full-service contract research organizations and negotiate direct SaaS contracts. Biotechnology firms with venture-constrained budgets exhibit highest price sensitivity; top-twenty pharmaceutical sponsors prioritize regulatory validation over cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for GPU hardware deployment, forcing domestic vendors toward regional cloud infrastructure partnerships. Supply concentrates in Taiwan for advanced semiconductor fabrication, South Korea for HBM memory modules, and the United States for cloud orchestration software. Raw material dependencies span NVIDIA A100/H100 accelerators, high-bandwidth memory stacks, and specialized cooling systems for data center operations. Single-source vulnerability around TSMC's 4nm process node for AI training chips exposes vendors to allocation rationing during demand surges. Distribution runs through direct enterprise contracts with Microsoft Azure, Amazon Web Services, and Google Cloud Platform rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI in clinical trials represents a high-growth disruption justified by FDA's emerging validation pathway for synthetic control arms in investigational new drug applications, which collapses traditional biostatistics timelines and redraws procurement criteria across pharmaceutical R&D.
For Market Incumbents: Secure proprietary real-world data lake access through exclusive partnerships with NIH-funded academic medical centers, insulating against emerging AI-native vendors lacking longitudinal patient records. Defend margin position by embedding large language models within legacy clinical trial management systems through costly middleware development that raises switching costs for pharmaceutical sponsors. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks regulatory credibility for synthetic data platforms, opening white space in rare disease trial automation where small patient populations necessitate generative cohort expansion. Target Germany and France for decentralized trial platform deployment, exploiting persistent site-centric traditions that delay incumbent penetration. Pursue direct point-solution contracts with mid-tier biotechnology firms bypassing bundled contract research organization relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-specialized vendors with regulatory validation credentials over infrastructure-anchored hyperscalers lacking therapeutic domain expertise. Long-term viability hinges on sustained FDA acceptance of generative outputs in submissions and EU AI Act conformity assessment scalability. Acquisition target archetype: synthetic data platforms with institutional review board-certified de-identification pipelines. Signal to watch: PMDA validation partnership announcements indicating Asian regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Validation Partnership | Secures synthetic data acceptance pathway for investigational new drug submissions. |
| Real-World Data Lake Acquisition | Captures proprietary longitudinal patient records for transformer model training. |
| EU AI Act Conformity Assessment | Enables European trial deployment through notified body certification. |
| Azure OpenAI Service Integration | Anchors enterprise-grade deployments at top-twenty pharmaceutical sponsors. |
| Generative Chemistry Convergence | Collapses silos between molecular design engines and clinical feasibility forecasting. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up modeling of vendor contract values and top-down triangulation against pharmaceutical R&D expenditure patterns validate market sizing. Sensitivity analysis examines alternative adoption curves for synthetic control arm acceptance and EU AI Act implementation timelines.
Sensitivity analysis frameworks stress-test projections across technology deployment model, organization size, therapeutic area complexity, integration architecture, and regional regulatory cluster segmentation. CAGRs derive from logistic adoption curves fitted to historical health information technology diffusion patterns and adjusted for FDA guidance release impacts. Forecast inputs incorporate NIH funding trajectories for academic medical center pilot programs and hyperscaler capex disclosures for GPU infrastructure expansion.
Underlying assumptions cover sustained FDA validation pathway development, EU AI Act enforcement consistency, and Taiwan semiconductor supply stability, with deviation risk concentrated in institutional review board approval uncertainty for synthetic arms and geopolitical friction affecting cloud infrastructure access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Edema Clinical Trials Market