
 India Computed Tomography Market | 2026-2036
India Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
India Computed Tomography Market Foresight
Modular scanner configurations with detachable detector arrays and upgradeable slice-count platforms is hardening as the dominant procurement model across Indian hospital chains. Siemens Healthineers leverages this architecture to sustain premium positioning in metropolitan tertiary care centers. GE Healthcare anchors its presence through localized assembly operations and extensive service networks. Allengers Medical Systems Limited competes on cost-engineered systems designed for district-level government tenders.
Computed tomography refers to diagnostic imaging using X-ray beams rotated around a patient to reconstruct cross-sectional anatomical slices, with modern multi-slice systems achieving sub-millimeter spatial resolution and temporal resolution below 100 milliseconds for cardiac gating. The technology serves primarily to detect tumors, vascular abnormalities, traumatic injuries, and neurological lesions with non-invasive precision. Multi-slice CT scanners command the dominant revenue share due to throughput requirements in high-volume oncology and cardiovascular workflows, while cone beam CT systems are penetrating dental and ENT specialty clinics where lower radiation dose and compact footprint outweigh full-body capability. Dual-energy CT remains nascent in India, constrained by radiologist training gaps and limited reimbursement codes, though research institutions in Delhi and Hyderabad are piloting spectral imaging protocols.
CDSCO mandates registration and post-market surveillance for all imported CT systems under the Medical Device Rules, while BIS certification governs electrical safety and electromagnetic compatibility standards for domestically manufactured units. The Atomic Energy Regulatory Board enforces strict radiation safety protocols for installation and operator certification, creating compliance barriers that favor established vendors with dedicated regulatory affairs teams. State-level public health departments are consolidating diagnostic equipment procurement through centralized tenders, a shift that demands vendors pre-qualify service response times and spare parts inventory commitments. Stakeholders must weigh the trade-off between premium technology positioning and the volume opportunity in government-funded health infrastructure expansion.
Market Dynamics
The Ayushman Bharat insurance expansion is restructuring procurement priorities across India's hospital network, tilting capital allocation toward high-throughput multi-slice CT systems capable of handling elevated patient volumes in newly covered populations.
Growth Catalysts
- Ayushman Bharat Coverage Expansion:Government-funded health insurance is unlocking scanner demand in Tier-II and Tier-III cities where private hospital chains are establishing imaging centers to capture reimbursed patient flows.
- CDSCO Quality Norms:Tightened registration requirements for refurbished imports are redirecting procurement budgets toward domestically assembled new units, benefiting local manufacturing ecosystems.
- Oncology Workflow Intensification:Rising cancer screening volumes in Maharashtra, Karnataka, and Tamil Nadu are mandating sub-millimeter resolution capabilities that only 128-slice and above platforms deliver.
Market Restraints
- Import Dependency for Detectors:Scintillator crystals and photodiode arrays concentrate among Japanese and German suppliers, exposing Indian assemblers to currency volatility and extended lead times.
- AERB Certification Bottlenecks:Radiation safety clearance timelines for installation and operator licensing frequently exceed six months, delaying revenue recognition for hospital projects.
- Dual-Energy CT Underutilization:Spectral imaging protocols remain confined to research institutions in Delhi and Hyderabad due to reimbursement code gaps and radiologist training deficits.
Strategic Opportunities
- Tier-III City Penetration:District hospital tenders in Bihar, Odisha, and Uttar Pradesh remain undersupplied with advanced imaging, creating volume slots for cost-engineered 64-slice platforms.
- Cone Beam ENT Specialization:Dental and otolaryngology clinics in metropolitan pockets are adopting compact CBCT systems where lower radiation dose and reduced footprint outweigh full-body diagnostic range.
- PLI Scheme Manufacturing Incentives:Production-linked incentive structures for medical electronics are attracting component localization investments that could reshape total cost of ownership calculations.
Industry Challenges
- Service Engineer Scarcity:Trained personnel capable of detector calibration and tube replacement are concentrated in Mumbai, Bengaluru, and Chennai, leaving hinterland installations with 48-hour-plus response commitments.
- Legacy PACS Integration:Government medical colleges operating decade-old picture archiving systems face workflow fragmentation when connecting modern DICOM-RT compliant scanners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Computed Tomography Market |
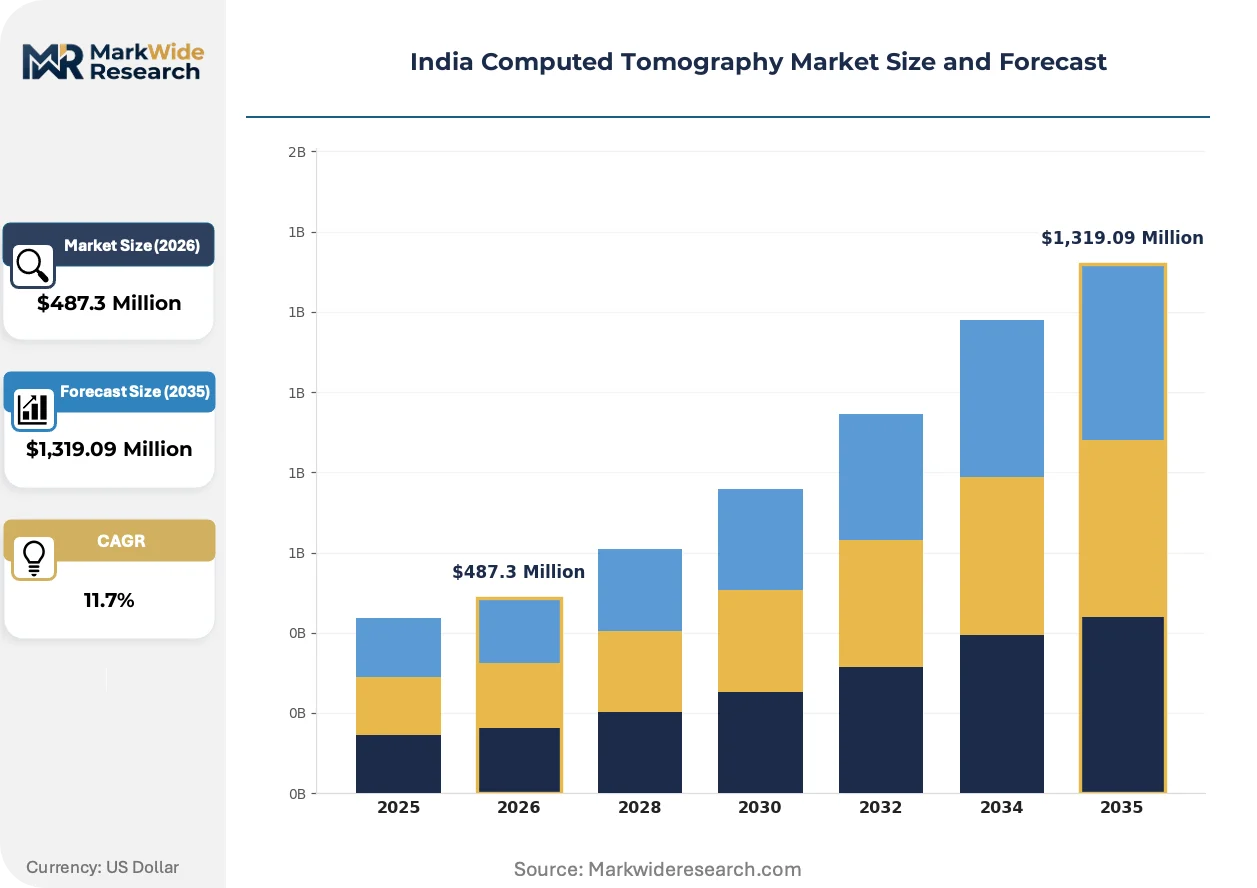
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Slice CT Scanner, Multi-Slice CT Scanner, Cone Beam CT, Dual-Energy CT End User: Hospitals, Diagnostic Centers, Research Institutions, Specialty Clinics Application: Oncology, Cardiovascular, Neurology, Trauma Technology: Helical CT, Digital Radiography, Conventional CT, Image-Guided Therapy |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Allengers Medical Systems Limited, United Imaging Healthcare Co., Ltd., Wipro GE Healthcare Private Limited, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Computed Tomography Market Shifts & Advancements
Detector architecture modularity is becoming the decisive specification in Indian hospital procurement, with upgradeable slice-count platforms allowing capital-constrained buyers to defer full replacement cycles while expanding clinical capabilities incrementally.
Artificial intelligence-embedded reconstruction algorithms are overtaking conventional filtered back-projection in metropolitan tertiary centers, with deep-learning denoising enabling diagnostic-quality images at 40% reduced radiation dose. Corporate hospital chains in Hyderabad and Chennai are mandating AI-ready acquisition platforms in new tenders, compressing competitive differentiation around raw hardware specifications toward software-enabled workflow efficiency gains.
CDSCO's 2023 amendments to Medical Device Rules have imposed mandatory post-market surveillance reporting for all imported CT systems, compelling foreign manufacturers to establish dedicated Indian regulatory affairs teams. Domestic assemblers holding BIS certification for electrical safety are capturing district-level government tenders where compliance documentation speed determines award outcomes, particularly in Maharashtra and Tamil Nadu state health department consolidations.
Hospital procurement committees are unbundling after-sales service from equipment purchase contracts, negotiating separate multi-year service level agreements with response time penalties. Private chains in Bengaluru and Delhi NCR are driving this disintermediation, forcing original equipment manufacturers to compete against independent service organizations for maintenance revenue that previously anchored equipment margins.
India Computed Tomography Market Segmentation
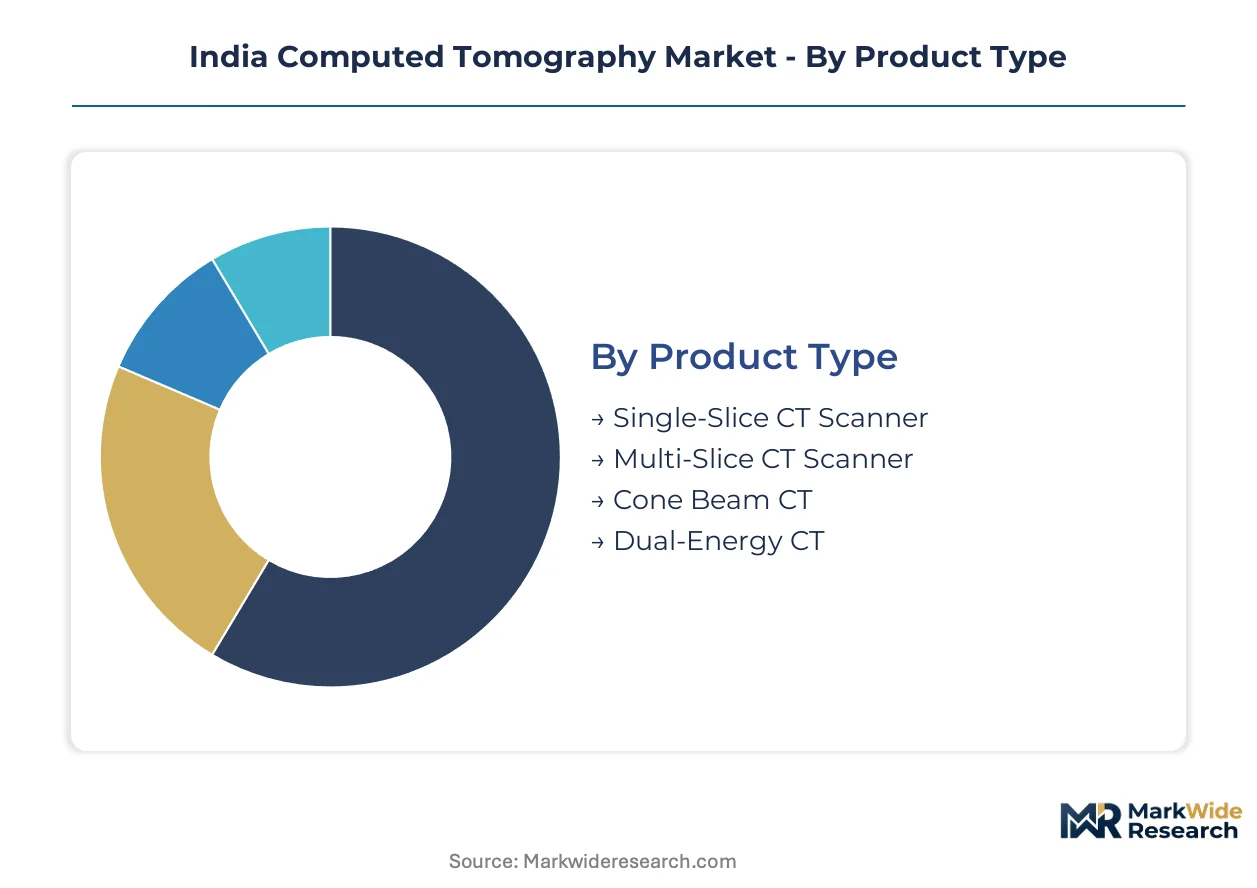
Scanner procurement patterns across Indian healthcare facilities diverge sharply by institutional capacity and patient throughput requirements. Capital allocation decisions hinge on balancing upfront acquisition costs against projected imaging volumes and reimbursement trajectories under expanding insurance coverage.
Product Type:
Capital-intensity stratification separates high-throughput tertiary installations from budget-constrained district facilities, with detector array sophistication driving the pricing ladder.
- Multi-Slice CT Scanner:Systems with 64 to 256 simultaneous detector rows deliver sub-millimeter spatial resolution and cardiac gating below 100 milliseconds. Maharashtra and Karnataka private hospital chains are mandating 128-slice minimum specifications for oncology workflows. These platforms absorb the bulk of installed capacity.
- Cone Beam CT:Compact gantry designs with flat-panel detectors rotate around fixed patient positions, emitting lower radiation doses than full-body systems. Dental and ENT specialty clinics in Delhi NCR and Chennai are adopting CBCT units where reduced footprint outweighs diagnostic range limitations. This segment is expanding most quickly.
- Single-Slice CT Scanner:Legacy sequential acquisition platforms remain deployed in Bihar and Uttar Pradesh district hospitals with constrained maintenance budgets.
- Dual-Energy CT:Spectral imaging systems with dual-source X-ray tubes enable material decomposition for gout and kidney stone characterization, though reimbursement code gaps limit deployment to Hyderabad and Delhi research institutions.
Multi-slice platforms anchor procurement volumes in metropolitan corridors; cone beam systems are climbing the fastest as specialty clinics proliferate.
End User:
Institutional purchasing power and patient volume predictability shape equipment specification tiers across the customer base.
- Hospitals:Tertiary care centers in Tamil Nadu and Karnataka operate 24/7 imaging departments requiring 300-plus daily scan throughput. Corporate chains negotiate enterprise service agreements covering detector calibration and tube replacement across multi-site networks.
- Diagnostic Centers:Standalone imaging facilities in Tier-II cities focus on rapid turnaround for walk-in patients, prioritizing 64-slice platforms with automated patient positioning to minimize technologist training requirements.
- Research Institutions:AIIMS Delhi and Hyderabad medical colleges pilot spectral imaging protocols and AI reconstruction algorithms, though clinical translation remains limited by radiologist certification gaps.
- Specialty Clinics:Orthopedic and dental practices in Bengaluru and Mumbai deploy compact CBCT systems for procedural planning, with lower capital thresholds enabling faster equipment refresh cycles.
Hospitals command the dominant share of installed base value; diagnostic centers are gaining share fastest as Ayushman Bharat redirects patient flows.
Application:
Clinical workflow intensity and reimbursement density determine which diagnostic domains justify premium scanner investments.
- Oncology:Tumor staging and treatment response monitoring require thin-slice protocols with contrast enhancement timing precision. Maharashtra cancer centers are driving demand for 256-slice platforms capable of whole-body PET-CT fusion.
- Cardiovascular:Coronary CT angiography demands sub-millimeter spatial resolution and prospective ECG gating to freeze cardiac motion. Chennai and Hyderabad cardiac institutes mandate dual-source architectures for high heart-rate patients.
- Neurology:Stroke protocol imaging prioritizes rapid acquisition speed over slice count, with 64-slice systems sufficient for most intracranial hemorrhage and large vessel occlusion detection.
- Trauma:Emergency department throughput requirements in Delhi and Mumbai government hospitals favor wide-bore multi-slice gantries accommodating ventilated patients and trauma boards.
Oncology applications concentrate the highest-value scanner deployments; cardiovascular imaging is expanding most rapidly as cardiac mortality awareness rises.
Technology:
Acquisition architecture maturity and software integration depth differentiate competitive positioning among modality vendors.
- Helical CT:Continuous patient translation during gantry rotation enables rapid volumetric acquisition with reduced motion artifacts. This architecture dominates installed base across Indian tertiary centers.
- Digital Radiography:Direct conversion flat-panel detectors replace image intensifier chains, improving dose efficiency and dynamic range for interventional CT applications.
- Conventional CT:Sequential slice-by-slice acquisition persists in legacy installations awaiting replacement funding under state health department tender cycles.
- Image-Guided Therapy:Intraoperative CT integration with navigation systems supports minimally invasive tumor ablation and biopsy procedures in specialized oncology centers.
Helical acquisition platforms anchor the technology mix; image-guided therapy configurations are expanding fastest as interventional radiology programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CT scanner production concentrates in domestic assembly operations serving consumption hubs across Maharashtra, Karnataka, and Tamil Nadu, while demand diffusion into Tier-II and Tier-III cities is reshaping procurement geography.
Maharashtra
Mumbai and Pune anchor the highest CT scanner deployment density, driven by corporate hospital chain expansion and government medical college upgrades. CDSCO's tightened quality norms for refurbished imports are redirecting procurement toward new domestically assembled units. The Mumbai-Pune corridor hosts dedicated imaging centers built by private chains to capture Ayushman Bharat reimbursed patient flows.
Karnataka
Bengaluru's tertiary care ecosystem drives demand for 128-slice and above platforms capable of cardiac gating and oncology workflows. State health department consolidated tenders are pre-qualifying vendors on service response times and spare parts inventory commitments. The city's medical technology cluster supports detector calibration and tube replacement capabilities that hinterland installations lack.
Tamil Nadu
Chennai's cardiac institutes mandate dual-source architectures for high heart-rate coronary CT angiography, pushing specification floors upward. AERB radiation safety clearance bottlenecks frequently exceed six months, delaying hospital project revenue recognition. Government medical colleges in the state are building dedicated imaging centers with 24/7 throughput requirements.
Telangana
Hyderabad's research institutions pilot spectral imaging protocols and AI reconstruction algorithms, though clinical translation remains limited by radiologist training gaps. The state's diagnostic center proliferation in Tier-II cities prioritizes 64-slice platforms with automated patient positioning. PLI scheme incentives are attracting component localization investments that could reshape total cost of ownership.
Delhi-NCR
AIIMS Delhi anchors advanced imaging research while surrounding private chains drive AI-ready acquisition platform tenders. Dental and ENT specialty clinics in the metro adopt compact cone beam CT systems where lower radiation dose and reduced footprint outweigh full-body capability. Legacy PACS integration challenges at government medical colleges create workflow fragmentation with modern DICOM-RT compliant scanners.
India Computed Tomography Market Competitive Landscape
The competitive structure tilts toward multinational equipment manufacturers with localized assembly operations and domestic cost-engineered specialists competing for district-level tenders. Siemens Healthineers leverages modular detector architecture to sustain premium positioning in metropolitan tertiary care. GE Healthcare anchors presence through extensive service networks. Allengers Medical Systems Limited competes on systems designed for government procurement. Strategic moves concentrate on service network densification and regulatory compliance team expansion.
Among Germany-based multinationals, Siemens Healthineers AG exemplifies the premium-tier archetype through modular platform architecture. GE Healthcare and Wipro GE Healthcare Private Limited occupy positions spanning metropolitan service density and localized assembly. Allengers Medical Systems Limited represents the domestic cost-engineered specialist archetype targeting district hospital tenders. Koninklijke Philips N.V. and Canon Medical Systems Corporation sit within the multinational imaging equipment tier competing on detector sophistication and software integration.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Allengers Medical Systems Limited |
| United Imaging Healthcare Co., Ltd. |
| Wipro GE Healthcare Private Limited |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Captive assembly operations in Bengaluru and Chennai anchor both supply positioning and pricing power for multinational vendors, while domestic specialists exploit PLI scheme incentives to compress total cost of ownership for government tenders. This integration choice separates premium-tier metropolitan deployments from cost-engineered district hospital configurations.
Pricing Analysis
Margin tightening in the 64-slice segment reflects CDSCO quality norms redirecting procurement from refurbished imports toward domestically assembled new units. Three-tier pricing structure across premium, standard, and economy levels stratifies by slice count and AI-readiness, with government medical colleges exhibiting highest price sensitivity and corporate cardiac institutes least. Pricing pressure stems from state health department consolidated tenders demanding pre-qualified service commitments.
Supply Chain Analysis
Direct-to-hospital channels handle metropolitan tertiary care demand while state-level tender aggregators consolidate district procurement volumes. Scintillator crystals and photodiode arrays concentrate among Japanese and German suppliers, exposing Indian assemblers to currency volatility and extended lead times. Single-source vulnerability for detector arrays compounds tariff exposure on precision electronics. Distribution runs through authorized service networks with spare parts inventory localized in Mumbai, Bengaluru, and Chennai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India CT market sits in a detector architecture transition, with modular upgradeable platforms displacing fixed-configuration legacy systems across hospital procurement committees.
For Market Incumbents: Extend service network densification into Tier-III cities before domestic competitors capture district hospital tender volumes under Ayushman Bharat expansion. Invest in detector calibration training centers to address engineer scarcity that delays AERB certification timelines. Anchor premium positioning through AI-embedded reconstruction algorithms that corporate chains now mandate in new tenders. For New Entrants and Emerging Players: Enter via cone beam CT specialization for dental and ENT clinics in Delhi NCR and Mumbai, where compact footprint requirements and lower capital thresholds enable faster penetration than saturated multi-slice segments. Target standalone diagnostic centers in Tier-II Telangana and Karnataka cities with automated patient positioning features that minimize technologist training requirements. Pursue PLI scheme qualification to reshape total cost of ownership calculations against established multinational pricing. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational imaging equipment manufacturers seeking service network augmentation. Long-term viability favors vendors with demonstrated AERB regulatory affairs capabilities and state tender pre-qualification track records. Watch for CDSCO post-market surveillance compliance cost escalation as an inflection indicator favoring acquirers with dedicated Indian regulatory teams.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Modularity Platform Development | Enables incremental slice-count upgrades that extend replacement cycles for capital-constrained buyers. |
| AI Reconstruction Algorithm Integration | Deep-learning denoising at 40% reduced radiation dose meets corporate hospital chain tender requirements. |
| PLI Scheme Manufacturing Qualification | Production-linked incentives attract component localization investments reshaping total cost structures. |
| State Tender Pre-Qualification | Service response time and spare parts inventory commitments determine award outcomes in consolidated procurement. |
| AERB Regulatory Affairs Team Expansion | Dedicated compliance capabilities compress radiation safety clearance timelines exceeding six months. |
Research Methodology
Independent corroboration across hospital procurement committees, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings, validated against CDSCO registration databases, state health department tender records, and AERB installation clearance filings. Bottom-up equipment shipment tracking triangulates with top-down hospital infrastructure budget allocations across Maharashtra, Karnataka, Tamil Nadu, Telangana, and Delhi-NCR.
Rate-of-change decomposition separates volume expansion in Tier-II and Tier-III cities from value migration toward higher-slice platforms across the projection horizon. Segmentation modeling incorporates product type, end user institutional tier, clinical application intensity, and technology architecture maturity. CAGRs derive from installed base replacement cycles, Ayushman Bharat reimbursement trajectory assumptions, and PLI scheme incentive uptake projections.
Revisions become necessary when CDSCO regulatory amendments, AERB certification bottleneck resolution, or PLI scheme restructuring materialize outside base-case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Brazil Digital Radiology Market