
 Retinal Imaging Devices Market | 2026-2036
Retinal Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Imaging Devices Market Outlook
Multi-source component procurement is restructuring supply relationships across the retinal imaging devices industry. Carl Zeiss Meditec AG anchors its competitive position through captive optical manufacturing in Germany. Topcon Corporation leverages its dominance in fundus camera platforms across Asian and European eye clinics. Heidelberg Engineering GmbH specializes in spectral-domain OCT engineering, sustaining premium positioning among academic medical centers.
Retinal imaging devices are diagnostic instruments that capture high-resolution photographs or cross-sectional scans of the posterior eye, typically employing wavelengths between 500-600 nanometers for fundus photography or near-infrared interferometry for optical coherence tomography, to detect pathological changes in retinal vasculature and neural tissue. Their primary commercial purpose is enabling early-stage diagnosis of sight-threatening conditions before symptomatic vision loss occurs. Optical coherence tomography generates the deepest margin pools due to recurring software upgrade cycles and disposable patient interfaces. Widefield imaging is displacing standard-field fundus photography in diabetic retinopathy screening programs across hospital networks. Eye clinics represent the fastest-growing end user channel as decentralized diagnostic models reduce patient travel burdens.
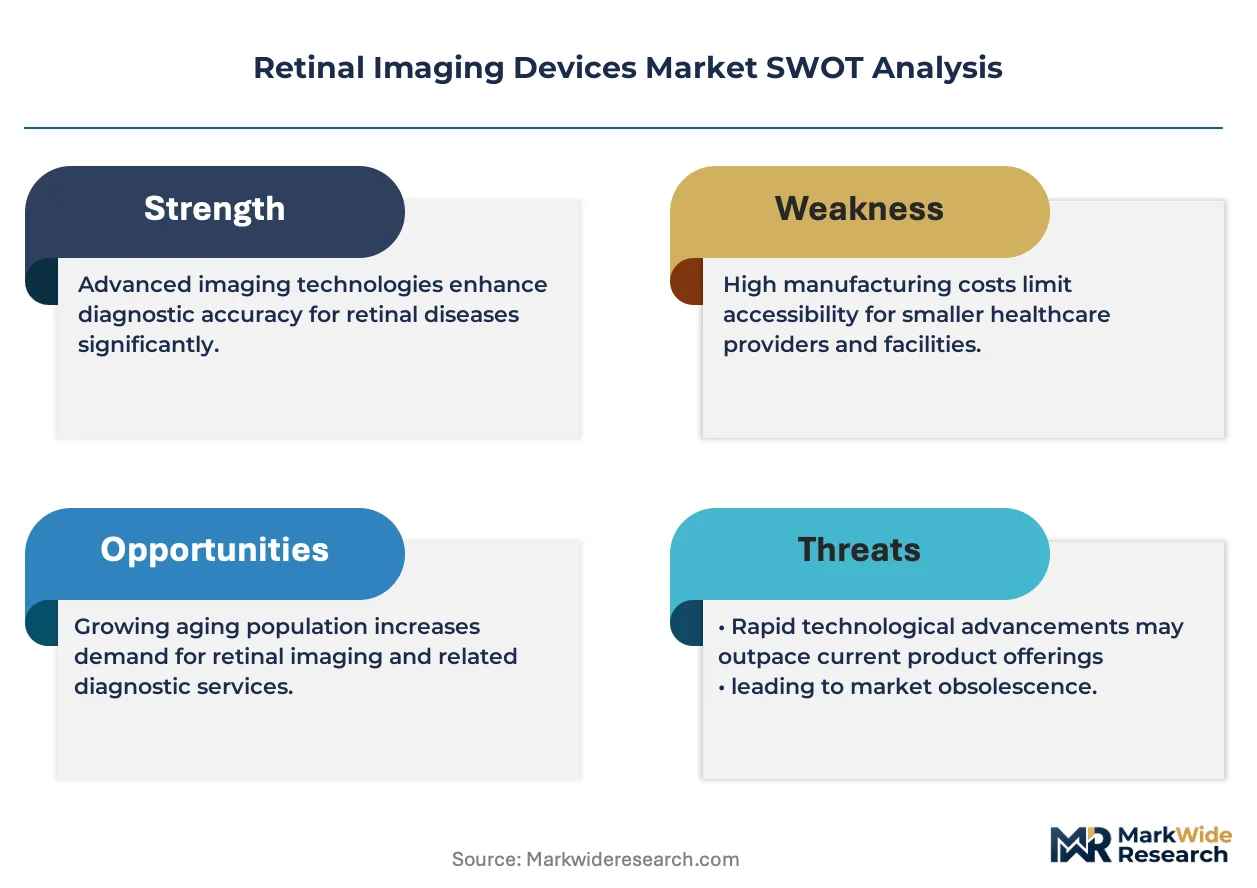
FDA premarket notification requirements and the EU Medical Device Regulation shape product development timelines, with MDR technical documentation demands forcing smaller manufacturers to consolidate regulatory affairs capabilities. The FDA's breakthrough device designation for AI-integrated retinal scanners is accelerating de novo pathway submissions from technology developers. Reimbursement volatility under CMS physician fee schedules and Japan's MHLW medical device pricing reforms create persistent margin uncertainty for capital equipment vendors. Stakeholders must monitor convergence between standalone hardware sales and subscription-based diagnostic software models.
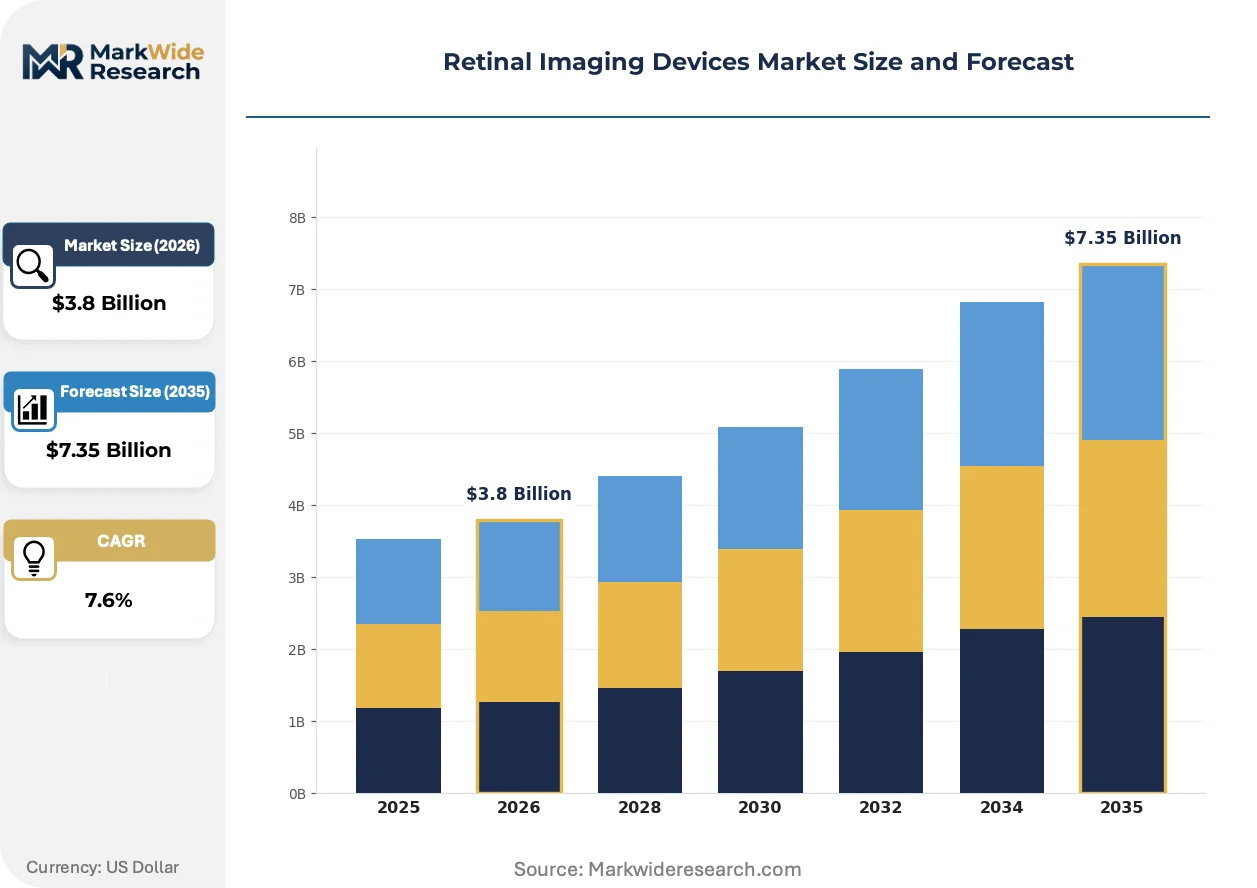
Market Dynamics
The convergence of AI-assisted diagnostic algorithms with spectral-domain OCT hardware is compressing diagnostic timelines and forcing device-software integration as the baseline commercial offering.
Growth Catalysts
- Non-mydriatic screening protocols:Hospital-based ophthalmology departments are adopting pupil-sparing fundus cameras to expand patient throughput without pharmacologic dilation delays.
- FDA breakthrough device designation:The FDA's accelerated pathway for AI-integrated retinal scanners is shortening premarket notification timelines for device-software combinations.
- Preventive reimbursement frameworks:CMS physician fee schedules in the United States, alongside Japan's MHLW pricing structures, now cover routine retinal screening for diabetic populations.
Market Restraints
- EU MDR technical documentation:The Medical Device Regulation's expanded clinical evidence requirements are forcing smaller manufacturers to consolidate regulatory affairs capabilities or exit the European market.
- Optical component supply concentration:High-precision interferometer lenses and near-infrared detectors concentrate among German and Japanese optical foundries, creating single-source vulnerability.
- Widefield imaging substitution:Ultra-widefield fundus systems are cannibalizing standard-field camera placements in hospital networks, compressing average selling prices for legacy platforms.
Strategic Opportunities
- Decentralized eye clinic networks:Community-based diagnostic hubs in the United States and Germany are replacing hospital-centered referral models, opening capital-light placement channels.
- Subscription software monetization:Recurring revenue from OCT analysis algorithms and cloud-based image management is displacing perpetual license sales among academic medical centers.
- AI diagnostic reimbursement expansion:Japan's MHLW is evaluating standalone reimbursement codes for autonomous screening algorithms, potentially validating software-only business models.
Industry Challenges
- OCT engineer scarcity:Spectral-domain system design requires rare expertise in Fourier-domain signal processing and ophthalmic optics, constraining R&D velocity at mid-tier manufacturers.
- Legacy PACS integration:Hospital IT departments face multi-month deployment cycles to connect new retinal imaging platforms to existing picture archiving systems, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Imaging Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundus Cameras, Optical Coherence Tomography, Retinal Scanners, Retinal Cameras Technology: Fluorescein Angiography, Indocyanine Green Angiography, Widefield Imaging, 3D Imaging Application: Diabetic Retinopathy, Age-Related Macular Degeneration, Glaucoma, Retinal Detachment End User: Hospitals, Eye Clinics, Research Institutions, Outpatient Facilities |
| Companies Covered | Optos, Canon Inc., Carl Zeiss Meditec AG, Lumibird Medical, Optomed, Topcon Corporation, Heidelberg Engineering GmbH, Essilor Instruments, NIDEK Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Imaging Devices Market Strategic Shifts
Retinal imaging is transitioning from hardware-centric capital sales to integrated diagnostic platforms where software-enabled functionality determines purchasing decisions and vendor loyalty.
Adaptive optics fundus photography is unifying cellular-resolution imaging with conventional widefield screening in single-platform configurations. Academic medical centers in Germany and Japan are piloting these hybrid systems for research-to-clinic translation. The technology is unifying previously separate capital budgets for basic science and clinical service lines, compressing procurement cycles.
Europe's Medical Device Regulation is mandating post-market surveillance systems and unique device identification for all Class IIa and above ophthalmic instruments. Manufacturers must now maintain clinical follow-up registries for software-upgradable devices across their installed base. The regulation is reshaping product lifecycle management, with Heidelberg and Topcon restructuring European service organizations to capture real-world performance data.
Eye clinics are consolidating diagnostic device procurement under multi-year managed service agreements rather than discrete capital purchases. Independent practice associations in the United States are negotiating fleet-wide OCT and fundus camera placements with single-source vendors. This shift is most visible in Texas and Florida, where private equity-backed ophthalmology platforms are standardizing equipment across 20-plus location networks.
Retinal Imaging Devices Market Segmentation
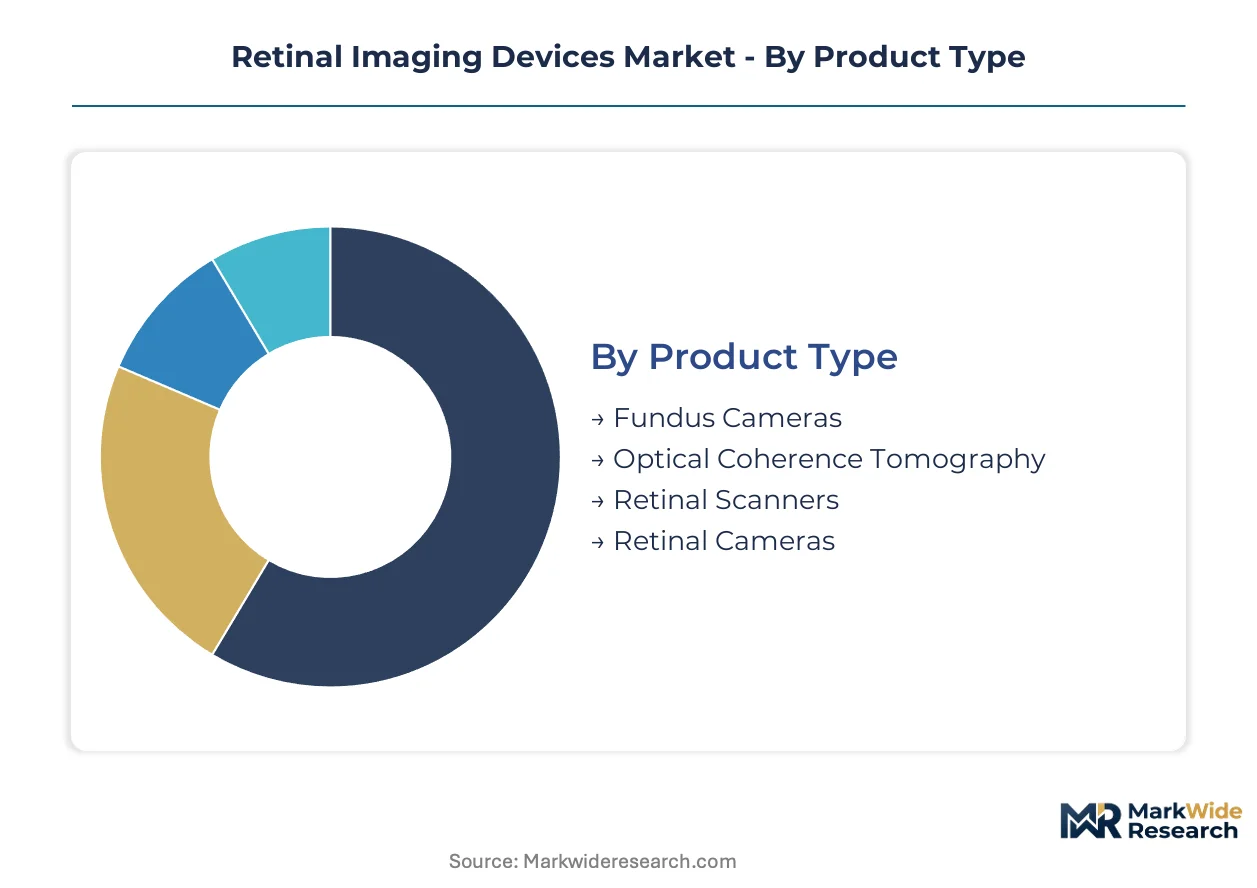
Retinal imaging device purchasing varies sharply by clinical setting and diagnostic purpose. Technology selection hinges on whether providers prioritize screening throughput or subspecialty precision. Reimbursement pathways and capital availability further stratify buying behavior across hospital systems and independent practices.
Product Type:
Capital intensity and software dependency distinguish purchasing priorities across hardware categories.
- Optical Coherence Tomography:Spectral-domain systems generate cross-sectional retinal scans through near-infrared interferometry, requiring recurring software licenses for image analysis. Demand concentrates in academic medical centers across Germany and Japan where research budgets subsidize premium platform acquisition.
- Fundus Cameras:These devices capture 500-600 nanometer wavelength photographs of the posterior pole using either mydriatic or non-mydriatic protocols. Eye clinics in the United States favor pupil-sparing models to eliminate pharmacologic dilation delays and expand daily patient throughput.
- Retinal Scanners:Portable scanning units enable point-of-care deployment in community settings. Texas and Florida private equity-backed ophthalmology networks standardize these across multi-location fleets under managed service agreements.
- Retinal Cameras:Dedicated imaging hardware for high-resolution macular documentation serves secondary screening roles. Research institutions in Japan deploy these for longitudinal disease progression studies requiring consistent image capture protocols.
Volume sits with fundus cameras; growth tilts toward optical coherence tomography.
Technology:
Imaging modality selection tracks disease-specific diagnostic requirements and dye safety protocols.
- Widefield Imaging:Ultra-widefield systems capture up to 200 degrees of the peripheral retina in single exposures using scanning laser ophthalmoscopy. Hospital networks in the United States are displacing standard-field fundus photography for diabetic retinopathy screening programs.
- Fluorescein Angiography:Intravenous sodium fluorescein dye-based vascular imaging remains the reference standard for choroidal neovascularization detection. German academic centers maintain high utilization despite dye allergy risks and procedure complexity.
- 3D Imaging:Volumetric reconstruction algorithms process sequential OCT B-scans into navigable tissue models. Outpatient facilities in Japan adopt these for patient education and surgical planning communication.
- Indocyanine Green Angiography:Near-infrared dye imaging penetrates retinal pigment epithelium to visualize choroidal circulation. Research institutions leverage this for inflammatory chorioretinopathy characterization where fluorescein provides insufficient depth.
Widefield imaging commands the largest installed base; 3D imaging is climbing the fastest.
Application:
Disease prevalence and screening program mandates determine device utilization intensity.
- Diabetic Retinopathy:Systematic screening of diabetic populations drives the highest device utilization rates. CMS reimbursement coverage in the United States and MHLW pricing structures in Japan incentivize preventive imaging protocols.
- Age-Related Macular Degeneration:Neovascular and atrophic form monitoring requires frequent OCT surveillance. German statutory health insurance funds cover quarterly imaging for anti-VEGF therapy monitoring.
- Glaucoma:Retinal nerve fiber layer thickness measurement supports progression tracking. Eye clinics incorporate OCT ganglion cell analysis into comprehensive optic nerve assessment workflows.
- Retinal Detachment:Preoperative peripheral retinal evaluation and postoperative surveillance utilize widefield modalities. Hospital emergency departments deploy portable scanners for trauma-related retinal assessment.
Diabetic retinopathy absorbs the most screening volume; age-related macular degeneration shows the steepest expansion trajectory.
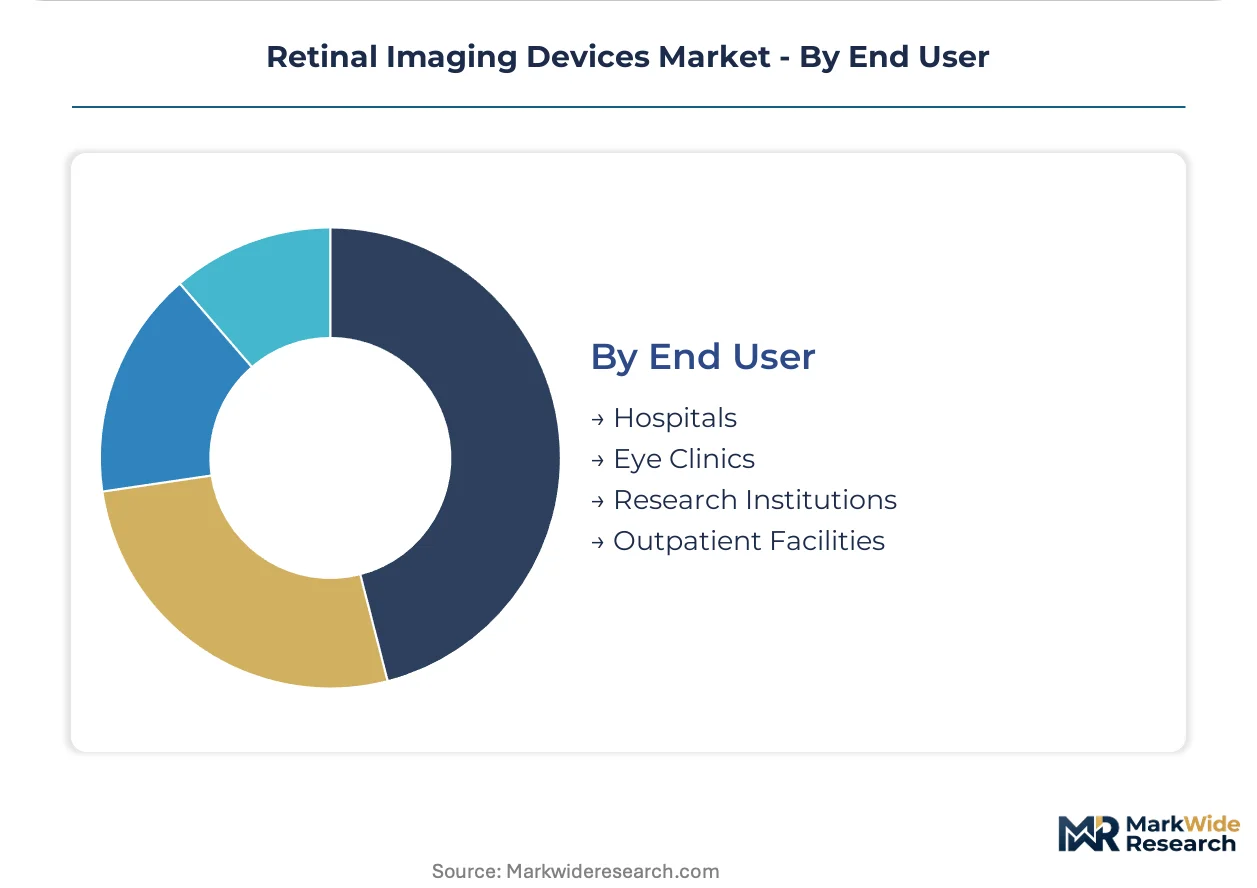
End User:
Capital availability and patient flow models create distinct procurement patterns across care settings.
- Eye Clinics:Decentralized diagnostic hubs reduce patient travel burdens and capture referral volume. Independent practice associations in Texas and Florida negotiate fleet-wide equipment placements under multi-year service contracts.
- Hospitals:Integrated health systems prioritize interoperability with existing PACS infrastructure and electronic health records. FDA breakthrough device designation for AI-integrated scanners accelerates technology refresh cycles.
- Outpatient Facilities:Ambulatory surgery centers require compact platforms for preoperative screening and postoperative monitoring. These settings favor device-software bundles with minimal IT department deployment requirements.
- Research Institutions:Academic medical centers demand adaptive optics capabilities and raw data export functionality. Heidelberg and Topcon restructure European service organizations to capture real-world performance data for regulatory compliance.
Hospital purchasing dominates current volume; eye clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical glass foundries supply the precision interferometer lenses anchoring retinal imaging device manufacturing. Japanese near-infrared detector fabrication concentrates in Nagoya and Osaka industrial corridors. United States reimbursement frameworks and FDA regulatory pathways shape commercialization velocity for device-software combinations.
United States
CMS physician fee schedules now cover routine diabetic retinal screening, expanding hospital ophthalmology department procurement. FDA breakthrough device designation for AI-integrated scanners accelerates premarket notification timelines. Texas and Florida private equity-backed ophthalmology networks standardize equipment across multi-location fleets under managed service agreements.
Germany
Statutory health insurance funds cover quarterly OCT imaging for anti-VEGF therapy monitoring in age-related macular degeneration patients. EU Medical Device Regulation mandates post-market surveillance systems and unique device identification for Class IIa and above ophthalmic instruments. Heidelberg and Topcon restructure European service organizations to capture real-world performance data for regulatory compliance.
Japan
MHLW medical device pricing reforms and preventive screening coverage for diabetic populations drive capital equipment demand. Japan's regulator is evaluating standalone reimbursement codes for autonomous screening algorithms, potentially validating software-only business models. Academic medical centers in Tokyo and Osaka pilot adaptive optics hybrid systems for research-to-clinic translation.
United Kingdom
NHS diabetic eye screening program mandates systematic retinal imaging for diabetic populations, creating institutional procurement volume. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements shapes product development timelines. London and Southeast England hospital networks displace standard-field fundus photography with ultra-widefield systems for screening programs.
India
Rising diabetic prevalence and expanding private ophthalmology chains drive demand for cost-effective screening platforms. CDSCO medical device registration requirements and quality standards shape import and local manufacturing decisions. Maharashtra and Karnataka urban centers concentrate eye clinic networks adopting non-mydriatic fundus cameras to expand patient throughput.
Retinal Imaging Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as device manufacturers integrate AI diagnostic software to meet baseline commercial expectations. The vendor base concentrates among established optical engineering specialists and diversified medical technology conglomerates. Three archetypes define competitive positioning: captive optical manufacturers with in-house lens fabrication, fundus camera platform specialists leveraging installed base relationships, and spectral-domain engineering boutiques serving academic medical centers. M&A activity and technology licensing agreements represent the primary competitive moves as firms acquire Fourier-domain signal processing capabilities and cloud-based image management platforms.
Among German-based optical engineering groups, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify divergent strategic positions. Zeiss anchors the captive manufacturing archetype through controlled supply of precision interferometer components. Heidelberg occupies the spectral-domain boutique tier, sustaining premium positioning among research-intensive academic medical centers. Japanese conglomerate Topcon Corporation represents the platform-leverage archetype, converting fundus camera installed base dominance across Asian and European eye clinics into cross-selling opportunities for advanced diagnostic modalities.
| Leading Market Players |
|---|
| Optos |
| Canon Inc. |
| Carl Zeiss Meditec AG |
| Lumibird Medical |
| Optomed |
| Topcon Corporation |
| Heidelberg Engineering GmbH |
| Essilor Instruments |
| NIDEK Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Private equity-rolled-up ophthalmology platforms in Texas and Florida are consolidating equipment procurement under multi-year managed service agreements, compressing capital equipment margins while shifting vendor pricing power toward recurring software subscriptions and fleet-wide service bundling.
Pricing Analysis
Warranty and service bundling separates premium-tier spectral-domain OCT vendors from unbundled economy-tier fundus camera suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks software dependency, with spectral-domain systems commanding recurring license fees and disposable interface revenues. Cost compression in standard-field fundus cameras intensifies because ultra-widefield systems cannibalize hospital network placements. Independent eye clinics exhibit highest price sensitivity; academic medical centers show lowest sensitivity due to research budget subsidies.
Supply Chain Analysis
Single-source vulnerability sits with German optical glass foundries supplying precision interferometer lenses and Japanese near-infrared detector fabrication concentrated in Nagoya-Osaka corridors. Manufacturing draws from high-precision optical components, Fourier-domain signal processing chipsets, and specialized ophthalmic scanning mechanics. Tariff exposure on Japanese detector imports threatens margin stability for mid-tier assemblers. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-clinic field sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinal imaging is transitioning from hardware-centric capital sales to AI-integrated diagnostic platforms, with spectral-domain OCT and autonomous screening algorithms displacing legacy fundus photography in reimbursement-preferred protocols.
For Market Incumbents: Lock in captive optical manufacturing positions by securing long-term supply agreements with German lens foundries and Japanese detector fabricators. Consolidate regulatory affairs capabilities to navigate EU MDR post-market surveillance mandates without third-party dependency. Defend against AI-native entrants by accelerating FDA breakthrough device submissions for autonomous diagnostic algorithms. For New Entrants and Emerging Players: AI-first diagnostic software without hardware attachment offers the most penetrable entry point into Japan's MHLW reimbursement evaluation for standalone screening codes. Target decentralized eye clinic networks in Texas and Florida where private equity platforms standardize equipment across 20-plus location fleets. Pursue white-label OEM partnerships with established fundus camera manufacturers to bypass capital-intensive optical engineering. For Investors and Strategic Acquirers: FDA breakthrough device designation for AI-integrated retinal scanners is the leading indicator that software-enabled diagnostic platforms will capture disproportionate valuation multiples over pure hardware vendors. Mid-cap spectral-domain engineering boutiques with academic medical center relationships represent priority acquisition archetypes. Watch for MHLW standalone reimbursement code approvals as the signal validating subscription-software business models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket timelines for AI-integrated spectral-domain OCT systems. |
| EU MDR Compliance Investment | Enables continued market access through post-market surveillance infrastructure. |
| Hospital System Partnership | Locks in multi-year managed service agreements with integrated health networks. |
| Software Companion Development | Captures recurring revenue from cloud-based image analysis algorithms. |
| Reimbursement Strategy | Secures CMS and MHLW coverage for preventive diabetic retinopathy screening. |
Study Parameters
FDA 510(k) filings, EU MDR technical documentation databases, and CMS physician fee schedule archives formed the secondary backbone, supplemented by primary interviews with ophthalmology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated device shipment estimates against reimbursement claim volumes and capital expenditure disclosures.
Historical trendline analysis of spectral-domain OCT and fundus camera placements across hospital, eye clinic, and research institution channels established baseline growth patterns. The projection framework modeled technology type, end-user setting, application disease state, and regional regulatory cluster across the analysis window. CAGR derivation incorporated software upgrade cycle frequencies, disposable interface utilization rates, and AI diagnostic reimbursement expansion scenarios.
Several conditions sit outside the modeled scope, including supply chain disruptions from geopolitical conflict, rapid obsolescence of non-AI-integrated hardware, and unanticipated regulatory reclassification of diagnostic software as medical devices. Forecasts reflect assumptions about continued reimbursement favorability for preventive screening and stable optical component supply from German and Japanese sources. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
China Mammography Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market