
 Dental Digital X Ray Market | 2026-2036
Dental Digital X Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Digital X Ray Market Intelligence
A shift from single-vendor lock-in to multi-source procurement for imaging components is restructuring the competitive landscape. Dentsply Sirona leverages its extensive global distribution network to maintain a strong market position. Vatech specializes in advanced imaging technologies, particularly in the Cone Beam Computed Tomography segment, while Carestream Dental competes on the strength of its integrated software and hardware solutions.
Dental digital X-ray systems capture radiographic images using electronic sensors, such as CCD or CMOS, instead of traditional film. These systems provide immediate image visualization for the diagnosis of caries and other oral pathologies. Within product types, Cone Beam Computed Tomography (CBCT) systems represent a high-margin segment, while intraoral sensors see the highest volume. Dental clinics remain the primary end-user, driving purchasing decisions based on workflow integration.
Regulatory compliance is a critical market barrier, with manufacturers navigating requirements from bodies like the US Food and Drug Administration (FDA). In Europe, adherence to the Medical Device Regulation (MDR) and CE marking is mandatory, governing device safety and performance. Future system selection will increasingly hinge on capabilities for AI-driven diagnostics and secure integration with patient management software.
Market Dynamics
The fundamental transition from analog film to digital radiography, driven by demands for lower radiation dosage and improved diagnostic workflow efficiency, is the central force shaping the market. This shift is accelerated by the clinical and financial advantages of advanced modalities like Cone Beam Computed Tomography (CBCT).
Growth Catalysts
- AI-Powered Diagnostics:The integration of artificial intelligence software for automated caries detection and anatomical landmark identification enhances the value of digital radiographs, encouraging system upgrades in dental practices.
- Radiation Safety Regulations:Mandates and guidelines from bodies like the US Food and Drug Administration (FDA) and principles embedded in Europe's Medical Device Regulation (MDR) promote the adoption of low-dose digital systems over higher-exposure film X-rays.
- Dental Infrastructure Modernization:Growing private investment in dental clinics across emerging economies, particularly in Brazil and India, creates consistent demand for new digital imaging equipment as part of facility upgrades.
Market Restraints
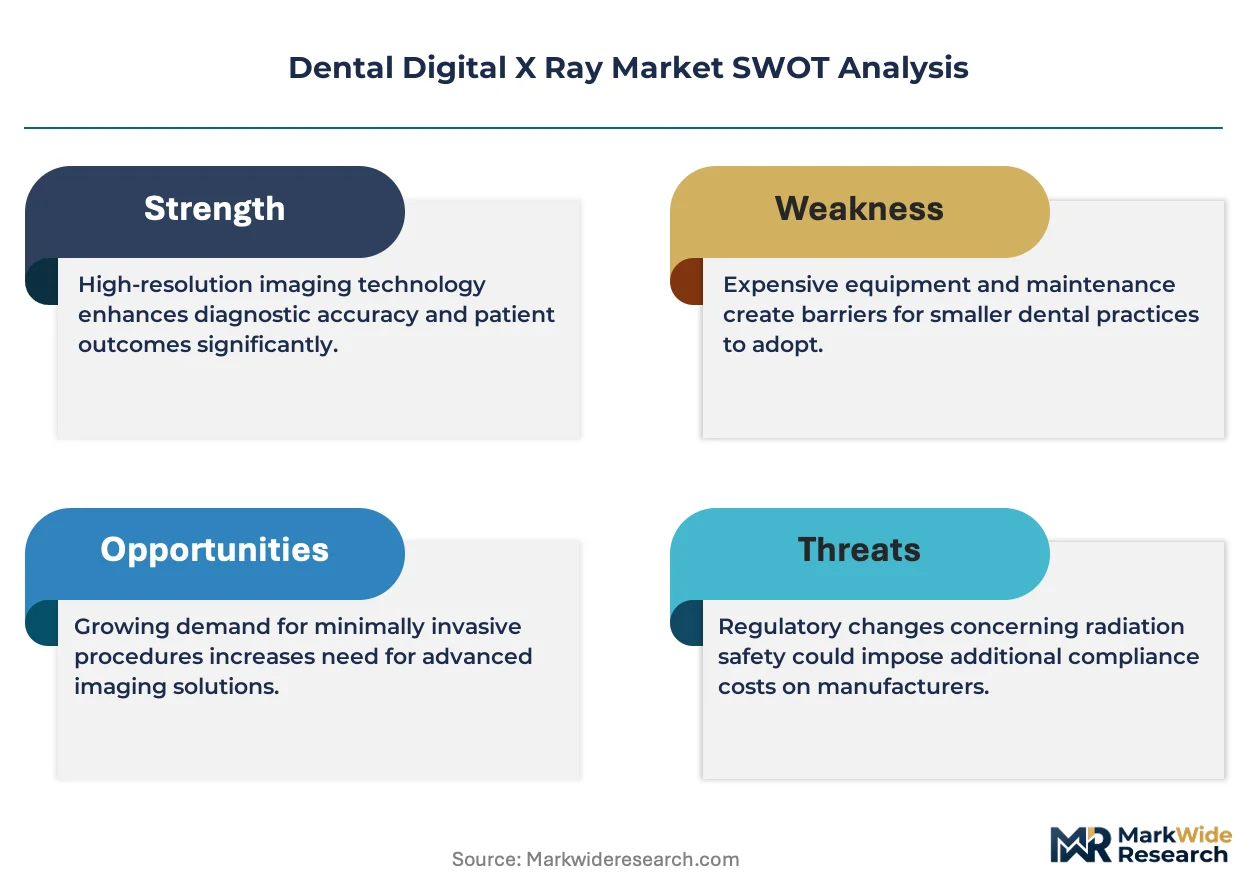
- High Capital Investment:The significant upfront cost of advanced systems, especially 3D CBCT units, remains a substantial barrier for small, independent dental clinics and practices in price-sensitive regions.
- Software Interoperability:A lack of standardization creates persistent compatibility issues between imaging hardware from one vendor and the patient management software from another, leading to fragmented workflows.
- Stringent Regulatory Pathways:The lengthy and resource-intensive process for obtaining market clearance, such as CE marking under the EU's MDR, can delay the introduction of new imaging technologies.
Strategic Opportunities
- Portable and Handheld Devices:Developing lightweight, battery-powered intraoral X-ray units opens new applications in mobile dentistry, teledentistry, and in-office consultations where space is limited.
- Expansion in Underpenetrated Markets:Targeting dental service providers in Southeast Asian nations like Vietnam and Indonesia, where dental care infrastructure is rapidly expanding, presents a major growth vector.
- Specialized Clinical Applications:The increasing use of CBCT imaging for pre-surgical planning in implantology, orthodontics, and endodontics provides an opportunity to develop specialized software and hardware bundles.
Industry Challenges
- Advanced Training Requirements:The effective use of 3D CBCT systems requires specialized training for dentists and radiological technicians to master image acquisition, interpretation, and radiation dose management.
- Data Security and Privacy:Ensuring compliance with patient data protection regulations like HIPAA in the United States and GDPR in Europe presents a continuous challenge, given the large file sizes and sensitive nature of radiographic images.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Digital X Ray Market |
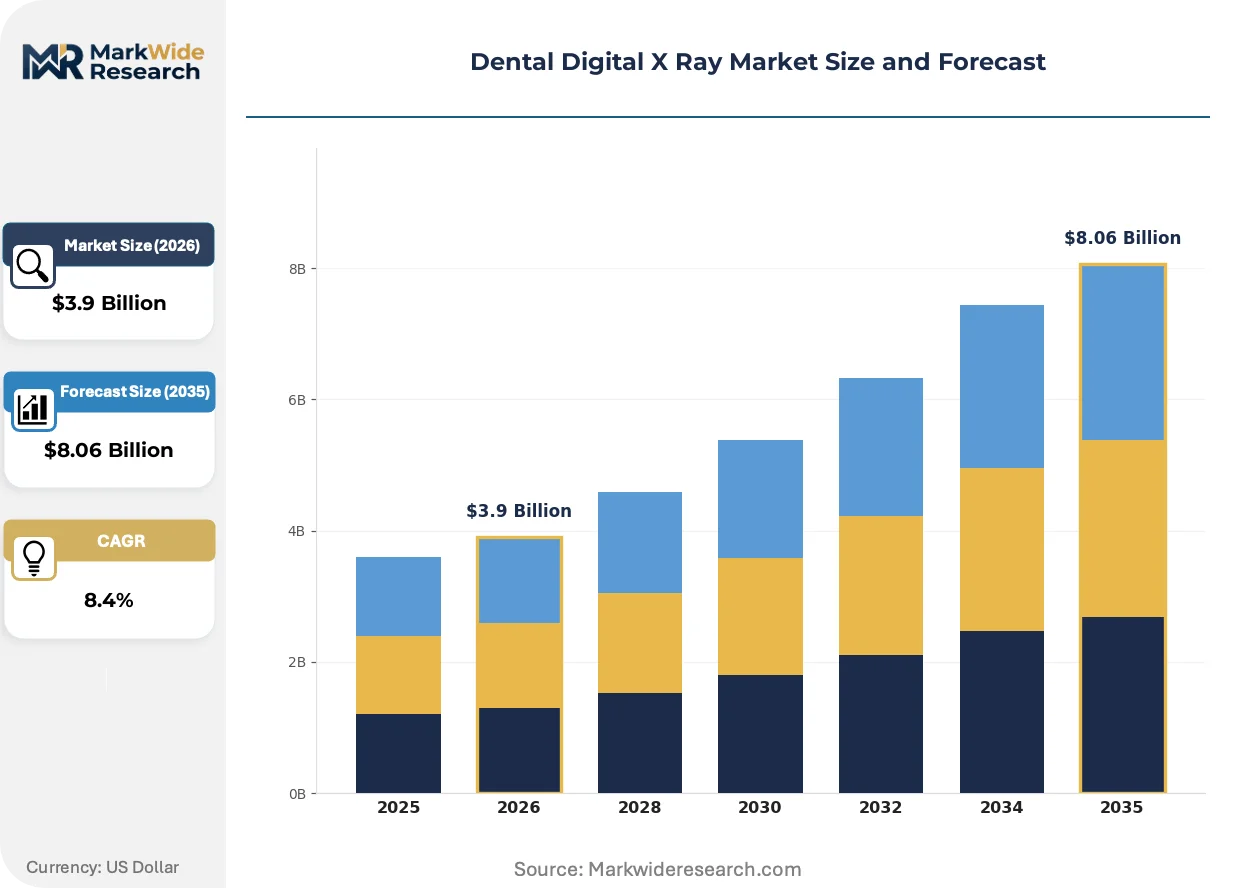
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral X-Ray, Extraoral X-Ray, Cone Beam Computed Tomography, Digital Sensors Technology: Computed Radiography, Direct Digital Radiography, Film-based Systems, Wireless Sensors End User: Dental Clinics, Hospitals, Research Institutions, Academic Institutions Application: Diagnosis, Treatment Planning, Periodontal Assessment, Orthodontic Evaluation |
| Companies Covered | Dentsply Sirona, Planmeca OY, Carestream Dental, Vatech, Envista Holdings Corporation, Acteon, Cefla, Air Techniques, Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Digital X Ray Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of imaging hardware into cohesive digital ecosystems, where artificial intelligence and cloud connectivity enhance diagnostic capabilities. This movement transforms radiographic devices from standalone tools into networked data-gathering nodes within a modern dental practice.
Wireless sensor technology, utilizing CMOS detectors, provides cable-free capture of intraoral radiographic images. Dental clinics and multi-practice organizations are adopting these systems to improve operatory ergonomics, reduce setup time, and enhance patient comfort during examinations. This shift away from tethered hardware is modularizing the dental operatory, allowing for more flexible room layouts and easier equipment sharing between treatment areas.
Europe's Medical Device Regulation (MDR) is elevating the standards for market access. The regulation mandates more rigorous clinical evidence and proactive post-market surveillance for all devices, including digital X-ray systems. Manufacturers of CBCT and panoramic systems are most affected, as they must now generate and maintain more extensive technical documentation on device performance and safety to secure or retain CE marking.
A preference for multi-source component purchasing is altering how large dental groups acquire technology. Instead of committing to a single vendor's closed ecosystem, dental service organizations (DSOs) are increasingly buying sensors, software, and CBCT units from different suppliers to optimize performance and cost. This trend is most prominent in North America and Western Europe, where it pressures vendors to ensure open interoperability.
Dental Digital X Ray Market Segmentation
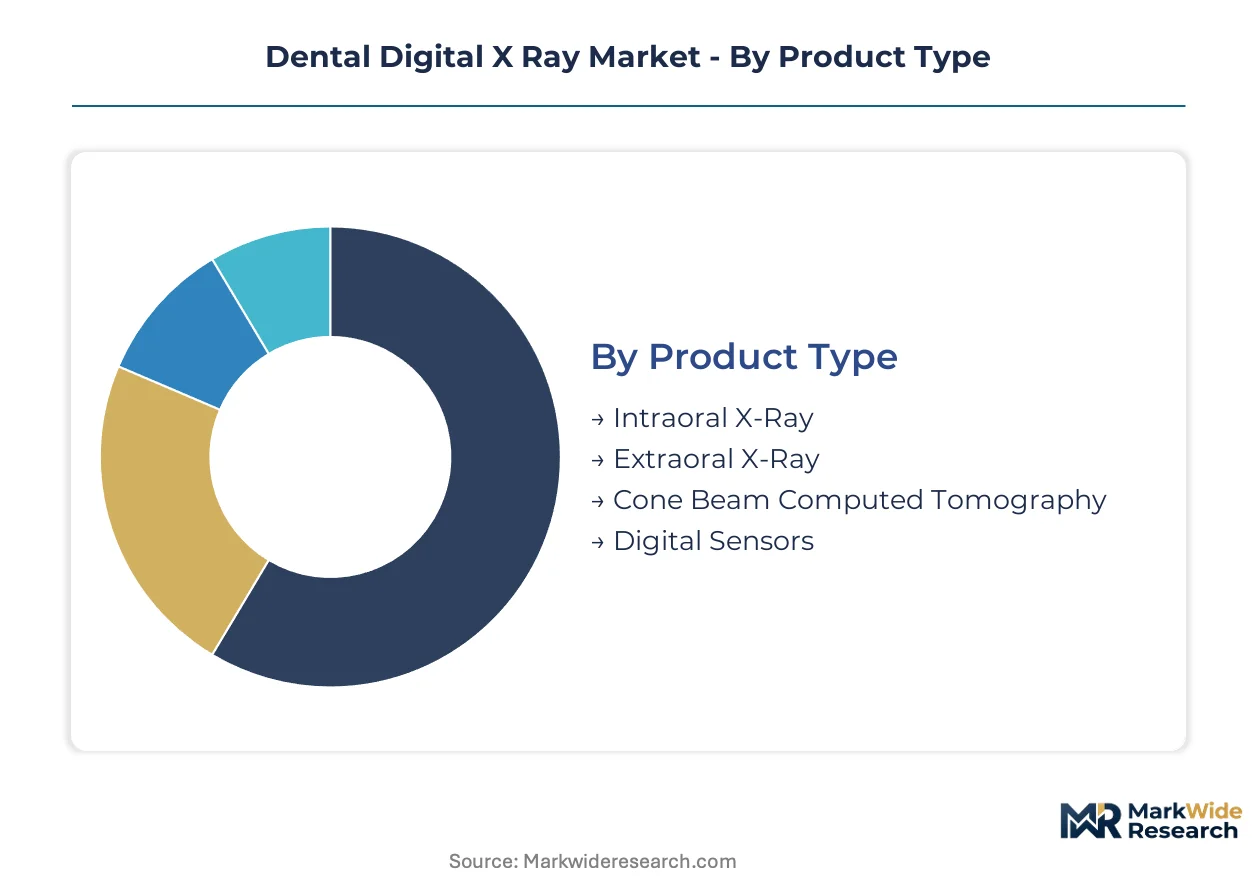
The Dental Digital X Ray Market segmentation provides granular insights into the diverse product offerings and end-user demands shaping industry growth. Understanding these distinct market components helps stakeholders identify specific investment opportunities and tailor product development to critical user needs.
Product Type:
The Product Type segmentation delineates the balance between highly standardized imaging tools and specialized, customizable diagnostic units.
- Cone Beam Computed Tomography:These systems provide high-resolution three-dimensional images of oral and maxillofacial structures. Demand accelerates in implantology and orthodontics due to precise pre-surgical planning requirements, particularly in technologically advanced markets like South Korea.
- Digital Sensors:Electronic detectors (CCD or CMOS) replace traditional film for immediate image capture and display. Demand concentrates in dental clinics across North America for workflow efficiency and reduced patient radiation exposure, driving high-volume adoption.
- Intraoral X-Ray:This category captures images of individual teeth and surrounding bone structures. Intraoral X-ray systems aid in detecting caries and assessing periodontal health.
- Extraoral X-Ray:These systems provide broader views of the jaw, skull, and temporomandibular joints. Orthodontic practices frequently use extraoral X-rays for comprehensive treatment planning.
Most installed capacity flows through Digital Sensors. Expansion is steepest in Cone Beam Computed Tomography.
Technology:
Technology segments reflect varying investment thresholds, ranging from foundational digital solutions to advanced, higher-cost innovations.
- Direct Digital Radiography:This technology employs CCD or CMOS sensors for instant image display and eliminates chemical processing. Dental practices in Europe prioritize these systems for their immediate diagnostic feedback and environmental benefits.
- Wireless Sensors:These devices offer cable-free image acquisition, enhancing patient comfort and operatory flexibility. Demand is growing in multi-chair clinics in Germany, seeking streamlined workflows and improved ergonomics.
- Computed Radiography:This technology uses reusable phosphor plates scanned by a laser to produce digital images. Smaller clinics in Brazil utilize computed radiography as a cost-effective digital transition.
- Film-based Systems:Traditional radiography relies on chemical processing to develop images. These systems are rapidly being phased out due to higher radiation doses and environmental concerns.
Direct Digital Radiography adoption is accelerating, while Film-based Systems face significant displacement.
End User:
End-user categories highlight distinct procurement behaviors, from volume-driven purchases by general practitioners to specialized demands from research facilities.
- Dental Clinics:Independent practices and dental service organizations constitute the largest purchasing segment for digital X-ray systems. Workflow integration and patient throughput drive their investment decisions.
- Hospitals:These facilities utilize digital X-ray systems for complex oral and maxillofacial surgeries and emergency dental care. Hospitals often require advanced CBCT capabilities for comprehensive diagnostic needs.
- Research Institutions:These institutions employ digital X-ray technology for studies on dental materials and diagnostic techniques. Research institutions often require high-resolution imaging for scientific investigation.
- Academic Institutions:These institutions integrate digital X-ray systems into dental education programs for student training. Academic institutions focus on teaching modern diagnostic protocols and imaging interpretation.
The largest volume of procurement originates from Dental Clinics, with specialized requirements from Hospitals.
Application:
Application segments reflect the diagnostic value chain, from routine examinations to high-margin, complex procedural guidance.
- Diagnosis:This fundamental application identifies caries, infections, and structural anomalies in teeth and bone. Diagnosis drives the initial adoption of all digital X-ray systems in general dentistry.
- Treatment Planning:This application guides procedures such as dental implants, root canals, and extractions. CBCT imaging is crucial for precise surgical planning, particularly in implantology across South Korea.
- Periodontal Assessment:This application evaluates bone loss and gum health to detect periodontal disease. Intraoral X-rays are routinely used for monitoring disease progression in patients.
- Orthodontic Evaluation:This application assesses tooth position, jaw alignment, and growth patterns for orthodontic treatment. Extraoral X-rays and CBCT scans provide critical data for complex case analysis.
High-volume applications center on Diagnosis, while Treatment Planning represents a niche with specialized imaging needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technologically advanced healthcare markets like South Korea drive significant demand for digital X-ray systems. This global market sees varied adoption rates influenced by economic development and regulatory frameworks. Investment in dental infrastructure modernization also shapes regional growth trajectories.
South Korea
South Korea's high technological adoption propels demand for advanced Cone Beam Computed Tomography (CBCT) systems in implantology. The Ministry of Food and Drug Safety (MFDS) strictly regulates medical devices, ensuring high standards for imaging equipment. Seoul's dense urban centers feature numerous specialized dental clinics adopting cutting-edge diagnostic tools for precise treatment planning.
United States
United States dental clinics prioritize digital sensors for workflow efficiency and reduced patient radiation exposure. The US Food and Drug Administration (FDA) mandates strict clearance processes for new dental imaging technologies. Major dental service organizations in California increasingly invest in integrated digital solutions for enhanced patient care.
Germany
Germany shows strong demand for wireless sensors and direct digital radiography due to streamlined workflows in multi-chair clinics. Adherence to Europe's Medical Device Regulation (MDR) is critical for market access and device safety. Multi-practice organizations in Bavaria adopt these systems for improved operatory ergonomics and faster image acquisition.
Brazil
Brazil's growing private investment in dental clinics creates consistent demand for new digital imaging equipment as part of facility upgrades. ANVISA, the national health surveillance agency, oversees medical device registration and post-market surveillance. Smaller clinics in São Paulo increasingly utilize computed radiography as a cost-effective digital transition.
India
India's expanding dental care infrastructure in urban areas fuels demand for modern digital X-ray units. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, including digital radiography systems, to ensure product quality. Tier-1 cities like Bangalore are seeing increased adoption of advanced imaging technology in new dental practices.
Dental Digital X Ray Market Key Industry Players
Global majors compete with regional champions across product innovation, technological integration, and distribution network reach. The market structure is moderately fragmented, featuring a blend of large integrated providers and specialized technology developers. Strategic archetypes include comprehensive solution providers, advanced imaging technology specialists, and cost-effective digital system manufacturers. Companies engage in portfolio diversification, strategic partnerships, and geographic expansion to solidify their market positions and capture new growth opportunities.
Within the established tier of market participants, Dentsply Sirona represents a major global player, utilizing its extensive distribution network to reach a broad customer base. Vatech exemplifies a specialized approach, focusing on advanced imaging technologies, particularly within the high-growth Cone Beam Computed Tomography segment. Carestream Dental occupies a position as a provider of integrated solutions, emphasizing the strength of its combined software and hardware offerings for streamlined dental practice workflows. These entities collectively demonstrate the diverse strategic orientations present in the market.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca OY |
| Carestream Dental |
| Vatech |
| Envista Holdings Corporation |
| Acteon |
| Cefla |
| Air Techniques |
| Midmark Corporation |
| Others |
Cost & Logistics Intelligence
Electronic sensor components, critical for digital X-ray systems, flow from specialized manufacturers through assembly lines, influencing the final pricing tiers for dental clinics and hospitals.
Pricing Analysis
Input-cost pass-through significantly affects final product pricing, especially for advanced imaging components. Pricing stratifies across premium, standard, and economy tiers, reflecting system capabilities and brand perception. Price differentiation stems from AI-driven diagnostic capabilities and comprehensive post-sale service agreements. Pricing softness reflects increasing competition from multi-source component procurement, particularly for intraoral sensors. Small, independent dental clinics exhibit the highest price sensitivity, while large hospitals prioritize advanced features over initial cost.
Supply Chain Analysis
Logistics and freight costs for bulky CBCT units and delicate sensors impact regional distribution expenses. Geographic supply concentrates in East Asian nations like South Korea and China for electronic components, alongside European manufacturers for precision optics. Raw material dependencies include specialized CMOS sensors, high-resolution optical lenses, and microprocessors. Single-source vulnerability for advanced imaging processors presents a structural supply chain risk. Distribution runs through a blend of direct sales forces and specialized medical device distributors, particularly for high-value systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a demand-shift toward premium specifications like AI-powered diagnostic integration. Investment in advanced imaging capabilities ensures long-term competitive advantage.
For Market Incumbents: Anchor existing market share by strengthening global distribution networks and investing heavily in integrated software ecosystems. This strategy mitigates the threat of fragmented workflows from interoperability issues. Leverage R&D in AI-driven diagnostics to differentiate offerings and command premium pricing. Expand after-sales support to secure customer loyalty against emerging competitors.
For New Entrants and Emerging Players: Portable and handheld device innovation offers a technology-first wedge into underserved segments like mobile dentistry and teledentistry. Target underpenetrated markets in Southeast Asia, where dental care infrastructure is rapidly expanding. Develop specialized software bundles for niche applications such as implantology pre-surgical planning. Partnerships with dental service organizations (DSOs) provide a rapid go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized technology specialists because fragmented software ecosystems present integration opportunities. Focus on companies with strong intellectual property in AI-powered diagnostic software or wireless sensor technology. The sustained digital transformation of dental practices provides long-term viability for investments. Watch for standardization of data protocols as a key inflection indicator for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-powered diagnostic software | Enhances diagnostic accuracy and workflow efficiency for dental practitioners, driving system upgrades. |
| Expand wireless sensor technology offerings | Improves operatory ergonomics and patient comfort, accelerating adoption in multi-chair clinics. |
| Target underpenetrated markets in Southeast Asia | Captures significant growth from rapidly expanding dental care infrastructure in nations like Vietnam. |
| Develop specialized CBCT software bundles | Addresses precise pre-surgical planning requirements in high-value segments like implantology. |
| Strengthen regulatory compliance capabilities | Ensures market access and mitigates risks associated with stringent requirements like Europe's MDR. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary validation from published reports, and proprietary database analysis — were reconciled to construct a comprehensive market view. This approach ensured a robust understanding of market dynamics through bottom-up and top-down triangulation. Dental practitioners, hospital procurement managers, medical device engineers, and regulatory compliance officers provided critical insights.
The data-stream reconciliation process informed the analytical framework, which models market performance across the analysis window. Segmentation dimensions included product type, technology, end-user, application, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected trends, considering specific industry inputs such as dental clinic upgrade cycles and radiation safety regulatory changes.
The model holds under current base conditions of technological evolution and regulatory stability; deviation in unforeseen technological breakthroughs or shifts in global economic stability would shift forecast trajectories. Forecasts reflect assumptions documented through extensive research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Ultrasound Elastography Systems Market