
 Global Agri Natural Enemy Pest Control Market | 2026-2036
Global Agri Natural Enemy Pest Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agri Natural Enemy Pest Control Market Intelligence
Subscription-based delivery models for beneficial insects and parasitoids is repositioning the market from one-off product sales to continuous, integrated pest management services. Koppert Biological Systems leverages its global distribution network and extensive R&D to support these service models. Biobest Group competes by offering specialized technical support and digital monitoring tools alongside its predator products. Syngenta integrates biocontrol options within its broader crop protection portfolios, creating hybrid solutions for large-scale agriculture.
Agri natural enemy pest control is a biological method using living organisms to suppress harmful insect and mite populations. The primary purpose is to introduce and conserve predators, parasitoids, and pathogens to maintain pest densities below an economic injury level, avoiding synthetic chemicals. Predators and parasitoids lead the product segments due to high efficacy and established use cases. The horticulture and greenhouse application segments command premium value, where targeted releases are most effective and economically justifiable.
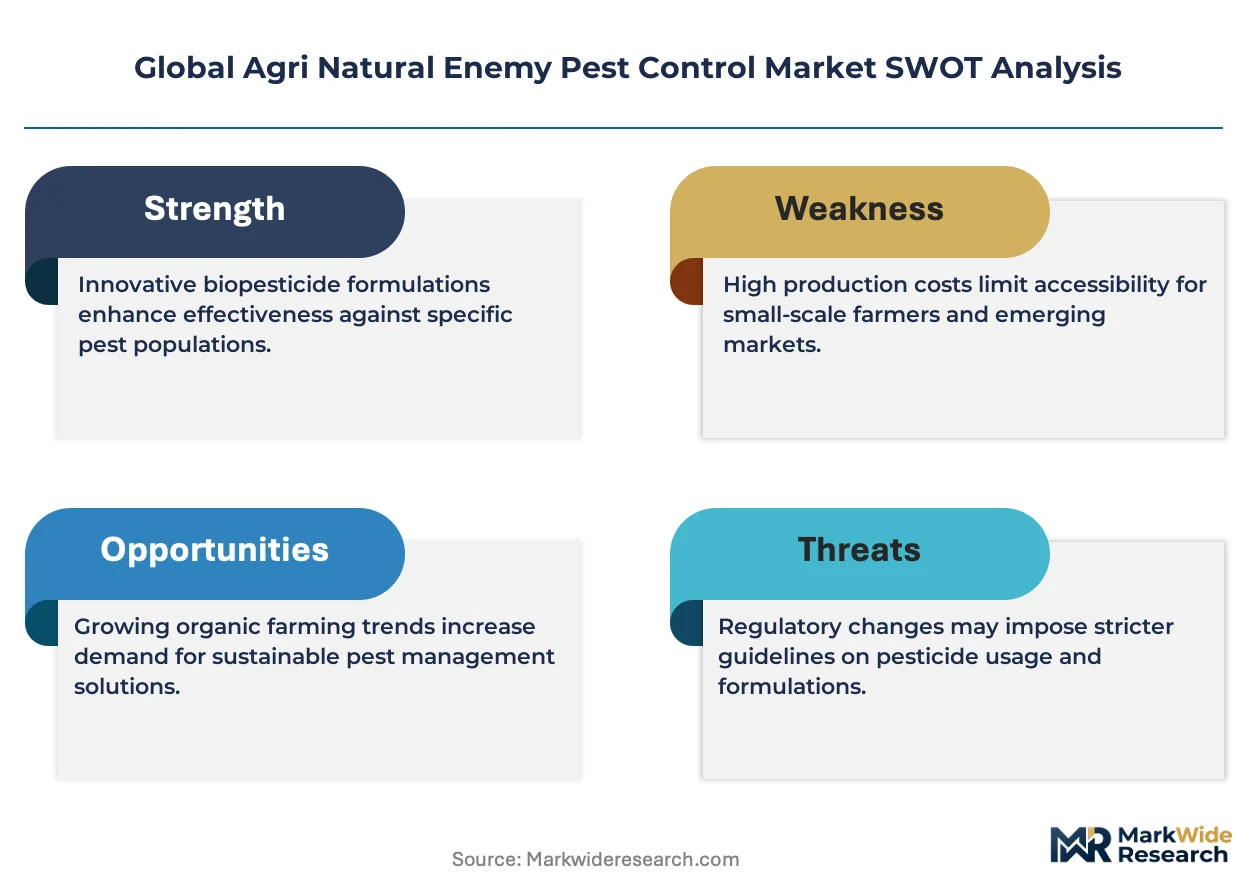
Regulatory bodies such as the US Environmental Protection Agency (EPA) and the European Food Safety Authority (EFSA) set stringent standards for the registration and use of biocontrol agents. These frameworks, alongside China's MEE policies promoting reduced chemical inputs, directly shape market access and product development priorities. Successful commercialization will depend on developing cost-effective, scalable rearing techniques and proving return on investment to conventional growers.
Market Dynamics
The fundamental dynamic shaping the market is the regulatory-driven displacement of synthetic chemical pesticides. Mandates from frameworks like the European Union's Farm to Fork strategy are forcing a structural shift in crop protection, creating a non-discretionary need for biological alternatives.
Growth Catalysts
- EU Regulatory Frameworks:The European Green Deal and its Farm to Fork strategy, which mandate significant reductions in chemical pesticide use, are creating direct market demand for biocontrol agents as compliant alternatives for growers.
- High-Value Horticulture Demand:The horticulture sector, particularly for fruits and vegetables in protected cropping systems, requires residue-free produce, making the targeted application of natural enemies an economically viable and premium-value solution.
- Advances in Rearing Techniques:Innovations in automated, scalable mass-rearing technologies for predators and parasitoids are improving production efficiency, lowering unit costs, and increasing the commercial availability of diverse biocontrol agents.
Market Restraints
- High Upfront Cost:The initial cost of application and the price per hectare for natural enemies can be higher than conventional chemical sprays, posing a significant adoption barrier for growers of large-acreage, lower-margin field crops.
- Product Viability and Shelf Life:As living organisms, biocontrol agents have a short shelf life and require specific storage and transport conditions, creating logistical complexities and risks of efficacy loss that are not present with chemical products.
- Fragmented Regulatory Approval:The lengthy, costly, and inconsistent registration processes for new biocontrol agents across different jurisdictions, such as the EPA in the US and EFSA in Europe, slow down innovation and market access.
Strategic Opportunities
- Expansion in Row Crops:While established in horticulture, there is a large, underpenetrated opportunity in large-scale field crops like corn and soy, particularly as drone technology enables cost-effective, wide-area application.
- Technology Convergence:Integrating biocontrol releases with digital agriculture platforms, including AI-powered pest detection sensors and drone delivery systems, offers a path to create highly precise, automated pest management solutions.
- Service Model Innovation:Shifting from one-off product sales to subscription-based integrated pest management services provides recurring revenue streams and deepens relationships with growers through continuous monitoring and support.
Industry Challenges
- Specialized Knowledge Gap:A primary operational challenge is the lack of widespread grower expertise in integrated pest management principles, which are essential for the successful and effective use of natural enemies compared to simpler chemical applications.
- Cold Chain Logistics:Maintaining a reliable and unbroken cold chain from the rearing facility to the farm is a critical and expensive logistical hurdle necessary to ensure the viability and effectiveness of live predator and parasitoid shipments.
- Quality Control Standardization:Establishing and enforcing industry-wide standards for the quality, purity, and performance of biocontrol agents is a challenge that impacts grower confidence and product consistency across different suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agri Natural Enemy Pest Control Market |
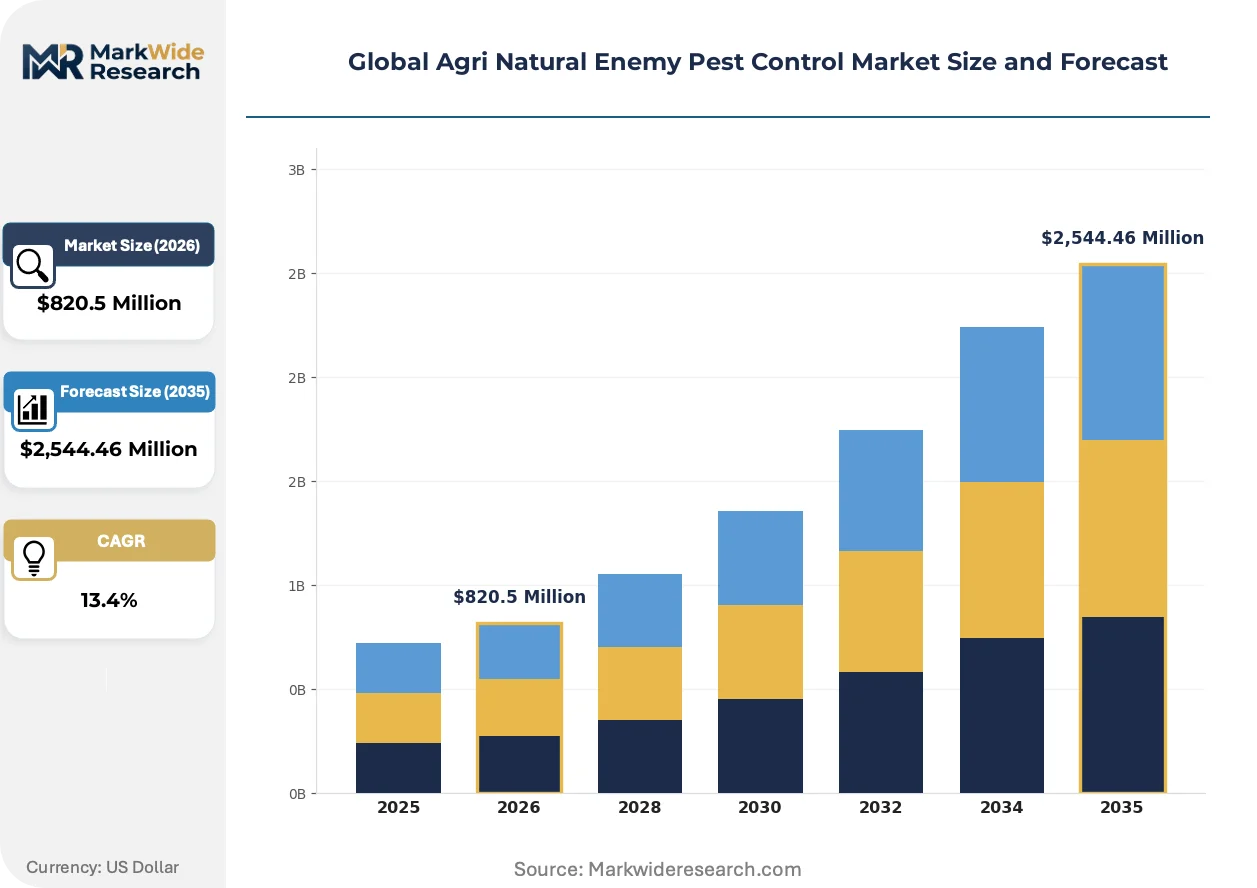
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,544.46 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predators, Parasitoids, Pathogens, Entomopathogenic Nematodes Crop Type: Cereals, Vegetables, Fruits, Pulses Application: Field Crops, Horticulture, Greenhouses, Organic Farming Distribution Channel: Online, Retail, Distributors, Agriculture Cooperatives |
| Companies Covered | Koppert Biological Systems, Biobest Group, Bioline AgroSciences, Andermatt Group, Certis Biologicals, Applied Bio-nomics, Syngenta, BASF, Anatis Bioprotection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agri Natural Enemy Pest Control Market Strategic Shifts & Innovations
The market is pivoting from broad-spectrum treatments toward precise, data-driven biological interventions. This evolution is driven by the convergence of biotechnology with digital agriculture tools, enabling more targeted and effective pest suppression strategies that align with modern sustainability goals.
Digital pest monitoring, which uses in-field sensors and AI-powered image recognition, is a key enabling technology. High-value greenhouse and orchard operations are the earliest adopters, seeking to optimize input costs and prove sustainability. This technology is unifying pest detection, economic threshold calculations, and the precision timing of beneficial organism releases into a single, automated workflow.
China's Ministry of Ecology and Environment (MEE) policies promoting reduced chemical inputs are creating a significant domestic market for biocontrol solutions. These national-level directives incentivize the adoption of green pest management techniques while restricting certain synthetic pesticides. The policy's impact is most pronounced in China's vast fruit and vegetable sectors, which are now accelerating investment in natural enemy programs.
A definitive behavioral shift involves growers moving from transactional product purchases to service-based subscription contracts. This model displaces the traditional one-time sale with a continuous service that includes pest scouting, data analysis, and scheduled releases of natural enemies. This trend is most visible in the advanced greenhouse horticulture markets of the Netherlands and Spain.
Global Agri Natural Enemy Pest Control Market Segmentation
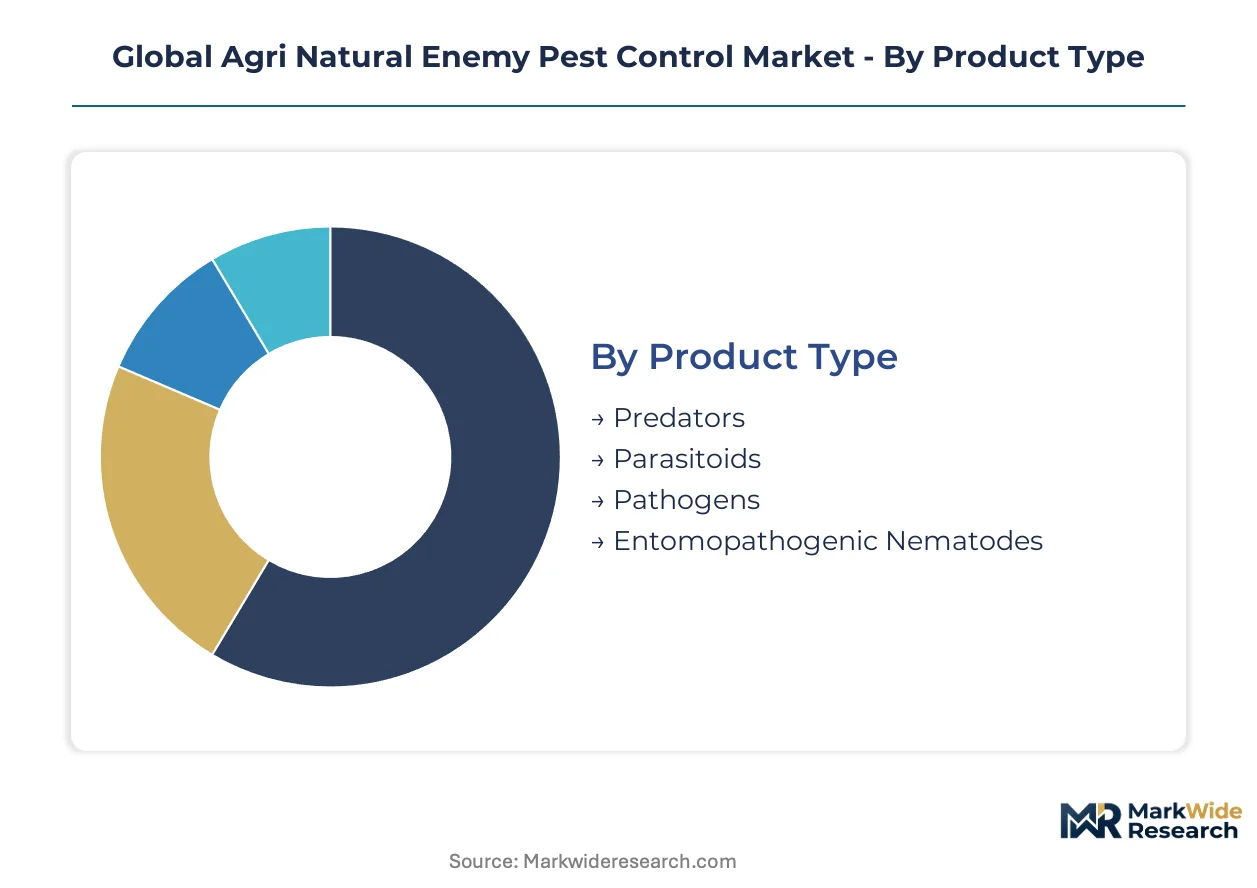
Segmentation provides a structured framework for understanding the diverse applications and underlying demand dynamics within the agri natural enemy pest control market. Analyzing distinct segments reveals specific growth drivers, adoption patterns, and technological requirements across various agricultural practices.
Product Type:
Buyers in the agri natural enemy pest control market differentiate their purchases based on the biological mechanism of action and the target pest spectrum. This distinction is crucial for effective integrated pest management strategies.
- Predators:These biological agents actively hunt and consume pest insects and mites, providing immediate and visible pest reduction. Demand concentrates in high-value horticulture and protected cropping systems across the Netherlands and Spain, driven by the need for quick pest suppression.
- Parasitoids:Parasitoids lay their eggs inside or on host pests, with the developing larvae eventually killing the host, offering a more sustained and long-term control mechanism. Protected agriculture in regions like California and China increasingly adopts parasitoids for their precision and efficacy against specific pest species.
- Pathogens:This segment includes fungi, bacteria, and viruses that infect and kill pests, offering broad-spectrum control in various environments.
- Entomopathogenic Nematodes:These microscopic worms seek out and infect insect pests in the soil, providing effective control for root-feeding insects and some foliar pests.
Predators lead volumes today; Entomopathogenic Nematodes are gaining share fastest.
Crop Type:
The economic margin of different crop types dictates the viability of natural enemy pest control solutions and influences investment in biological alternatives. High-value crops can absorb the initial costs more readily.
- Fruits:Fruit cultivation, particularly in regions like France and Italy, demands residue-free produce for export and consumer safety, making natural enemy pest control a premium solution. Regulatory pressures from the European Union's Farm to Fork strategy further accelerate adoption in these high-value crops.
- Vegetables:Protected vegetable cultivation in countries such as Germany and the United Kingdom relies heavily on biological control to maintain yield quality and meet stringent market standards. Targeted releases of natural enemies are economically justifiable in these intensive production systems.
- Cereals:Large-acreage cereal crops like wheat and corn in the United States face cost-efficiency challenges, limiting widespread adoption of biological control compared to conventional chemical sprays.
- Pulses:Pulse crops, including lentils and chickpeas, represent an emerging opportunity for natural enemy pest control as growers seek sustainable alternatives in regions like Canada and Australia.
High-value crops like fruits and vegetables demonstrate the highest adoption rates for natural enemy pest control.
Application:
The operational environment where pest control is applied significantly influences the selection and efficacy of natural enemy solutions, from open fields to controlled greenhouses.
- Horticulture:This application segment encompasses high-value fruits, vegetables, and ornamental plants, where targeted biological control minimizes chemical residues and enhances product quality. Horticulture operations in Spain and the Netherlands are early adopters of these advanced solutions.
- Greenhouses:Controlled greenhouse environments offer ideal conditions for precise application and establishment of natural enemies, leading to highly effective and economically justifiable pest management. Growers in North America and Japan increasingly leverage biocontrol in these protected settings.
- Field Crops:Large-scale field crops present logistical challenges for natural enemy application, but drone technology is creating new avenues for cost-effective, wide-area deployment.
- Organic Farming:Organic certification mandates the avoidance of synthetic pesticides, making natural enemy pest control an essential and foundational component of pest management strategies.
Greenhouse applications demand precise biocontrol strategies, while field crops represent a significant growth opportunity.
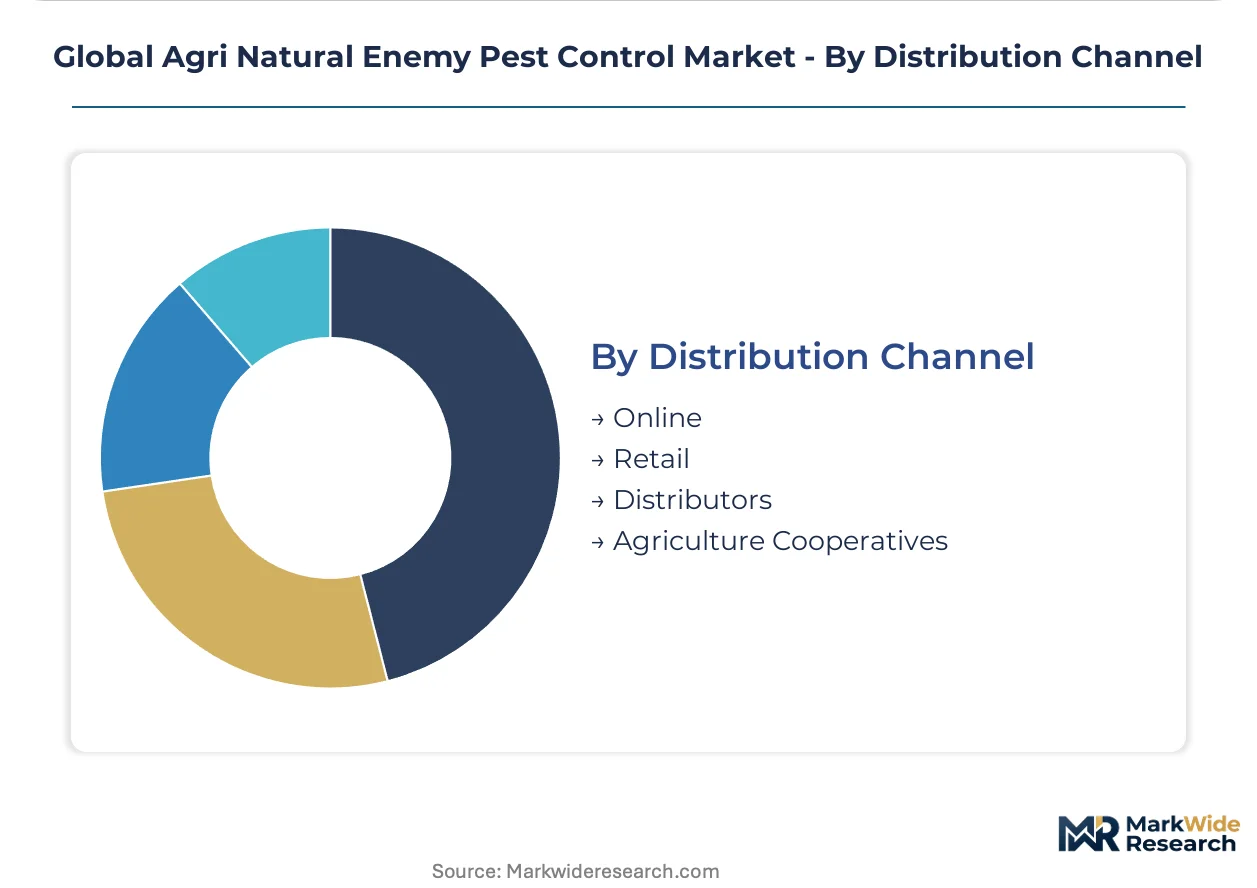
Distribution Channel:
The pathways through which agri natural enemies reach growers determine market reach and logistical efficiency, impacting product viability and accessibility.
- Distributors:Specialized distributors with cold chain logistics and technical expertise are critical for delivering live biological agents from rearing facilities to growers globally. Companies like Koppert Biological Systems utilize extensive distribution networks to reach diverse agricultural markets.
- Agriculture Cooperatives:Farmer cooperatives facilitate collective purchasing and knowledge sharing, enabling smaller growers to access and effectively utilize natural enemy pest control solutions. These cooperatives are particularly impactful in regions with fragmented land ownership, such as Italy.
- Online:The online channel offers direct access for smaller-scale growers and hobbyists, providing convenience for ordering and delivery of biocontrol agents.
- Retail:Retail outlets, including agricultural supply stores, serve as local points of sale for readily available natural enemy products, particularly for common garden and small farm applications.
Specialized distributors and cooperatives facilitate the complex logistics required for live biological agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the Netherlands showcases advanced adoption in protected horticulture, China's vast agricultural sector is rapidly integrating biocontrol solutions driven by national policies. These diverse regional approaches highlight the global shift towards sustainable pest management. Regulatory pressures and consumer demand for residue-free produce are shaping market dynamics across continents.
Netherlands
The Netherlands exhibits high adoption rates for natural enemies in its sophisticated greenhouse horticulture sector. The European Union's Farm to Fork strategy mandates significant chemical pesticide reductions, directly boosting demand for biological alternatives. The Westland region, a hub for advanced greenhouse technology, actively integrates biocontrol agents.
China
China's Ministry of Ecology and Environment (MEE) policies promoting reduced chemical inputs create a robust domestic market for biocontrol solutions. These national directives incentivize green pest management techniques across its vast agricultural lands. Shandong province, with its intensive fruit and vegetable production, accelerates investment in natural enemy programs.
United States
Growing consumer demand for residue-free produce drives natural enemy use in the United States, particularly in organic farming. The USDA's National Organic Program standards necessitate biological pest control methods, avoiding synthetic chemicals. California's high-value specialty crop regions, like the Central Valley, actively implement integrated pest management strategies.
France
Fruit cultivation in France, especially for export markets, increasingly relies on natural enemy pest control to meet stringent residue limits. The European Green Deal provides a strong regulatory impetus for growers to transition from chemical dependency. The Loire Valley, known for its vineyards and fruit orchards, integrates biocontrol options for product quality.
Australia
Australia's agricultural sector, including pulse crops, explores natural enemy solutions for sustainable pest management. National biosecurity regulations and initiatives to reduce pesticide use encourage biological controls. Queensland's horticulture industry actively engages in research and development for native biocontrol agents suitable for diverse crops.
Global Agri Natural Enemy Pest Control Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting diverse market needs and operational scales. The market structure exhibits a dynamic mix of large, diversified crop protection companies and specialized biological solution providers. Strategic archetypes include integrated pest management service providers focused on continuous support, alongside mass producers of specific biocontrol agents. Geographic expansion, strategic partnerships, and technology convergence are dominant competitive moves shaping the industry landscape.
Specialists in integrated pest management solutions, such as Koppert Biological Systems, leverage extensive global distribution networks to support continuous service models and R&D efforts. Biobest Group occupies a distinct position by offering specialized technical support and digital monitoring tools alongside its predator and parasitoid products. Syngenta, a larger player, integrates biocontrol options within its broader crop protection portfolios, creating hybrid solutions that appeal to large-scale agriculture seeking comprehensive pest management.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| Biobest Group |
| Bioline AgroSciences |
| Andermatt Group |
| Certis Biologicals |
| Applied Bio-nomics |
| Syngenta |
| BASF |
| Anatis Bioprotection |
| Others |
Cost & Logistics Intelligence
High-value horticulture's premium pricing for natural enemies contrasts sharply with the cost-sensitive field crop segment. This divergence influences both product formulation and distribution network design.
Pricing Analysis
Capacity additions in European production hubs are reshaping price floors for common natural enemies. The market operates on a hybrid pricing model, combining subscription-based integrated pest management services with per-unit transactional sales for specialized agents. Price differentiation stems from product efficacy, specialized technical support, and digital monitoring integration. Pricing pressure stems from the high upfront costs for large-acreage field crops. Field crop growers exhibit high price sensitivity, while high-value horticulture and greenhouse operators are less sensitive to initial outlays.
Supply Chain Analysis
Specialized distributor networks manage the complex logistics required for live biological agents. Supply concentration centers in countries like the Netherlands, Spain, and China, where advanced rearing facilities operate. Production relies on consistent availability of specific host insects and specialized rearing media. A primary supply chain risk is maintaining an unbroken cold chain, critical for the short shelf life and viability of living organisms. Agricultural cooperatives also facilitate distribution, particularly for smaller growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agri natural enemy pest control market represents a stable compounder, driven by non-discretionary regulatory mandates for chemical pesticide reduction. This structural shift ensures continuous, long-term demand for biological alternatives.
For Market Incumbents: Cement market leadership by investing in automated, scalable mass-rearing techniques to lower unit costs. Expand digital monitoring tools and technical support services to deepen grower relationships, countering the threat of new entrants offering specialized solutions. Strategic R&D into novel biocontrol agents and drone application methods provides a critical lever for sustained growth.
For New Entrants and Emerging Players: Capture underpenetrated segments by developing cost-effective biocontrol solutions for large-acreage field crops. Focus on specific pest challenges in regions like the US Midwest or South America, leveraging drone technology for wide-area application. A compelling go-to-market angle involves proving clear return on investment to conventional growers, emphasizing yield protection and regulatory compliance.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized cold chain logistics and R&D capabilities create barriers to entry. The market offers excellent long-term viability, driven by sustained regulatory and consumer demand for residue-free produce. Target acquisition archetypes include specialized biological solution providers with robust R&D pipelines or unique distribution networks. The signal to watch is the successful commercialization of cost-effective biocontrols for major field crops.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Mass Rearing | Improves production efficiency and lowers unit costs for diverse biocontrol agents. |
| Digital Integration | Connects pest detection sensors with precision timing for beneficial organism releases. |
| Cold Chain Optimization | Ensures viability and effectiveness of live predator and parasitoid shipments to farms. |
| Field Crop Expansion | Unlocks significant underpenetrated market opportunities in large-scale agriculture. |
| Service Model Shift | Transitions from one-off sales to recurring revenue through continuous IPM support. |
Research Approach
Direct dialogue with biocontrol manufacturers, agricultural distributors, farm managers, and regulatory officials formed the primary research. This qualitative insight was validated through secondary sources including EFSA reports, EPA guidelines, China's MEE policies, and specialized academic journals. Bottom-up data collection from production hubs and top-down market analysis provided comprehensive triangulation.
A bottom-up analytical lens, cross-referenced with top-down market sizing, defined the forecast framework across the analysis window. Segmentation dimensions modeled included product type, crop type, application, distribution channel, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data analysis, expert interviews, and projected regulatory impacts. Pesticide use reduction mandates served as a key industry-specific forecast input.
Regulatory shifts, technological breakthroughs in rearing, and grower adoption rate changes are the dominant revision risks. Forecasts reflect assumptions regarding market dynamics and policy trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Global Agricultural Inoculant Market