
 Humic-Based Biostimulants Market | 2026-2036
Humic-Based Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Humic-Based Biostimulants Market Outlook
The EU Green Deal is pivoting agricultural input procurement toward soil health certification. Valagro SpA leverages Mediterranean distribution networks to sustain premium positioning in liquid formulations. Koppert anchors biological input portfolios with humic acid compatibility across integrated crop management programs.
Humic-based biostimulants comprise organic compounds derived from decomposed plant matter, primarily humic and fulvic acids with molecular weights ranging from hundreds to tens of thousands of daltons, functioning to chelate minerals and enhance root membrane permeability for nutrient assimilation. Liquid formulations dominate commercial volumes due to ease of fertigation integration and foliar application compatibility, while granular products occupy price-sensitive broadacre segments where soil incorporation prevails. Farmers represent the core end-user channel, though agricultural retailers increasingly control technical advisory and bundling decisions that influence brand selection.
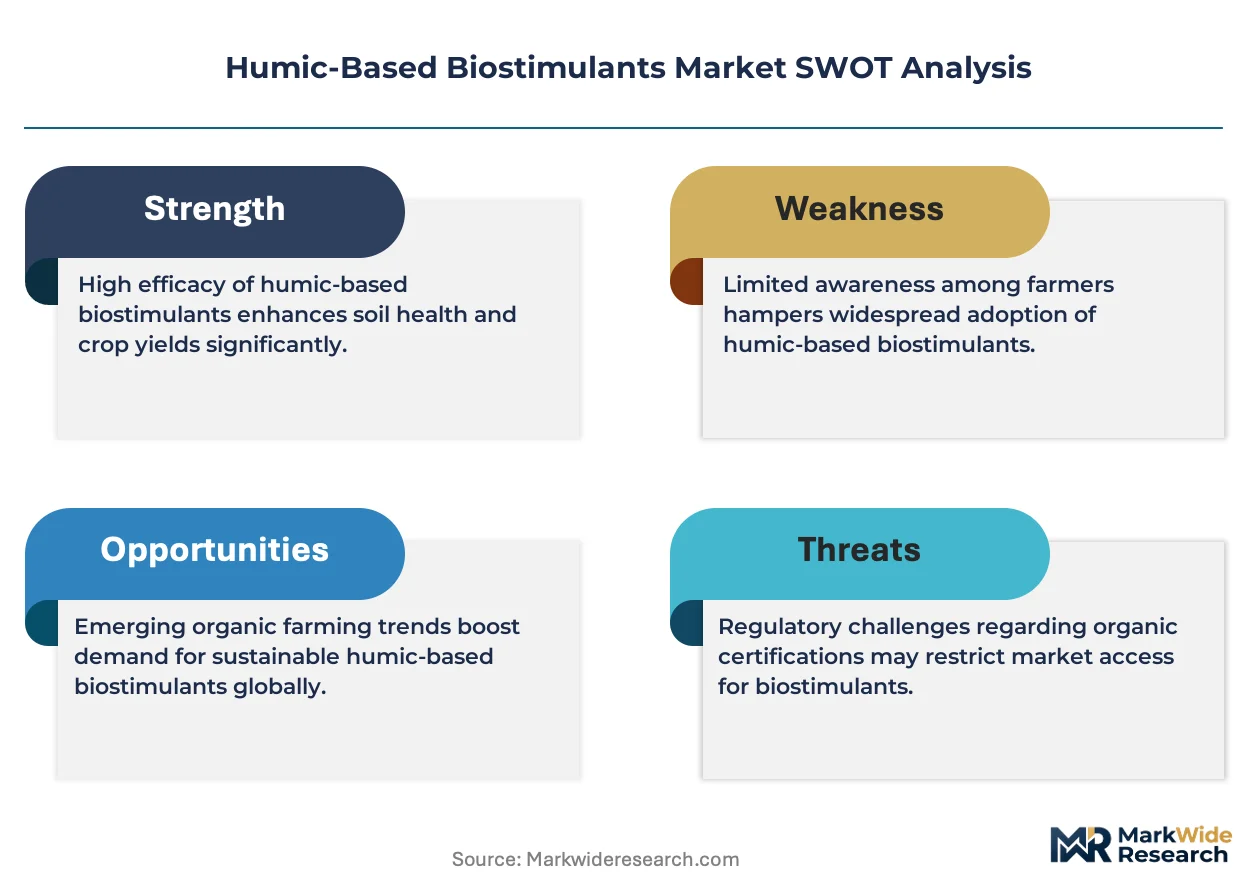
EU REACH registration requirements and the EU Fertilising Products Regulation shape product composition standards and market access conditions for humic substance manufacturers. The EPA in the United States maintains distinct biostimulant oversight pathways that create divergent compliance architectures across Atlantic trade corridors. Stakeholders must monitor regulatory harmonization progress between EU fertilizing product standards and emerging national frameworks in Brazil and India.
Market Dynamics
EU Fertilising Products Regulation enforcement is compressing formulation tolerances and forcing manufacturers toward standardized humic acid extraction protocols that satisfy cross-border certification requirements.
Growth Catalysts
- EU Green Deal soil health mandates:Member states must restore degraded agricultural land, directing public procurement toward biostimulant-qualified suppliers. Spain and Italy lead implementation through regional farm advisory programs.
- Fertigation infrastructure expansion:Drip irrigation networks in water-stressed horticulture zones integrate liquid humic products as standard protocol. Almond and tomato growers in Murcia adopt scheduled humic dosing through automated systems.
- Biological input compatibility requirements:Integrated crop management programs demand humic formulations that pair with microbial inoculants. Koppert and biological input distributors specify humic acid stability in tank-mix protocols.
Market Restraints
- Peat and leonardite supply concentration:Premium humic feedstock deposits cluster in specific mining districts. North Dakota and New Mexico supply chains face extraction permit delays and transport cost volatility.
- REACH registration cost burden:Full substance dossier preparation for EU market access demands six-figure euro investments. Small extraction facilities in Eastern Europe defer registration, ceding shelf space to compliant competitors.
- Synthetic chelate substitution:EDTA and DTPA mineral chelators maintain cost advantages in broadacre grain production. Price-sensitive wheat and corn operations in the US Corn Belt resist humic premium positioning.
Strategic Opportunities
- India PLI scheme for organic fertilizers:Production-linked incentives for biofertilizer manufacturing extend to humic acid blending facilities. Domestic extraction from lignite deposits in Tamil Nadu and Gujarat gains policy support.
- Carbon farming credit stacking:Soil organic carbon measurement protocols under developing national frameworks reward humic application. Australian Emissions Reduction Fund methodology revisions may qualify humic-treated hectares.
- Drone-based foliar application:Unmanned aerial systems enable precision humic dosing in irregular vineyard and orchard topography. Service providers in Champagne and Napa Valley pilot subscription spraying models.
Industry Challenges
- Carbon-14 dating verification bottlenecks:Biobased content certification for EU fertilizing product claims requires specialized laboratory capacity. Accredited testing facilities in the Netherlands and Germany report twelve-week turnaround delays.
- Application rate standardization gaps:Crop-specific dosage protocols vary across Mediterranean advisory networks. Conflicting recommendations from Italian and Spanish extension services confuse grower decision-making.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humic-Based Biostimulants Market |
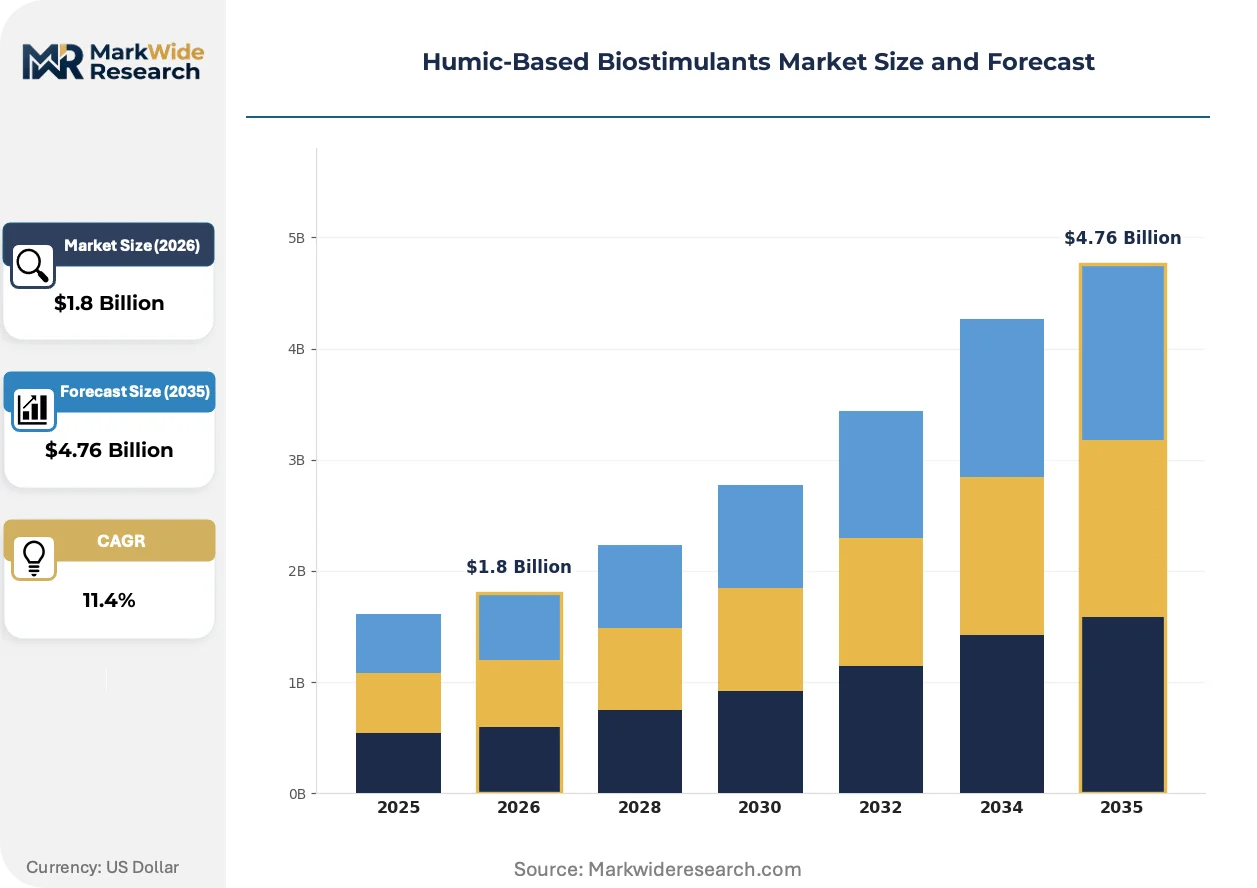
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powdered, Pellet Application: Agricultural Crops, Horticultural Crops, Turf, Ornamental Plants End User: Farmers, Agricultural Retailers, Distributors, Research Institutions Functionality: Nutrient Uptake, Soil Health, Stress Resistance, Growth Promotion |
| Companies Covered | FMC Corporation, Valagro SpA, Biolchim S.p.A, Koppert, Haifa Group, UPL Ltd., Bayer AG, HUMINTECH GMBH, BORREGAARD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humic-Based Biostimulants Market Strategic Shifts
Extraction technology refinement and regulatory measurement protocols are compressing product differentiation windows while elevating transparency requirements across Mediterranean and North American supply corridors.
Advanced oxidation processes for humic acid fractionation are absorbing capital allocation from traditional alkaline extraction methods. Spanish formulation specialists in Valencia deploy membrane filtration systems that isolate low-molecular-weight fulvic fractions for high-value specialty crop applications. This technology is absorbing price premiums previously captured by imported Canadian peat derivatives.
EU Fertilising Products Regulation harmonized standards for organic carbon determination enter full enforcement for new product registrations. Manufacturers must submit third-party validated biobased content declarations alongside heavy metal contaminant profiles. Liquid formulation suppliers serving Italian horticulture cooperatives accelerate laboratory certification investments to maintain market access.
Retailer-controlled technical advisory is displacing independent agronomist relationships in Mediterranean procurement channels. Agricultural cooperatives in Almeria and Sicily consolidate purchasing through distribution networks that bundle biostimulants with crop protection products. This concentration is most visible in Spanish greenhouse vegetable operations where three distributor groups control seventy percent of input recommendations.
Humic-Based Biostimulants Market Segmentation
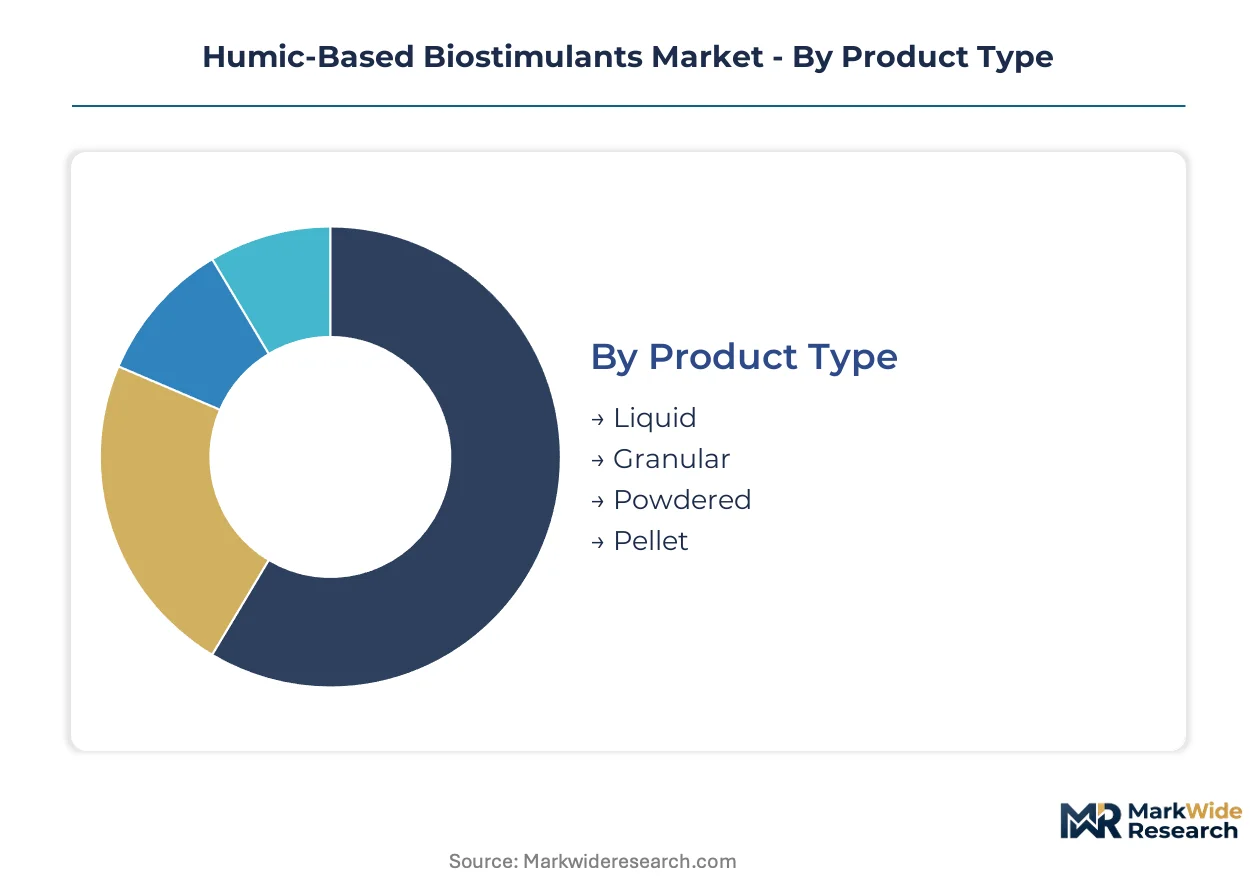
Product differentiation in humic-based biostimulants hinges on formulation compatibility with existing farm infrastructure. Application method determines upgrade cycles for growers integrating biostimulants into precision agriculture systems.
Product Type:
Replacement cycles vary sharply across formulation categories, with fertigation infrastructure driving faster upgrade adoption in liquid formats while granular products follow slower soil amendment schedules.
- Liquid:Aqueous suspensions of humic and fulvic acids enable drip irrigation integration and foliar spraying. Spanish greenhouse operators in Almeria deploy automated dosing systems that schedule weekly humic applications alongside nitrogen feeds.
- Granular:Compressed humic matter blended with mineral carriers for broadcast spreading. US Corn Belt wheat farmers apply granular formulations during pre-plant tillage where soil incorporation replaces fertigation infrastructure.
- Powdered:Fine-ground leonardite derivatives requiring dissolution before field application.
- Pellet:Extruded humic compounds for mechanical spreading equipment compatibility.
Liquid sits at the top of the volume ranking, with Pellet climbing the fastest as orchard growers seek precision placement alternatives.
Application:
Cost tier differentiation separates high-value specialty crop applications from commodity grain segments where price sensitivity constrains formulation premiums.
- Horticultural Crops:Intensive vegetable and fruit production commands concentrated humic dosing protocols. Italian tomato cooperatives in Sicily apply liquid fulvic fractions through fertigation to meet EU Green Deal soil organic carbon benchmarks.
- Agricultural Crops:Broadacre cereal and oilseed operations deploy lower-concentration applications. Australian wheat growers in Western Australia trial humic-treated hectares for carbon farming credit qualification under Emissions Reduction Fund methodologies.
- Turf:Golf course and sports field maintenance programs.
- Ornamental Plants:Nursery and landscape sector applications.
Horticultural Crops captures the highest margin tier, with Turf gaining share fastest as municipal water restrictions elevate soil amendment priorities.
End User:
Customer concentration patterns concentrate procurement influence through distributor networks that bundle biostimulants with crop protection inputs.
- Farmers:Direct purchasers managing application decisions on owned or leased land. California almond growers in Fresno County contract with drone service providers for precision foliar humic dosing.
- Agricultural Retailers:Input distributors controlling technical advisory and product bundling. Spanish cooperatives in Murcia consolidate seventy percent of biostimulant procurement through three distributor groups.
- Distributors:Wholesale channel operators managing cross-border logistics.
- Research Institutions:Public and private trial facilities establishing dosage protocols.
Agricultural Retailers sits at the top of the volume ranking, with Farmers climbing the fastest as direct-to-grower digital platforms expand.
Functionality:
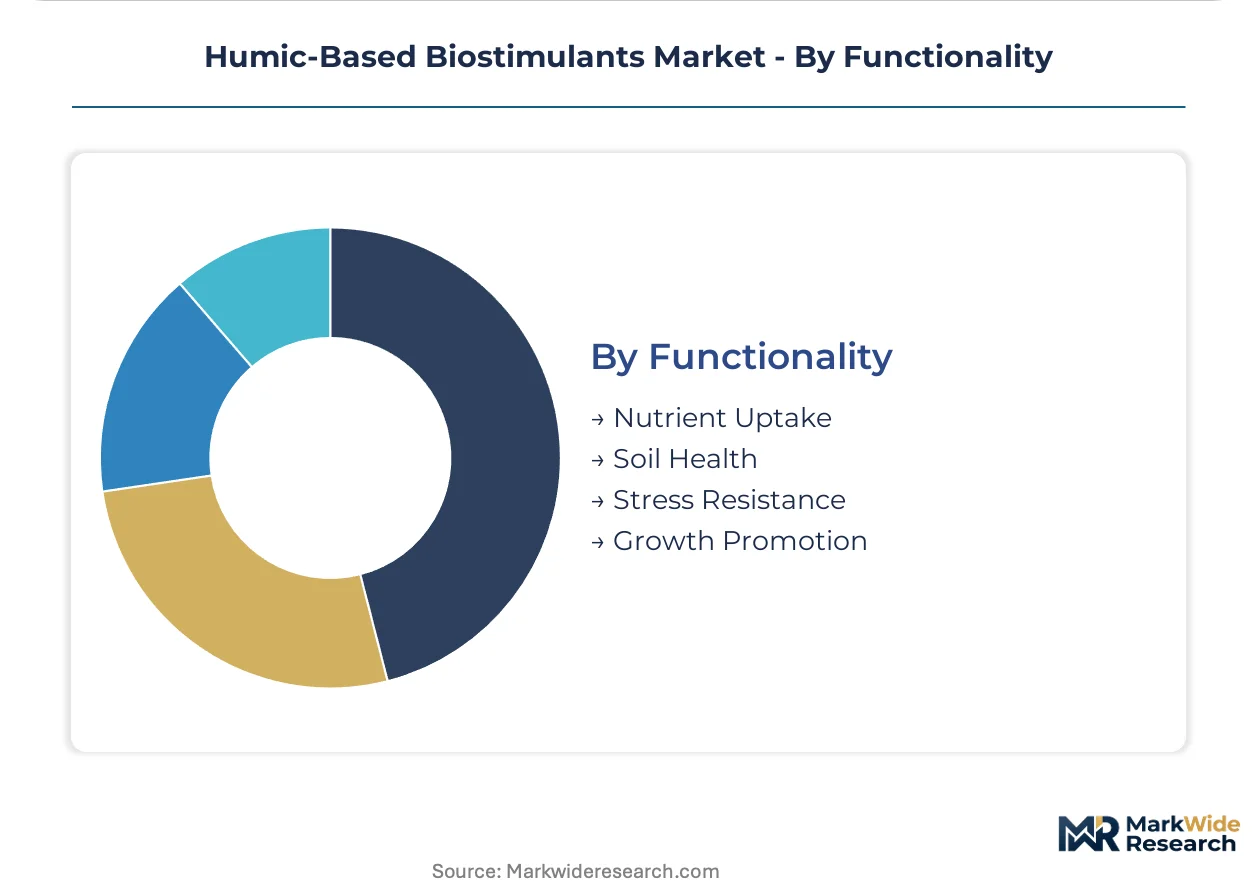
Supply concentration in fulvic acid extraction capabilities favors manufacturers positioned for premium nutrient uptake formulations.
- Nutrient Uptake:Chelating functions that enhance mineral assimilation through root membranes. Valencia-based extraction specialists deploy membrane filtration to isolate low-molecular-weight fractions for high-value specialty crop markets.
- Soil Health:Organic carbon contributions supporting microbial biomass and structure. Italian extension services in Emilia-Romagna specify humic application rates for degraded soil restoration under regional farm advisory programs.
- Stress Resistance:Drought and salinity tolerance enhancement protocols.
- Growth Promotion:Hormonal pathway stimulation for yield optimization.
Nutrient Uptake sits at the top of the volume ranking, with Soil Health climbing the fastest as carbon measurement protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The humic-based biostimulants industry traces its commercial scale-up to European horticulture cooperatives during the 1990s, when Italian and Spanish growers first systematized liquid humic dosing through fertigation networks. This Mediterranean foundation established extraction protocols and application methodologies that now propagate across water-stressed agricultural zones worldwide.
Spain
Almería and Murcia greenhouse operators deploy automated humic dosing systems to meet EU Green Deal soil organic carbon benchmarks. The country's national agricultural regulator enforces EU Fertilising Products Regulation compliance through regional farm advisory programs. Valencia-based extraction specialists deploy membrane filtration to isolate premium fulvic fractions for export markets.
Italy
Tomato cooperatives in Sicily and Emilia-Romagna apply concentrated liquid formulations through drip irrigation to restore degraded soils. Italian extension services specify application rates under regional soil health mandates aligned with EU Green Deal targets. Bologna-area distributors bundle biostimulants with crop protection inputs for horticulture clusters.
United States
California almond growers in Fresno County contract drone service providers for precision foliar humic dosing amid persistent drought conditions. The EPA maintains distinct biostimulant oversight pathways that diverge from EU compliance architectures. North Dakota leonardite deposits supply premium feedstock to extraction facilities facing permit delays and transport cost volatility.
India
Tamil Nadu and Gujarat lignite deposits support domestic humic acid blending facilities incentivized under the PLI scheme for organic fertilizers. The country's national standards body certifies biofertilizer composition for state procurement programs. Karnataka horticulture zones trial humic-treated hectares for carbon farming credit qualification under developing national frameworks.
Australia
Western Australia wheat growers pilot humic application protocols for Emissions Reduction Fund methodology revisions that may qualify treated hectares. The country's national agricultural regulator monitors soil organic carbon measurement standards under developing carbon farming frameworks. Queensland irrigation districts integrate liquid formulations into broadacre nutrient management programs.
Humic-Based Biostimulants Market Competitive Environment
Premium-margin players sit above commodity-margin players across extraction technology and formulation purity tiers. The vendor base stratifies between integrated agricultural input conglomerates, specialized biostimulant formulators, and regional extraction facilities serving price-sensitive broadacre segments. Three archetypes dominate: Mediterranean formulation specialists with proprietary fractionation capabilities, multinational crop science portfolios leveraging distribution scale, and leonardite mining operations with captive upstream supply. Capacity expansion and strategic partnerships represent the dominant competitive moves, with extraction facilities securing offtake agreements and formulators building biological input compatibility protocols.
Within the specialized formulation tier, Valagro SpA and Koppert occupy positions exemplifying Mediterranean-rooted technical advisory integration. Haifa Group anchors the scale-driven segment among Israel-based agricultural input conglomerates. These three entities represent distinct strategic postures: proprietary extraction technology deployment, biological input compatibility specification, and integrated nutrient portfolio bundling respectively.
| Leading Market Players |
|---|
| FMC Corporation |
| Valagro SpA |
| Biolchim S.p.A |
| Koppert |
| Haifa Group |
| UPL Ltd. |
| Bayer AG |
| HUMINTECH GMBH |
| BORREGAARD |
| Others |
Value Chain & Pricing Dynamics
Captive upstream control over leonardite deposits in North Dakota and New Mexico anchors pricing power for integrated extraction operations serving premium liquid formulation markets. This backward integration insulates margin structures from feedstock volatility while concentrating bargaining leverage against non-integrated blenders dependent on spot market sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates membrane-filtered fulvic fractions from alkaline-extracted humic acids and raw leonardite derivatives. Price differentiation hinges on EU Fertilising Products Regulation certification grade and molecular weight fraction purity. Cost compression in economy-tier granular products is intensifying because synthetic chelate substitution in US Corn Belt grain operations erodes volume premiums. Agricultural retailers exhibit lowest price sensitivity due to bundling economics, while broadacre wheat farmers in price-sensitive segments resist humic premiums.
Supply Chain Analysis
Freight cost volatility from North Dakota mining districts to European formulation facilities compresses margins for non-integrated distributors. Supply concentrates in the United States, Spain, and India, with leonardite deposits, Mediterranean extraction specialists, and Tamil Nadu lignite processing feeding global volumes. Raw material dependencies span leonardite ore, lignite feedstock, and membrane filtration equipment. Single-source vulnerability in accredited carbon-14 testing facilities creates certification bottlenecks. Distribution runs through agricultural retailer networks that bundle biostimulants with crop protection inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in humic-based biostimulants rests on carbon farming credit stacking that commands premium pricing for soil organic carbon verification. REACH registration cost compression favors scaled players with dossier amortization across product portfolios.
For Market Incumbents: To counter synthetic chelate substitution in broadacre grain segments, deepen backward integration into North Dakota leonardite mining to secure captive feedstock supply. Prioritize membrane filtration capacity expansion in Valencia to isolate premium fulvic fractions for EU horticulture cooperatives. For New Entrants and Emerging Players: Launch via drone-based foliar application service models in water-stressed California vineyard and almond districts. Target carbon farming credit qualification protocols in Australia and developing Indian frameworks. White-space concentration sits in precision dosing subscription services for irregular topography operations. For Investors and Strategic Acquirers: Roll-up economics work for Mediterranean formulation specialists with proprietary extraction technology because EU Fertilising Products Regulation compliance creates acquisition currency for non-compliant Eastern European facilities. Long-term viability favors integrated players with biobased content certification capabilities. The signal to watch is carbon-14 testing facility capacity expansion as inflection indicator for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leonardite Mining | Captive feedstock supply from North Dakota deposits insulates margin structures from transport cost volatility. |
| Membrane Filtration Capacity Expansion | Valencia-based facilities isolate premium fulvic fractions that command pricing premiums in Italian tomato cooperatives. |
| EU Fertilising Products Regulation Certification Investment | Third-party validated biobased content declarations secure shelf space in Spanish agricultural retailer networks. |
| Drone-Based Foliar Application Service Launch | Precision dosing subscriptions in California almond districts address water stress management priorities. |
| Carbon Farming Credit Protocol Development | Australian Emissions Reduction Fund methodology revisions may qualify humic-treated hectares for offset revenue. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction facility operators, agricultural retailer procurement heads, formulation R&D directors, and drone application service providers with secondary validation from EU Fertilising Products Regulation filings, ECHA REACH dossiers, and customs trade data for leonardite and lignite derivatives. Bottom-up volume modeling triangulated against top-down agricultural input spending analysis.
Segment-weighting across product type, application, end user, and functionality dimensions drove analytical framework construction throughout the forecast period. CAGRs derived from trend extrapolation of fertigation infrastructure expansion rates, EU Green Deal implementation timelines, and carbon farming credit protocol adoption curves. Industry-specific inputs included drip irrigation network penetration data and biobased content certification velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH registration timeline delays or carbon-14 testing facility capacity constraints. Forecasts reflect documented assumptions regarding EU member state soil health mandate enforcement intensity and synthetic chelate pricing trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
North America Agricultural Microbials Market